
Market Overview:
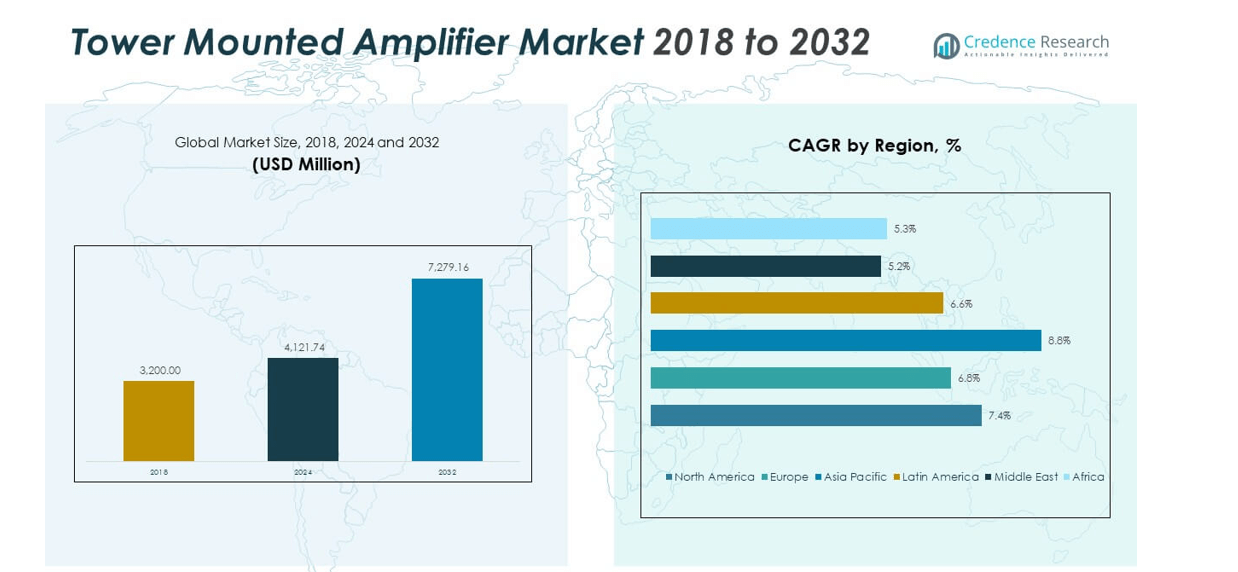
The Global Tower Mounted Amplifier Market size was valued at USD 3,200.00 million in 2018 to USD 4,121.74 million in 2024 and is anticipated to reach USD 7,279.16 million by 2032, at a CAGR of 7.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Tower Mounted Amplifier Market Size 2024 | USD 4,121.74 million |
| Tower Mounted Amplifier Market, CAGR | 7.44% |
| Tower Mounted Amplifier Market Size 2032 | USD 7,279.16 million |
Strong network expansion initiatives fuel steady demand for tower mounted amplifiers. Telecom firms focus on wide-area coverage and improved call clarity to support high data loads. The rollout of massive MIMO setups encourages operators to pair antennas with high-performance amplification units. The shift toward outdoor small cells also helps drive usage in large cities. Countries modernize legacy networks to reduce dropped-call risk and improve user experience. Rising expectations from enterprise users lift interest in better uplink sensitivity. Strong investment in next-generation infrastructure sustains long-term deployment across global carriers.
North America leads the Global Tower Mounted Amplifier Market due to large-scale 5G rollouts and strong operator spending on high-capacity sites. Europe follows with steady upgrades across dense metro clusters and rural zones that seek better signal reach. Asia Pacific shows fast growth with heavy investment from major economies and rising smartphone penetration across expanding cities. The Middle East improves network resilience through targeted TMA deployment in harsh climates and remote regions. Latin America gains traction through modern network upgrades and rising focus on improved urban coverage across major economies.
Market Insights:
- The Global Tower Mounted Amplifier Market grew from USD 3,200.00 million in 2018 to USD 4,121.74 million in 2024 and is projected to reach USD 7,279.16 million by 2032, registering a 44% CAGR across the period.
- North America (35.36%), Europe (27.45%), and Asia Pacific (24.64%) hold the largest regional shares due to dense telecom infrastructure, strong 5G rollout activity, and continuous modernization across high-traffic urban networks.
- Asia Pacific, the fastest-growing region with an 8.8% CAGR and a 64% share, expands rapidly through large-scale tower deployments, rising smartphone usage, and robust investments in rural and urban connectivity.
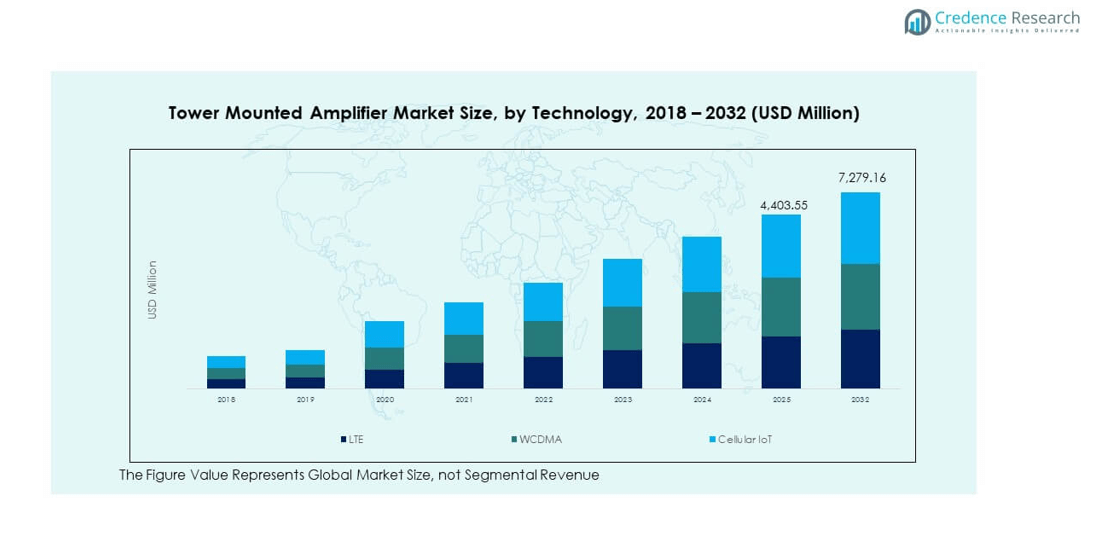
- Based on the technology split visible in the chart, Cellular IoT accounts for an estimated 35–38% share of the 2024 market structure, reflecting strong adoption driven by smart-city systems and connected devices.
- WCDMA and LTE together contribute roughly 60–65% of the technology share in 2024, supported by continued reliance on legacy 3G/4G networks and widespread upgrades across developing and developed markets.
Market Drivers:
Rising Need For Strong Uplink Performance Across Expanding Telecom Networks
The Global Tower Mounted Amplifier Market benefits from growing pressure to improve uplink strength in dense service areas. Operators deploy robust amplifiers to reduce noise levels and enhance antenna sensitivity. Many networks upgrade legacy units to support heavy data traffic during peak hours. The push for better voice clarity across cities drives higher demand from carriers. Enterprises expect stable coverage for field teams and outdoor equipment. Rural zones rely on TMAs to close gaps created by long-distance transmission paths. The market gains steady traction from countries strengthening national connectivity programs. It supports reliable service quality across wide territories.
- For instance, CommScope’s TMA series improves uplink sensitivity by up to 5 dB, which operators use to enhance performance on congested macro sites. It supports reliable service quality across wide territories.
Growing Deployment Of 5G Infrastructure With High-Capacity Radio Sites
Large telecom providers invest in tower mounted amplifiers to support advanced 5G radio units. The equipment strengthens uplink signals on high-frequency bands and improves receiver performance. Many operators expand small-cell clusters to limit congestion during busy hours. Carriers pair amplifiers with massive MIMO setups to stabilize fast data sessions. Smart-city projects depend on strong uplink quality for sensor networks and public platforms. The Global Tower Mounted Amplifier Market gains wider acceptance from governments promoting digital access. Vendors design low-noise units to support challenging metro environments. It enables stronger network output across large city grids.
- For instance, Kaelus developed TMAs with passive intermodulation (PIM) performance below –153 dBc, which supports clean uplink channels for 5G radios. It enables stronger network output across large city grids.
Expanding Mobile User Base Driving Higher Demand For Better Network Reliability
A rising number of smartphone users drives the need for stable call and data services. Telecom operators deploy TMAs to reduce call drops and maintain uplink strength during movement. Remote areas receive network upgrades to support emergency communication and essential tasks. Enterprise parks adopt wide-area networks that rely on strong amplification near tower sites. Outdoor entertainment events and sports venues add temporary TMAs for crowd management. The Global Tower Mounted Amplifier Market gains momentum from networks handling wider user loads. Vendors improve designs to support efficient power use and longer uptime cycles. It supports more resilient signal management across diverse locations.
Increasing Modernization Of Legacy Telecom Infrastructure Across Key Regions
Government-led modernization programs push operators to replace outdated radio units. Many networks strengthen rural communication to support education, health, and transport services. Carriers upgrade TMA systems to improve spectrum efficiency during high-demand periods. The shift toward cloud-managed radio networks increases interest in advanced outdoor equipment. Energy-efficient amplifiers attract buyers seeking reduced operating costs and longer service cycles. The Global Tower Mounted Amplifier Market benefits from large-scale retrofitting plans across major economies. Vendors launch durable products suited for harsh climates and remote sites. It strengthens operator capability across long-term growth programs.
Market Trends:
Growing Shift Toward Low-Power And Energy-Efficient Amplifier Designs
Manufacturers design low-power TMAs to support sustainability targets across telecom networks. Operators prefer units that reduce heat levels and extend equipment life. Many firms upgrade product lines to cut energy waste during long operational cycles. Remote areas gain value from low-power systems with limited maintenance needs. The Global Tower Mounted Amplifier Market reflects strong interest in energy-optimized hardware. Telecom providers seek devices that minimize failure risk in extreme weather. Vendors integrate advanced shielding to reduce interference around busy tower sites. It aligns with global goals for reduced operational emissions.
- For instance, the Filtronic Morpheus II E-band transceiver module offers high performance for carrier-grade mobile XHaul applications. The module provides a receiver noise figure of 7 to 10 dB in high-gain mode and achieves a low phase noise of -112 dBc/Hz at 1 MHz. It supports high data rates with up to 512QAM modulation and channel bandwidths over 2 GHz, which helps maximize network throughput and spectral efficiency, aligning with goals for reduced operational emissions. The more recent Morpheus X2 offers an enhanced noise figure option as low as 4.5 to 5.5 dB.
Rising Integration Of Remote Monitoring And Intelligent Diagnostic Features
Next-generation amplifiers support remote tracking to reduce field visits and service delays. Networks use predictive tools to identify early faults before major disruption. Many operators invest in cloud-linked TMA systems to enhance visibility across assets. Real-time status checks help teams manage tower performance during peak hours. Rural deployments gain value from remote access functions that maintain uptime. The Global Tower Mounted Amplifier Market shows fast interest in digital diagnostics for complex sites. Vendors embed smart alert features that guide rapid repair actions. It supports stronger operational continuity across wide geographic areas.
Increased Adoption Of Compact Multi-Band Amplifiers To Support Dense Urban Coverage
Telecom networks favor compact units that handle multiple bands within tight tower spaces. Urban zones demand smaller footprints to manage rising antenna counts. Operators deploy multi-band TMAs to strengthen uplink across varied frequency layers. Many carriers reduce tower clutter by replacing older single-band devices. Vendors improve thermal control to ensure consistent performance in constrained sites. The Global Tower Mounted Amplifier Market gains interest from smart-city rollouts with heavy network loads. Multi-band products help reduce maintenance tasks during equipment shifts. It supports simpler integration with modern radio platforms.
Growing Transition Toward Ruggedized Amplifiers For Harsh And Remote Environments
Harsh climates drive demand for robust outdoor amplifiers built for temperature swings. Remote towers require units that maintain stable performance during dust storms, heavy rain, or snow. Vendors engineer reinforced housings to protect sensitive circuitry. Energy-efficient cooling systems support reliability in high-heat zones. The Global Tower Mounted Amplifier Market aligns with infrastructure programs across deserts, mountains, and coastlines. Operators deploy rugged TMAs to reduce outage risk in isolated areas. Many networks prefer long-life designs to limit service interruptions. It enhances network strength across extreme terrains.
Market Challenges Analysis:
High Maintenance Pressure And Operational Cost Burden Impacting Long-Term Network Planning
The Global Tower Mounted Amplifier Market faces cost pressure due to frequent servicing needs. Many towers require skilled teams to manage calibration, testing, and repair cycles. Operators struggle to balance upgrade budgets with rising site complexity. Harsh outdoor conditions shorten component life and increase replacement frequency. Older tower layouts make integration difficult during modernization tasks. Legacy interference issues reduce network stability in some regions. Carriers attempt to limit downtime while managing tight timelines for rollouts. It creates planning challenges for large telecom providers.
Complex Deployment Requirements And Disruptions From Multi-Vendor Ecosystems
Telecom networks operate through mixed equipment from different suppliers. Integration challenges emerge when advanced TMAs interact with older radios. Many carriers face compatibility issues during fast network expansion. Site congestion makes installation harder in dense cities. Rural towers require long travel times, slowing repair actions during outages. Regulatory rules increase approval steps for hardware placement. The Global Tower Mounted Amplifier Market faces delays when operators adjust multi-band configurations. It affects project execution across competitive regions.
Market Opportunities:
Growing Expansion Of 5G And Future Network Generations Across Major Economies
The Global Tower Mounted Amplifier Market gains strong opportunities from wider 5G coverage plans. Many countries invest in large radio networks to support fast data growth. Operators seek flexible amplifiers that match evolving frequency needs. Smart manufacturing sites create demand for high-performance uplink support. Advanced IoT zones rely on strong coverage for continuous data exchange. Vendors develop products that meet new spectrum allocations across regions. It encourages broader adoption of next-generation amplification. New technology cycles help expand long-term market potential.
Rising Telecom Investments In Rural Connectivity And Cross-Border Communication Corridors
Governments launch programs that improve remote communication for education, health, and industry. Carriers deploy TMAs to stabilize uplink signals across long-distance routes. New transport corridors require robust coverage to support logistics and safety systems. Rural economies adopt digital tools that depend on strong tower coverage. Vendors design cost-effective amplifiers for isolated areas with minimal support access. The Global Tower Mounted Amplifier Market benefits from these national initiatives aimed at network equality. It helps expand telecom reach into under-served zones. New expansion paths strengthen revenue prospects for global suppliers.
Market Segmentation Analysis:
By Type
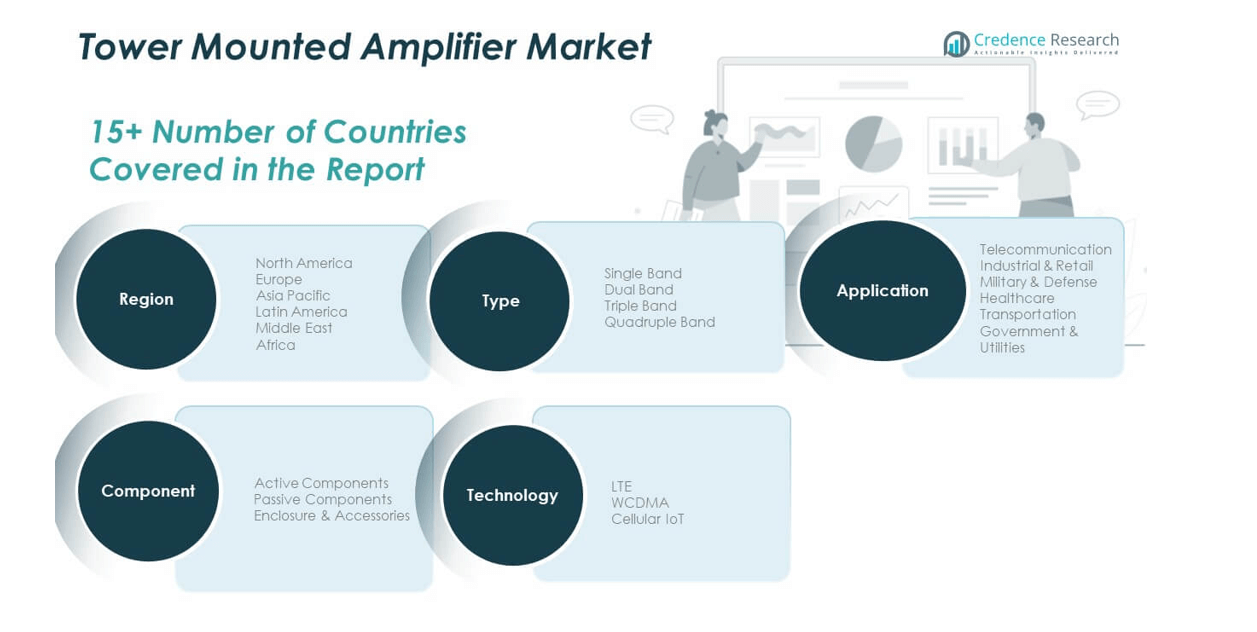
The Global Tower Mounted Amplifier Market expands through strong demand across Single Band, Dual Band, Triple Band, and Quadruple Band units. Single Band models support legacy networks with stable performance. Dual Band units gain traction due to better compatibility across mixed frequency layers. Triple Band systems help operators manage swelling data loads across cities. Quadruple Band designs attract carriers aiming for flexible deployments. Many networks upgrade older towers to multi-band setups for wider coverage. It supports broader adoption across high-density environments.
- For instance, Comba Telecom offers multi-band TMAs supporting up to four operating bands within one enclosure, helping operators reduce tower load and simplify deployments. It supports broader adoption across high-density environments.
By Application
Telecommunication leads demand due to high tower density and growing data traffic. Industrial & Retail users adopt TMAs to maintain stable connectivity for automation and digital tools. Military & Defense agencies deploy systems for secure communication across sensitive zones. Healthcare facilities rely on strong signals to support real-time monitoring inside large buildings. Transportation networks improve communication across rail, aviation, and road systems. Government & Utilities sectors use amplifiers to strengthen emergency and public service communication networks.
- For instance, Kathrein’s TMAs support operational temperatures from –40°C to +65°C, enabling consistent performance for emergency and government communication towers exposed to harsh climates.
By Component
Active Components dominate due to strong demand for low-noise amplifiers and filters that enhance uplink quality. Passive Components support stable operation by improving signal flow and reducing interference. Enclosure & Accessories gain growth from rising tower upgrades requiring durable housings. Many sites adopt weather-resistant materials to improve performance in harsh zones. It helps operators extend equipment life across remote regions.
By Technology
LTE holds a major share due to wide global adoption and constant network modernization. WCDMA remains relevant in regions with strong 3G bases. Cellular IoT grows fast with the rise of smart infrastructure and connected devices. Many operators expand IoT grids to support real-time field operations. It strengthens long-term traction across evolving telecom ecosystems.
Segmentation:
By Type
- Single Band
- Dual Band
- Triple Band
- Quadruple Band
By Application
- Telecommunication
- Industrial & Retail
- Military & Defense
- Healthcare
- Transportation
- Government & Utilities
By Component
- Active Components
- Passive Components
- Enclosure & Accessories
By Technology
- LTE
- WCDMA
- Cellular IoT
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Tower Mounted Amplifier Market size was valued at USD 1,145.60 million in 2018 to USD 1,457.42 million in 2024 and is anticipated to reach USD 2,570.29 million by 2032, at a CAGR of 7.4 during the forecast period. North America holds 35.36% share of the Global Tower Mounted Amplifier Market. The region leads due to strong investment in 5G infrastructure and dense macro-cell deployment. Major operators expand tower assets to support higher throughput needs. Urban zones adopt advanced multi-band TMAs to reduce interference and improve uplink strength. The market gains support from enterprise networks that require stable outdoor coverage. Harsh-weather regions drive demand for ruggedized components with long service cycles. Vendors collaborate with carriers to optimize network efficiency across diverse terrains. It benefits from strong digital adoption across commercial and public sectors.
Europe
The Europe Global Tower Mounted Amplifier Market size was valued at USD 911.14 million in 2018 to USD 1,131.43 million in 2024 and is anticipated to reach USD 1,896.10 million by 2032, at a CAGR of 6.8 during the forecast period. Europe holds 27.45% share of the Global Tower Mounted Amplifier Market. The region benefits from continuous mobile network modernization across urban and rural zones. Many operators upgrade multi-band sites to meet high data usage patterns. Regulatory pressure encourages carriers to improve service reliability across key corridors. Harsh climate conditions lift the need for durable enclosures and low-noise units. Industrial hubs adopt TMAs to support automation and cross-border logistics networks. Growing IoT penetration strengthens demand for uplink-enhancing components. It supports long-term network resilience across strategic regions.
Asia Pacific
The Asia Pacific Global Tower Mounted Amplifier Market size was valued at USD 753.92 million in 2018 to USD 1,015.78 million in 2024 and is anticipated to reach USD 1,986.49 million by 2032, at a CAGR of 8.8 during the forecast period. Asia Pacific holds 24.64% share of the Global Tower Mounted Amplifier Market. The region grows fast due to large-scale network rollouts across expanding cities. Telecom operators deploy dense tower grids to manage heavy mobile traffic. Rural connectivity programs raise demand for long-range uplink support. Strong smartphone adoption drives higher data loads throughout the region. Vendors introduce cost-efficient multi-band units to support varied spectrum usage. Smart-city initiatives accelerate the need for reliable tower-mounted systems. It gains momentum from robust investments in digital transformation.
Latin America
The Latin America Global Tower Mounted Amplifier Market size was valued at USD 230.40 million in 2018 to USD 294.25 million in 2024 and is anticipated to reach USD 486.76 million by 2032, at a CAGR of 6.6 during the forecast period. Latin America holds 7.14% share of the Global Tower Mounted Amplifier Market. The region grows through expanding telecom upgrades across major economies. Operators improve tower density to reduce call drops in crowded cities. Remote zones rely on TMAs to strengthen long-distance communication links. Energy and utility sectors use stable uplink systems for field operations. Vendors gain traction by offering durable and climate-resistant units. Government programs support digital access across rural communities. It continues to benefit from rising mobile data use across diverse industries.
Middle East
The Middle East Global Tower Mounted Amplifier Market size was valued at USD 78.40 million in 2018 to USD 91.06 million in 2024 and is anticipated to reach USD 135.43 million by 2032, at a CAGR of 5.2 during the forecast period. The Middle East holds 2.21% share of the Global Tower Mounted Amplifier Market. The region invests in improved tower systems to support fast-growing digital platforms. Desert environments require rugged amplifiers that deliver stable performance. Operators expand 5G corridors around economic hubs and industrial zones. Harsh climate exposure increases demand for advanced enclosure systems. Enterprises adopt better uplink support to manage large-scale IoT networks. Many countries upgrade communication links for transport and security operations. It gains support from national programs focused on digital modernization.
Africa
The Africa Global Tower Mounted Amplifier Market size was valued at USD 80.54 million in 2018 to USD 131.79 million in 2024 and is anticipated to reach USD 204.10 million by 2032, at a CAGR of 5.3 during the forecast period. Africa holds 3.20% share of the Global Tower Mounted Amplifier Market. The region expands tower infrastructure to improve basic communication access. Rural and semi-urban zones depend on TMAs to support long-distance signal reach. Growing mobile adoption increases pressure on carriers to upgrade networks. Operators introduce multi-band units suited for diverse terrains. Vendors offer cost-optimized systems for wide deployment across remote areas. Governments promote connectivity projects that raise demand for reliable uplink performance. It gains steady momentum from rising digital participation across key sectors.
Key Player Analysis:
- Amphenol Antenna Solutions
- Comba Telecom Systems Holdings Ltd.
- Combilent A/S
- CommScope Inc.
- Communication Components Inc.
- Eyecom Telecommunications Group
- Filtronic plc
- Kaelus, Inc.
- Kathrein-Werke KG
- Microdata Telecom AB
- Molex, Inc.
- NXP Semiconductors N.V.
- Westell Technologies
Competitive Analysis:
The Global Tower Mounted Amplifier Market features strong competition among telecom equipment manufacturers offering multi-band, low-noise, and energy-efficient units. Leading companies focus on product reliability, wide frequency support, and rugged outdoor designs. Many brands expand portfolios to meet 5G and small-cell deployment needs. Vendors strengthen partnerships with operators to enhance network performance across dense and remote zones. Innovation centers on compact architectures, lower power consumption, and improved thermal stability. Firms compete through regional expansion and customized tower solutions for harsh environments. Product differentiation depends on noise reduction, flexibility, and long-term durability. It continues to attract investment from suppliers targeting modern telecom upgrades.
Recent Developments:
- On August 3, 2025, CommScope announced it has entered into a definitive agreement to sell its Connectivity and Cable Solutions (CCS) segment to Amphenol for approximately $10.5 billion in cash, with closing expected within the first half of 2026.
- In August 2025, Kathrein Broadcast, the German antenna specialist, announced the sale of its U.S. division to American Amplifier Technologies (AAT), a California-based provider of broadcast and electrical products. AAT acquired 100% of the shares in Kathrein Broadcast USA and will continue operating the company under the same name. Jörg Lippert, designated CEO of Kathrein Broadcast GmbH, stated: "This step strengthens our global presence. AAT has been familiar with the U.S. markets for years and can position our products there even more effectively."
- In February 2025, Amphenol completed the acquisition of CommScope 's Outdoor Wireless Networks (OWN) and Distributed Antenna Systems (DAS) businesses. The transaction was valued at approximately $2.1 billion in cash and was officially closed on February 2, 2025. The acquisition was announced on July 18, 2024, and brought approximately 4,000 employees into the Amphenol family. Amphenol's President and Chief Executive Officer, R. Adam Norwitt, stated: "The acquisition of the OWN and DAS businesses brings to Amphenol a strong portfolio of innovative and advanced technologies for communications networks.
- In February 2025, CommScope completed the divestiture of its Outdoor Wireless Networks and Distributed Antenna Systems businesses to Amphenol . The transaction closed on February 2, 2025, as initially announced on July 18, 2024. CommScope utilized the proceeds from the sale to repay all outstanding amounts under its asset-backed revolving credit facility and to repay a portion of its Senior Secured Notes.
Report Coverage:
The research report offers an in-depth analysis based on Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for multi-band TMAs will grow with expanding 5G infrastructure.
- Rugged outdoor systems will gain traction in regions with harsh climates.
- IoT growth will encourage operators to deploy amplifiers supporting low-power technologies.
- Compact amplifier designs will become more common across dense tower sites.
- Remote monitoring and diagnostics will shape next-generation TMA platforms.
- Network modernization programs will lift demand for legacy site upgrades.
- Energy-efficient designs will influence buying decisions for large operators.
- Urban densification will increase reliance on small-cell compatible TMAs.
- Vendor partnerships will strengthen innovation in low-noise architectures.
- Global investment in telecom resilience will support steady market expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of 5G Infrastructure
The rapid rollout of 5G networks globally is driving demand for tower mounted amplifiers, as operators require advanced amplification to support high-capacity radio sites and massive MIMO deployments, ensuring strong uplink performance and network reliability.
Modernization of Legacy Telecom Networks
Government-led and operator-driven modernization programs are prompting upgrades from outdated radio units to advanced TMAs, improving spectrum efficiency, reducing dropped calls, and supporting new digital services across both urban and rural regions.
Rising Mobile and IoT Device Penetration
The surge in smartphone adoption and the proliferation of IoT devices are increasing network traffic and uplink requirements, compelling telecom operators to deploy more TMAs for stable connectivity and enhanced user experience in both dense urban and remote areas.
Demand for Energy-Efficient and Ruggedized Solutions
Operators are seeking low-power, durable TMAs to reduce operational costs and ensure reliable performance in harsh environments, aligning with sustainability goals and the need for long-life equipment in challenging climates.
Integration of Remote Monitoring and Diagnostics
Next-generation TMAs with intelligent diagnostics and remote monitoring capabilities are gaining traction, as they help operators minimize maintenance costs, reduce downtime, and proactively manage network performance across widespread tower assets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Tower Mounted Amplifier (TMA) market?
At what Compound Annual Growth Rate is the Global Tower Mounted Amplifier Market projected to grow between 2025 and 2032?
What are the key drivers of the TMA market?
How do TMAs improve network performance?
Which regions are experiencing significant growth in the TMA market?
What role does digital transformation play in the TMA market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Single Band
- 1.2.2 Dual Band
- 1.2.3 Triple Band
- 1.2.4 Quadruple Band
- 1.3 By Component
- 1.3.1 Active Components
- 1.3.2 Passive Components
- 1.3.3 Enclosure & Accessories
- 1.4 By Technology
- 1.4.1 LTE
- 1.4.2 WCDMA
- 1.4.3 Cellular IoT
- 1.5 By Application
- 1.5.1 Telecommunication
- 1.5.2 Industrial & Retail
- 1.5.3 Military & Defense
- 1.5.4 Healthcare
- 1.5.5 Transportation
- 1.5.6 Government & Utilities
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 4,121.74 million → 2032: USD 7,279.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Tower Mounted Amplifier Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Tower Mounted Amplifier Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Tower Mounted Amplifier Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Tower Mounted Amplifier Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Tower Mounted Amplifier Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Tower Mounted Amplifier Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Tower Mounted Amplifier Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Tower Mounted Amplifier Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 4,121.74 million → 2032: USD 7,279.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Tower Mounted Amplifier Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single Band
- 12.3.7.2 Dual Band
- 12.3.7.3 Triple Band
- 12.3.7.4 Quadruple Band
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Active Components
- 12.4.7.2 Passive Components
- 12.4.7.3 Enclosure & Accessories
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 LTE
- 12.5.7.2 WCDMA
- 12.5.7.3 Cellular IoT
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Telecommunication
- 12.6.7.2 Industrial & Retail
- 12.6.7.3 Military & Defense
- 12.6.7.4 Healthcare
- 12.6.7.5 Transportation
- 12.6.7.6 Government & Utilities
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Tower Mounted Amplifier End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Tower Mounted Amplifier Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Tower Mounted Amplifier Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Tower Mounted Amplifier Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 CommScope Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Amphenol Antenna Solutions
- 18.4 Comba Telecom Systems Holdings Ltd.
- 18.5 Kaelus, Inc.
- 18.6 Filtronic plc
- 18.7 Kathrein-Werke KG
- 18.8 Microdata Telecom AB
- 18.9 Molex, Inc.
- 18.10 NXP Semiconductors N.V.
- 18.11 Westell Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

