
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Flexible Copper Clad Laminate (FCCL) Market Size 2024 | USD 1,419.73 Million |
| Flexible Copper Clad Laminate (FCCL) Market, CAGR | 7.23% |
| Flexible Copper Clad Laminate (FCCL) Market Size 2032 | USD 2,581.24 Million |
Market Overview
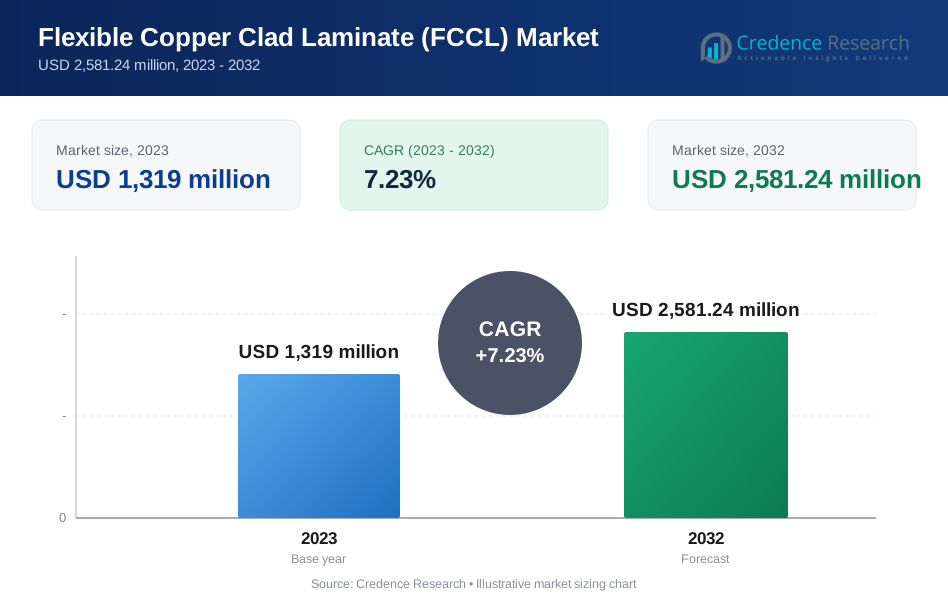
The Global Flexible Copper Clad Laminate (FCCL) Market is projected to grow from USD 1,419.73 million in 2024 to an estimated USD 2,581.24 million by 2032, with a compound annual growth rate (CAGR) of 7.23% from 2025 to 2032. Key market drivers include the rising penetration of 5G infrastructure, growing demand for consumer electronics, and the increasing trend toward electric and autonomous vehicles. The push for flexible electronics and improvements in adhesive and substrate technologies continue to shape innovation in FCCL production. Trends such as roll-to-roll processing and the development of halogen-free, eco-friendly FCCLs support both performance enhancement and sustainability goals, driving competitiveness across the value chain. Geographically, Asia Pacific dominates the FCCL market due to strong electronics manufacturing bases in China, South Korea, Taiwan, and Japan. North America and Europe also hold significant shares, fueled by automotive electronics and aerospace applications. Leading players shaping the global FCCL landscape include DuPont, Hitachi Chemical, Panasonic Corporation, Taiflex Scientific, Doosan Corporation, LG Chem, Arisawa Mfg Co., Ltd., and Nippon Steel Chemical. These companies focus on R&D, capacity expansion, and vertical integration to strengthen their market positions and meet the evolving needs of high-frequency and high-speed circuit applications.Market Insights
- The market is projected to grow from USD 1,419.73 million in 2024 to USD 2,581.24 million by 2032, registering a CAGR of 7.23% between 2025 and 2032.
- Rising adoption of 5G infrastructure, electric vehicles, and wearable electronics is fueling demand for advanced FCCL materials.
- Increasing miniaturization and complexity of electronic components require flexible, heat-resistant laminates, boosting FCCL utilization.
- High raw material costs and technical complexity in manufacturing pose challenges to new entrants and small-scale producers.
- Asia Pacific holds the largest regional share, driven by large-scale electronics manufacturing in China, South Korea, Japan, and Taiwan.
- North America and Europe show strong growth supported by demand in automotive, aerospace, and telecom applications.
- Market players are investing in halogen-free, eco-friendly FCCL and roll-to-roll processing technologies to stay competitive.
Market Drivers
Rising Demand from Consumer Electronics and Wearable Devices is Driving FCCL Adoption The Global Flexible Copper Clad Laminate (FCCL) Market benefits from the surging demand for compact and high-performance consumer electronics. Smartphones, tablets, smartwatches, and fitness trackers increasingly rely on FCCL due to its light weight, flexibility, and thermal conductivity. The miniaturization of devices requires materials that can conform to tight spaces without compromising performance. FCCL serves this purpose by enabling high-density circuit integration. Consumer preference for multifunctional, portable, and durable devices continues to push manufacturers toward advanced FCCL solutions. The market shows strong growth momentum due to the volume of consumer electronics manufactured globally.- For instance, according to a 2024 International Data Corporation (IDC) device tracker report, global shipments of wearable devices-including smartwatches and fitness trackers-reached 560,000,000 units in a single year, reflecting the scale at which FCCL is adopted in the consumer electronics sector.
- For instance, a 2024 survey by the IPC Association Connecting Electronics Industries found that 2,100 electronics manufacturers worldwide upgraded their production lines to accommodate new-generation FCCL materials for advanced flexible PCB fabrication during the year.
Market Trends
Shift Toward Halogen-Free and Eco-Friendly FCCL Materials Gains Momentum The Global Flexible Copper Clad Laminate (FCCL) Market is witnessing a clear shift toward halogen-free and environmentally sustainable materials. Stricter environmental regulations and growing awareness of green electronics are pushing manufacturers to develop low-toxicity, recyclable FCCL variants. These materials reduce emissions during production and disposal while maintaining electrical performance. Consumers and OEMs are increasingly prioritizing eco-compliant products, prompting suppliers to align with international sustainability standards. It supports this shift by introducing new resins and adhesive systems that comply with RoHS and REACH directives. This trend enhances brand value and meets compliance expectations in developed markets.- For instance, according to a 2024 survey by the Japan Electronics and Information Technology Industries Association, 27 major FCCL manufacturers reported launching a total of 52 new halogen-free FCCL products over the previous 12 months to comply with updated environmental standards.
- For instance, a 2023 technical report from DuPont revealed that the company supplied over 4 million square meters of ultra-thin FCCL (less than 25 microns thick) for use in 5G smartphones and automotive radar modules worldwide during the year.
Market Challenges
Volatility in Raw Material Prices and Supply Chain Disruptions Create Operational Risks The Global Flexible Copper Clad Laminate (FCCL) Market faces significant challenges due to fluctuations in raw material prices, particularly copper foil and polyimide films. Supply chain instability, driven by geopolitical tensions and global trade restrictions, affects material availability and cost predictability. Manufacturers often encounter delays and cost overruns that impact production schedules and pricing strategies. It reduces profit margins for suppliers and creates uncertainty in long-term contracts. Smaller firms with limited procurement flexibility are more vulnerable to these disruptions. Ensuring a stable supply chain requires diversified sourcing and closer collaboration with raw material providers.- For instance, a 2021 production halt at Polyplastics’ Fukushima plant reduced global LCP resin supply by 15%, causing lead times for LCP film FCCL to spike from 8–10 weeks to over 20 weeks, while a force majeure event at a major HBA plant in Germany in 2022 triggered a 9-month inventory shortage for FCCL manufacturers, illustrating the market’s vulnerability to raw material disruptions
Market Opportunities
Expansion of Electric Vehicles and ADAS Systems Opens New Application Areas The rapid adoption of electric vehicles (EVs) and advanced driver-assistance systems (ADAS) presents strong growth opportunities for FCCL. These systems demand lightweight, heat-resistant, and space-efficient materials for electronic control units and battery management systems. FCCL meets these needs by offering reliable performance under thermal and mechanical stress. Automotive manufacturers are investing in high-density electronics that require flexible and durable laminates. The Global Flexible Copper Clad Laminate (FCCL) Market can scale production to meet the rising demand from EV and ADAS segments. It stands to benefit from vehicle electrification trends across North America, Europe, and Asia Pacific. Rising Demand for Flexible Electronics in Medical and Industrial Applications Creates Growth Potential Flexible electronics used in medical devices, sensors, and industrial automation systems are expanding FCCL’s market potential. Devices such as wearable health monitors, diagnostic tools, and industrial sensors rely on compact and flexible circuit substrates. It enables manufacturers to design smaller, more efficient products without sacrificing durability. Growth in telemedicine, remote diagnostics, and smart manufacturing supports wider FCCL adoption. The Global Flexible Copper Clad Laminate (FCCL) Market can explore these emerging segments through targeted product development and partnerships. It positions FCCL as a core component in next-generation healthcare and industrial technology systems.Market Segmentation Analysis
By Product Type The Global Flexible Copper Clad Laminate (FCCL) Market is segmented into single-sided, double-sided, and multi-layer flexible copper-clad laminates. Single-sided FCCLs hold a strong share due to their cost efficiency and wide use in consumer electronics. Double-sided laminates are preferred for circuits requiring higher connection density and mechanical stability. Multi-layer FCCLs are gaining traction in advanced electronic systems, including automotive radar and 5G infrastructure. It supports compact designs with high circuit integration, making it suitable for space-constrained and high-performance applications. The shift toward miniaturized and multifunctional devices is increasing demand for double-sided and multi-layer FCCLs.- For instance, manufacturers shipped 320 million square meters of single-sided FCCL, 210 million square meters of double-sided FCCL, and 95 million square meters of multi-layer FCCL globally.
- For instance, according to a 2024 survey by the China Electronic Materials Industry Association, 410 million square meters of polyimide-based FCCL were produced, compared to 130 million square meters of epoxy resin, 55 million square meters of PTFE, and 60 million square meters of flexible insulation-based FCCL.
Segments
Based on Product Type- Single-Sided Flexible Copper-Clad Laminate
- Double-Sided Flexible Copper-Clad Laminate
- Multi-Layer Flexible Copper-Clad Laminate
- Polyimide Copper-Clad Laminate
- Epoxy Resin Copper-Clad Laminate
- PTFE (Teflon) Copper-Clad Laminate
- Flexible Insulation Copper-Clad Laminate
- Consumer Electronics
- Automotive Electronics
- Aerospace and Defense
- Medical Devices
- Others
- Thin (<0.5 mm)
- Medium (0.5 mm to 1.5 mm)
- Thick (>1.5 mm)
- Electrical and Electronics
- Medical Industry
- Renewable Energy
- Telecommunications
- Automotive
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Flexible Copper Clad Laminate (FCCL) Market North America accounted for USD 441.26 million in 2024 and is projected to reach USD 805.37 million by 2032, registering a CAGR of 7.3%. It holds approximately 31.07% of the global market share in 2024. Strong demand from the consumer electronics and automotive sectors in the U.S. and Canada drives regional growth. Electric vehicles, advanced driver-assistance systems (ADAS), and 5G infrastructure projects support FCCL deployment. The region also benefits from the presence of high-end electronics manufacturers and robust R\&D activity. The Flexible Copper Clad Laminate (FCCL) Market in North America shows strong prospects for both volume and technological innovation. Europe Flexible Copper Clad Laminate (FCCL) Market Europe contributed USD 264.39 million in 2024 and is forecasted to reach USD 439.38 million by 2032, growing at a CAGR of 6.0%. It represents around 18.62% of the global FCCL market share in 2024. The region’s focus on clean energy, smart mobility, and aerospace electronics supports consistent FCCL usage. Germany, France, and the UK lead demand through automotive electronics and defense systems. Regulatory emphasis on halogen-free and sustainable materials strengthens product innovation. It supports moderate growth driven by regional manufacturing and technology partnerships. Asia Pacific Flexible Copper Clad Laminate (FCCL) Market Asia Pacific dominates the market with USD 609.89 million in 2024, projected to reach USD 1,180.21 million by 2032, growing at the highest CAGR of 8.1%. It holds 42.96% of the global market share in 2024. China, South Korea, Japan, and Taiwan are major manufacturing hubs for smartphones, flexible displays, and printed circuit boards. Strong local supply chains, low-cost production, and high demand for consumer electronics sustain its leadership. The Flexible Copper Clad Laminate (FCCL) Market in Asia Pacific continues to benefit from scale, innovation, and high export volume. Latin America Flexible Copper Clad Laminate (FCCL) Market Latin America generated USD 49.34 million in 2024 and is projected to reach USD 75.87 million by 2032, at a CAGR of 5.0%. The region holds a 3.47% share of the global market in 2024. Brazil and Mexico lead FCCL consumption, supported by growing automotive and electronics manufacturing. Regional expansion in telecommunications and medical devices adds to market potential. Limited local production capacity requires higher imports from Asia. It presents modest opportunities for strategic investment and supply chain diversification. Middle East Flexible Copper Clad Laminate (FCCL) Market The Middle East market stood at USD 30.09 million in 2024 and is estimated to reach USD 44.38 million by 2032, expanding at a CAGR of 4.4%. It accounts for about 2.12% of the global FCCL market share in 2024. Demand is driven by telecom network upgrades and smart city initiatives in countries like the UAE and Saudi Arabia. Investment in defense electronics and renewable energy applications further contributes to FCCL usage. It remains a niche yet evolving region with targeted growth potential. Africa Flexible Copper Clad Laminate (FCCL) Market Africa recorded USD 24.75 million in 2024 and is projected to grow to USD 36.02 million by 2032, reflecting a CAGR of 4.2%. The region represents 1.74% of the global market share in 2024. Growth is primarily driven by rising digitalization, mobile connectivity, and investment in electronics assembly. Nigeria, South Africa, and Egypt are emerging as key demand centers. Infrastructure development and regional trade agreements could improve market access. The Flexible Copper Clad Laminate (FCCL) Market in Africa remains small but holds long-term strategic value.Key players
- Nippon Steel Corporation
- Doosan Corporation
- Shin-Etsu Chemical Co., Ltd.
- Kingboard Holdings Limited
- Isola Group
- Rogers Corporation
- ITEQ Corporation
Competitive Analysis
The Global Flexible Copper Clad Laminate (FCCL) Market features a competitive landscape dominated by vertically integrated manufacturers and technology-driven suppliers. Nippon Steel Corporation and Doosan Corporation maintain strong positions through diversified product portfolios and large-scale operations. Companies like Shin-Etsu Chemical Co., Ltd. and Rogers Corporation focus on specialty FCCL products tailored for high-frequency and advanced electronics applications. Kingboard Holdings Limited and ITEQ Corporation leverage regional manufacturing strengths and broad distribution networks to maintain cost competitiveness. Isola Group strengthens its position through innovation and partnerships targeting automotive and aerospace sectors. The market shows moderate consolidation, with leading players investing in R\&D, capacity expansion, and eco-friendly material development. It favors companies that deliver consistent quality, comply with global environmental standards, and support evolving end-user applications.Recent Developments
In April 2025, Doosan Corporation strengthened its Flexible Copper Clad Laminate (FCCL) product line to focus on smart device, automotive, and network equipment sectors as part of its strategic repositioning efforts. This move is likely related to Doosan's broader strategy of developing new technologies and expanding into emerging markets. In June 2024, Nippon Steel Corporation introduced ESPANEX M, an adhesive-less two-layer Flexible Copper Clad Laminate (FCCL) designed for high-frequency and impedance-matching applications in flexible printed wiring boards.Market Concentration and Characteristics
The Global Flexible Copper Clad Laminate (FCCL) Market displays moderate to high market concentration, with a few key players holding a significant share of global revenue. It is characterized by strong competition among vertically integrated manufacturers and specialized suppliers. Leading companies maintain their positions through advanced production capabilities, proprietary technologies, and robust supply chain networks. The market emphasizes high product quality, performance reliability, and compliance with environmental regulations. It shows consistent innovation in materials, including halogen-free and high-frequency laminates. Entry barriers remain high due to capital-intensive manufacturing, technical complexity, and stringent quality standards.Report Coverage
The research report offers an in-depth analysis based on Product Type, Material Type, Application, Thickness, End User Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- The rising global deployment of 5G networks will increase demand for high-frequency, low-loss FCCLs. It supports next-generation communication hardware requiring enhanced signal performance.
- Wider adoption of EVs and advanced driver-assistance systems will drive FCCL usage in automotive electronics. It enables compact, durable circuits essential for high-reliability automotive systems.
- Foldable smartphones and wearable electronics will create new design requirements favoring ultra-thin FCCLs. It offers flexibility, durability, and space efficiency critical for compact devices.
- Demand for halogen-free, recyclable FCCLs will rise in response to environmental regulations. It encourages manufacturers to develop sustainable formulations without compromising performance.
- Growth in wearable medical devices and remote diagnostics will expand FCCL use in healthcare. It provides the mechanical resilience and electrical reliability needed for continuous monitoring.
- IoT and AI-enabled devices require flexible, multilayer circuitry to manage data flow and device connectivity. It reinforces the role of FCCL in connected consumer and industrial technologies.
- The market will see increasing demand for FCCLs compatible with high-frequency and high-speed circuit designs. It addresses needs in telecom, aerospace, and computing infrastructure.
- Roll-to-roll and automated lamination processes will improve production efficiency and consistency. It helps manufacturers meet large-scale orders with shorter lead times.
- Asia Pacific will retain its dominant position with strong supply chains and high-volume production. It will also drive innovation through investments in R\&D and material science.
- Future growth will involve joint ventures and acquisitions focused on material innovation and geographic expansion. It will strengthen market presence and diversify product offerings across regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
5G Infrastructure Expansion
The global rollout of 5G networks is driving demand for high-frequency, low-loss FCCLs, as these materials are essential for advanced communication hardware requiring superior signal integrity and miniaturization.
Growth in Consumer Electronics and Wearables
The proliferation of smartphones, tablets, smartwatches, and fitness trackers is increasing the need for lightweight, flexible, and thermally conductive FCCLs, which enable compact, high-density circuit integration in next-generation devices.
Electric Vehicles and Automotive Electronics
The shift toward electric vehicles and advanced driver-assistance systems (ADAS) is boosting FCCL adoption in automotive electronics, where lightweight, heat-resistant, and vibration-tolerant materials are critical for reliability and performance.
Technological Advancements in Flexible PCBs
Continuous innovation in flexible PCB technology, including multilayer and ultra-thin designs, is enhancing the value of FCCLs by supporting complex, high-speed, and space-efficient electronic assemblies.
Sustainability and Halogen-Free Materials
Stricter environmental regulations and consumer demand for eco-friendly electronics are pushing manufacturers to develop halogen-free and recyclable FCCLs, opening new market opportunities and ensuring compliance with global standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Flexible Copper Clad Laminate (FCCL) market in 2023, and what is its projected size and CAGR by 2032?
Which industries are the primary drivers of FCCL demand?
Why is FCCL preferred in modern electronic applications?
Which region holds the largest share in the FCCL market?
Who are the leading players in the global FCCL market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Thickness
- 1.2.1 Thin (<0.5 mm)
- 1.2.2 Medium (0.5 mm to 1.5 mm)
- 1.2.3 Thick (>1.5 mm)
- 1.3 By Application
- 1.3.1 Consumer Electronics
- 1.3.2 Automotive Electronics
- 1.3.3 Aerospace and Defense
- 1.3.4 Medical Devices
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Single-Sided Flexible Copper-Clad Laminate
- 1.4.2 Double-Sided Flexible Copper-Clad Laminate
- 1.4.3 Multi-Layer Flexible Copper-Clad Laminate
- 1.5 By Material Type
- 1.5.1 Polyimide Copper-Clad Laminate
- 1.5.2 Epoxy Resin Copper-Clad Laminate
- 1.5.3 PTFE (Teflon) Copper-Clad Laminate
- 1.5.4 Flexible Insulation Copper-Clad Laminate
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,319 million → 2032: USD 2,581.24 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Flexible Copper Clad Laminate (FCCL) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Flexible Copper Clad Laminate (FCCL) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Flexible Copper Clad Laminate (FCCL) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Flexible Copper Clad Laminate (FCCL) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Flexible Copper Clad Laminate (FCCL) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Flexible Copper Clad Laminate (FCCL) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Flexible Copper Clad Laminate (FCCL) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Flexible Copper Clad Laminate (FCCL) Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,319 million → 2032: USD 2,581.24 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Flexible Copper Clad Laminate (FCCL) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Thickness - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Thin (<0.5 mm)
- 12.3.7.2 Medium (0.5 mm to 1.5 mm)
- 12.3.7.3 Thick (>1.5 mm)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Consumer Electronics
- 12.4.7.2 Automotive Electronics
- 12.4.7.3 Aerospace and Defense
- 12.4.7.4 Medical Devices
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single-Sided Flexible Copper-Clad Laminate
- 12.5.7.2 Double-Sided Flexible Copper-Clad Laminate
- 12.5.7.3 Multi-Layer Flexible Copper-Clad Laminate
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Material Type - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Polyimide Copper-Clad Laminate
- 12.6.7.2 Epoxy Resin Copper-Clad Laminate
- 12.6.7.3 PTFE (Teflon) Copper-Clad Laminate
- 12.6.7.4 Flexible Insulation Copper-Clad Laminate
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Flexible Copper Clad Laminate (FCCL) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Flexible Copper Clad Laminate (FCCL) Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Flexible Copper Clad Laminate (FCCL) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Flexible Copper Clad Laminate (FCCL) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nippon Steel Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Doosan Corporation
- 18.4 Shin-Etsu Chemical Co., Ltd.
- 18.5 Kingboard Holdings Limited
- 18.6 Isola Group
- 18.7 Rogers Corporation
- 18.8 ITEQ Corporation
- 18.9 Panasonic Corporation
- 18.10 Taiflex Scientific
- 18.11 LG Chem
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

