
Market Overview
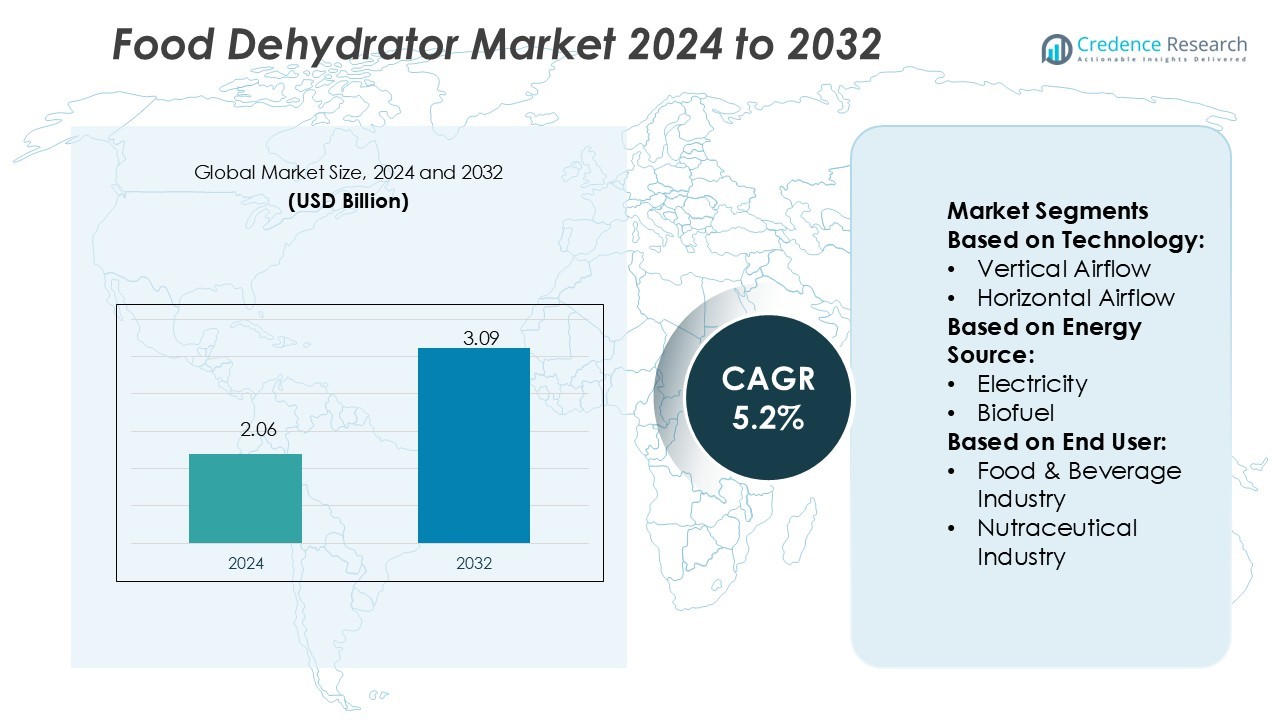
Food Dehydrator Market size was valued USD 2.06 billion in 2024 and is anticipated to reach USD 3.09 billion by 2032, at a CAGR of 5.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Dehydrator Market Size 2024 | USD 2.06 Billion |
| Food Dehydrator Market, CAGR | 5.2% |
| Food Dehydrator Market Size 2032 | USD 3.09 Billion |
The food dehydrator market is shaped by key players including Hamilton Beach Brands, Kerone Engineering Solutions, Aroma Housewares, Foshan Mel-Tech Electrical Appliances Company, Vitality 4 Life, Waring Commercial, The Metal Ware (Nesco), Koolatron, Ekotec Energy Heat Pumps, and National Presto Industries. These companies focus on innovation, energy efficiency, and expanding product portfolios to meet growing demand across residential, commercial, and industrial applications. Asia-Pacific leads the global market with a 35% share, driven by strong cultural acceptance of dried foods, rapid urbanization, and expanding nutraceutical and herbal industries. The region’s dominance is supported by rising disposable incomes, large agricultural output, and widespread e-commerce penetration, making it the fastest-growing market for both traditional and advanced dehydration systems.
Market Insights
- The Food Dehydrator Market size was valued at USD 2.06 billion in 2024 and is projected to reach USD 3.09 billion by 2032, growing at a CAGR of 5.2% during the forecast period.
- Market growth is driven by rising demand for packaged snacks, dried fruits, nutraceutical products, and herbal supplements, supported by consumer preference for clean-label and preservative-free foods.
- Key trends include the adoption of energy-efficient and solar-powered dehydrators, integration of smart controls, and expansion of e-commerce channels, making products more accessible to both households and commercial users.
- Competitive dynamics are shaped by major players such as Hamilton Beach Brands, The Metal Ware (Nesco), National Presto Industries, and others focusing on product innovation, while high initial costs and energy consumption remain key restraints.
- Asia-Pacific leads the market with a 35% share, followed by North America at 28% and Europe at 24%, while the food and beverage industry dominates end-user adoption with the largest segment share.
Market Segmentation Analysis:
By Technology
The horizontal airflow segment dominates the food dehydrator market with 58% share. This design ensures even drying, preventing flavor mixing and providing consistent product quality. Its suitability for large-scale dehydration of fruits, vegetables, and meat products makes it a preferred choice for commercial and industrial users. Growing demand for uniform quality in packaged foods drives adoption. Manufacturers are also integrating digital controls and energy-efficient features into horizontal models, further strengthening their market share compared to vertical airflow dehydrators.
- For instance, Hamilton Beach’s commercial model 78450 uses a horizontal airflow fan system rated at 1,200 W to ensure consistent drying across 10 trays (16 sq ft drying area).
By Energy Source
Electricity leads the energy source segment, accounting for 65% market share. Widespread availability of electric infrastructure and consistent performance make it the most reliable choice. Electric dehydrators are widely used in both residential and industrial settings due to their ease of operation, stable output, and integration with temperature-control systems. Rising household adoption of electric dehydrators for small-scale food preservation and the food industry’s preference for precise drying processes support this segment’s dominance. Solar-based dehydrators are gaining traction in emerging economies, but they remain secondary.
- For instance, EcoTech Solutions manufactures a commercial-grade food dehydrator with 12 stainless steel trays that uses a 1,000 W heating and fan system to provide consistent airflow.
By End-User
The food and beverage industry is the largest end-user, holding 42% share of the market. Growing demand for packaged and processed food products, such as dried fruits, snacks, and meat products, fuels adoption. Companies in this sector rely on dehydrators to extend shelf life, maintain nutritional value, and reduce waste. Rising health awareness has also boosted demand for clean-label dehydrated products, strengthening industry reliance on dehydration systems. While domestic usage is increasing with consumer self-sufficiency trends, commercial food producers remain the dominant growth driver.
Key Growth Drivers
Rising Demand for Packaged and Processed Foods
The growing popularity of packaged snacks, dried fruits, and ready-to-eat meals drives strong demand for food dehydrators. Consumers are increasingly seeking convenient, long-lasting products that retain nutritional value. Food manufacturers depend on dehydrators to extend product shelf life and reduce spoilage losses. Rising urbanization and changing lifestyles further increase reliance on packaged food options, strengthening the role of dehydration technologies. This demand supports continuous adoption across both commercial and industrial applications, making it a core growth driver for the global food dehydrator market.
- For instance, Vitality 4 Life is the manufacturer of the BioChef Arizona Sol series of food dehydrators. The dehydrator uses a rear-mounted, fan-forced horizontal airflow system, which ensures consistent drying across the trays without the need for rotation.
Health and Wellness Trends Supporting Natural Products
The rising focus on natural, chemical-free, and clean-label food products boosts demand for dehydrators. Consumers are favoring nutrient-rich snacks and herbal products without artificial preservatives. Dehydration helps retain vitamins, minerals, and flavors while eliminating the need for additives. This aligns with the wellness-driven food culture, where dried fruits, vegetables, and herbal supplements are gaining popularity. Nutraceutical and herbal industries benefit significantly from this trend, as they rely on dehydration technology for quality preservation. The clean-label movement is therefore a major catalyst for market growth.
- For instance, Waring Commercial's WDH10 10-Tray Dehydrator is built with an 800 W heating and fan system that delivers horizontal airflow across 10 stainless steel trays, offering a total drying area of 1.3 m² (14 sq. ft.).
Technological Advancements in Dehydration Systems
Continuous innovations in airflow systems, energy-efficient designs, and digital automation accelerate the adoption of food dehydrators. Horizontal airflow models with precision temperature controls ensure uniform drying, meeting industrial quality standards. Integration of smart controls and IoT-based monitoring allows users to optimize processes and reduce energy costs. Solar-powered and biofuel-based dehydrators are also gaining attention in emerging economies, offering sustainable solutions. These technological advancements enhance product reliability, operational efficiency, and eco-friendly benefits, positioning advanced dehydrators as a preferred choice in both developed and developing markets.
Key Trends & Opportunities
Growing Adoption of Solar-Powered Dehydrators
The push toward sustainable energy solutions creates opportunities for solar-based dehydrators. Emerging economies with high agricultural outputs benefit from cost-effective, eco-friendly drying solutions that reduce dependency on electricity. Governments and NGOs support solar dehydrator adoption in rural areas, promoting small-scale food preservation and reducing post-harvest losses. This trend aligns with global climate goals, presenting opportunities for manufacturers to design affordable solar-powered units. With increasing demand for green technology, solar dehydrators are expected to expand their footprint in both developing and developed regions.
- For instance, Nesco manufactures the FD-1040 Gardenmaster Digital
- Operates on 1,000 W Product descriptions and specifications for the FD-1040 confirm it has a 1,000 W drying power.
Expansion of E-Commerce Distribution Channels
The rapid growth of online retail platforms creates new opportunities for dehydrator sales. Consumers are increasingly purchasing dehydrators through e-commerce, supported by competitive pricing and doorstep delivery. Food processors also leverage digital channels to source commercial-grade equipment, improving market access. Small-scale producers and households in urban areas benefit from the convenience of online distribution, boosting sales for both domestic and industrial dehydrators. The rise of digital marketing and direct-to-consumer strategies further enhances brand visibility, creating long-term growth potential for manufacturers globally.
- For instance, Ekotec also offers standard air-source monoblock heat pumps: for example, model ETH25W01T features nominal heating capacity 24 kW, power consumption 11.4 kW, and a COP of 2.11, operating across –10 °C to +45 °C ambient range.
Key Challenges
High Initial Costs and Energy Consumption
Food dehydrators, especially advanced horizontal airflow and industrial-grade models, require significant upfront investment. Small and medium enterprises often struggle with affordability, limiting adoption. Additionally, high energy consumption in electricity-based units increases operational costs, posing challenges in cost-sensitive markets. Although energy-efficient and solar-powered designs are emerging, they remain less accessible due to limited availability and higher pricing. This cost-related barrier continues to restrict wider market penetration, especially in developing economies where purchasing power is comparatively lower.
Limited Awareness in Developing Regions
In many emerging economies, awareness about modern food dehydration technologies remains limited. Farmers and small businesses often rely on traditional drying methods, leading to higher wastage and lower product quality. Lack of technical knowledge and inadequate training further delay adoption of advanced systems. While government programs and NGOs promote modern practices, penetration remains slow due to infrastructure and affordability constraints. This challenge hampers the market’s full potential in regions with abundant agricultural produce, reducing opportunities for manufacturers to expand effectively.
Regional Analysis
North America
North America holds a 28% share of the food dehydrator market, supported by high demand for packaged and processed food. The U.S. leads consumption due to strong household adoption and large-scale industrial use in the food and beverage sector. Rising popularity of clean-label snacks, jerky, and dried fruits drives growth. Technological advancements, including smart dehydrators with digital controls, further strengthen adoption. The nutraceutical and herbal industries also contribute significantly, as dehydration ensures preservation of nutritional value. Strong distribution networks and e-commerce platforms support steady market expansion across both domestic and commercial segments.
Europe
Europe accounts for 24% of the global food dehydrator market, driven by stringent food quality regulations and rising demand for healthy, preservative-free snacks. Countries such as Germany, France, and the UK dominate adoption, supported by advanced food processing industries. Growing interest in organic and herbal products boosts the use of dehydrators in the nutraceutical sector. Energy-efficient models and sustainable drying solutions gain traction, aligning with the region’s climate goals. Increasing consumer preference for dried fruits, vegetables, and herbal supplements continues to support steady growth, particularly in Western Europe’s mature markets.
Asia-Pacific
Asia-Pacific leads the food dehydrator market with a 35% share, driven by rapid urbanization, rising disposable incomes, and strong cultural acceptance of dried foods. China, India, and Japan represent key markets, with high consumption of dried fruits, vegetables, and herbal products. Expanding nutraceutical and herbal industries also fuel demand for dehydration systems. Solar-powered dehydrators are gaining popularity in rural areas, helping reduce post-harvest losses. The region’s large agricultural output supports continuous adoption across commercial and industrial applications. Growing e-commerce distribution networks further enhance accessibility, positioning Asia-Pacific as the fastest-growing regional market.
Latin America
Latin America holds a 7% share of the food dehydrator market, supported by growing food processing industries in Brazil, Mexico, and Argentina. Rising consumer interest in convenient and shelf-stable food products fuels demand for dehydration technologies. The herbal and nutraceutical industries, particularly in Brazil, drive adoption for processing native plants and natural health products. However, limited awareness and affordability issues constrain faster market growth. Increasing investments in modern food processing infrastructure and expanding retail networks are expected to create new opportunities. Solar-powered dehydrators are also gaining attention in rural and agricultural communities.
Middle East & Africa
The Middle East and Africa represent 6% of the global food dehydrator market, with gradual adoption driven by urbanization and growing demand for packaged food. South Africa and GCC countries lead the regional market, supported by rising interest in health and wellness products. The herbal products industry is a key growth driver, particularly in countries with a strong tradition of natural remedies. Limited awareness and high equipment costs hinder widespread adoption. However, increasing e-commerce penetration and government support for small-scale food processing present opportunities for market expansion in the coming years.
Market Segmentations:
By Technology:
- Vertical Airflow
- Horizontal Airflow
By Energy Source:
- Electricity
- Biofuel
By End User:
- Food & Beverage Industry
- Nutraceutical Industry
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The food dehydrator market players such as Hamilton Beach Brands, Kerone Engineering Solutions, Aroma Housewares, Foshan Mel-Tech Electrical Appliances Company, Vitality 4 Life, Waring Commercial, The Metal Ware (Nesco), Koolatron, Ekotec Energy Heat Pumps, and National Presto Industries. The food dehydrator market is characterized by strong competition, with companies focusing on innovation, energy efficiency, and advanced airflow technologies to strengthen their market presence. Manufacturers are expanding product portfolios to serve both residential users seeking compact, affordable models and commercial buyers requiring large-scale dehydration systems. The demand for multifunctional units with digital controls, precision temperature settings, and sustainable energy options is driving technological advancements. E-commerce distribution and direct-to-consumer strategies further enhance brand visibility and global reach. Growing emphasis on eco-friendly solutions, such as solar and energy-efficient dehydrators, positions manufacturers to capture new opportunities in both developed and emerging markets.
Key Player Analysis
- Hamilton Beach Brands
- Kerone Engineering Solutions
- Aroma Housewares
- Foshan Mel-Tech Electrical Appliances Company
- Vitality 4 Life
- Waring Commercial
- The Metal Ware (Nesco)
- Koolatron
- Ekotec Energy Heat Pumps
- National Presto Industries
Recent Developments
- In July 2025, MK Fire Doors makes the bold and strategic move of adding an innovative fire safety system to its offering. This is a huge leap in the direction of India's preparedness for emergencies and state-of-the-art architectural fire resistance.
- In September 2024, Tufwud, India's largest fire door manufacturer, proudly launched FD120 ID-ISI-certified India's first fully insulated fire door. This revolutionary new product, launched at the country's most prominent Fire & Security India Expo (FSIE) 2024 at Jio Convention Centre, Mumbai, raises the bar on fire safety by combining design, functionality, and highly effective defense.
- In January 2024, ComBank partnered with UNDP to donate food dehydrators to the Hettipola Women’s Society, aiding in drying produce for off-season use. The collaboration aims to boost local economy and ensure sustainable food sources.
- In March 2023, ASSA ABLOY, a major leader in the security business, agreed to purchase Mottura Serrature di sicurezza Spa, a recognized Italian company known for making secure residential armoured lock cases and security cylinders, thereby expanding ASSA ABLOY's product portfolio and market position.
Report Coverage
The research report offers an in-depth analysis based on Technology, Energy Source, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as demand for packaged and shelf-stable foods increases.
- Adoption of solar-powered and biofuel-based dehydrators will grow in emerging economies.
- Technological advancements will improve efficiency, airflow design, and energy savings.
- E-commerce channels will play a stronger role in product distribution worldwide.
- Rising health awareness will drive demand for clean-label and additive-free dehydrated products.
- The nutraceutical and herbal industries will increasingly rely on dehydration systems.
- Compact and smart home dehydrators will gain popularity among domestic users.
- Commercial food producers will continue to dominate adoption due to large-scale needs.
- Sustainable manufacturing practices will become a competitive differentiator for key players.
- Developing regions will see faster adoption as awareness and infrastructure improve.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Packaged and Processed Food Consumption
The increasing popularity of packaged snacks, dried fruits, and ready-to-eat meals is driving demand for food dehydrators, as manufacturers seek to extend shelf life and reduce spoilage. Urbanization and changing consumer lifestyles further boost reliance on convenient, long-lasting food products.
Health and Wellness Trends Favoring Clean-Label Products
Consumers are increasingly seeking natural, preservative-free foods, which has led to higher demand for dehydrated products that retain nutritional value without additives. This trend is particularly strong in the nutraceutical and herbal supplement sectors, where dehydration is essential for product quality.
Technological Advancements in Dehydration Systems
Innovations such as horizontal airflow designs, energy-efficient models, and smart digital controls are making dehydrators more effective and accessible. These advancements improve drying consistency, reduce energy costs, and appeal to both commercial and domestic users.
Expansion of E-Commerce and Direct-to-Consumer Channels
The growth of online retail platforms has made food dehydrators more accessible to a wider audience, supporting both household and commercial adoption. E-commerce enables competitive pricing, greater product variety, and convenient delivery, accelerating market penetration globally.
Adoption of Sustainable and Solar-Powered Dehydrators
Rising environmental awareness and the need for cost-effective solutions in emerging economies are driving the adoption of solar-powered and energy-efficient dehydrators. These technologies help reduce operational costs and align with global sustainability goals, opening new market opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Food Dehydrator Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Dehydrator Market projected to grow between 2025 and 2032?
Which Food Dehydrator Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Dehydrator Market?
Who are the leading companies in the Food Dehydrator Market?
Which region commanded the largest share of the Food Dehydrator Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Food & Beverage Industry
- 1.2.2 Nutraceutical Industry
- 1.2.3 Households
- 1.2.4 Commercial Food Processors
- 1.3 By Technology
- 1.3.1 Horizontal Airflow
- 1.3.2 Vertical Airflow
- 1.4 By Energy Source
- 1.4.1 Electricity
- 1.4.2 Solar
- 1.4.3 Biofuel
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.06 billion → 2032: USD 3.09 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Dehydrator Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Dehydrator Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Dehydrator Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Dehydrator Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Dehydrator Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Dehydrator Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Dehydrator Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Dehydrator Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.06 billion → 2032: USD 3.09 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Dehydrator Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food & Beverage Industry
- 12.3.7.2 Nutraceutical Industry
- 12.3.7.3 Households
- 12.3.7.4 Commercial Food Processors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Horizontal Airflow
- 12.4.7.2 Vertical Airflow
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Energy Source - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electricity
- 12.5.7.2 Solar
- 12.5.7.3 Biofuel
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Dehydrator End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Food Dehydrator Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Food Dehydrator Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Food Dehydrator Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hamilton Beach Brands
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kerone Engineering Solutions
- 18.4 Aroma Housewares
- 18.5 Foshan Mel-Tech Electrical Appliances Company
- 18.6 Vitality 4 Life
- 18.7 Waring Commercial
- 18.8 The Metal Ware (Nesco)
- 18.9 Koolatron
- 18.10 Ekotec Energy Heat Pumps
- 18.11 National Presto Industries
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

