
Market Overview
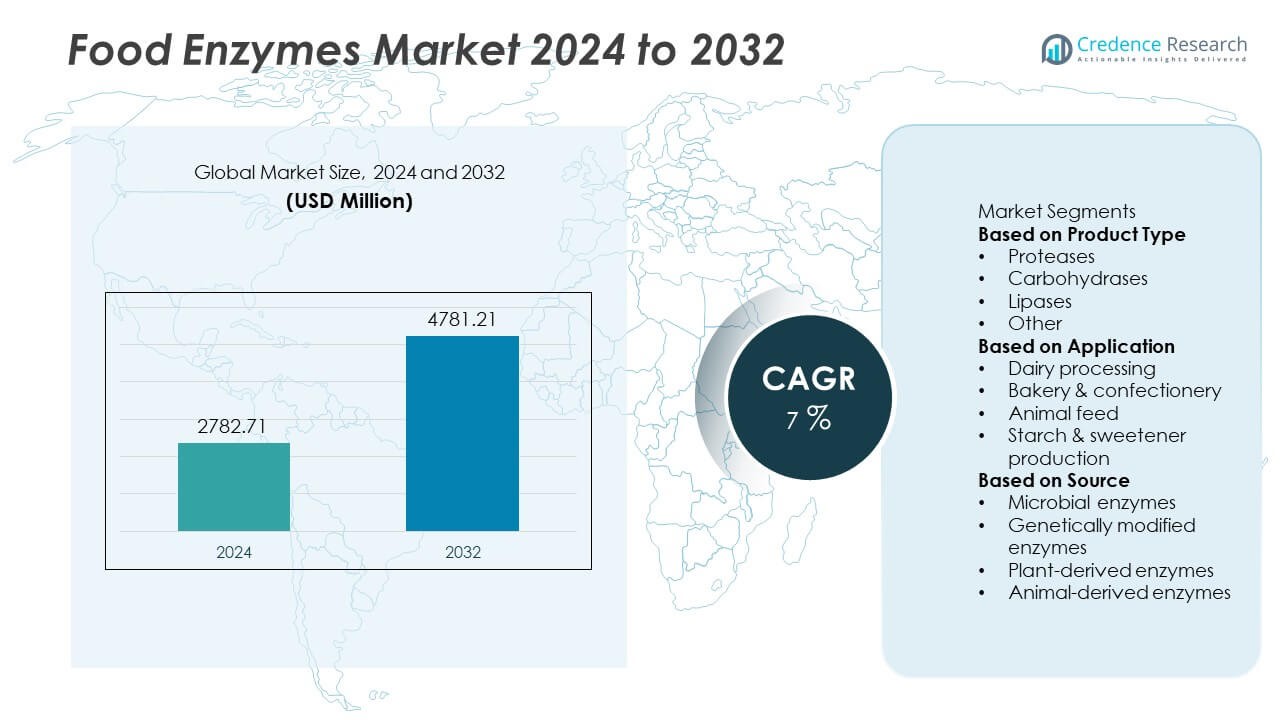
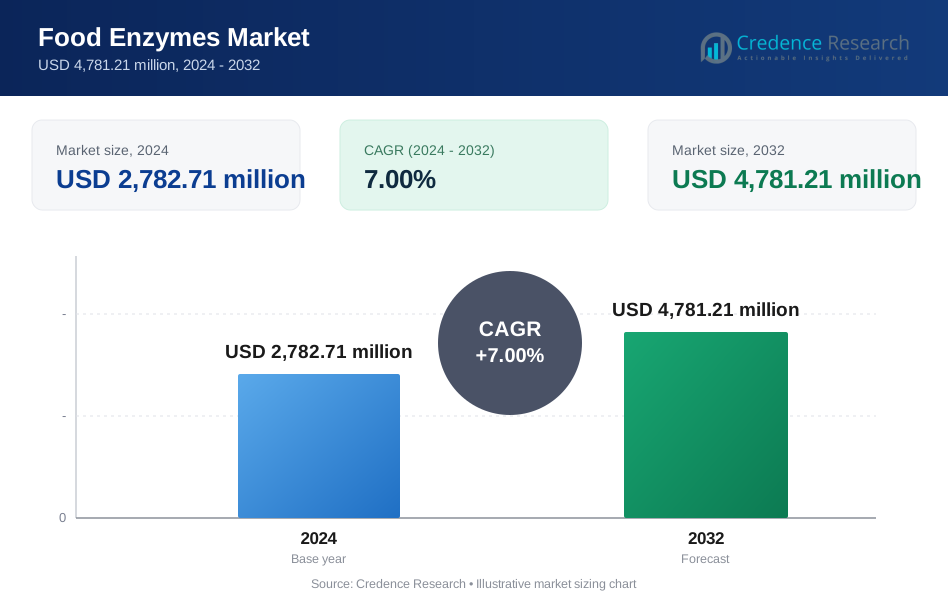
The Food Enzymes Market reached USD 2,782.71 million in 2024 and is projected to climb to USD 4,781.21 million by 2032, reflecting a steady 7% CAGR across the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Enzymes Market Size 2024 | USD 2,782.71 Million |
| Food Enzymes Market, CAGR | 7% |
| Food Enzymes Market Size 2032 | USD 4,781.21 Million |
The Food Enzymes market includes key players such as BASF SE, Advanced Enzyme Technologies Ltd, Novozymes A/S (now Novonesis), Chr. Hansen Holding A/S, Kerry Group plc, Kemin Industries Inc, Amano Enzyme Inc, International Flavors & Fragrances Inc. (IFF), Associated British Foods plc, and DSM-firmenich. These companies focus on expanding enzyme portfolios for bakery, dairy, brewing, and plant-based food applications. Strategic R&D investments enhance microbial and genetically engineered enzyme performance, supporting clean-label and reduced-sugar product development. North America leads the market with a 34% share, supported by strong adoption of enzyme-based processing in packaged foods, advanced fermentation capacity, and clear regulatory acceptance of food-grade enzyme formulations.
Market Insights
- The Food Enzymes market reached USD 2,782.71 million in 2024 and is expected to reach USD 4,781.21 million by 2032 at a 7% CAGR, driven by wider adoption in processed food production.
- Rising demand for clean-label bakery, dairy, and plant-based foods drives use of carbohydrases, which lead product type share at 46%, supporting texture, sweetness, and shelf-life improvement in packaged food categories.
- Trends include enzyme integration in sugar-reduced formulations, lactose-free dairy, and alternative protein processing, while rapid advancements in precision fermentation and strain engineering improve efficiency and cost control.
- The market remains competitive with strong innovation from global players focusing on tailored enzyme solutions, while regulatory approval complexity and cost sensitivity in emerging markets act as key restraints to faster penetration.
- North America holds 34%, Europe 28%, Asia Pacific 24%, Latin America 8%, and Middle East & Africa 6% of the market share, supported by strong bakery, dairy, and starch conversion industries across these regions.
Market Segmentation Analysis:
By Product Type:
Carbohydrases lead the Food Enzymes market with a 46% share due to strong demand in bakery, beverage, and sugar processing. Carbohydrases enhance texture, shelf life, and sweetness levels, supporting wider use in processed food categories. Proteases follow, driven by protein hydrolysis needs in dairy and meat tenderization. Lipases support flavor development in cheese and enzyme-modified dairy fats. The “Other” segment includes pectinases and lactases used for fruit juice clarification and lactose-free product manufacturing. Growth in carbohydrase use is driven by rising carbohydrate conversion efficiency, expanding enzymatic sweetener production, and increased investment in sugar reduction formulations across global markets.
- For instance, Novonesis expanded its baking enzyme line by adding a new solution called Novamyl® BestBite, a maltogenic alpha-amylase that helps maintain crumb softness, moistness, and elasticity in baked goods, ultimately improving shelf life and reducing food waste. It allows bread to remain fresh for much longer, with consumers liking bread that was 15 days old as much as fresh bread in a study.
By Application:
Bakery & confectionery remains the dominant application segment with a 39% share, supported by consistent demand for dough conditioning, volume improvement, and crumb structure enhancement. Enzymes help reduce additives and improve product softness and shelf stability. Dairy processing is the next major area due to enzyme roles in cheese ripening and lactose-free milk production. Starch and sweetener production benefits from enzymatic conversion for syrup and glucose manufacturing. Animal feed enzymes enhance nutrient absorption and digestion efficiency. Growth is driven by consumer preference for clean-label bakery products and steady industrial adoption of enzyme-based texture and flavor optimization.
- For instance, DSM-firmenich offers advanced bakery enzyme systems, such as the BakeZyme® portfolio, that are specifically designed to deliver precise, measurable improvements in dough quality and final product characteristics in commercial baking.
By Source:
Microbial enzymes hold the largest share at 52%, driven by high production efficiency, stability across pH and temperature variations, and ease of genetic enhancement. Genetically modified enzymes expand adoption by improving catalytic performance and enabling specialized food formulations. Plant-derived enzymes support clean-label and vegan positioning, while animal-derived enzymes serve niche applications such as rennet substitution in cheese manufacturing. Microbial sources dominate due to scalable fermentation, cost-effective downstream processing, and strong use in dairy, baking, brewing, and starch conversion. Their growth is further supported by rising investment in precision fermentation and increased regulatory approval for food-grade microbial enzyme strains.
Key Growth Drivers
Rising Demand for Processed and Functional Foods
Rising consumption of packaged, ready-to-eat, and functional foods drives higher adoption of food enzymes. Enzymes improve flavor, texture, shelf stability, and nutritional value, making them essential in bakery, dairy, beverage, and plant-based food categories. The shift toward protein-rich and fiber-enhanced diets also increases the use of specialty enzymes for hydrolysis and bioavailability improvement. Food manufacturers integrate enzymes to replace chemical additives and support clean-label product development. The demand surge remains aligned with urban lifestyles, expanding retail channels, and continuous product innovations across global markets.
- For instance, Advanced Enzyme Technologies produces a range of protein-hydrolyzing enzymes used in the food and beverage industry to increase the release of amino acids during controlled hydrolysis.
Expansion of Clean-Label and Natural Ingredient Formulations
Food enzymes support label simplification and removal of synthetic additives, enabling manufacturers to match clean-label purchasing behavior. Enzymes allow natural processing without compromising sensory attributes, making them ideal in dairy-free, gluten-free, and reduced-sugar products. Brands use enzymatic solutions to improve dough handling, lactose breakdown, protein modification, and flavor enhancement. Regulatory encouragement for reduced chemical usage further accelerates enzyme utilization. As consumer awareness of ingredient transparency strengthens, demand for enzymatic processing solutions increases across mainstream and premium food segments.
- For instance, Chr. Hansen, a major bioscience company now part of Novozymes, developed a lactase formulation called NOLA® Fit that enables the production of lactose-free or reduced-sugar dairy products without compromising the natural dairy taste.
Technological Advancements in Enzyme Engineering and Fermentation
Advances in enzyme engineering improve catalytic efficiency, substrate specificity, and temperature tolerance. Precision fermentation and genetically optimized microbial strains enhance enzyme yields and functionality for industrial-scale food production. Enhanced production methods reduce costs and allow development of application-specific enzymes for bakery, brewing, and nutritional manufacturing. Technologies supporting immobilized enzymes and controlled-release systems also unlock efficiency in continuous processing lines. Innovation in bioinformatics and protein modeling enables rapid enzyme customization, supporting wider commercialization across diverse food formulations.
Key Trends & Opportunities
Growth of Plant-Based and Alternative Protein Food Enzymes
Expansion of plant-based dairy and meat alternatives creates strong demand for specialized enzyme solutions. Enzymes improve texture, emulsification, and protein digestibility in soy, pea, and oat-based formulations. They also enable flavor development by reducing bitterness and enhancing fat simulation in vegan cheese and cultured products. As food manufacturers scale production of plant-based beverages and protein snacks, enzyme providers gain opportunities to deliver tailored solutions. Increasing investments in sustainable protein processing accelerate this trend and support long-term growth potential.
- For instance, Amano Enzyme offers a range of specialty proteases and protein-modifying enzymes, such as Protein Glutaminase "Amano" 500 (PG500) and Umamizyme™ Pulse, that improve the functionality and sensory properties of plant proteins, including pea isolates.
Increasing Use of Enzymes in Sugar Reduction and Nutritional Improvement
Food and beverage companies use enzymes to support sugar reduction, starch conversion, and functional carbohydrate development. Enzymatic processing helps create low-glycemic sweeteners and prebiotic fibers that meet nutritional labeling needs. Demand rises in bakery, confectionery, and beverages, where sweetness retention and calorie reduction remain key goals. Enzymes improve nutrient release and digestion benefits, enabling more nutritionally balanced product positioning. This trend strengthens opportunities in metabolic health and personalized nutrition-focused product portfolios.
- For instance, DuPont Nutrition & Biosciences offers various amylase solutions, such as Amylex 6T and SPEZYME ALPHA, which are highly effective for industrial starch processing, including brewing and ethanol production.
Key Challenges
Regulatory Compliance and Complex Approval Requirements
Stringent safety evaluation and approval procedures for enzyme-derived food ingredients challenge new product commercialization. Regional regulatory differences require extensive documentation, toxicology validation, and GRAS or novel-food certifications. Manufacturers must ensure allergen management and transparent labeling to meet compliance rules. Delays in clearance processes may restrict innovation cycles and market entry for emerging enzyme variants. This challenge raises development costs and increases the need for strong regulatory strategy across global food markets.
Price Sensitivity and Competition from Conventional Processing Methods
High enzyme development and production costs affect adoption in cost-sensitive food categories and emerging markets. Some manufacturers continue using traditional processing or chemical additives due to lower short-term costs, despite reduced sustainability benefits. Intense competition among enzyme suppliers and the presence of generic alternatives may pressure pricing strategies. Securing consistent fermentation inputs and managing supply chain disruptions also influence cost stability. These factors limit faster market penetration in lower-margin food manufacturing segments.
Regional Analysis
North America
North America holds a 34% market share driven by strong demand for processed bakery, dairy, and convenience food products. Large-scale adoption of microbial and genetically modified enzymes supports stable growth across the United States and Canada. Food manufacturers integrate enzymes to improve texture, shelf life, and nutritional quality while meeting clean-label standards. Advanced fermentation capabilities and a strong presence of enzyme technology developers further strengthen regional output. Regulatory support for reduced chemical additives and rising interest in sugar-reduced and lactose-free formulations continue to encourage enzyme adoption in commercial food processing operations.
Europe
Europe accounts for a 28% market share, supported by established bakery, confectionery, and specialty dairy processing industries. Enzyme utilization grows under strict labeling and sustainability regulations, reinforcing clean-label and natural ingredient development. Strong adoption of carbohydrases and proteases supports large industrial baking and brewing activities across Germany, France, the United Kingdom, and the Netherlands. The region benefits from leading research in precision fermentation and food biotechnology. Consumer demand for plant-based, gluten-free, and reduced-sugar foods accelerates the incorporation of specialty enzymes, enhancing product innovation across retail and foodservice channels.
Asia Pacific
Asia Pacific holds a 24% market share, driven by rapid expansion in processed food consumption across China, India, Japan, and Southeast Asia. Growing bakery and dairy production, along with rising demand for sweeteners and starch conversion, increases the use of carbohydrases and amylases. The region shows strong interest in enzyme-based texture modification, shelf-life enhancement, and flavor improvement for packaged food. Rising urbanization and investment in fermentation capacity strengthen enzyme supply capabilities. The growth of plant-based food and beverage manufacturers further boosts enzyme demand across diverse product categories.
Latin America
Latin America represents an 8% market share, supported by the expansion of bakery, beverage, and dairy production in Brazil, Mexico, Argentina, and Chile. Enzymes are increasingly used to improve dough stability, sweetness optimization, and lactose conversion, meeting changing consumer diets. Local producers adopt enzymes to reduce food waste and maintain product freshness during extended distribution cycles. Increasing investment in sugar processing and ethanol-related starch applications encourages carbohydrase and protease adoption. Growth opportunities strengthen as regional food processors align with global clean-label standards and enhance nutritional value in packaged food categories.
Middle East & Africa
The Middle East & Africa region holds a 6% market share, with growing demand for extended shelf-life bakery goods, dairy applications, and beverage processing. Enzymes support product consistency in hot-climate logistics, reducing spoilage and quality loss. Rising food manufacturing investment in the United Arab Emirates, Saudi Arabia, and South Africa drives interest in enzyme-enhanced processing. Expansion in halal and specialty nutrition products also increases demand for plant-derived and microbial enzyme solutions. Growth potential remains strong as countries enhance food security programs and encourage domestic production of enzyme-supported processed food products.
Market Segmentations:
By Product Type
- Proteases
- Carbohydrases
- Lipases
- Other
By Application
- Dairy processing
- Bakery & confectionery
- Animal feed
- Starch & sweetener production
By Source
- Microbial enzymes
- Genetically modified enzymes
- Plant-derived enzymes
- Animal-derived enzymes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape is characterized by major participants including BASF SE, Advanced Enzyme Technologies Ltd, Novozymes A/S (now Novonesis), Chr. Hansen Holding A/S, Kerry Group plc, Kemin Industries Inc, Amano Enzyme Inc, International Flavors & Fragrances Inc. (IFF), Associated British Foods plc, and DSM-firmenich. Companies strengthen their presence through enzyme engineering, precision fermentation, and application-specific formulation capabilities. Leading suppliers focus on expanding portfolios for bakery, dairy, brewing, starch conversion, and plant-based food processing to support cleaner formulations and texture optimization. Strategic partnerships with food manufacturers accelerate development of tailored solutions for reduced sugar, improved digestibility, and enhanced shelf-life stability. Investments in biotechnology and microbial strain improvement drive innovations in catalytic performance and cost-efficient production. Competitors also pursue acquisitions, joint ventures, and regional capacity expansion to enhance market reach, particularly in Asia Pacific and North America. Rising interest in sustainable and allergen-free enzyme sources encourages ongoing R&D initiatives and differentiated product positioning.
Key Player Analysis
- BASF SE
- Advanced Enzyme Technologies Ltd
- Novozymes A/S (now Novonesis)
- Hansen Holding A/S
- Kerry Group plc
- Kemin Industries Inc
- Amano Enzyme Inc
- International Flavors & Fragrances Inc. (IFF)
- Associated British Foods plc
- DSM-firmenich
Recent Developments
- In October 2025, BASF SE announced that it is evaluating strategic options for its feed enzymes business, aiming to find a partner focused on that segment.
- In October 2025, International Flavors & Fragrances Inc. (IFF) and BASF announced a strategic collaboration to develop next-generation enzyme and polymer technologies, including enzyme systems for industrial and cleaning applications.
- In September 2025, Kerry Group plc established a new Biotechnology Centre in Leipzig, Germany for enzyme and strain identification, engineering, fermentation and bioprocess development.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Food enzymes will gain wider adoption across bakery, dairy, beverage, and plant-based food processing.
- Enzyme engineering and precision fermentation will improve catalytic efficiency and reduce production costs.
- Clean-label and natural ingredient demand will accelerate enzymatic replacement of chemical additives.
- Sugar reduction and starch conversion enzymes will support healthier formulation strategies.
- Growth in lactose-free and digestive-friendly dairy products will increase demand for lactase and protease solutions.
- Enzyme use in plant-based meat and dairy alternatives will expand product texture and flavor optimization.
- Automation and digital monitoring will enhance enzyme dosing and processing accuracy in manufacturing lines.
- Mergers, acquisitions, and partnerships will strengthen global supply and innovation networks.
- Regional production capacity will grow, especially in Asia Pacific enzyme fermentation facilities.
- Sustainability goals will drive interest in enzyme-enabled waste reduction and improved resource efficiency in food production.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Clean-Label and Natural Ingredient Formulations
Food enzymes enable manufacturers to replace synthetic additives and simplify ingredient lists, aligning with consumer demand for clean-label, natural, and transparent food products. This trend is especially strong in bakery, dairy, and plant-based foods, where enzymatic processing supports natural texture and flavor without compromising product quality.
Technological Advancements in Enzyme Engineering and Fermentation
Innovations in precision fermentation, strain engineering, and enzyme immobilization have improved enzyme yields, specificity, and cost efficiency. These advancements allow for the development of application-specific enzymes that enhance processing efficiency and enable new product formulations across bakery, dairy, and alternative protein sectors.
Growth of Plant-Based and Alternative Protein Foods
The rise of plant-based dairy and meat alternatives is driving demand for specialized enzymes that improve texture, flavor, and protein digestibility in soy, pea, and oat-based products. Enzymes are critical for overcoming sensory and functional challenges in these rapidly expanding food categories.
Increasing Use of Enzymes in Sugar Reduction and Nutritional Improvement
Food and beverage manufacturers are leveraging enzymes to reduce sugar content, convert starches into functional sweeteners, and enhance the nutritional profile of products. This supports the development of low-glycemic, reduced-calorie, and fiber-enriched foods that meet evolving health and wellness trends.
Rising Demand for Processed and Functional Foods
Urbanization, changing lifestyles, and the popularity of ready-to-eat and functional foods are boosting the adoption of food enzymes. Enzymes improve shelf life, texture, and nutritional value, making them essential for large-scale production of bakery, dairy, and convenience foods.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Food Enzymes market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Enzymes market projected to grow between 2025 and 2032?
Which Food Enzymes market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Enzymes market?
Who are the leading companies in the Food Enzymes market?
Which region commanded the largest share of the Food Enzymes market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Microbial enzymes
- 1.2.2 Genetically modified enzymes
- 1.2.3 Plant-derived enzymes
- 1.2.4 Animal-derived enzymes
- 1.3 By Application
- 1.3.1 Dairy processing
- 1.3.2 Bakery & confectionery
- 1.3.3 Animal feed
- 1.3.4 Starch & sweetener production
- 1.4 By Product Type
- 1.4.1 Proteases
- 1.4.2 Carbohydrases
- 1.4.3 Lipases
- 1.4.4 Other
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,782.71 million → 2032: USD 4,781.21 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Enzymes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Enzymes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Enzymes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Enzymes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Enzymes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Enzymes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Enzymes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Enzymes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,782.71 million → 2032: USD 4,781.21 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Enzymes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Microbial enzymes
- 12.3.7.2 Genetically modified enzymes
- 12.3.7.3 Plant-derived enzymes
- 12.3.7.4 Animal-derived enzymes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dairy processing
- 12.4.7.2 Bakery & confectionery
- 12.4.7.3 Animal feed
- 12.4.7.4 Starch & sweetener production
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Proteases
- 12.5.7.2 Carbohydrases
- 12.5.7.3 Lipases
- 12.5.7.4 Other
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Enzymes End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Food Enzymes Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Food Enzymes Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Food Enzymes Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Advanced Enzyme Technologies Ltd
- 18.4 Novozymes A/S (now Novonesis)
- 18.5 Chr. Hansen Holding A/S
- 18.6 Kerry Group plc
- 18.7 Kemin Industries Inc
- 18.8 Amano Enzyme Inc
- 18.9 International Flavors & Fragrances Inc. (IFF)
- 18.10 Associated British Foods plc
- 18.11 DSM-firmenich
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

