
Food Waste Disposable Market Overview:
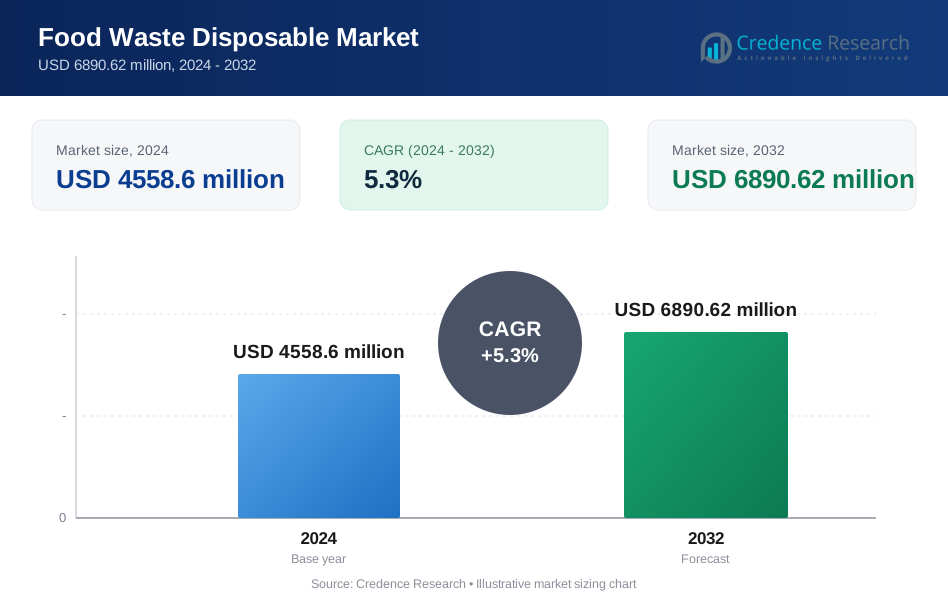
Food Waste Disposer Market size was valued USD 4558.6 million in 2024 and is anticipated to reach USD 6890.62 million by 2032, at a CAGR of 5.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Waste Disposer Market Size 2024 | USD 4558.6 million |
| Food Waste Disposer Market, CAGR | 5.3% |
| Food Waste Disposer Market Size 2032 | USD 6890.62 million |
Food Waste Disposable Market Insights
- Market growth is driven by stricter organic waste regulations, increasing adoption across commercial food service establishments, and growing emphasis on sustainable waste management and circular-economy practices.
- Key market trends include integration of disposers with anaerobic digestion and waste-to-energy systems, rising use of automation and digital monitoring, and product innovations focused on efficiency, durability, and noise reduction.
- Competitive intensity remains high as integrated waste service providers leverage large collection networks, advanced processing infrastructure, long-term municipal contracts, and technology-enabled operational optimization.
- North America leads the market with an exact 38% share, supported by strong regulatory frameworks, while residential disposers dominate by segment with an estimated ~46% share due to widespread household adoption and urban infrastructure maturity.

Food Waste Disposable Market Segmentation Analysis:
By Product Type
The Food Waste Disposer Market by product type is led by Residential food waste disposals, which account for an estimated 52% market share, driven by rising urbanization, smaller household sizes, and growing adoption of built-in kitchen appliances. Residential units benefit from compact designs, lower installation costs, and compatibility with standard plumbing systems, supporting penetration across apartments and single-family homes. Commercial food waste disposals follow, supported by restaurants, hotels, and institutional kitchens seeking hygiene compliance and labor efficiency. Industrial food waste disposals hold a smaller share but show steady uptake in large-scale food processing facilities focused on volume reduction and operational continuity.
- For instance, Rumpke manages a total throughput of more than 4.5 million tons of waste and recycling annually across its multi-state footprint. Its flagship Resource Center in Columbus the largest in North America features processing capacities exceeding 680 tons per day, utilizing 19 optical sorters and AI-driven automation to eliminate manual sorting of plastics.
By Technology
By technology, Mechanical food waste disposal systems dominate the market with approximately 61% share, owing to their proven reliability, cost-effectiveness, and ease of maintenance. Mechanical systems, based on grinding and motor-driven shredding, are widely adopted across residential and commercial settings due to simple operation and minimal process complexity. Biological/organic technologies are gaining traction in sustainability-driven facilities, while chemical disposal systems remain niche due to regulatory and safety constraints. Emerging options such as plasma arc and hybrid technologies are limited in adoption, primarily constrained to pilot projects and high-capital industrial applications.
- For instance, Veolia operates large-scale mechanical and biological food-waste treatment assets, including anaerobic digestion units designed to process more than 100,000 metric tons of organic waste per year per facility, equipped with automated feedstock pre-treatment lines capable of handling particle sizes below 12 millimeters and biogas upgrading systems delivering methane purity above 97%, as documented in its publicly disclosed organics treatment infrastructure specifications.
By Waste Processing Method
In terms of waste processing method, Grinding and shredding is the dominant sub-segment, holding nearly 57% market share, supported by its integration with mechanical disposers and ability to deliver immediate volume reduction. This method aligns well with household and foodservice environments requiring fast, on-site disposal. Anaerobic digestion is expanding steadily, driven by biogas recovery and circular economy initiatives in municipalities and large facilities. Composting remains relevant in decentralized and eco-focused installations, while waste-to-energy and other advanced methods are emerging selectively where infrastructure and regulatory support enable higher upfront investment.
Key Growth Drivers
Rising Urbanization and Household Convenience Demand
Rapid urbanization and changing lifestyles are driving sustained demand for food waste disposers, particularly in residential settings. Smaller household sizes, busier routines, and increased focus on kitchen hygiene are accelerating adoption of in-sink waste disposal systems as a convenient alternative to manual waste handling. Consumers increasingly value solutions that reduce odors, pests, and daily waste management effort. In urban apartments and modern housing projects, food waste disposers support cleaner kitchens and improved sanitation, making them an attractive appliance choice. This convenience-driven shift continues to expand the addressable consumer base across developed and emerging markets.
- For instance, Covanta Ltd. operates waste-to-energy facilities engineered with advanced material handling and combustion control systems capable of processing more than 20,000 tons of municipal solid waste per day across its operating network, using automated feed systems and real-time combustion monitoring that maintains furnace temperatures above 1,800 °F to ensure complete organic waste destruction, as detailed in the company’s publicly available facility and technology disclosures.
Regulatory Push for Organic Waste Reduction
Government regulations aimed at reducing landfill waste and diverting organic waste toward sustainable treatment methods are a major growth catalyst. Municipal mandates promoting source-level waste segregation and organic waste diversion encourage the use of food waste disposers as part of integrated waste management systems. By reducing the volume of food waste entering landfills, disposers help lower methane emissions and landfill dependency. Local authorities increasingly view these systems as supportive infrastructure for wastewater-based organic waste treatment, strengthening adoption across residential complexes, commercial kitchens, and institutional facilities under evolving environmental compliance frameworks.
- For instance, Biffa operates a nationwide organics network including eight flagship anaerobic digestion facilities with a combined processing capacity exceeding 600,000 metric tons of food waste per year. To ensure material quality, Biffa provides standardized 7-liter and 23-liter lockable caddy systems designed to eliminate odors and leaks during collection.
Expansion of Commercial Foodservice Infrastructure
The rapid expansion of restaurants, hotels, cafeterias, and institutional foodservice facilities is significantly boosting market growth. Commercial kitchens generate large volumes of food waste and require efficient, hygienic, and continuous disposal solutions to maintain operational efficiency. Food waste disposers reduce manual handling, labor costs, and downtime associated with waste storage and collection. As foodservice operators prioritize cleanliness, regulatory compliance, and streamlined back-of-house operations, demand for high-capacity, durable disposers continues to rise, particularly in quick-service restaurants, healthcare facilities, and large-scale catering operations.
Key Trends & Opportunities
Integration with Sustainable Waste Management Systems
A key trend shaping the market is the integration of food waste disposers with broader sustainable waste management and wastewater treatment ecosystems. Modern systems are increasingly designed to work alongside anaerobic digestion and waste-to-energy processes, enabling organic waste recovery rather than simple disposal. This creates opportunities for utilities and municipalities to convert food waste into biogas or nutrient-rich byproducts. Manufacturers that align disposer designs with sustainability goals, water efficiency standards, and municipal treatment capabilities are well positioned to capture long-term growth opportunities.
- For instance, Republic Services, Inc. operates 25 dedicated organics processing facilities across North America and has launched the proprietary Blue Polymers™ and Polymer Center network to advance plastics circularity.
Technological Advancements and Smart Features
Ongoing technological innovation is transforming food waste disposers into smarter, more efficient appliances. Advancements in grinding mechanisms, noise reduction, corrosion-resistant materials, and energy-efficient motors are improving performance and durability. The emergence of sensor-enabled and IoT-compatible disposers allows users and facility managers to monitor usage, detect overloads, and optimize maintenance schedules. These innovations enhance reliability and user experience, creating differentiation opportunities for manufacturers and supporting premium pricing in both residential and commercial segments.
- For instance, Remondis SE & Co., KG operates an extensive network of approximately 1,000 facilities in more than 30 countries, handling over 30 million tons of recyclables annually, including organic waste streams integrated into high-throughput processing systems that incorporate enclosed anaerobic digestion units and tunnel composting reactors designed to produce quality-assured compost and biogas.
Growth Opportunities in Emerging Economies
Emerging economies present strong untapped potential as urban infrastructure improves and awareness of hygienic waste management increases. Rising middle-class populations, growth in modern housing developments, and expansion of organized foodservice are creating new demand for food waste disposers. Although penetration remains relatively low, increasing investments in wastewater infrastructure and gradual regulatory alignment with waste reduction goals are opening long-term opportunities. Manufacturers that offer cost-effective, locally adapted solutions can accelerate adoption and establish early market leadership in these regions.
Key Challenges
Concerns over Water and Energy Consumption
One of the primary challenges facing the food waste disposer market is concern over increased water and energy usage. In regions facing water scarcity or strict resource conservation policies, disposers are sometimes viewed as adding pressure to utilities. Misperceptions about excessive water consumption can hinder adoption, particularly in residential markets. Manufacturers must address these concerns through efficient designs, consumer education, and compliance with water-saving standards to ensure broader acceptance across sustainability-conscious markets.
Infrastructure Compatibility and Regulatory Constraints
Infrastructure limitations and inconsistent regulatory frameworks pose another significant challenge. In areas with aging sewer systems or limited wastewater treatment capacity, authorities may restrict or discourage disposer installations due to concerns over pipe blockages and treatment overload. Additionally, regulations vary widely by region, creating complexity for manufacturers and installers. Overcoming these barriers requires collaboration with municipalities, infrastructure upgrades, and clear technical guidelines to ensure safe integration of food waste disposers into existing drainage and treatment systems.
Regional Analysis
North America
North America dominates the global food waste disposer market with an estimated 42% market share, supported by high household penetration, advanced plumbing infrastructure, and strict municipal waste diversion regulations. The United States drives regional demand due to widespread residential adoption, strong awareness of sustainability, and supportive local policies encouraging food waste reduction. Commercial installations across restaurants, hotels, and institutional kitchens further strengthen demand. Technological advancements such as noise-reduction motors, higher grinding efficiency, and stainless-steel components enhance replacement cycles. Additionally, smart home integration and energy-efficient disposer models continue to reinforce North America’s leadership position.
Europe
Europe accounts for approximately 27% of the global food waste disposer market, driven by stringent environmental regulations, landfill reduction mandates, and circular-economy initiatives. Countries such as the UK, Germany, and the Nordic nations show rising adoption in both residential and commercial segments as municipalities promote organic waste diversion. Growth remains uneven across the region due to plumbing constraints and regulatory restrictions in certain countries. However, increasing investments in sustainable kitchen appliances, compact disposer designs suitable for older infrastructure, and alignment with EU waste management directives are steadily improving adoption rates across Western and Northern Europe.
Asia-Pacific
Asia-Pacific holds nearly 21% market share and represents the fastest-growing regional market, supported by rapid urbanization, expanding middle-class populations, and rising awareness of food waste management. Japan, South Korea, China, and Australia are key contributors, driven by dense urban housing and increasing adoption of modern kitchen appliances. Government initiatives promoting waste segregation and smart city development support market expansion. While penetration remains relatively low in developing economies, improving plumbing infrastructure, growth in high-rise residential construction, and increasing demand from hotels and commercial kitchens continue to accelerate regional growth.
Latin America
Latin America contributes around 6% of the global food waste disposer market, with growth driven by gradual urban infrastructure development and increasing focus on municipal waste reduction. Brazil, Mexico, and Chile lead regional adoption, primarily in high-income urban households and commercial foodservice establishments. Market expansion remains constrained by limited awareness, cost sensitivity, and uneven plumbing compatibility. However, rising sustainability initiatives, growth in modern residential construction, and increased investment in hospitality and foodservice sectors are creating new opportunities. Over time, educational campaigns and localized product offerings are expected to improve adoption across the region.
Middle East & Africa
The Middle East & Africa region holds approximately 4% market share, reflecting early-stage adoption and infrastructure variability across countries. Demand is concentrated in developed urban centers such as the UAE, Saudi Arabia, and South Africa, where premium residential developments and commercial kitchens drive installations. Growth is supported by expanding hospitality sectors, particularly hotels and large catering facilities. However, limited awareness, water usage concerns, and regulatory inconsistencies restrict wider penetration. As urbanization accelerates and governments emphasize sustainable waste management solutions, gradual adoption of food waste disposers is expected across select markets.
Food Waste Disposable Market Segmentations:
By Product Type:
- Commercial food waste disposals
- Residential food waste disposals
By Technology:
- Mechanical
- Biological/organic
By Waste Processing Method:
- Compositing
- Anaerobic digestion
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Food Waste Disposer Market players such as Rumpke, Veolia, Covanta Ltd., Biffa, Republic Services, Inc., Remondis SE & Co., KG, Clean Harbors, Inc., Suez, Stericycle, Inc., Waste Management, Inc. the Food Waste Disposer Market is characterized by the presence of large, integrated waste management providers that compete on service breadth, processing efficiency, and regulatory expertise. Market participants focus on delivering end-to-end solutions that combine food waste collection, on-site and centralized disposal, composting, anaerobic digestion, and waste-to-energy processing to meet the needs of municipalities, commercial kitchens, and institutional facilities. Competitive differentiation increasingly depends on investments in automation, smart monitoring systems, and data-driven route and plant optimization to improve diversion rates and reduce operating costs. Companies also pursue long-term municipal contracts, public–private partnerships, and strategic acquisitions to strengthen regional coverage and secure stable revenue streams. Sustainability and circular-economy alignment remain central to competitive positioning, as stricter landfill diversion regulations and climate commitments drive demand for efficient, compliant, and scalable food waste disposer solutions.
Key Player Analysis
- Rumpke
- Veolia
- Covanta Ltd.
- Biffa
- Republic Services, Inc.
- Remondis SE & Co., KG
- Clean Harbors, Inc.
- Suez
- Stericycle, Inc.
- Waste Management, Inc.
Recent Developments
- In July 2025, SUEZ and SIAAP launched France's largest biogas unit at the Seine Aval plant near Paris, processing 130,000 tonnes of sludge yearly to produce 350 GWh of clean energy, powering the facility and supplying biomethane to the grid, making it a significant step in renewable energy for the Paris region.
- In April 2025, LG and Samsung have sued India's government to quash a policy which increases payouts to electronic-waste recyclers. Samsung and LG sued India’s environment ministry over e-waste pricing, citing disproportionate EPR-certificate costs.
- In February 2025, InSinkErator has published a new Designer catalogue and point of sale (POS) material, designed for kitchen retailers and designers. InSinkErator introduced its new designer catalog and point-of-sale material by showcasing the newly launched next-generation food waste disposers.
- In September 2024, Sumitomo Mitsui Banking Corporation (SMBC), in partnership with the Gramin Vikas Trust (GVT), launched a major e-waste management initiative in the Delhi-NCR region around focusing on a 360-degree approach to improve Reduce, Reuse, Recycle (RRR) centers, train waste workers, and raise community awareness about e-waste hazards, aiming for sustainable, replicable practices in India.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Technology, Waste Processing Method and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of food waste disposers will increase as governments strengthen landfill diversion and organic waste separation mandates.
- Integration of disposers with anaerobic digestion and biogas systems will expand to support circular-economy objectives.
- Smart and IoT-enabled disposers will gain traction to enable real-time monitoring, predictive maintenance, and performance optimization.
- Commercial establishments will accelerate adoption to improve hygiene, reduce waste handling costs, and meet sustainability targets.
- Municipal investments in decentralized food waste processing infrastructure will support wider market penetration.
- Product designs will focus on higher grinding efficiency, lower energy consumption, and reduced noise levels.
- Partnerships between disposer manufacturers and waste processing operators will increase to deliver integrated solutions.
- Emerging economies will witness faster adoption driven by urbanization and expanding food service industries.
- Regulatory incentives and green certifications will encourage replacement of traditional disposal methods with disposers.
- Long-term growth will be supported by rising awareness of food waste reduction and environmental impact mitigation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Food Waste Disposer Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Waste Disposer Market projected to grow between 2024 and 2032?
Which Food Waste Disposer Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Waste Disposer Market?
Who are the leading companies in the Food Waste Disposer Market?
Which region commanded the largest share of the Food Waste Disposer Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Food Waste Disposable Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Food Waste Disposable Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4558.6 million → 2032: USD 6890.62 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Food Waste Disposable Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Food Waste Disposable Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Food Waste Disposable Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Food Waste Disposable Market Drivers
- 3.3 Food Waste Disposable Market Restraints & Challenges
- 3.4 Food Waste Disposable Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Food Waste Disposable Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Food Waste Disposable Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Food Waste Disposable category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Food Waste Disposable Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Food Waste Disposable Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Food Waste Disposable market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Food Waste Disposable Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Food Waste Disposable Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Food Waste Disposable Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Food Waste Disposable (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Food Waste Disposable Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Food Waste Disposable Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Food Waste Disposable Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Food Waste Disposable Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Food Waste Disposable Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Food Waste Disposable Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Food Waste Disposable Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Food Waste Disposable Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Food Waste Disposable Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
