
Market Overview
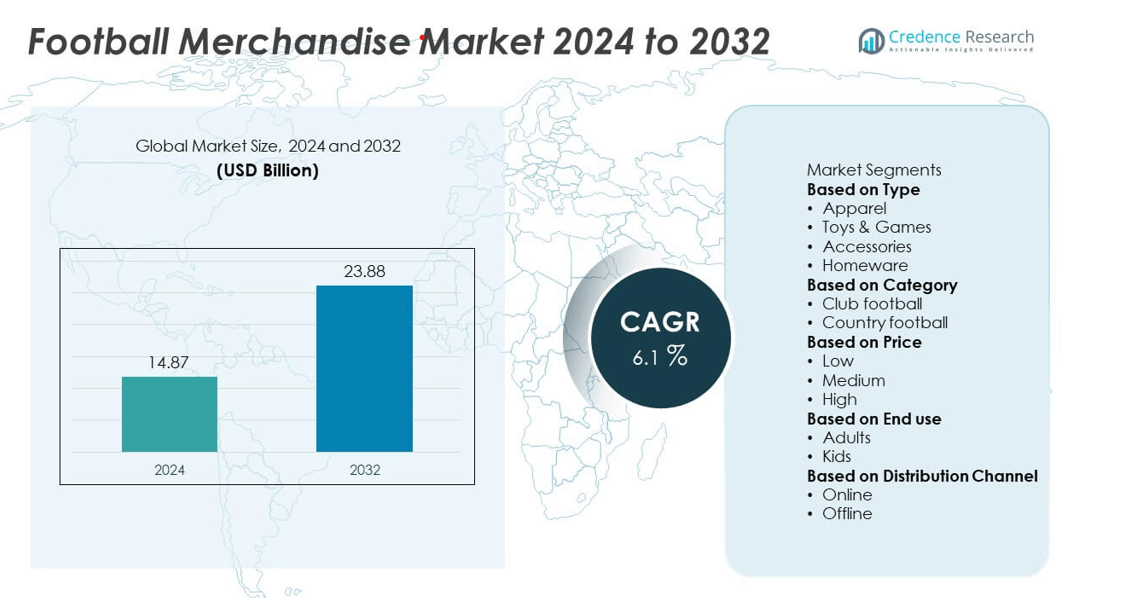
The Football Merchandise Market was valued at USD 14.87 billion in 2024 and is projected to reach USD 23.88 billion by 2032, expanding at a CAGR of 6.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Football Merchandise Market Size 2024 | USD 14.87 billion |
| Football Merchandise Market, CAGR | 6.1% |
| Football Merchandise Market Size 2032 | USD 23.88 billion |
The football merchandise market is driven by top players including Joma Sport, Nike, Inc., Fanatics, Inc., Mitre Sports International, Adidas AG, Kappa, Hummel International, New Era Cap Co., Inc., Le Coq Sportif, and Diadora. These companies strengthen their positions through official kit deals, licensed partnerships, and strong global retail networks. Europe led the market in 2024 with 35% of global share, supported by the dominance of major leagues and club followership. North America accounted for 28% share, driven by growing fan engagement and e-commerce adoption, while Asia Pacific captured 22% share, emerging as the fastest-growing region due to rising disposable incomes, youth participation, and increasing accessibility to licensed merchandise.
Market Insights
- The football merchandise market was valued at USD 14.87 billion in 2024 and is projected to reach USD 23.88 billion by 2032, growing at a CAGR of 6.1% during the forecast period.
- Rising global popularity of football and strong fan engagement through leagues, tournaments, and sponsorships drive merchandise demand, with apparel holding over 50% share in 2024.
- Key trends include the surge of e-commerce platforms, eco-friendly merchandise launches, and collaborations between sportswear and fashion brands to attract younger consumers.
- The competitive landscape is led by Joma Sport, Nike, Adidas, Fanatics, Kappa, Hummel, Mitre Sports, New Era, Le Coq Sportif, and Diadora, who focus on licensed products, digital retail, and sustainability initiatives.
- Regionally, Europe led with 35% share, North America followed with 28%, and Asia Pacific accounted for 22%, positioning itself as the fastest-growing region due to rising disposable incomes and increasing accessibility to licensed merchandise.
Market Segmentation Analysis:
By Type
Apparel dominated the football merchandise market in 2024, holding over 50% of total market share. Jerseys, training kits, and footwear remain the most purchased items, driven by fan loyalty and the growing popularity of football worldwide. Major clubs and national teams generate significant revenue through apparel sales, particularly during tournaments and league seasons. Collaborations with global sportswear brands and limited-edition releases further enhance demand. Toys & games, accessories, and homeware continue to expand, but apparel remains the core revenue generator due to its strong cultural and emotional connection with fans.
- For instance, Fanatics generated an estimated $7 billion in total revenue in 2023, with its core Fanatics Commerce division being the largest contributor.
By Category
Club football led the market in 2024 with around 65% share, supported by the global popularity of major leagues such as the English Premier League, La Liga, and Bundesliga. Fans consistently purchase club jerseys, scarves, and memorabilia to showcase loyalty and affiliation. Marketing campaigns, global fan bases, and sponsorship deals further boost demand in this segment. Country football, while smaller in share, sees spikes during international tournaments such as the FIFA World Cup and UEFA European Championship, where national pride drives significant merchandise sales.
- For instance, Nike provided the kits for the France national team at the 2022 FIFA World Cup, with reports highlighting a high demand for French football merchandise. The team's strong performance likely contributed to this demand, with one analysis of U.S. sales during the tournament suggesting that Nike was selling merchandise faster and at a higher price point than Adidas.
By Price
The medium price range dominated the football merchandise market in 2024, capturing over 45% share. This segment balances affordability with quality, appealing to the largest base of football fans across developed and emerging economies. Official club kits and licensed products in this range remain accessible while retaining authenticity, which strengthens consumer trust. Low-priced merchandise continues to attract younger and cost-conscious buyers, while high-priced categories, including premium memorabilia and limited-edition collectibles, cater to niche consumers and collectors. The medium segment’s mass appeal ensures its continued leadership in the market.
Key Growth Drivers
Rising Popularity of Football Worldwide
The growing global fan base of football is a primary driver of the football merchandise market. Major leagues such as the English Premier League, La Liga, and international tournaments like the FIFA World Cup and UEFA Champions League attract millions of fans, boosting demand for jerseys, accessories, and memorabilia. Clubs and federations leverage broadcasting rights and sponsorship deals to expand their reach, creating consistent demand for merchandise. The rise of youth participation in football further strengthens long-term market growth and merchandise consumption.
- For instance, Adidas sold more than 2 million Germany national team jerseys during the 2014 FIFA World Cup, which was the highest-selling national team jersey. The company sold more than 8 million jerseys in total across all sponsored teams that year, demonstrating how major tournaments drive apparel demand on a global scale.
Expanding E-Commerce and Online Retail Channels
The rapid growth of e-commerce platforms has transformed access to football merchandise globally. Fans now purchase official products directly from club websites, online sports retailers, and global e-commerce platforms. This accessibility enables international supporters to engage with their favorite clubs and national teams. Exclusive online launches, digital marketing campaigns, and direct-to-consumer strategies further boost sales. With increasing smartphone penetration and secure digital payment systems, online retail is expected to remain a key growth driver for the football merchandise market.
- For instance, Manchester United achieved record e-commerce revenues in fiscal year 2022, alongside generating over 2.8 billion digital interactions across all platforms and reaching more than 220 markets with its app, highlighting how e-commerce and digital engagement extend global reach for football merchandise.
Increased Fan Engagement and Brand Collaborations
Rising collaborations between football clubs, national teams, and global sportswear brands fuel merchandise demand. Partnerships with Nike, Adidas, and Puma result in limited-edition kits, fanwear, and collectible items. Clubs also partner with lifestyle and fashion brands to diversify product ranges, attracting younger and style-conscious consumers. Social media campaigns and celebrity endorsements further drive fan engagement and merchandise sales. This growing intersection between sport, fashion, and entertainment continues to push the football merchandise market forward, expanding both reach and consumer appeal.
Key Trends & Opportunities
Shift Toward Licensed and Authentic Products
Consumers are increasingly demanding officially licensed and authentic football merchandise to ensure quality and brand association. Clubs and federations have responded with improved distribution strategies, hologram tagging, and exclusive retail partnerships to reduce counterfeit risks. This trend creates opportunities for official partners to strengthen brand loyalty and increase revenue streams. Licensed products, particularly jerseys and collectibles, dominate sales during major tournaments, reflecting the rising importance of authenticity in consumer purchasing behavior.
- For instance, Nike uses RFID-enabled tags in its apparel and footwear to track inventory and ensure authenticity, as confirmed by its then-CEO in a June 2019 conference call. This technology helps manage supply chains and verify products.
Sustainability and Eco-Friendly Merchandise
The trend toward sustainable products is reshaping the football merchandise market. Leading sportswear brands are developing eco-friendly jerseys made from recycled polyester and organic cotton. Clubs are increasingly marketing sustainability initiatives, appealing to environmentally conscious fans. This opportunity aligns with global climate action goals while opening new consumer segments. Eco-friendly fanwear, accessories, and packaging are expected to grow, creating a competitive edge for clubs and brands that prioritize sustainability in their merchandise portfolios.
- For instance, Adidas manufactured more than 5.5 million football jerseys using recycled ocean plastic under its Parley for the Oceans initiative, including kits for Real Madrid and Bayern Munich, proving large-scale adoption of sustainable materials in sports merchandise.
Key Challenges
High Prevalence of Counterfeit Merchandise
The widespread availability of counterfeit products remains a significant challenge in the football merchandise market. Fake jerseys and accessories are often sold at lower prices, undermining official sales and damaging brand reputation. Despite anti-counterfeiting measures like holograms and exclusive licensing agreements, counterfeit trade continues to thrive, especially in developing markets. This issue impacts revenue generation for clubs and official partners while limiting the growth potential of licensed merchandise. Combating counterfeits requires stricter enforcement, consumer awareness, and stronger retail partnerships.
Seasonal and Tournament-Dependent Sales Fluctuations
The football merchandise market experiences strong seasonality, with sales peaking during major tournaments and league seasons but dropping significantly in off-season periods. Demand heavily relies on club performance, player transfers, and international competitions. This creates unpredictability in revenue streams for manufacturers and retailers. Smaller clubs and regions with fewer international tournaments face greater challenges in maintaining consistent merchandise sales. Developing year-round engagement strategies and lifestyle-oriented products is essential to address this seasonal dependency and stabilize market growth.
Regional Analysis
North America
North America held 28% of the global football merchandise market share in 2024, supported by growing fan bases of international leagues and rising popularity of Major League Soccer (MLS). The U.S. leads regional demand, with strong merchandise sales driven by global club followership and local league expansion. E-commerce channels play a vital role, allowing fans to access official products of European and South American clubs. Rising youth participation in football and upcoming events like the FIFA World Cup 2026 further strengthen merchandise demand. Canada and Mexico also contribute significantly, driven by active football cultures and international tournament participation.
Europe
Europe accounted for 35% of the football merchandise market share in 2024, making it the largest regional contributor. The presence of leading clubs in the Premier League, La Liga, Bundesliga, and Serie A drives robust merchandise sales. Fan loyalty, combined with club rivalries, fuels continuous demand for jerseys, scarves, and collectibles. The region also benefits from extensive retail networks and official club stores, supported by global sportswear partnerships. National team merchandise further spikes during major tournaments such as the UEFA European Championship. Europe’s strong football heritage ensures consistent growth, keeping the region at the forefront of merchandise revenues.
Asia Pacific
Asia Pacific captured 22% of the global football merchandise market share in 2024, emerging as the fastest-growing region. Rising football viewership in China, India, and Japan, along with the growing influence of European clubs in regional markets, drives merchandise demand. Increasing middle-class income levels and expanding online retail channels make official products more accessible. International clubs’ pre-season tours and marketing campaigns in Asia further strengthen fan engagement. The popularity of global tournaments, along with the rise of local football leagues, ensures continued growth. Asia Pacific’s large youth population provides a strong base for long-term merchandise expansion.
Latin America
Latin America represented 9% of the football merchandise market share in 2024, driven by the region’s deep-rooted football culture and passion for both club and national teams. Brazil and Argentina lead regional demand, with strong sales of jerseys and collectibles for both local clubs and global stars. Fan loyalty to national teams creates spikes during Copa América and FIFA World Cup events. Despite economic fluctuations, affordable merchandise and growing e-commerce adoption support steady growth. Local clubs are also enhancing partnerships with global brands, expanding product availability, and boosting official sales across regional and international markets.
Middle East & Africa
The Middle East & Africa accounted for 6% of the global football merchandise market share in 2024, fueled by rising interest in international football and hosting of high-profile events. Qatar’s hosting of the FIFA World Cup 2022 boosted regional merchandise sales and created long-term fan engagement. Countries like Saudi Arabia and the UAE are investing heavily in football clubs and international partnerships, driving increased merchandise adoption. In Africa, fan loyalty to European clubs such as Manchester United, Real Madrid, and Barcelona strengthens demand. Expanding online retail access and rising youth engagement further support steady growth in the region.
Market Segmentations:
By Type
- Apparel
- Toys & Games
- Accessories
- Homeware
By Category
- Club football
- Country football
By Price
- Low
- Medium
- High
By End use
- Adults
- Kids
By Distribution Channel
- Online
- Offline
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the football merchandise market is shaped by leading players such as Joma Sport, Nike, Inc., Fanatics, Inc., Mitre Sports International, Adidas AG, Kappa, Hummel International, New Era Cap Co., Inc., Le Coq Sportif, and Diadora. These companies maintain dominance through extensive product portfolios, global distribution networks, and strong partnerships with clubs, leagues, and national teams. Global giants like Nike and Adidas drive market leadership through official kit deals and high-profile sponsorships, while Fanatics focuses on digital retail platforms to expand accessibility. Regional brands such as Joma, Hummel, and Kappa strengthen their positions by serving niche markets and building partnerships with smaller clubs and federations. Companies are also prioritizing sustainability by introducing eco-friendly jerseys and merchandise lines. The market is further influenced by growing collaborations between sportswear brands and fashion labels, as well as rising investment in e-commerce and licensed merchandise to meet evolving consumer demand worldwide.
Key Player Analysis
- Joma Sport
- Nike, Inc.
- Nike, Inc.
- Fanatics, Inc.
- Mitre Sports International
- Adidas AG
- Kappa
- Hummel International
- New Era Cap Co., Inc.
- Le Coq Sportif
- Diadora
Recent Developments
- In August 2025, Adidas AG and Liverpool FC launched new home and away kits for the 2025/26 season, renewing their collaboration and bringing new designs to fans.
- In May 2025, Nike, Inc. launched its 2025 National Team football kits using Dri-FIT ADV material, with new mesh and ribbed zones tailored using body-mapping data.
- In 2025, Nike and the NFL introduced the 2025 Rivalries uniforms along with related fan merchandise (jerseys, hoodies, headwear), to be sold globally starting September 10.
Report Coverage
The research report offers an in-depth analysis based on Type, Category, Price, End use, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily with rising global fan engagement and football’s expanding reach.
- Apparel will remain the dominant merchandise category supported by official kit sales.
- E-commerce platforms will drive accessibility and boost international merchandise sales.
- Licensed and authentic products will gain more traction as consumers avoid counterfeits.
- Collaborations between sportswear and fashion brands will attract younger demographics.
- Sustainability will shape future merchandise with eco-friendly jerseys and accessories.
- Asia Pacific will remain the fastest-growing region due to rising incomes and youth participation.
- Europe will continue to lead the market, supported by strong club loyalty.
- Seasonal spikes during tournaments like the FIFA World Cup will boost revenues.
- Digital fan engagement and exclusive online launches will enhance brand visibility and sales.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Football Merchandise market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Football Merchandise market projected to grow between 2025 and 2032?
Which Football Merchandise market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Football Merchandise market?
Who are the leading companies in the Football Merchandise market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14.87 billion → 2032: USD 23.88 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Football Merchandise Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Football Merchandise Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Football Merchandise Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Football Merchandise Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Football Merchandise Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Football Merchandise Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Football Merchandise Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Football Merchandise Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14.87 billion → 2032: USD 23.88 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Football Merchandise Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Football Merchandise Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Football Merchandise Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Football Merchandise Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
