
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
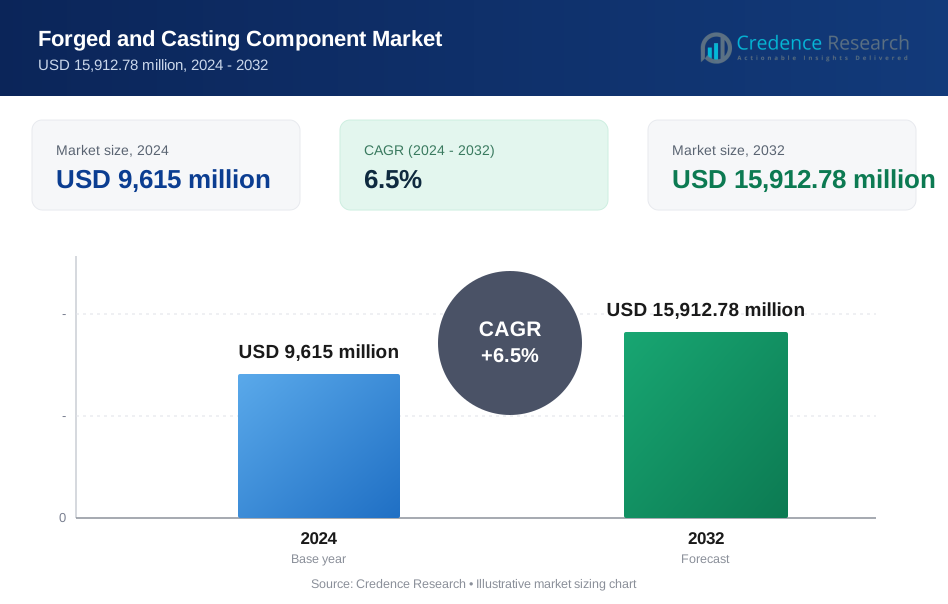
| Forged And Casting Component Market Size 2024 | USD 9,615 Million |
| Forged And Casting Component Market, CAGR | 6.5% |
| Forged And Casting Component Market Size 2032 | USD 15,912.78 Million |
Market Overview
The Forged And Casting Component Market is projected to grow from USD 9,615 million in 2024 to USD 15,912.78 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 6.5% during the forecast period.
The growth of the Forged and Casting Component Market is driven by increasing demand across automotive, aerospace, and construction industries, where durability and strength are critical. The rising trend toward lightweight materials in automotive and aerospace applications to improve fuel efficiency and reduce emissions has amplified the adoption of advanced forging and casting techniques. Additionally, rapid industrialization in emerging economies has fueled the demand for heavy machinery and equipment, further bolstering market growth. Technological advancements, including automation and precision casting, are enabling manufacturers to produce complex and high-quality components, meeting stringent industry standards. The growing focus on renewable energy infrastructure, such as wind turbines, is also contributing to market expansion, as forged and cast components play a vital role in their manufacturing. Furthermore, the increasing emphasis on sustainability and recycling in metal production is fostering the adoption of environmentally friendly practices in the forging and casting processes.
The Forged and Casting Component Market exhibits strong regional dynamics, with Asia-Pacific holding approximately 45% of the global market share, driven by rapid industrialization, urbanization, and the growth of automotive and construction sectors in countries like China, India, and Japan. North America follows with a substantial 25% market share, supported by advanced manufacturing capabilities, strong aerospace and defense sectors, and the adoption of sustainable practices in the U.S. and Canada. Europe is another key region, leveraging its established automotive and engineering industries. Leading players such as Robert Bosch GmbH, ZF Friedrichshafen AG, Thyssenkrupp AG, Magna International, and Denso Corporation dominate the market globally. These companies focus on technological innovation, strategic collaborations, and sustainable production methods, contributing significantly to the growth and competitiveness of the market.
Market Drivers:
Growing Demand from Automotive and Aerospace Industries:
The automotive and aerospace sectors are key drivers of the Forged and Casting Component Market, owing to their need for high-strength and durable components. In the automotive industry, forged and cast parts are essential in producing critical components like engine blocks, crankshafts, and suspension systems. For instance, the Ministry of Heavy Industries reported that India's automotive sector aims to double its size by 2024, driven by advancements in electric powertrains and self-driving technology. Similarly, the aerospace industry demands lightweight yet robust components, driving advancements in precision casting techniques to meet stringent safety and performance standards. The rising adoption of electric vehicles (EVs) further fuels the demand for lightweight forged and cast parts to improve energy efficiency.
Expansion of Industrial Infrastructure and Machinery:
The rapid growth of industrial infrastructure, particularly in emerging economies, is significantly propelling the market. Industries such as construction, mining, and energy rely heavily on forged and cast components for heavy machinery and equipment. For instance, the Indian government's National Industrial Corridor Development Programme aims to create new industrial cities as "Smart Cities," integrating next-generation technologies across various infrastructure sectors. The increasing investments in infrastructure projects and the rise of smart manufacturing facilities are boosting the demand for custom-designed forged and cast parts, tailored to meet specific industrial requirements.
Technological Advancements in Manufacturing Processes:
Innovations in forging and casting technologies are enhancing the quality, precision, and efficiency of component production. The adoption of computer-aided design (CAD) and automation in manufacturing has allowed for more intricate designs, reduced waste, and improved material utilization. For instance, the Government of India's "Make in India" initiative and the Production-Linked Incentive (PLI) scheme are driving technological advancements in manufacturing, including the integration of AI and IoT in production processes. Advancements in material science, including the development of high-performance alloys, are also enabling manufacturers to produce components with superior mechanical properties, catering to industries with specialized requirements such as defense and healthcare.
Sustainability and Circular Economy Initiatives:
The increasing focus on sustainability and environmental responsibility is driving the adoption of eco-friendly practices in the forging and casting industry. Recycling scrap metals and using energy-efficient production methods are becoming standard practices. For instance, Bharat Forge's sustainability report highlights their efforts in reducing specific energy consumption and greenhouse gas emissions through advanced manufacturing technologies and process optimization. Additionally, the push for a circular economy, where materials are reused and recycled, is encouraging industries to adopt forging and casting techniques that reduce raw material consumption and minimize waste, aligning with global sustainability goals.
Market Trends:
Adoption of Advanced Materials and Alloys:
The Forged and Casting Component Market is witnessing a significant shift toward the use of advanced materials and alloys to meet industry-specific requirements. High-performance materials like titanium, aluminum, and superalloys are gaining traction in aerospace, automotive, and medical sectors due to their superior strength-to-weight ratios and resistance to extreme conditions. For instance, a report by the Ministry of Heavy Industries highlights the increasing use of advanced aluminum alloys in the automotive sector to enhance fuel efficiency and reduce emissions. Manufacturers are investing in research and development to innovate new alloy compositions that enhance durability, reduce weight, and offer cost-effective solutions.
Integration of Automation and Smart Manufacturing:
Automation and smart manufacturing technologies are transforming the forging and casting processes, enabling precision, efficiency, and scalability. The use of robotics and computer-aided manufacturing systems ensures consistent quality and reduces production downtime. For instance, the Government of India's "Make in India" initiative promotes the adoption of smart manufacturing technologies, including IoT-enabled monitoring systems and digital twins, to enhance operational efficiency. These technological advancements are allowing manufacturers to produce complex geometries with high accuracy, meeting the growing demand for customized components.
Growth in Renewable Energy and Infrastructure Development:
The rise of renewable energy projects and infrastructure development is driving demand for forged and cast components. Wind turbines, solar panel mounting systems, and hydroelectric plants rely on these components for their structural integrity and performance. For instance, the Ministry of New and Renewable Energy reported significant growth in India's renewable energy capacity, with substantial investments in wind and solar projects. The construction boom in emerging economies and the expansion of smart cities are further increasing the need for heavy machinery and equipment, creating opportunities for the forging and casting industries to supply robust and reliable components.
Emphasis on Sustainable Manufacturing Practices:
Sustainability is becoming a key focus in the Forged and Casting Component Market, with manufacturers adopting eco-friendly practices. Recycling scrap metals, minimizing energy consumption, and reducing waste are integral to modern production processes. For instance, a report by the Global Council for the Promotion of International Trade (GCPIT) highlights that Indian manufacturers are increasingly adopting sustainable practices, such as recycling and energy-efficient processes, to reduce their environmental impact. Additionally, the industry is embracing life cycle analysis (LCA) and environmental impact assessments to align with global sustainability goals, ensuring that production methods are both cost-effective and environmentally responsible.
Market Challenges Analysis:
High Raw Material Costs and Supply Chain Disruptions:
One of the major challenges faced by the Forged and Casting Component Market is the volatility in raw material prices. The costs of key materials like steel, aluminum, and specialized alloys are subject to fluctuations due to geopolitical tensions, trade policies, and mining regulations. These unpredictable price changes strain manufacturers' profit margins, making it challenging to offer cost-effective solutions while maintaining product quality. Additionally, supply chain disruptions, particularly in the wake of global events such as pandemics or natural disasters, exacerbate the issue, delaying production timelines and impacting the availability of raw materials.
Stringent Environmental Regulations and Technological Barriers:
Stringent environmental regulations are another significant hurdle for the market. Governments worldwide are enforcing strict emission controls and waste management standards, compelling manufacturers to adopt eco-friendly production methods. While these initiatives promote sustainability, they also increase production costs and require substantial investments in upgrading technology and processes. Moreover, the technological complexity of advanced forging and casting techniques poses a barrier, particularly for small and medium-sized enterprises (SMEs). Limited access to high-end equipment and skilled labor hampers the ability of these businesses to compete effectively in the market, creating a disparity between large-scale manufacturers and smaller players.
Market Segmentation Analysis:
By Component Type
The Forged and Casting Component Market is broadly segmented by component type, including crankshafts, gears, bearings, and connecting rods. Among these, crankshafts and gears dominate due to their critical role in automotive and industrial machinery applications. These components ensure durability, performance, and reliability, particularly in high-stress environments. Bearings and connecting rods also play a significant role, especially in aerospace applications where precision and lightweight design are crucial. The increasing focus on lightweight components in automotive and aerospace industries is driving advancements in these segments to enhance performance and fuel efficiency.
By Material Type
The market is also categorized by material type, comprising steel, aluminum, titanium, and other specialized materials. Steel remains a key material owing to its high strength and cost-effectiveness, making it suitable for heavy-duty applications across various industries. Aluminum is rapidly gaining traction for its lightweight properties, aligning with the growing demand for fuel-efficient vehicles and aircraft. Titanium, though used in niche applications, is essential for sectors like aerospace and defense due to its superior resistance to extreme conditions. Other materials, such as superalloys and composites, are increasingly utilized for specialized applications, reflecting the market’s continuous adaptation to evolving industrial demands.
Segments:
Based on Component Type:
- Automotive
- Engine Components
- Transmission Components
- Structural Components
- Suspension Components
- Exhaust System Components
- Powertrain Components
- Interior Components
- Exterior Components
- Others
- Aerospace
-
- Safety Critical Structural Parts
- Non-Safety Critical Parts
- Arms & Defense
-
- Mobility
- Arms & Gear
- High-Performance Electronics & Automation
-
- Heat Management
- Electronic-Housings
- Automation Structural Parts
- Food & Beverage
-
- Structural Components
- Functional Components
Based on Material Type:
- Aluminum Alloy 2xxx Series
- Aluminum Alloy 3xxx Series
- Aluminum Alloy 5xxx Series
- Aluminum Alloy 6xxx Series
- Aluminum Alloy 7xxx Series
Based on Manufacturing Process:
- Casting Process
-
- Sand Casting
- Die Casting
- High Pressure Die Casting
- Others
- Forging Process
-
- Open Die Forging
- Closed Die Forging
- Upset Forging
- Precision Forging
- Rheocasting Process
- Others
Based on Sales Channels:
- OEM
- Aftermarket
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific leads the Forged and Casting Component Market, holding approximately 45% of the global market share, driven by rapid industrialization, urbanization, and expanding manufacturing sectors. Countries like China, India, and Japan are at the forefront, with China alone contributing a significant portion due to its robust automotive and industrial machinery industries. The region benefits from abundant raw material availability, low production costs, and a skilled workforce, making it a hub for forging and casting activities. Furthermore, the expanding construction sector in countries like India and Southeast Asia is boosting the demand for forged and cast components in heavy machinery and infrastructure projects. The automotive industry's rapid growth, particularly the increasing adoption of electric vehicles (EVs), adds to the demand for lightweight yet durable components. Japan, with its advanced manufacturing technology, also plays a crucial role in shaping the market dynamics in the region. In addition, Asia-Pacific is witnessing a surge in renewable energy projects, such as wind and solar power installations, which require high-performance forged and cast components for their equipment. The region's increasing focus on exports has prompted manufacturers to invest in advanced technologies to produce high-quality components that meet international standards. Government initiatives to promote domestic manufacturing through favorable policies and incentives further bolster the market's growth. The integration of automation and smart manufacturing practices in key markets is also driving efficiency, cost reduction, and innovation, solidifying Asia-Pacific's leadership in the global market.
North America
North America holds a substantial 25% share of the global Forged and Casting Component Market, driven by advanced manufacturing capabilities and the presence of major players in the automotive, aerospace, and defense sectors. The United States, in particular, plays a pivotal role in market growth, supported by technological advancements in forging and casting processes. The region's focus on lightweight materials and high-performance alloys meets the increasing demand for fuel-efficient vehicles and innovative aerospace applications. Additionally, the robust demand for forged components in the defense sector, such as aircraft and naval equipment, highlights North America's strategic importance in the global market. The region is also a leader in adopting sustainable manufacturing practices, with companies heavily investing in energy-efficient production methods and recycling initiatives. Government regulations promoting environmental responsibility have further driven these trends, encouraging manufacturers to adopt greener processes. Canada, with its strong emphasis on aerospace and energy industries, complements the market's growth in North America. Strategic partnerships between manufacturers and end-user industries, along with extensive R&D investments, ensure the region remains competitive on a global scale. Moreover, the integration of digital twins and IoT technologies into forging and casting processes enhances productivity and quality, aligning North America's industrial landscape with future market demands.
Key Player Analysis:
- Continental AG
- BorgWarner
- Denso Corporation
- Brembo S.p.A.
- Thyssenkrupp AG
- Magna International
- Lear Corporation
- Mahle GmbH
- JTEKT CORPORATION
- Hitachi Astemo, Ltd.
Competitive Analysis:
The Forged and Casting Component Market is highly competitive, with leading players such as Robert Bosch GmbH, ZF Friedrichshafen AG, Denso Corporation, Thyssenkrupp AG, and Magna International driving innovation and market expansion. These companies leverage advanced technologies, such as precision forging and automated casting, to produce high-quality components that meet the evolving demands of industries like automotive, aerospace, and construction. For instance, a report by the Ministry of Heavy Industries highlights the adoption of precision forging techniques in the automotive sector to enhance fuel efficiency and reduce emissions. The market is characterized by strategic partnerships, mergers, and acquisitions as key players aim to expand their global presence and enhance their product portfolios. Additionally, companies like Faurecia, Valeo S.A., Lear Corporation, and Eaton Corporation Plc are focusing on lightweight materials and sustainable production methods to align with global environmental goals and customer requirements. For instance, a survey by the International Energy Agency (IEA) emphasizes the importance of lightweight materials in reducing the carbon footprint of automotive components. With continuous investment in research and development, these players maintain a competitive edge by introducing innovative solutions and catering to the growing demand for reliable and efficient components across industries.
Recent Developments:
- In October 2024, Bharat Forge Ltd. announced the acquisition of AAM India Manufacturing Corporation Private Limited. This strategic move aims to enhance Bharat Forge's capabilities in manufacturing axles for commercial vehicles, thereby expanding its product portfolio in the automotive sector.
- In December 2024, GE Aviation expanded its investment casting capabilities with the opening of a new facility in the United States. This facility is dedicated to producing advanced turbine engine components for the aerospace industry.
- In December 2024, Bharat Forge launched a new line of high-performance aluminum casting products designed for electric vehicles. This initiative addresses the growing demand for lightweight and durable components in the expanding EV market.
- In February 2023, Hindustan Aeronautics Limited (HAL), Bharat Forge Limited, and Saarloha Advanced Materials Pvt Ltd entered into an MoU for the development and production of aerospace-grade steel alloys. This agreement was made during the Aero India event and is intended to reduce dependency on foreign suppliers for critical aerospace materials, supporting the Indian government's "Atmanirbhar Bharat" initiative.
Market Concentration & Characteristics:
The Forged and Casting Component Market exhibits a moderately fragmented structure, characterized by the presence of several key players and numerous regional manufacturers. Prominent companies such as Robert Bosch GmbH, ZF Friedrichshafen AG, and Thyssenkrupp AG dominate the market, leveraging their global reach, advanced technologies, and extensive product portfolios. These players focus on innovation, precision manufacturing, and sustainable practices to maintain their competitive edge. Despite the dominance of established players, regional manufacturers play a significant role, particularly in emerging economies where cost-effective production and localized operations are crucial. The market is marked by high competition, driven by the growing demand for lightweight materials, advanced alloys, and sustainable manufacturing processes. Strategic collaborations, mergers, and acquisitions are common as companies aim to expand their capabilities and market presence. Overall, the market's concentration highlights a dynamic balance between global leaders and regional contributors, fostering innovation and catering to diverse industry needs.
Report Coverage:
The research report offers an in-depth analysis based on Component Type, Material Type, Manufacturing Process, Sales Channels, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market
Future Outlook:
- The Forged and Casting Component Market is expected to witness steady growth driven by increasing demand from automotive and aerospace industries.
- Advancements in lightweight materials and high-performance alloys will shape the future of component manufacturing.
- The adoption of automation and digital technologies will enhance precision, efficiency, and production scalability.
- Renewable energy projects, including wind and solar, will create significant opportunities for forged and cast components.
- Emerging economies in Asia-Pacific and Latin America will drive market expansion with rising industrialization and infrastructure development.
- Sustainability will remain a key focus, with manufacturers adopting eco-friendly production methods and recycling initiatives.
- Strategic partnerships and collaborations between key players will strengthen global market presence and innovation.
- Increasing adoption of electric vehicles will accelerate the demand for lightweight and durable forged and cast components.
- Regulatory emphasis on reducing emissions and waste will push the industry toward greener practices.
- Investment in research and development will lead to innovations in materials, processes, and product designs, meeting evolving industry demands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Automotive and Aerospace Industry Growth
The need for high-strength, lightweight, and durable components in automotive and aerospace applications is driving demand for advanced forged and cast parts, especially as manufacturers seek to improve fuel efficiency and reduce emissions.
Industrialization and Infrastructure Expansion
Rapid industrialization and infrastructure development in emerging economies are increasing the demand for heavy machinery and equipment, which rely heavily on forged and cast components for performance and reliability.
Technological Advancements in Manufacturing
Innovations such as automation, computer-aided design, and precision casting/forging are enabling the production of complex, high-quality components, meeting stringent industry standards and supporting market growth.
Shift Toward Lightweight and Advanced Materials
The adoption of advanced alloys and lightweight materials, particularly in automotive and aerospace sectors, is boosting the use of forging and casting techniques to achieve better strength-to-weight ratios and improved efficiency.
Sustainability and Circular Economy Initiatives
Growing emphasis on recycling, energy-efficient production, and environmentally friendly practices in metalworking is fostering the adoption of sustainable forging and casting processes, aligning with global regulatory and customer expectations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Forged and Casting Component Market?
What factors are driving the growth of the Forged and Casting Component Market?
What are the key segments within the Forged and Casting Component Market?
What are some challenges faced by the Forged and Casting Component Market?
Who are the major players in the Forged and Casting Component Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material Type
- 1.2.1 Steel
- 1.2.2 Aluminum Alloy
- 1.2.3 Titanium
- 1.2.4 Superalloys
- 1.2.5 Composites
- 1.3 By Sales Channel
- 1.3.1 OEM
- 1.3.2 Aftermarket
- 1.4 By Component Type
- 1.4.1 Engine Components
- 1.4.2 Transmission Components
- 1.4.3 Structural Components
- 1.4.4 Suspension Components
- 1.4.5 Safety Critical Structural Parts
- 1.4.6 Heat Management Components
- 1.5 By Manufacturing Process
- 1.5.1 Sand Casting
- 1.5.2 Die Casting
- 1.5.3 Open Die Forging
- 1.5.4 Closed Die Forging
- 1.5.5 Precision Forging
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,615 million → 2032: USD 15,912.78 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Forged and Casting Component Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Forged and Casting Component Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Forged and Casting Component Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Forged and Casting Component Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Forged and Casting Component Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Forged and Casting Component Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Forged and Casting Component Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Forged and Casting Component Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,615 million → 2032: USD 15,912.78 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Forged and Casting Component Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Steel
- 12.3.7.2 Aluminum Alloy
- 12.3.7.3 Titanium
- 12.3.7.4 Superalloys
- 12.3.7.5 Composites
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 OEM
- 12.4.7.2 Aftermarket
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Component Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Engine Components
- 12.5.7.2 Transmission Components
- 12.5.7.3 Structural Components
- 12.5.7.4 Suspension Components
- 12.5.7.5 Safety Critical Structural Parts
- 12.5.7.6 Heat Management Components
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Manufacturing Process - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Sand Casting
- 12.6.7.2 Die Casting
- 12.6.7.3 Open Die Forging
- 12.6.7.4 Closed Die Forging
- 12.6.7.5 Precision Forging
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Forged and Casting Component Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Forged and Casting Component Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Forged and Casting Component Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Robert Bosch GmbH
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 ZF Friedrichshafen AG
- 17.4 Thyssenkrupp AG
- 17.5 Magna International
- 17.6 Denso Corporation
- 17.7 Bharat Forge Ltd.
- 17.8 Continental AG
- 17.9 BorgWarner
- 17.10 Brembo S.p.A.
- 17.11 Mahle GmbH
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

