
French banks move from pilots to group-wide AI platforms
The France AI in finance market was valued at USD 1.82 billion in 2025 and is projected to increase from USD 2.24 billion in 2026 to USD 14.21 billion by 2035, registering a CAGR of 22.80% during 2026–2035. Demand comes from banks, insurers, asset managers and payment firms that use machine learning to score fraud and credit risk and, since 2024, generative assistants to cut document work in branches, contact centers and investment banking. Île-de-France held the largest regional share, 58.0% in 2025, because the headquarters, trading floors and data teams of the main banking and insurance groups sit in and around Paris. Auvergne-Rhône-Alpes is the fastest-growing region at 23.9% a year, as regional cooperative banks and Lyon insurers roll group platforms out to local networks. The main commercial change is a move from in-house chatbots to multi-year model and cloud contracts, with French groups splitting work between Mistral AI, Google, Microsoft and their own private infrastructure.
Software, models and integration services make up the spend
The estimate covers AI software licenses and subscriptions, model and API consumption, AI features inside risk, fraud, analytics and customer service platforms, and the consulting, integration and managed services that deploy them. Buyers are banks, insurers and mutuelles, asset managers, market infrastructures, payment firms and fintechs operating in France, valued at the prices they pay to suppliers.
The estimate excludes general IT hardware, the salaries of in-house data teams and AI used by nonfinancial companies for their own accounting. Large groups buy models and cloud capacity directly from model owners and hyperscalers, while regional banks and smaller insurers mostly reach the same tools through group IT subsidiaries, software vendors and integrators.
France AI in Finance Market Insights
- The France AI in finance market was valued at USD 1.82 billion in 2025 and is projected to reach USD 14.21 billion by 2035, registering a CAGR of 22.80% during 2026–2035.
- Île-de-France held a 58.0% share of 2025 value, because the head offices and data teams of the main banking and insurance groups sit there.
- Fraud detection led applications with a 27.0% share of 2025 value, as payment fraud in France stood just under €1.2 billion in 2024.
- BPCE said in November 2025 that more than half of its 100,000 employees use AI daily, which shows how far generative tools have spread.
- BNP Paribas signed a five-year Google Cloud agreement in September 2026 while keeping some data categories out of the public cloud.
Fraud scoring leads while virtual assistants grow fastest
Licensed platforms lead while integration services grow faster
Based on component, the market is categorized into solution and services. Solution led with a 63.0% share of 2025 value, because most spending goes to licensed platforms that sit inside risk and compliance processes. Crédit Agricole renewed its multi-year SAS contract in December 2025 to run SAS Viya at its IT arm and its 39 regional banks, which serve 24 million clients, according to SAS. Services grow faster at 23.5% a year, as agent projects need integrators that redesign workflows, and Paris-based Capgemini completed its purchase of WNS on Oct. 17, 2025, to add agent-based operations services that it sells to banks and insurers.
On-premise leads as banks keep risk data in-house
Based on deployment mode, the market is categorized into on-premise and cloud. On-Premise led with a 54.0% share of 2025 value, because large groups keep customer and risk data inside their own data centers. Crédit Agricole’s IT arm routes AI workloads by sensitivity across its private cloud and outside partners, according to the group’s October 2026 release. Cloud grows faster at 24.1% a year, as per-seat assistants arrive as hosted services, and AXA announced in July 2026 a phased rollout of Microsoft 365 Copilot to employees worldwide, according to Reinsurance News.
Generative AI grows fastest from a classic ML base
Based on technology, the market is categorized into generative AI and other AI technologies. Other AI Technologies led with a 61.0% share of 2025 value, because fraud scoring, credit models and anti-money laundering checks still run on classic machine learning. Groupe BPCE uses Dataiku to improve its risk and anti-fraud processes and holds a backlog of more than 100 AI and data projects, according to Dataiku. Generative AI grows fastest at 24.8% a year, as staff use spreads quickly once a secure tool exists, and nearly nine in 10 trained Crédit Agricole employees use Sécuri’Chat regularly.
Instant-payment fraud keeps fraud detection in front
Based on application, the market is categorized into virtual assistant (chatbots), business analytics and reporting, fraud detection, quantitative and asset management, and others. Fraud Detection led with a 27.0% share of 2025 value, because instant transfers carried fraud of about €46 per €100,000 paid in 2024, against about €43 for consumer online-banking transfers and about €1 for all transfers, according to the Banque de France. Banks therefore buy fraud detection and prevention tools that check instant flows within seconds. Virtual assistants (chatbots) grow fastest at 24.3% a year, as HelloïZ, the Hello bank! assistant launched in January 2026, reached more than one million clients.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Component | Solution | 63.0% | Services | 23.5% |
| By Deployment Mode | On-Premise | 54.0% | Cloud | 24.1% |
| By Technology | Other AI Technologies | 61.0% | Generative AI | 24.8% |
| By Application | Fraud Detection | 27.0% | Virtual Assistant (Chatbots) | 24.3% |
Seat licenses and token fees set the cost of scale
Pricing combines per-seat assistant licenses, consumption fees for model calls and day-rate integration work. Seat prices look small, but a group with 100,000 staff faces annual license bills in the tens of millions of euros, which is why banks negotiate group contracts and route simple prompts to cheaper models. Token prices have fallen sharply as model owners compete, so the cost of a call matters less than volume and hosting terms. Suppliers that control the routing layer and the data connectors keep the highest margins, while pure resellers compete mainly on discounts.
| Offer | Typical price or fee | Basis |
|---|---|---|
| Microsoft 365 Copilot Business | €15.60–18.20 per user a month, excluding VAT | Microsoft France price page, November 2026 |
| Microsoft Copilot Studio capacity pack | €173.30 a month for 25,000 credits | GeoToolbox reseller guide, 2026 |
| Mistral Medium 3 API | USD 0.40 input, USD 2.00 output per million tokens | CloudZero price guide, September 2026 |
| Mistral Le Chat Team | USD 24.99 per user a month, excluding taxes | Mistral lists, November 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Fraud losses and group rollouts push spending up
Rising scam losses push banks toward real-time scoring
Payment fraud is the clearest cost that AI spending reduces, because scams now target the customer rather than the card. Annual payment fraud in France stayed just under €1.2 billion in 2024, and manipulation fraud made up 32% of it, according to the Banque de France payment security observatory’s 2024 report. Fraud rose 7% to €618 million in the first half of 2025, while manipulation fraud jumped 37% to €245 million, according to the observatory’s January 2026 release. French banks also introduced payee verification in October 2025 and planned a shared file of risky IBANs for May 2026, the same release says. Each new control needs scoring models that act in seconds, which favors suppliers of behavioral analytics and real-time transaction monitoring.
Group-wide assistant rollouts lift license and model spend
Every employee seat and prompt now adds to a recurring bill, because French groups have moved assistants from pilots to whole workforces. More than half of BPCE’s 100,000 employees used AI daily by November 2025, and its MAiA assistant handled more than 2 million prompts a month, according to Groupe BPCE. About 45,000 BPCE staff had been trained, and its voicebots had handled one million calls. Crédit Agricole set aside nearly €500 million for AI over 2026–2028, including €150 million to capitalize its new AI subsidiary. These budgets make model access, hosting and integration the core of demand and favor suppliers that can serve tens of thousands of users securely.
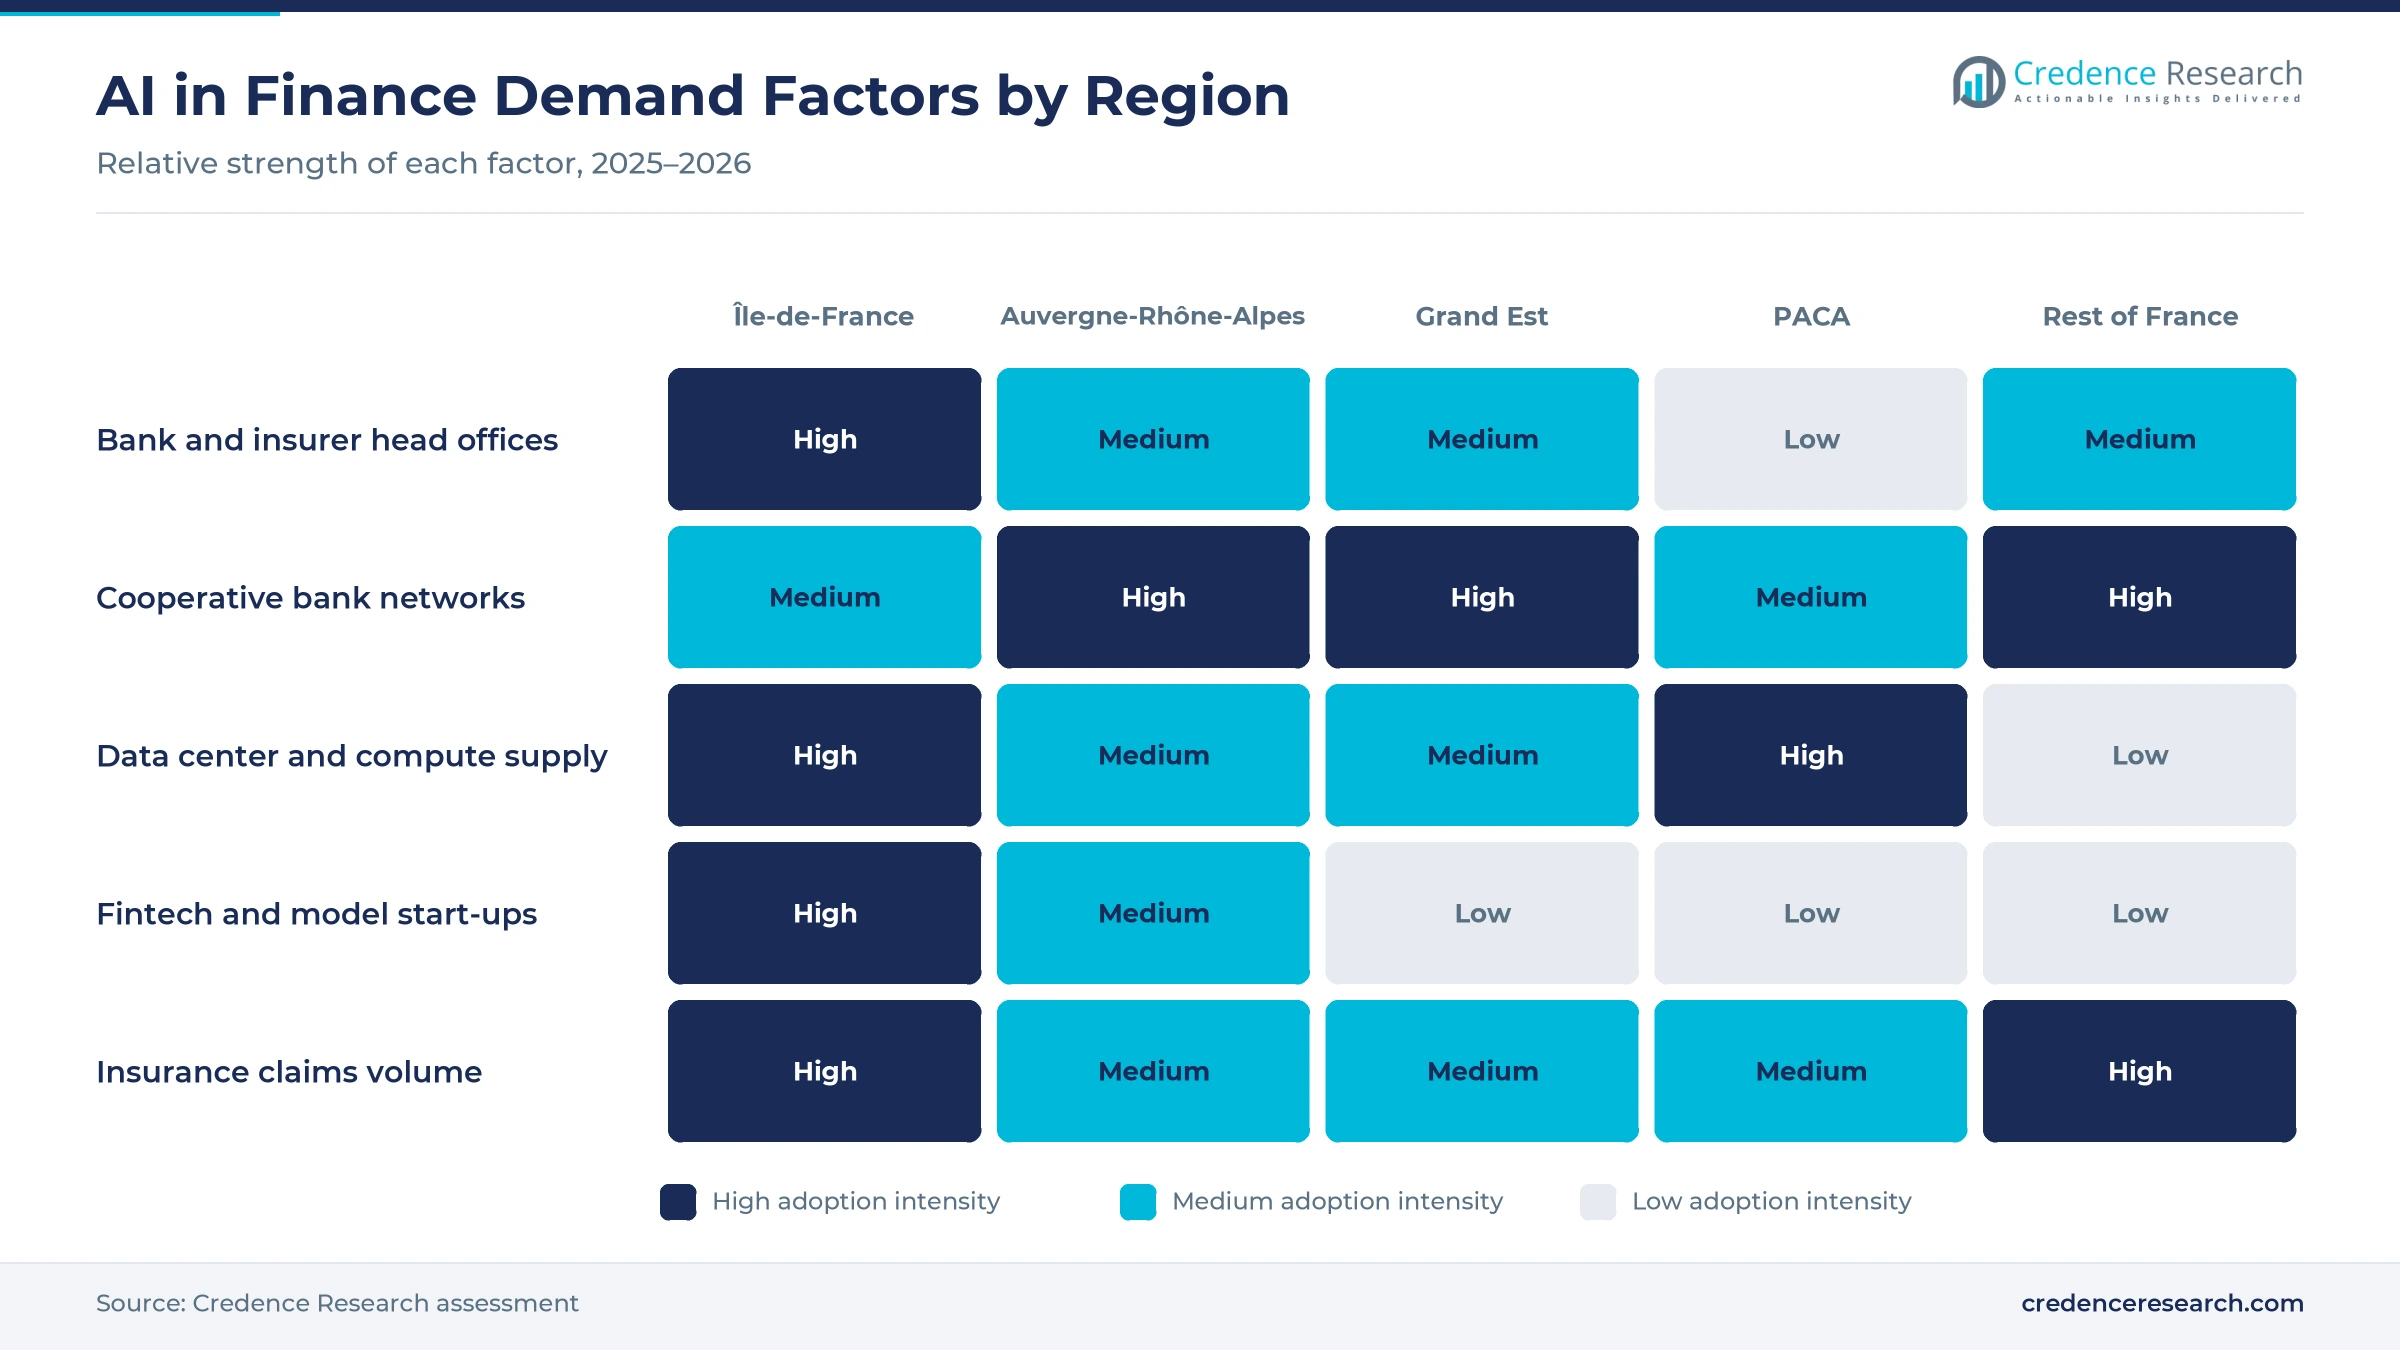
Capital markets firms move AI into production
Asset managers, brokers and market infrastructures are moving from trials to production, which widens demand beyond retail banking. Among the 69 supervised financial entities that answered, 90% already use AI and 54% have use cases in production, with a further 36% in development or testing, according to the Autorité des marchés financiers in February 2026. Generative AI accounted for 52% of the 106 detailed use cases, led by drafting, summaries and internal co-pilots. The ACPR reported in 2025 that nearly all banks and insurers had AI use cases in production. Demand from portfolio managers favors suppliers of research summaries, compliance checks and code tools rather than client-facing robo-advice.
Domestic models and compute shorten security reviews
Security reviews move faster when regulated data can stay on French soil with a European model owner. Mistral AI raised €1.7 billion in a Series C led by ASML on Sept. 9, 2025, at an €11.7 billion valuation, according to the company. The Élysée said in February 2025 that more than €109 billion of AI infrastructure investment had been announced for France. Microsoft pledged €4 billion in May 2024 to expand its Paris and Marseille data center sites and build a new campus near Mulhouse in Grand Est, according to Solutions Numériques. Banks that want French hosting and European models now have real options, which favors suppliers able to host models inside France.
Multi-model contracts and agents reshape buying
Banks shift from in-house chatbots to model contracts
Large banking groups are shifting toward multi-year contracts with model owners to keep pace with releases, creating openings for large language models sold as managed services. Société Générale decommissioned its SoGPT assistant at the end of 2025 and began moving staff to Microsoft Copilot in January 2026, according to Le Monde Informatique. BNP Paribas renewed its Mistral AI partnership for three years on May 26, 2026, widening it to software and co-development within a multi-model approach. BPCE’s MAiA assistant draws on models from Mistral AI, OpenAI, Google and Anthropic. Suppliers win by fitting into a bank’s routing layer, not by owning the whole stack.
Agents move into credit and corporate banking work
Corporate and investment banks are shifting from question-answering tools toward agents that complete defined tasks, creating openings for agent platforms across credit, research and operations. BNP Paribas signed a five-year deal with Google Cloud in September 2026 to deploy agents that prepare corporate credit memos, according to BNP Paribas. Gemini models will also run inside LLM@CIB, and Gemini already supports 200 customer advisers at Nickel through Nickel Assist. Crédit Agricole’s October 2026 partnership with Mistral AI also covers agentic redesign of key processes and a conversational agent for retail clients. Each agent needs authentication, logging and access limits, which favors vendors with strong controls.
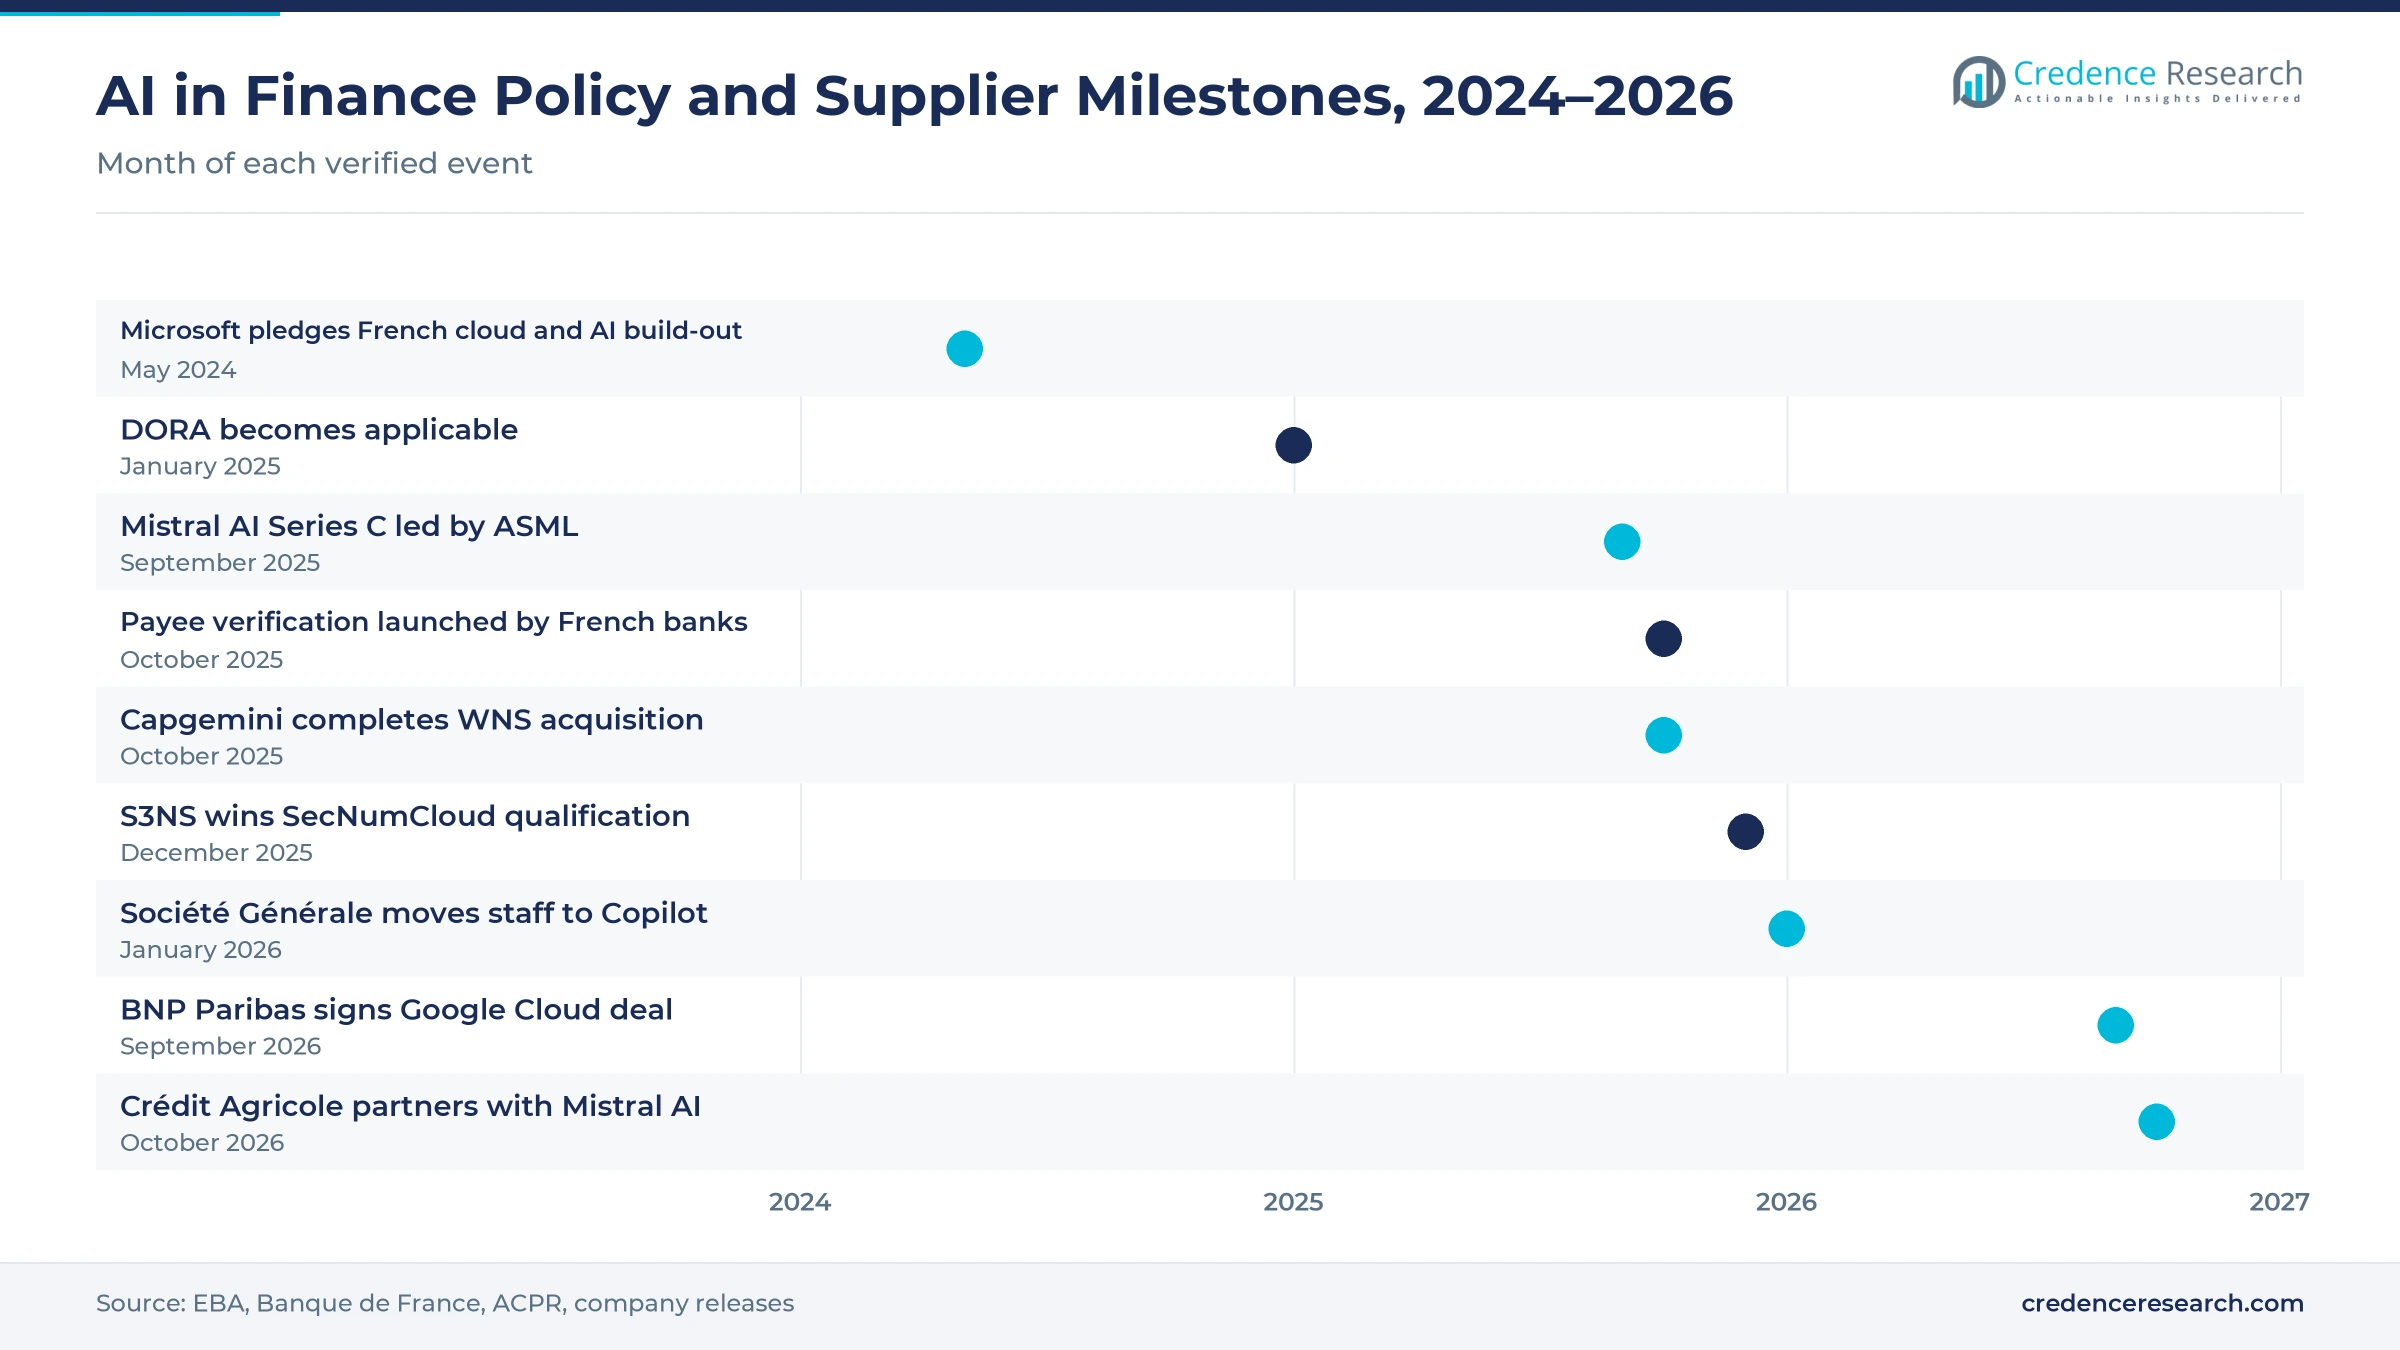
Trusted cloud qualification opens regulated workloads
Mid-size banks, fintechs and insurers that cannot run private AI clusters gain an opening as trusted cloud offers win French security qualification. S3NS, the Thales and Google venture, received SecNumCloud 3.2 qualification for PREMI3NS in December 2025, with Qonto among the financial customers migrating, according to Business Wire. Bleu, the trusted cloud built by Capgemini and Orange on Microsoft technology, passed its J1 audit milestone in November 2025 and is targeting qualification of about 100 services for the end of 2026, according to Next. BNP Paribas, which offers LLM@CIB to more than 65,000 employees, states that certain categories of data will not be stored in a public cloud. Qualified hosting lets these buyers use hosted models for KYC and claims files without building data centers.
Insurance claims and health fraud offer a large niche
Property and health insurers offer an opening for claims analytics, because fraud losses are large and claims files are document-heavy. Property and casualty fraud costs about €2.5 billion a year in France, according to Shift Technology, whose tools Direct Assurance, owned by AXA, extended from auto to home claims. Since May 2021, Cegedim Insurance Solutions has held exclusive rights to distribute Shift fraud tools to French health insurers using its third-party payment services. Direct Assurance has more than one million customers, and Lyon-based APRIL described a virtual assistant for partner brokers in March 2026, according to LyonMag. Vendors of insurtech platforms that combine document reading with fraud scoring can sell to mutuelles that lack data teams.
AI Act timing, DORA and build-or-buy risk
AI Act rules weigh most on lenders and insurers
Consumer lenders and life and health insurers face the heaviest compliance load, because credit scoring and insurance pricing for individuals are high-risk uses under the EU AI Act. The ACPR said in July 2026 that these obligations would apply from Dec. 2, 2027, after a delay from Aug. 2, 2026, while fraud detection is excluded. Its fairness paper, open to comment until Sept. 30, 2026, warns that removing sensitive variables is not enough. Lenders must document data, bias tests and explanations before new models go live.
DORA registers slow cloud model contracts
DORA raises the cost of every outside AI contract, because banks must record and monitor each ICT supplier. The regulation applies from Jan. 17, 2025, under Article 64 of the DORA text published in the Official Journal, and the European Banking Authority says banks must keep a register of all ICT third-party arrangements at entity and group level. Model and cloud contracts need exit plans, audit rights and incident reporting terms. Smaller banks and fintechs that rely on one hyperscaler face the longest reviews and the highest legal costs per contract.
Replaced in-house tools waste early budgets
Banks that built their own assistants risk writing off early spending when market products move faster. Société Générale replaced SoGPT after a little more than a year, as noted above, even though its SocGen AI unit targets €500 million a year from AI and data starting in 2026, according to Le Monde Informatique. Rapid model releases make custom interfaces obsolete within one budget cycle. Groups with large internal teams are most exposed, while vendors that sell model routing and governance layers gain from the switch.
Specialist day rates limit smaller institutions
Specialist pay limits how fast smaller banks, mutuelles and asset managers can deploy AI on their own. A senior freelance data scientist charges about €850 to €1,100 a day in Paris in 2026, with regional rates 10% to 20% lower, according to Freelance-Solution. A six-month model project can therefore cost more than a small institution’s annual analytics budget. These buyers depend on packaged software and integrators, which slows custom work and concentrates spending with large vendors.
Paris leads while Lyon and regional networks grow fastest
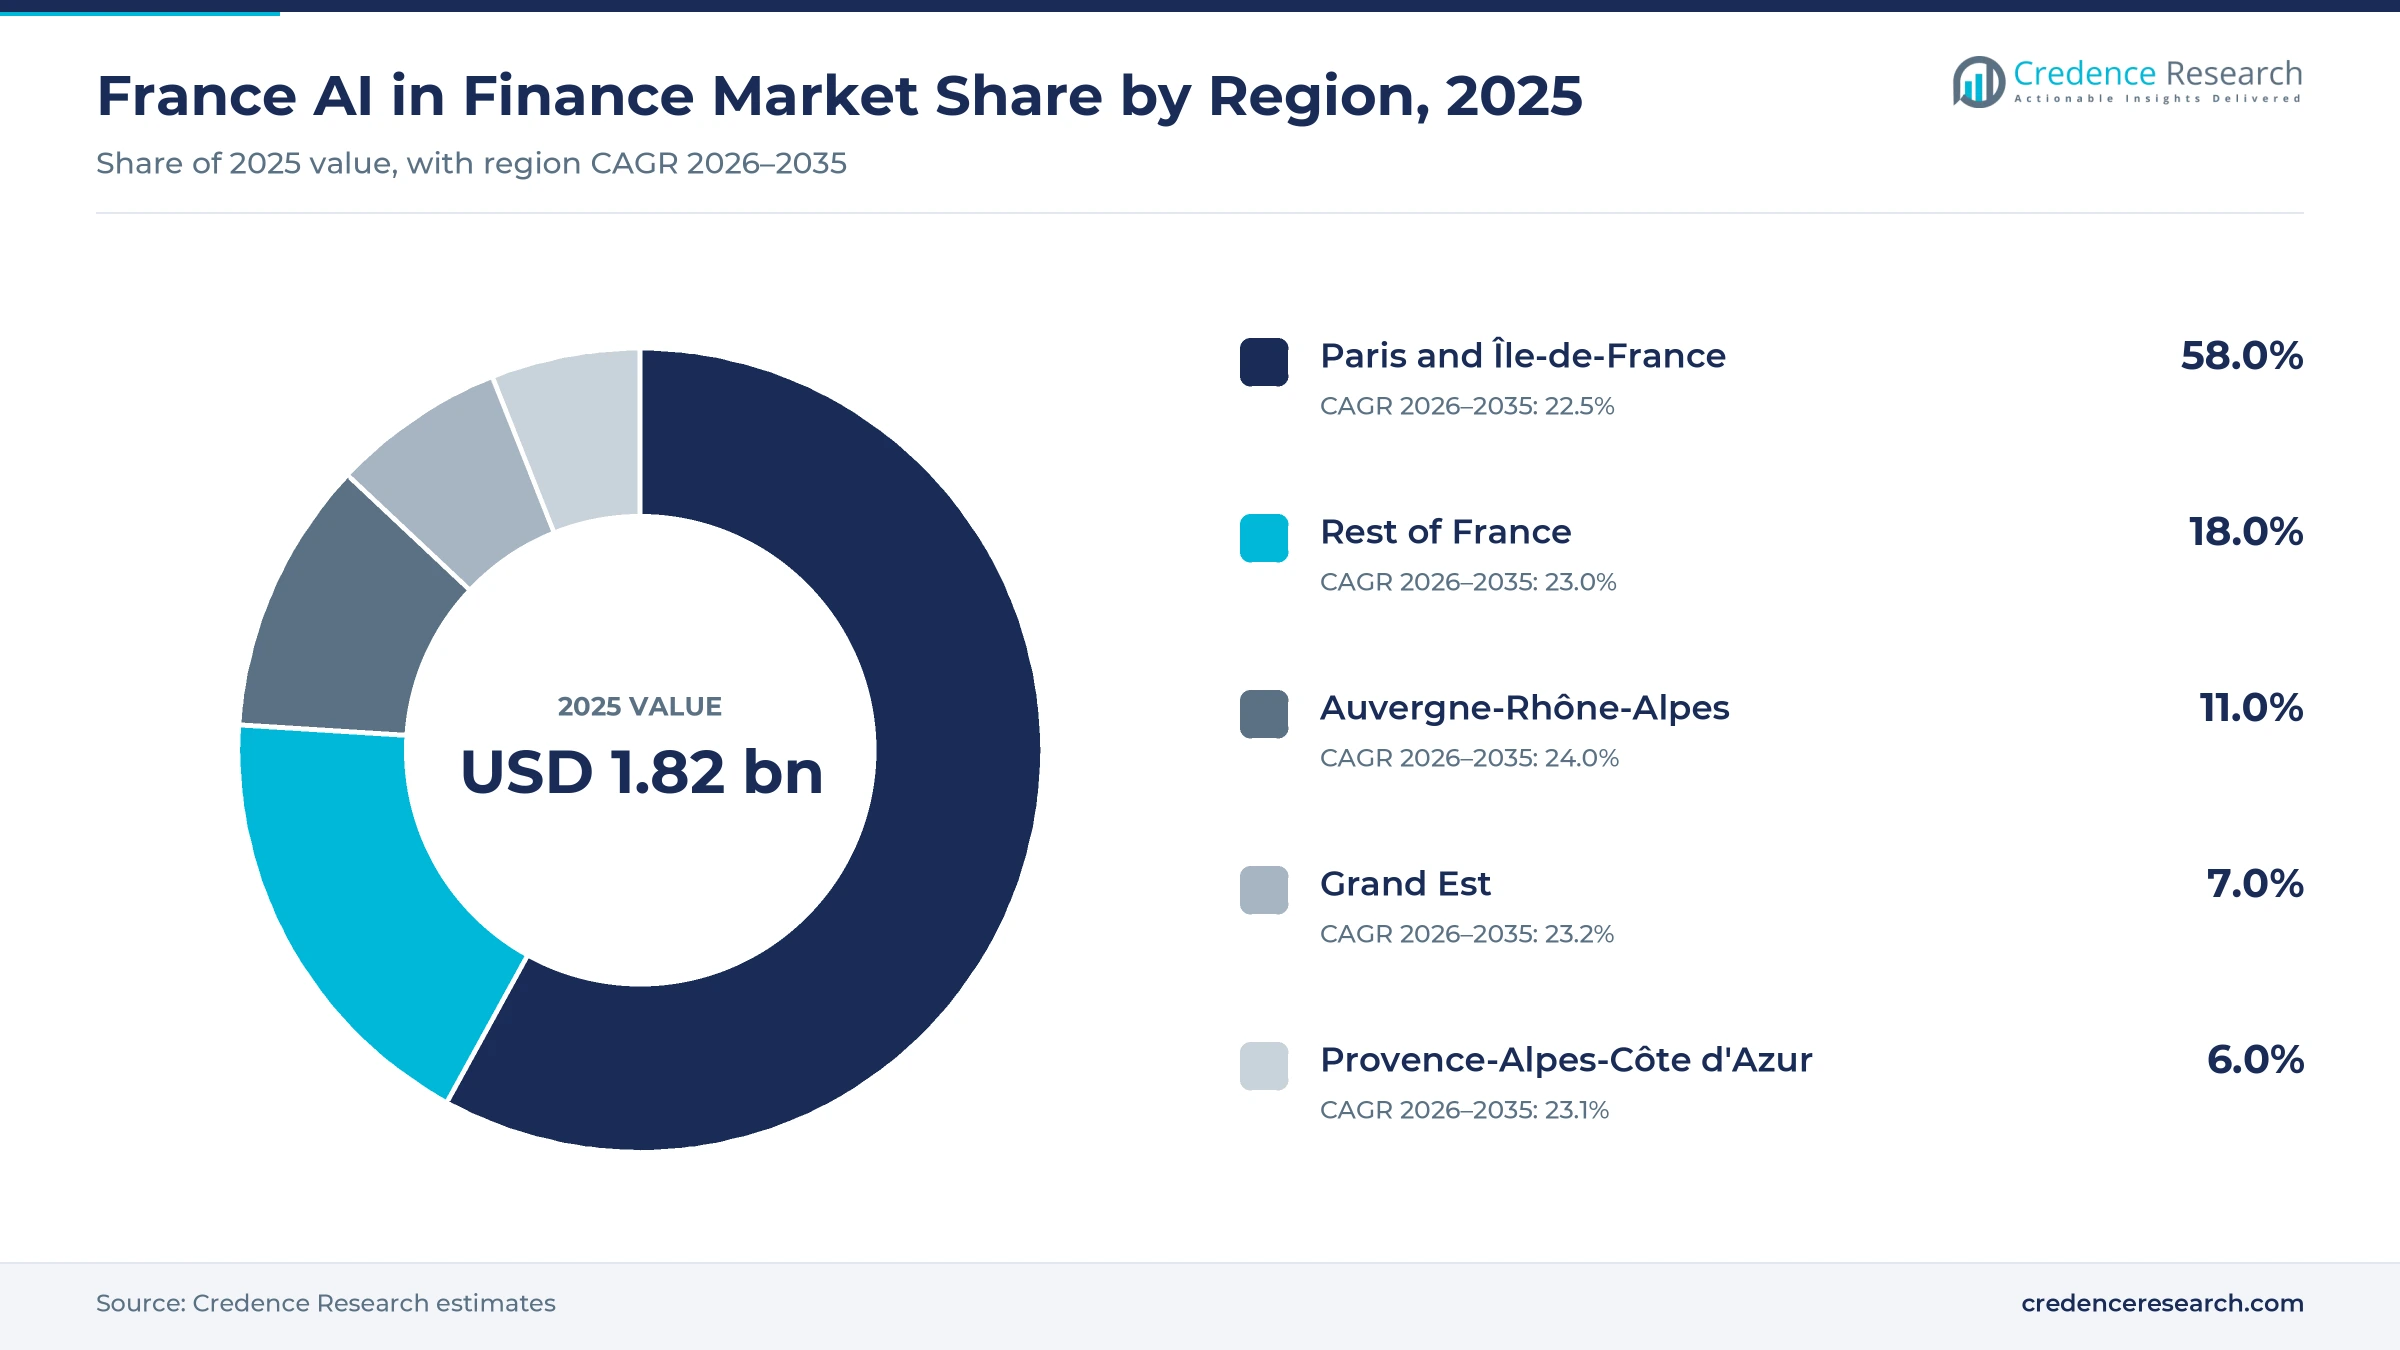
The France AI in finance market is split into Paris and Île-de-France, Auvergne-Rhône-Alpes, Grand Est, Provence-Alpes-Côte d’Azur and the rest of the country. Zone shares and growth rates are Credence Research estimates based on INSEE regional output and the location of bank, insurer and IT center sites.
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Paris and Île-de-France | 1.06 | 58.0% | 22.4% |
| Rest of France | 0.33 | 18.0% | 22.9% |
| Auvergne-Rhône-Alpes | 0.20 | 11.0% | 23.9% |
| Grand Est | 0.13 | 7.0% | 23.1% |
| Provence-Alpes-Côte d'Azur | 0.11 | 6.0% | 23.1% |
Paris head offices hold most of the spending
Paris and Île-de-France held a 58.0% share of 2025 value and grows at 22.4% a year, because group-level AI budgets, model contracts and trading-floor tools are bought at Paris head offices. The head offices of BNP Paribas, Société Générale, BPCE, Crédit Agricole S.A. and AXA buy group-wide licenses, models and cloud capacity there. Paris also hosts Mistral AI and the corporate and investment banking teams that use LLM@CIB. Growth is slightly below the national rate because the largest groups already hold broad licenses.
Lyon insurers and regional banks grow fastest
Auvergne-Rhône-Alpes held 11.0% of 2025 value and grows fastest at 23.9% a year, because it is the largest regional economy outside Paris, with €337 billion of GDP in 2023, according to INSEE. Lyon hosts insurance broker APRIL, with 3,300 employees, which is automating document reading and broker support. Regional cooperative banks are receiving group platforms such as the SAS Viya rollout noted above.
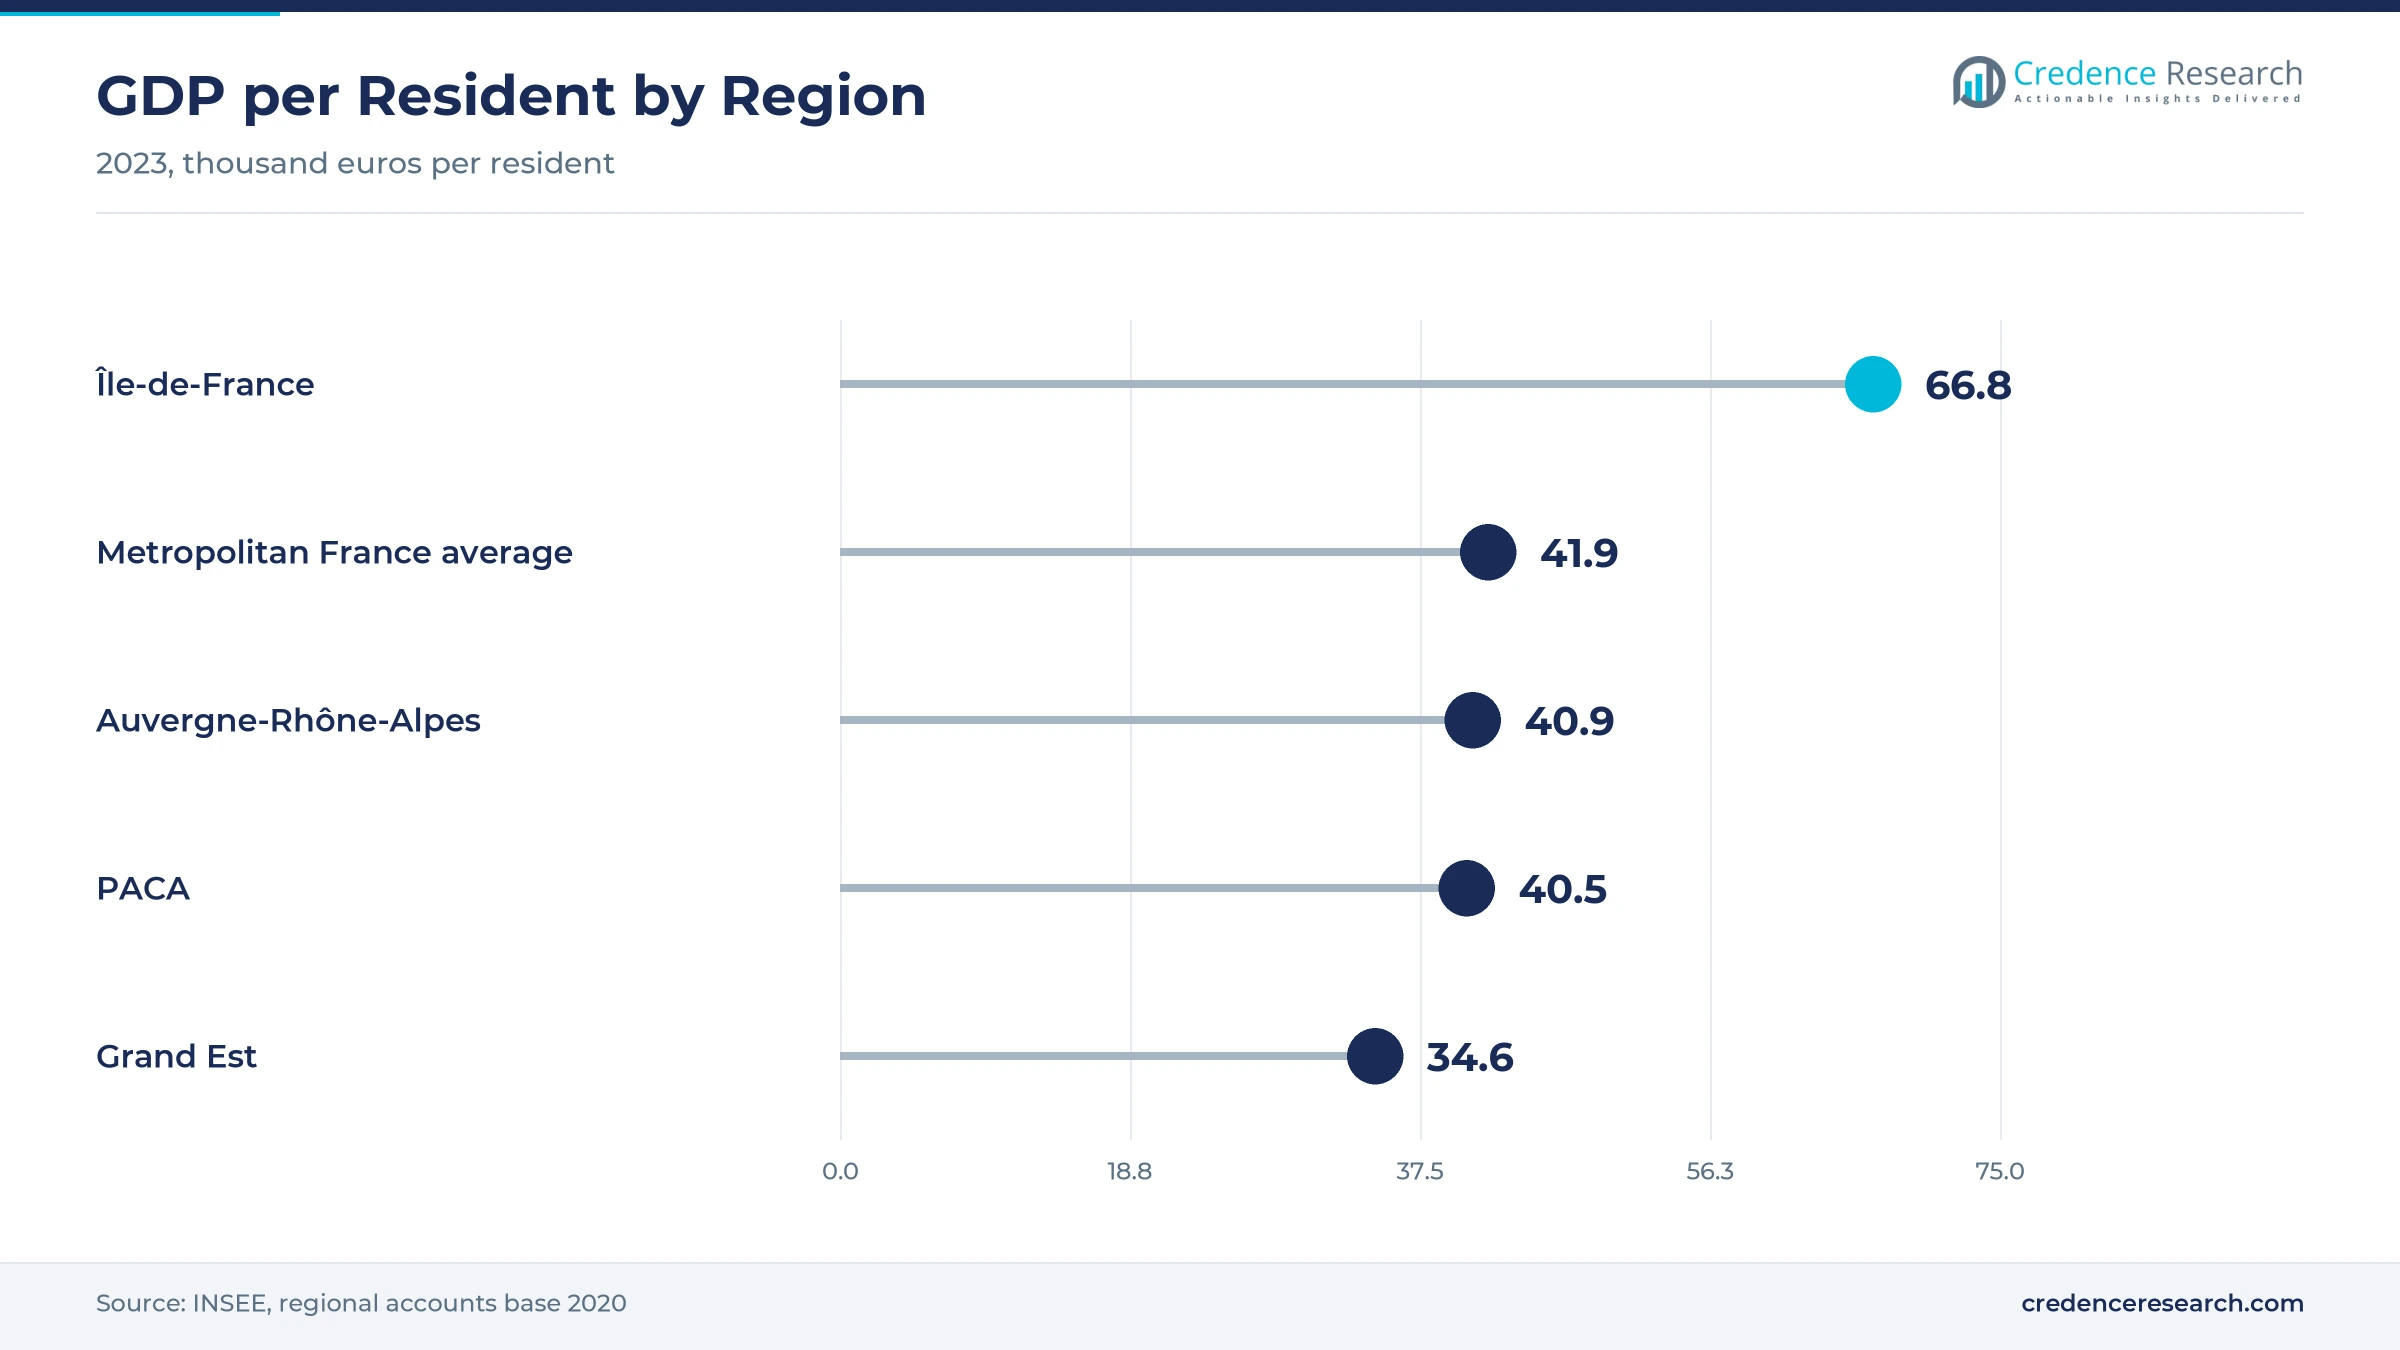
A cooperative bank IT hub anchors Grand Est
Grand Est held 7.0% of 2025 value and grows at 23.1% a year, led by Strasbourg, home of Crédit Mutuel Alliance Fédérale. The group said in June 2024 that it would deploy IBM watsonx on its in-house infrastructure, after AI saved nearly one million hours of administrative work in 2023, according to IBM. Its 25,000 advisors use AI daily, and its IT arm Euro-Information employs almost 4,000 people. The new Microsoft campus planned in the region adds hosting capacity close to these buyers.
The south-east trails on head office presence
Provence-Alpes-Côte d’Azur held 6.0% of 2025 value and grows at 23.1% a year, the smallest zone because few banking or insurance head offices sit in the south-east. Local demand comes mostly from regional bank branches and insurers whose AI tools are bought by head offices in Paris or Lyon. Microsoft’s planned expansion of its Marseille site adds data center capacity rather than local buyers. Public data on financial-sector AI spending by region are thin, so this zone estimate carries the widest range.
Regional bank networks buy through group platforms
The rest of France held 18.0% of 2025 value and grows at 22.9% a year, covering the head offices of regional cooperative banks, mutual insurers and mutuelles in the other regions. Demand arrives mostly through group platforms, such as the virtual assistant in the Banque Populaire and Caisse d’Epargne apps used by one million active digital clients. Smaller insurers buy claims and fraud tools through software partners. Local institutions rarely buy models directly, so growth follows national group budgets.
Model, cloud and integrator deals since 2025
| Development | Status and market relevance |
|---|---|
| In October 2025, Capgemini completed its acquisition of WNS for about USD 3.3 billion to build agent-based operations services. | Completed acquisition that widens Capgemini’s managed operations offer for banks and insurers |
| In December 2025, S3NS received SecNumCloud 3.2 qualification from ANSSI for its PREMI3NS trusted cloud. | Qualification granted, with financial customers such as Qonto migrating |
| In May 2026, BNP Paribas and Mistral AI renewed their partnership for three years and widened it to software and co-development. | Signed agreement, initially focused on corporate and retail banking divisions |
| In September 2026, BNP Paribas signed a five-year agreement with Google Cloud for Gemini models and agents. | Signed agreement, with first use cases in corporate and institutional banking |
| In October 2026, Crédit Agricole announced a partnership with Mistral AI to help build its group AI platform. | Announced partnership, part of a near €500 million AI budget for 2026–2028 |
Models, agents and trusted cloud change the stack
- Model routing layers send each request to an approved model according to data sensitivity and cost, so a group can use Mistral AI, Google and OpenAI models side by side.
- Task agents prepare credit memos, KYC files and call reports from internal data, which moves AI from answering questions to completing work.
- Trusted cloud hosting runs hosted models under SecNumCloud rules, which lets mid-size banks and fintechs use them without private GPU clusters.
- Transaction monitoring models extend anti-money laundering software with behavioral signals, so banks can block manipulation scams before instant transfers settle.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Model owners, platforms and integrators compete
Competition centers on who holds the group contract and the data connectors rather than on model quality alone. Mistral AI has signed group partnerships with BNP Paribas and Crédit Agricole and appears in BPCE’s model mix. Microsoft supplies Copilot to Société Générale and AXA, while Google Cloud signed a five-year agreement with BNP Paribas in 2026. IBM supplies watsonx to Crédit Mutuel Alliance Fédérale on its own infrastructure. SAS Institute and Dataiku hold risk, fraud and analytics work at Crédit Agricole and BPCE, and Shift Technology sells claims fraud tools to French insurers. Capgemini adds integration and managed operations, and Amazon Web Services and Oracle compete for cloud and banking software workloads. Suppliers that fit a multi-model approach hold the strongest positions.
Model owners, software vendors and integrators split the stack
The supply side is organized in three layers that rarely compete head-on. Model owners and hyperscalers such as Mistral AI, Microsoft, Google Cloud and Amazon Web Services sell model access, compute and assistants under group contracts. Specialist software vendors such as SAS Institute, Dataiku, IBM and Shift Technology sell risk, fraud, analytics and claims platforms that sit inside regulated processes. Integrators such as Capgemini connect these tools to core systems. Entry barriers are highest in risk and compliance software, where model validation and supervisor scrutiny apply, and margins sit with platforms that hold customer data connectors.
Global clouds and French model owners share the shortlist
| Company | Type | Role in the market |
|---|---|---|
| Microsoft Corporation | Model and cloud supplier | Copilot assistants, Azure hosting and Copilot Studio agents for banks and insurers |
| Alphabet Inc. (Google Cloud) | Model and cloud supplier | Gemini models, Gemini Enterprise agents and AI infrastructure for banks |
| Mistral AI | Model owner | Language models, assistants and deployment support for French banking groups |
| IBM Corporation | Platform supplier | watsonx AI and data platform deployed on bank infrastructure |
| Amazon Web Services (Amazon) | Cloud supplier | Hosted model access, machine learning services and cloud capacity |
| SAS Institute | Analytics software vendor | SAS Viya for risk, compliance and customer analytics in banking |
| Capgemini | Integrator | AI integration, consulting and agent-based managed operations for financial firms |
| Dataiku | Analytics platform vendor | Data science and AI platform used for risk and anti-fraud work |
| Shift Technology | Specialist software vendor | Claims fraud and financial crime detection for insurers |
| Oracle Corporation | Software and cloud supplier | Banking applications, analytics and cloud infrastructure with built-in AI |
Why vendor choice now decides AI returns
Credence Research's view is that French financial-sector AI spending will keep growing fast but will concentrate with suppliers that fit a multi-model approach. Large groups have shown they will drop an in-house tool or add a second model owner within a year when products move faster elsewhere. Fraud losses and staff assistants keep demand broad, while the AI Act and DORA add cost to credit and cloud projects. Vendors that hold data connectors, routing and governance layers should gain share by 2035, while single-model resellers face the steepest price pressure.
Bank budgets and public data anchor the estimate
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. The earlier estimate was brought forward to 2025 at its own growth rate and cross-checked with a build-up of disclosed bank AI budgets and a top-down share of global spending, and the growth rate was then reset to a level those budgets support. Segment splits and zone shares are Credence Research estimates from public data. Sources used are regulator and central bank publications, official statistics, company releases, price listings and trade press, and no interviews or surveys were used.
Assistants and agents carry growth to 2035
The France AI in finance market is expected to reach USD 14.21 billion by 2035, registering a 22.80% CAGR during 2026–2035, as assistants, agents and fraud models spread across banks, insurers and asset managers. Growth should be strongest in generative AI, virtual assistants, cloud deployment and Auvergne-Rhône-Alpes, because group platforms are now reaching regional networks and smaller institutions. AI Act obligations from December 2027, DORA contract rules and seat saturation could slow some years. Suppliers that combine French hosting with model choice should hold the strongest positions.
Seat saturation and AI Act timing set the 2035 range
The base case assumes banks and insurers keep expanding assistants and agents at the pace of current group budgets, with AI Act obligations absorbed from December 2027. The downside case follows a pause in license growth once seats saturate, tighter bank cost targets and slow approval of high-risk credit models. The upside case needs agents to replace whole back-office steps, trusted cloud capacity to open hosted models to mid-size institutions and insurers to adopt claims automation widely.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 18.8% | USD 10.55 billion | Seat licenses saturate and high-risk model approvals slow after 2027 |
| Base | 22.80% | USD 14.21 billion | Group budgets grow as announced and AI Act rules are absorbed on schedule |
| Upside | 25.8% | USD 17.66 billion | Agents replace back-office steps and trusted cloud opens hosted models widely |
Frequently Asked Questions
How big is the France AI in finance market?
How fast is generative AI growing in French banking and fintech?
Which region leads AI spending in French finance?
Why is fraud detection the largest application?
Which AI models do French banks use?
When do AI Act rules for credit scoring apply in France?
How much do AI assistants cost French financial firms?
How does financial analytics fit into this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Solution
- 1.2.2 Services
- 1.3 By Deployment Mode
- 1.3.1 On-Premise
- 1.3.2 Cloud
- 1.4 By Technology
- 1.4.1 Other AI Technologies
- 1.4.2 Generative AI
- 1.5 By Application
- 1.5.1 Fraud Detection
- 1.5.2 Business Analytics and Reporting
- 1.5.3 Virtual Assistant (Chatbots)
- 1.5.4 Quantitative and Asset Management
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.82 billion → 2035: USD 14.21 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 France AI in Finance Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 France AI in Finance Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 France AI in Finance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 France AI in Finance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 France AI in Finance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 France AI in Finance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 France AI in Finance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 France AI in Finance Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.82 billion → 2035: USD 14.21 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 France AI in Finance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solution
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment Mode - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 On-Premise
- 12.4.7.2 Cloud
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Other AI Technologies
- 12.5.7.2 Generative AI
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Fraud Detection
- 12.6.7.2 Business Analytics and Reporting
- 12.6.7.3 Virtual Assistant (Chatbots)
- 12.6.7.4 Quantitative and Asset Management
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 France AI in Finance End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 France AI in Finance Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 France AI in Finance Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 France AI in Finance Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Microsoft Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Alphabet Inc. (Google Cloud)
- 18.4 Mistral AI
- 18.5 IBM Corporation
- 18.6 Amazon Web Services (Amazon)
- 18.7 SAS Institute
- 18.8 Capgemini
- 18.9 Dataiku
- 18.10 Shift Technology
- 18.11 Oracle Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

