
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| France Industry Vertical Modernization Services Market Size 2023 | USD 68.35 Million |
| France Industry Vertical Modernization Services Market, CAGR | 14.36% |
| France Industry Vertical Modernization Services Market Size 2032 | USD 199.93 Million |
Market Overview
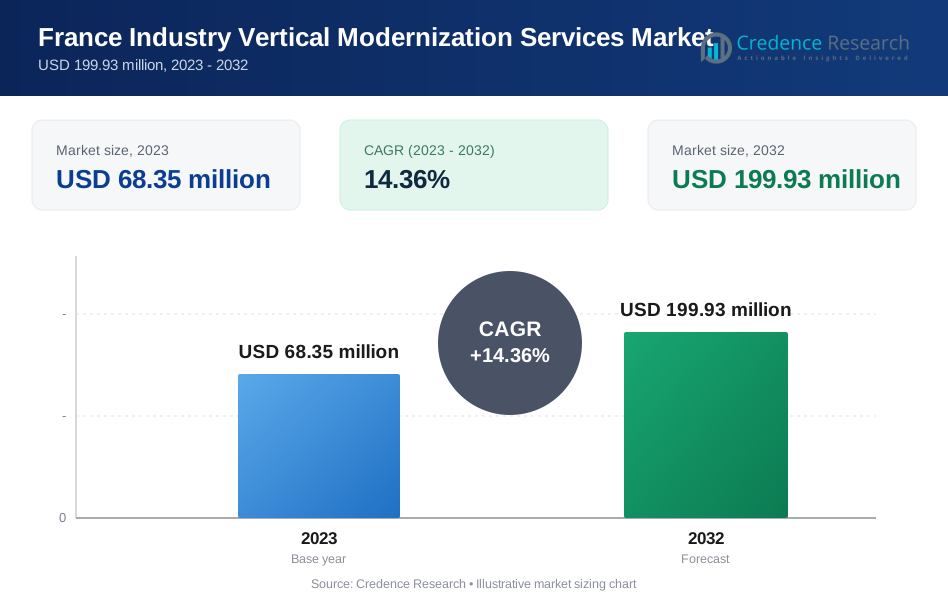
The France Industry Vertical Modernization Services Market is projected to grow from USD 68.35 million in 2023 to USD 199.93 million by 2032, at a compound annual growth rate (CAGR) of 14.36%.
The France Industry Vertical Modernization Services market is driven by the increasing need for digital transformation across various sectors, including manufacturing, healthcare, and retail. The growing demand for automation, cloud computing, and data-driven decision-making solutions is fueling the market’s expansion. Companies are increasingly adopting modernization services to enhance operational efficiency, reduce costs, and stay competitive in the digital era. Additionally, the rise of Industry 4.0 and the Internet of Things (IoT) is driving innovation, enabling businesses to integrate advanced technologies and improve productivity. Moreover, the ongoing shift towards sustainable and energy-efficient solutions is fostering the adoption of modernized systems. As businesses face pressure to remain agile and responsive to market demands, the trend of digital modernization is expected to continue gaining momentum, propelling the market toward substantial growth in the coming years.
The geographical analysis of France’s industry vertical modernization services reveals significant activity across key regions, with Northern and Southern France leading in terms of technological adoption and investments in modernization initiatives. Northern France benefits from a robust industrial base, particularly in IT, BFSI, and telecom sectors, while Southern France is a hub for aerospace, automotive, and energy industries. Eastern and Western France focus on manufacturing and agriculture, respectively, driving demand for automation and digital solutions. Key players in the market include global technology firms such as Capgemini, Atos SE, SAP SE, Siemens AG, Accenture, and TCS, which are instrumental in providing modernization services across various sectors. These companies offer a wide range of solutions, including cloud migration, AI integration, and digital transformation, supporting businesses in improving efficiency, sustainability, and competitiveness. Their strategic investments in R&D and partnerships with local enterprises further strengthen their market presence.
Market Insights
- The France Industry Vertical Modernization Services market is projected to grow from USD 68.35 million in 2023 to USD 199.93 million by 2032, at a CAGR of 14.36%.
- Increasing adoption of cloud computing, automation, and AI technologies is driving market growth.
- Businesses are shifting towards digital transformation to improve efficiency and competitiveness, leading to a rise in demand for modernization services.
- Market competition is intensifying, with multiple global players offering innovative solutions to meet diverse industry needs.
- High implementation costs and a shortage of skilled talent remain key challenges for businesses looking to modernize.
- Northern and Southern France lead in the adoption of modernization services, with strong growth in IT, aerospace, and manufacturing sectors.
- The government's focus on sustainability and digitalization further accelerates market growth, creating opportunities for service providers.
Market Drivers
Advancements in Automation and Artificial Intelligence
The rise of automation and artificial intelligence (AI) in industrial applications is reshaping how companies operate in France. For instance, the National Strategy for AI in France aims to integrate AI technologies across various sectors, enhancing automation and decision-making processes. Automation is driving efficiencies across manufacturing, logistics, and supply chain sectors, enabling firms to reduce human error, lower costs, and increase productivity. AI technologies are being integrated into modernization services to improve decision-making processes, optimize operations, and predict trends. As more organizations adopt AI-driven automation, the demand for industry vertical modernization services is expected to grow significantly.
Growing Demand for Digital Transformation
The increasing push for digital transformation across industries in France is a significant driver of the Industry Vertical Modernization Services market. Companies are leveraging modernization services to adopt cutting-edge technologies such as cloud computing, AI, and big data analytics. This shift is not only enhancing operational efficiency but also enabling businesses to offer personalized services to customers. The need to adapt to rapidly evolving technological trends and maintain a competitive edge is pushing French companies to modernize their infrastructure, systems, and workflows, further expanding the demand for these services.
Focus on Operational Efficiency and Cost Reduction
France’s businesses are under constant pressure to improve operational efficiency and reduce costs, which has spurred the adoption of modernization services. By upgrading outdated systems and workflows, companies can streamline their operations, optimize resource utilization, and reduce redundancies. These services enable organizations to eliminate inefficiencies, enhance productivity, and maximize returns on investment. The focus on cost reduction through improved systems and processes continues to drive the market's growth in various sectors, including healthcare, manufacturing, and retail.
Increasing Adoption of Industry 4.0 and IoT
The advent of Industry 4.0 and the Internet of Things (IoT) is significantly contributing to the expansion of the France Industry Vertical Modernization Services market. For instance, a report by IoT Analytics highlighted that 72% of manufacturers in France have an Industry 4.0 strategy in place. IoT enables the seamless integration of physical devices and machines with digital systems, leading to real-time data collection and analysis. This interconnectedness enhances the efficiency and functionality of industrial processes. As French businesses continue to embrace Industry 4.0 solutions, modernization services play a key role in facilitating the adoption of IoT technologies, thus fostering further market growth.
Market Trends
Rising Adoption of Cloud Technologies
The demand for cloud-based solutions is driving the modernization of industrial sectors in France. Companies are increasingly shifting from traditional infrastructure to cloud platforms to enhance operational efficiency, scalability, and data accessibility. Cloud computing supports advanced data analytics, artificial intelligence (AI), and Internet of Things (IoT) solutions, which are transforming how industries operate. For example, the manufacturing sector is leveraging cloud technology for predictive maintenance and process automation. This trend aligns with France’s broader digital transformation strategies, encouraging industries to adopt innovative technologies to remain competitive in the global market.
Increased Focus on Sustainability and Green Technologies
Modernization efforts in French industries are increasingly driven by sustainability goals and the adoption of green technologies. For instance, France is ranked the fourth greenest country in the world according to the MIT Technology Review's Green Future Index. The government’s push toward carbon neutrality and energy efficiency is encouraging industries to invest in eco-friendly solutions. Automation and smart energy management systems are being integrated into manufacturing processes to reduce waste and energy consumption. Sectors such as automotive and construction are incorporating sustainable practices by modernizing production lines and materials. This trend reflects the growing emphasis on environmental responsibility as a key driver of industrial modernization.
Rising Investments in Cybersecurity Solutions
With digitalization comes increased exposure to cybersecurity threats, prompting industries in France to prioritize robust security measures as part of modernization strategies. For instance, the French government has implemented several programs to address cybersecurity concerns, leading to a dynamic cybersecurity industry. Companies are investing in advanced cybersecurity solutions to protect sensitive data and maintain regulatory compliance. Industrial sectors are implementing network security, endpoint protection, and real-time threat monitoring to mitigate risks. This trend is particularly prominent in sectors like finance, healthcare, and critical infrastructure, where data security is paramount. The rising adoption of Industrial Internet of Things (IIoT) devices further highlights the need for enhanced cybersecurity protocols.
Expansion of Automation and Smart Manufacturing
The modernization of France’s industrial landscape is marked by significant investments in automation and smart manufacturing technologies. Robotics, AI-driven systems, and digital twins are transforming traditional manufacturing processes, increasing productivity and reducing operational costs. The automotive and aerospace industries are leading the way in adopting automation for precision and efficiency. Furthermore, the development of smart factories, where machines communicate and optimize processes autonomously, is becoming a key competitive advantage. This trend supports France’s Industry 4.0 initiatives aimed at boosting innovation and industrial growth.
Market Challenges Analysis
High Implementation Costs and Limited Budgetary Flexibility
One of the significant challenges facing industry vertical modernization services in France is the high cost of implementing advanced technologies. Modernizing legacy systems and integrating new digital tools require substantial investments in infrastructure, software, and skilled labor. Many small and medium-sized enterprises (SMEs), which form a large portion of the industrial landscape, struggle with budget constraints that limit their ability to adopt cutting-edge solutions. Additionally, the cost of maintaining and updating these technologies adds to the financial burden, making it difficult for companies to achieve a balance between innovation and profitability. Government subsidies and financial incentives are available, but navigating complex regulatory frameworks can further complicate access to these resources, delaying modernization efforts.
Talent Shortages and Cybersecurity Risks
The shortage of skilled professionals poses another challenge to modernization across industry verticals in France. For instance, the Cedefop Labour and Skills Shortage Index highlights that ICT professionals are among the high shortage occupations in France, with 68% of companies indicating difficulties finding suitable candidates. The demand for expertise in artificial intelligence, data analytics, cloud computing, and cybersecurity far exceeds the current supply of qualified workers. This talent gap slows the implementation of new technologies and hinders the ability of companies to fully leverage modernization benefits. Additionally, as industries become increasingly connected, the risk of cybersecurity breaches rises. Many organizations lack the robust security frameworks necessary to protect sensitive information and critical systems from sophisticated threats. This vulnerability can lead to financial losses, regulatory penalties, and reputational damage, making cybersecurity a critical, yet challenging, aspect of modernization. Addressing these issues requires substantial investment in workforce development and advanced security solutions, adding further complexity to modernization initiatives.
Market Opportunities
Growing Demand for Digital Transformation Solutions
The increasing adoption of digital transformation strategies presents substantial growth opportunities for industry vertical modernization services in France. Companies across sectors such as manufacturing, healthcare, automotive, and retail are investing in smart technologies to improve efficiency, reduce costs, and enhance customer experiences. The rising use of automation, artificial intelligence (AI), and Industrial Internet of Things (IIoT) solutions creates a strong market for service providers specializing in system upgrades, process optimization, and integration of advanced digital tools. Additionally, the government’s Industry of the Future initiative, aimed at fostering innovation and modernization, provides a favorable environment for businesses offering tailored digital solutions. This initiative encourages companies to embrace modernization, boosting the demand for consulting, implementation, and managed services.
Expansion of Cloud-Based and Cybersecurity Services
The rapid transition to cloud-based infrastructures presents lucrative opportunities for modernization service providers focusing on cloud integration and management. Businesses are increasingly migrating to hybrid and multi-cloud environments to enhance operational flexibility and scalability. This shift creates a need for expertise in cloud architecture design, data migration, and performance optimization. Furthermore, the heightened emphasis on cybersecurity offers significant potential for growth. With industries facing rising cyber threats, demand for specialized services in network security, endpoint protection, and compliance management is expected to increase. Companies offering comprehensive modernization services with a strong cybersecurity focus can position themselves as strategic partners, capturing a larger share of this expanding market. These opportunities highlight the transformative potential of modernization services in shaping the future of France's industrial landscape.
Market Segmentation Analysis:
By Type:
The France industry vertical modernization services market is segmented into Industry Vertical Portfolio Assessment, Cloud Industry Vertical Migration, Industry Vertical Replatforming, Industry Vertical Integration, and Industry Vertical Retirements. Among these, Cloud Industry Vertical Migration holds a dominant position as organizations increasingly migrate legacy systems to cloud platforms to enhance scalability and operational efficiency. Industry Vertical Integration also exhibits significant growth potential, driven by the rising demand for seamless data flow and process optimization across interconnected systems. Additionally, Industry Vertical Portfolio Assessment plays a crucial role in identifying modernization needs, allowing businesses to prioritize investments strategically. The growing complexity of IT environments is further accelerating demand for modernization services to ensure streamlined operations and competitive agility.
By Industry Vertical:
Based on industry vertical, the market is categorized into BFSI, IT and Telecom, Retail and E-commerce, Healthcare, and Others. The BFSI sector leads the adoption of modernization services, focusing on digital transformation to improve customer engagement and regulatory compliance. The IT and Telecom industry is experiencing robust demand due to the need for enhanced network infrastructure and cloud integration. Retail and E-commerce sectors are embracing modernization to deliver personalized customer experiences and optimize supply chains. The healthcare sector is increasingly adopting modernization services to enhance data management, telehealth capabilities, and patient care solutions. Other industries, including manufacturing and logistics, are also driving growth as they implement advanced technologies to remain competitive.
Segments:
Based on Type:
- Industry Vertical Portfolio Assessment
- Cloud Industry Vertical Migration
- Industry Vertical Replatforming
- Industry Vertical Integration
- Industry Vertical Retirements
Based on Industry Vertical:
- BFSI
- IT and Telecom
- Retail and E-commerce
- Healthcare
- Others
Based on Deployment Mode:
- On-Premises
- Cloud
Based on Enterprise Size:
- Small and Medium Enterprises (SMEs)
- Large Enterprises
Based on the Geography:
- Northern France
- Southern France
- Eastern France
- Western France
Regional Analysis
Northern France
Northern France holds a significant share of 32% in the industry vertical modernization services market, largely due to its strong industrial base and strategic position within Europe. This region benefits from its proximity to major cities like Paris, Lille, and Rouen, which are home to key industries such as BFSI, IT, and telecom, driving the demand for modernization services. The region’s focus on digital transformation and cloud migration is evident as businesses across these sectors invest heavily in upgrading legacy systems to enhance operational efficiency. Additionally, Northern France's strong industrial and manufacturing sectors are increasingly embracing automation, AI, and IoT technologies, further boosting the demand for modernization services. The continued investment in digital infrastructure by both public and private entities in Northern France ensures that the region will maintain its leading position in the modernization services market.
Southern France
Southern France accounts for approximately 28% of the market share, with its emphasis on high-tech industries such as aerospace, automotive, and energy. Major cities like Toulouse and Nice are hubs for innovation, attracting significant investments in digital technologies and industrial modernization. Southern France's robust aerospace and automotive sectors are increasingly adopting automation, IoT, and AI-driven solutions to enhance production processes and optimize supply chains. The region's investment in renewable energy and smart grids is also contributing to the growth of modernization services, as industries seek advanced digital tools to improve sustainability and operational efficiency. With increasing government incentives and strategic initiatives focused on technological advancements, Southern France is expected to maintain strong growth in industry vertical modernization services.
Eastern France
Eastern France holds a 20% market share in the industry vertical modernization services sector, driven primarily by the region’s manufacturing and industrial base. Cities like Strasbourg and Mulhouse are key centers for sectors including automotive, chemicals, and heavy industry. These industries are actively pursuing digital transformation initiatives to enhance productivity, reduce operational costs, and meet evolving consumer demands. The automotive sector, in particular, is investing heavily in Industry 4.0 technologies, such as connected machinery, robotics, and AI, to remain competitive. Additionally, Eastern France benefits from its proximity to neighboring countries, which facilitates cross-border collaborations and the integration of advanced technological solutions. As more businesses in this region shift to digital-first strategies, the demand for modernization services is expected to grow steadily.
Western France
Western France, contributing 20% to the market share, is focusing on industries such as agriculture, manufacturing, and maritime. Cities like Nantes and Rennes play a pivotal role in driving the modernization of agriculture through the adoption of smart farming technologies, automation, and data analytics. Additionally, the maritime industry in Western France is leveraging digital tools to improve operational efficiencies and reduce environmental impacts. The region's commitment to sustainability and green technologies is further driving modernization initiatives, with sectors like renewable energy and green manufacturing receiving significant attention. As Western France continues to embrace digital transformation, the demand for industry vertical modernization services will grow in tandem, with local enterprises increasingly adopting cloud, AI, and automation solutions to meet both regional and global market demands.
Key Player Analysis
- Capgemini
- Atos SE
- SAP SE
- Siemens AG
- Accenture
- TCS (Tata Consultancy Services)
- Cognizant
- IBM Corporation
- Infosys
- Wipro
Competitive Analysis
The competitive landscape of France's industry vertical modernization services market is dominated by several leading players, including Capgemini, Atos SE, SAP SE, Siemens AG, Accenture, TCS (Tata Consultancy Services), Cognizant, IBM Corporation, Infosys, and Wipro. These companies are at the forefront of delivering digital transformation solutions, encompassing cloud migration, automation, AI, and IoT integration. Leading companies are capitalizing on the growing demand for digital transformation services by offering comprehensive solutions in cloud migration, automation, AI, IoT, and data analytics. These firms differentiate themselves through their ability to provide end-to-end modernization, spanning everything from legacy system upgrades to seamless integration of new technologies across industries like BFSI, automotive, and manufacturing. A key competitive strategy is the emphasis on innovation and technological expertise, with many companies investing heavily in research and development to stay ahead of emerging trends such as Industry 4.0 and smart manufacturing. For instance, the Ministry of Industry's study identified 598 manufacturing firms that adopted industrial robots between 2010 and 2015, highlighting the focus on automation. Additionally, the ability to provide tailored, sector-specific solutions is vital for gaining a competitive edge. Partnerships and acquisitions are common tactics, enabling firms to expand their service offerings and strengthen their market positions. As the demand for industry vertical modernization services grows, firms are also focusing on improving their customer experience, offering enhanced support and post-implementation services. The competitive pressure is fostering rapid advancements in service offerings, ensuring that clients benefit from the latest technologies and remain competitive in an increasingly digital world.
Recent Developments
- In August 2024, Capgemini signed an agreement to acquire Syniti, one of the leading companies in the enterprise data management software and services including platform and migration services. This acquisition will strengthen Capgemini’s data-driven solutions, especially for large-scale SAP transformations like the shift to SAP S/4HANA.
- In June 2024, Cognizant expanded its partnership with Cengage Group. This move highlights the trend of modernizing educational platforms by integrating advanced technologies to enhance digital learning experiences, reflecting the broader push towards modernizing application infrastructures across sectors.
- In January 2024, IBM Corporation acquired application modernization capabilities from Advanced, increasing IBM Consulting's offerings in mainframe application and data modernization services. The acquisition is intended to enhance IBM's ability to provide a comprehensive range of options for modernizing mainframe applications, aligning with the abilities of IBM Watsonx Code Assistant for Z, a generative AI-assisted tool designed to expedite mainframe application modernization.
- In January 2024, Accenture acquired Work & Co, enhancing its capabilities in creating innovative digital products. This acquisition reflects the increasing importance of blending design and technology to modernize applications, helping clients improve user experiences and stay competitive in the digital age.
Market Concentration & Characteristics
The France Industry Vertical Modernization Services market presents substantial growth opportunities, primarily driven by the increasing demand for digital transformation across various sectors. Industries such as BFSI, healthcare, automotive, and manufacturing are accelerating their efforts to modernize legacy systems, adopt cloud technologies, and integrate AI-driven solutions to enhance efficiency, reduce costs, and stay competitive. The government's continued focus on innovation, particularly through initiatives like the "Industry of the Future" program, fosters an environment conducive to technological advancement. This opens opportunities for service providers to deliver tailored modernization solutions that align with specific industry needs, such as automation in manufacturing or digital banking solutions for the BFSI sector. Additionally, as organizations increasingly migrate to cloud platforms, the demand for cloud-based modernization services is expected to grow, creating a lucrative market for service providers specializing in cloud migration, integration, and management. Another key opportunity lies in addressing the cybersecurity needs of businesses undergoing modernization. As industries embrace digital solutions, the threat landscape expands, creating a need for robust security frameworks to safeguard critical systems and data. Service providers that offer comprehensive modernization services with an integrated focus on cybersecurity can capture a larger share of the market. Furthermore, the growing trend of IoT adoption and the rise of smart technologies in sectors like agriculture, healthcare, and retail presents additional avenues for modernization services. As businesses increasingly rely on connected devices, there will be a heightened demand for services that facilitate seamless integration and management of IoT infrastructure, further driving the growth of the market.
Report Coverage
The research report offers an in-depth analysis based on Type, Industry Vertical, Deployment Mode, Enterprise Size and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The France Industry Vertical Modernization Services market is expected to see continued growth, driven by the ongoing shift toward digital transformation.
- Cloud migration and AI integration will remain central to modernization strategies across key industries.
- The increasing adoption of automation technologies will create new opportunities for modernization service providers.
- Government initiatives focused on digitalization and sustainability will encourage further investments in modernization services.
- Industry sectors such as BFSI, healthcare, and manufacturing will continue to lead in modernization efforts.
- As cybersecurity threats rise, there will be a growing demand for services that combine modernization with robust security measures.
- The IoT and smart technologies sector will present significant growth prospects as industries embrace connected devices and data analytics.
- Small and medium-sized enterprises (SMEs) will increasingly seek modernization services as digital adoption becomes more accessible and cost-effective.
- The demand for data-driven decision-making will drive the need for advanced analytics and modernization solutions.
- Collaboration between service providers and local enterprises will strengthen, enabling tailored solutions to meet specific regional and industry needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Automation and Artificial Intelligence
The integration of automation and AI technologies is transforming industrial operations in France, enabling companies to optimize processes, reduce human error, and increase productivity. This is driving demand for modernization services that can implement and manage these advanced solutions.
Growing Demand for Digital Transformation
French companies across sectors are prioritizing digital transformation to enhance operational efficiency, customer experience, and competitiveness. This push is fueling the need for modernization services that facilitate cloud migration, big data analytics, and the adoption of new digital tools.
Focus on Operational Efficiency and Cost Reduction
Businesses are seeking to streamline operations and reduce costs by upgrading legacy systems and workflows. Modernization services help organizations eliminate inefficiencies, optimize resource utilization, and maximize ROI, making them essential for maintaining profitability.
Increasing Adoption of Industry 4.0 and IoT
The rise of Industry 4.0 and IoT in France is driving the need for modernization services that enable seamless integration of connected devices, real-time data analytics, and smart manufacturing. This trend is particularly strong in manufacturing, automotive, and logistics sectors.
Government Initiatives for Sustainability and Digitalization
French government programs promoting sustainability, energy efficiency, and digital innovation are encouraging industries to modernize. Incentives and regulatory support are accelerating investments in modernization services, especially in sectors like energy, manufacturing, and healthcare.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the France Industry Vertical Modernization Services market?
What factors are driving the growth of the France Industry Vertical Modernization Services market?
What are the key segments within the France Industry Vertical Modernization Services market?
What are some challenges faced by the France Industry Vertical Modernization Services market?
Who are the major players in the France Industry Vertical Modernization Services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Industry Vertical Portfolio Assessment
- 1.2.2 Cloud Industry Vertical Migration
- 1.2.3 Industry Vertical Replatforming
- 1.2.4 Industry Vertical Integration
- 1.2.5 Industry Vertical Retirements
- 1.3 By Deployment Mode
- 1.3.1 On-Premises
- 1.3.2 Cloud
- 1.4 By Enterprise Size
- 1.4.1 Small and Medium Enterprises (SMEs)
- 1.4.2 Large Enterprises
- 1.5 By Industry Vertical
- 1.5.1 BFSI
- 1.5.2 IT and Telecom
- 1.5.3 Retail and E-commerce
- 1.5.4 Healthcare
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 68.35 million → 2032: USD 199.93 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 France Industry Vertical Modernization Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 France Industry Vertical Modernization Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 France Industry Vertical Modernization Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 France Industry Vertical Modernization Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 France Industry Vertical Modernization Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 France Industry Vertical Modernization Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 France Industry Vertical Modernization Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 France Industry Vertical Modernization Services Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 68.35 million → 2032: USD 199.93 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 France Industry Vertical Modernization Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Base-Year Market Share, 2023
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Industry Vertical Portfolio Assessment
- 12.3.6.2 Cloud Industry Vertical Migration
- 12.3.6.3 Industry Vertical Replatforming
- 12.3.6.4 Industry Vertical Integration
- 12.3.6.5 Industry Vertical Retirements
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment Mode - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Base-Year Market Share, 2023
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 On-Premises
- 12.4.6.2 Cloud
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Base-Year Market Share, 2023
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Small and Medium Enterprises (SMEs)
- 12.5.6.2 Large Enterprises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Base-Year Market Share, 2023
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 BFSI
- 12.6.6.2 IT and Telecom
- 12.6.6.3 Retail and E-commerce
- 12.6.6.4 Healthcare
- 12.6.6.5 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 France Industry Vertical Modernization Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 France Industry Vertical Modernization Services Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 France Industry Vertical Modernization Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2023-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 France Industry Vertical Modernization Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Capgemini
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Atos SE
- 18.4 SAP SE
- 18.5 Siemens AG
- 18.6 Accenture
- 18.7 TCS (Tata Consultancy Services)
- 18.8 Cognizant
- 18.9 IBM Corporation
- 18.10 Infosys
- 18.11 Wipro
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

