
Market Overview:
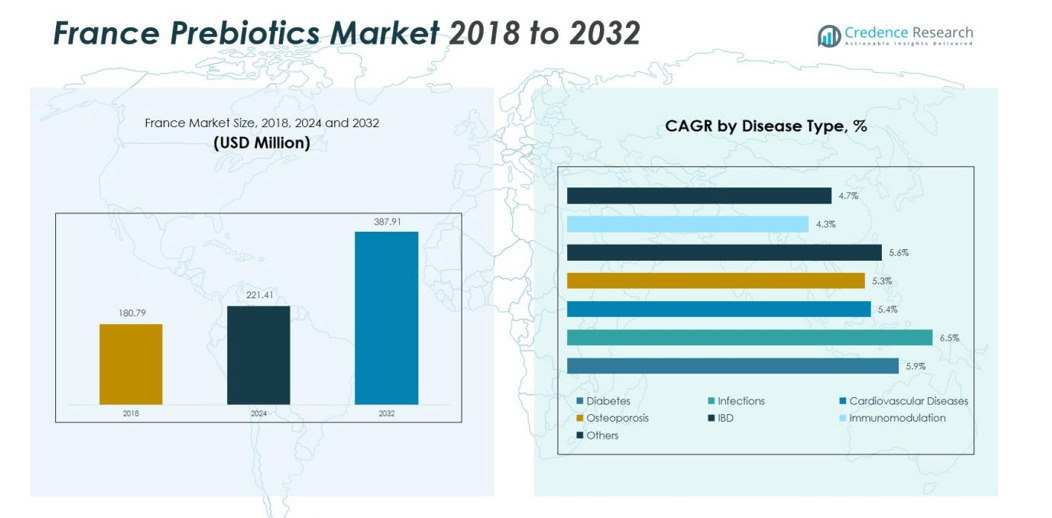
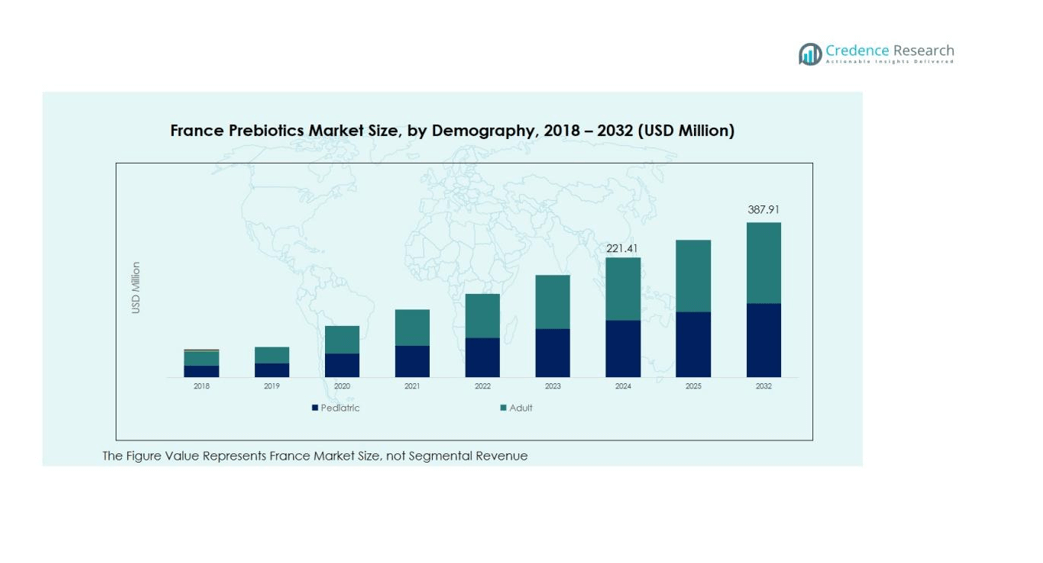
The France Prebiotics Market size was valued at USD 180.79 million in 2018 to USD 221.41 million in 2024 and is anticipated to reach USD 387.91 million by 2032, at a CAGR of 7.26% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Prebiotics Market Size 2024 | USD 221.41 million |
| France Prebiotics Market, CAGR | 7.26% |
| France Prebiotics Market Size 2032 | USD 387.91 million |
Market growth is primarily driven by rising awareness about digestive health, immunity, and gut microbiota balance. French consumers are shifting toward clean-label and wellness-oriented food products, encouraging manufacturers to incorporate inulin, FOS, and GOS into diverse formulations. Ongoing research investments and favorable European regulations supporting health claims strengthen innovation and competitive differentiation among domestic and international brands.
Regionally, Northern and Western France lead the market, supported by advanced food manufacturing facilities and a high concentration of health-conscious consumers. Paris and neighboring regions show strong consumption patterns due to higher disposable incomes and access to functional products. Southern and Eastern France are emerging as growth areas, driven by the expansion of nutraceutical distribution networks and increasing adoption in fortified dairy and bakery segments.
Market Insights:
- The France Prebiotics Market was valued at USD 180.79 million in 2018, reached USD 221.41 million in 2024, and is projected to attain USD 387.91 million by 2032, registering a CAGR of 7.26% during the forecast period.
- Northern France holds the largest share of 38%, supported by strong consumer awareness, advanced food processing facilities, and the presence of major functional food manufacturers.
- Western France accounts for 27% of the market, driven by established dairy industries and increasing adoption of fortified food and beverage products.
- Southern France, with a 19% share, is the fastest-growing region, supported by expanding nutraceutical production, higher disposable incomes, and growing demand for healthy beverages and snacks.
- By product, inulin leads with a 32% share, followed by fructo-oligosaccharides (FOS) at 24%, reflecting strong demand in functional dairy and dietary supplements across France.
Market Drivers:
Rising Focus on Digestive Health and Preventive Nutrition
The France Prebiotics Market is driven by increasing consumer awareness about the role of gut health in overall wellness. People are adopting dietary habits that support digestive balance, immunity, and metabolic health. This shift encourages manufacturers to develop products enriched with prebiotic ingredients like inulin, FOS, and GOS. It benefits from growing demand for functional foods that promote natural and preventive nutrition across all age groups.
- For Instance, FrieslandCampina Ingredients partnered with Brenntag Specialties to exclusively distribute its Biotis prebiotic range for nutritional health products in France.
Expansion of Clean-Label and Plant-Based Food Products
Consumers in France are increasingly prioritizing transparency and sustainability in food choices. The demand for clean-label and plant-based food and beverage products supports the inclusion of prebiotic fibers sourced from chicory, agave, and other natural origins. It encourages food producers to reformulate offerings and comply with evolving consumer expectations for traceable ingredients. This transition strengthens the position of prebiotics within the broader health and wellness market.
- For Instance, BENEO expanded its overall chicory root fiber production capacity by more than 40% through a multi-million euro investment announced in November 2021. The expansion project involves its production sites in both Oreye, Belgium, and Pemuco, Chile, and was initiated in 2022 to meet growing demand for prebiotic fiber.
Government Support and Regulatory Framework for Functional Foods
Strong government backing and European Food Safety Authority (EFSA) regulations encourage innovation in the functional food sector. The France Prebiotics Market benefits from these favorable policies, which help brands secure approvals for scientifically validated health claims. It enables product differentiation and boosts consumer trust in prebiotic-based products. This environment supports R&D investments and fosters long-term market competitiveness.
Expanding Applications Across Nutraceutical and Dairy Industries
Prebiotics are gaining importance across sectors such as nutraceuticals, dairy, and infant nutrition. Leading French food and supplement manufacturers are integrating prebiotics to improve gut health benefits and product functionality. It allows producers to target diverse consumer groups, from infants to older adults. The growing availability of fortified yogurts, drinks, and supplements highlights the expanding use of prebiotics across multiple industries.
Market Trends:
Integration of Prebiotics in Functional Foods and Nutraceutical Formulations
The France Prebiotics Market is witnessing strong integration of prebiotics into functional foods, beverages, and nutraceutical products. Manufacturers are leveraging scientific research to develop formulations that improve gut microbiota and immunity. Growing consumer awareness of digestive wellness has led to widespread adoption of prebiotic-enriched dairy, bakery, and plant-based alternatives. It supports higher innovation in natural sweeteners and fiber-rich ingredients sourced from chicory and Jerusalem artichoke. Companies are introducing new formats such as gummies, powders, and drink mixes to appeal to younger demographics. The rising preference for convenient and personalized nutrition solutions is reinforcing the market’s diversification across both retail and online platforms.
- For instance, Danone launched Activia Proactive in August 2025, a thick and creamy low-fat yogurt containing billions of live probiotics and 3 grams of prebiotic fiber per serving, specifically designed to support digestive health and cater to the growing consumer demand for functional wellness foods.
Rising Influence of Clean-Label, Sustainable, and Personalized Nutrition Trends
Sustainability and transparency have become key purchasing factors among French consumers. The France Prebiotics Market reflects this shift through rising use of locally sourced, traceable, and eco-friendly ingredients. It aligns with the country’s broader movement toward responsible consumption and reduced environmental impact. Manufacturers are increasingly focusing on clean-label product innovation, highlighting natural origin and absence of synthetic additives. Digital health tools and personalized nutrition apps are helping consumers choose products that match specific digestive and metabolic needs. Collaborations between research institutions and food producers are expanding the scientific validation of prebiotic benefits, driving long-term market credibility and brand differentiation.
- For instance, Exden, a French manufacturer specializing in probiotic, prebiotic, and postbiotic supplements, guarantees 100% French manufacturing with ISO 22000 certification for quality and traceability, supporting clean-label innovation in the sector with small or large batch production capabilities.
Market Challenges Analysis:
High Production Costs and Complex Ingredient Sourcing Processes
The France Prebiotics Market faces challenges from high production costs and complex sourcing of raw materials. Extracting inulin, FOS, and GOS from natural sources like chicory and agave involves energy-intensive processes and advanced purification systems. It limits cost competitiveness and makes prebiotics more expensive than synthetic alternatives. Supply chain disruptions and seasonal fluctuations in raw material availability increase price volatility. Smaller manufacturers often struggle to maintain profit margins while ensuring quality and consistency. These factors create barriers for new entrants and affect large-scale commercialization efforts.
Regulatory Complexity and Limited Consumer Understanding of Prebiotic Benefits
Regulatory complexity remains a major restraint for the France Prebiotics Market. The approval process for health claims under EFSA regulations requires strong clinical evidence and detailed product validation. It slows product launches and increases compliance costs for companies. Limited consumer understanding of the difference between probiotics and prebiotics also affects market penetration. Many consumers associate gut health benefits only with probiotics, reducing awareness of prebiotic functionality. Continuous education and marketing investments are essential to overcome misconceptions and support long-term market growth.
Market Opportunities:
Growing Potential in Personalized Nutrition and Functional Food Innovation
The France Prebiotics Market holds strong potential in personalized nutrition and functional product innovation. Rising demand for tailored health solutions encourages the development of prebiotic formulations designed for specific digestive, metabolic, and immune needs. It allows brands to target niche segments such as sports nutrition, weight management, and healthy aging. The adoption of digital health platforms supports customized dietary recommendations based on gut microbiome data. Food and beverage companies are using this trend to launch fortified products with measurable health outcomes. This focus on personalization is expected to redefine consumer engagement and expand market penetration.
Expansion Across Pharmaceutical, Animal Feed, and Infant Nutrition Segments
Emerging applications across pharmaceuticals, animal feed, and infant nutrition create new avenues for growth. The France Prebiotics Market benefits from ongoing clinical research linking prebiotics to immune modulation and metabolic health. It enables wider product diversification beyond traditional food categories. Infant formula producers are incorporating prebiotic blends to replicate the benefits of human milk oligosaccharides. Animal feed manufacturers are also adopting prebiotics to enhance gut health and productivity in livestock. Expanding across these high-value sectors strengthens industry resilience and opens sustainable long-term growth prospects.
Market Segmentation Analysis:
By Product Segment
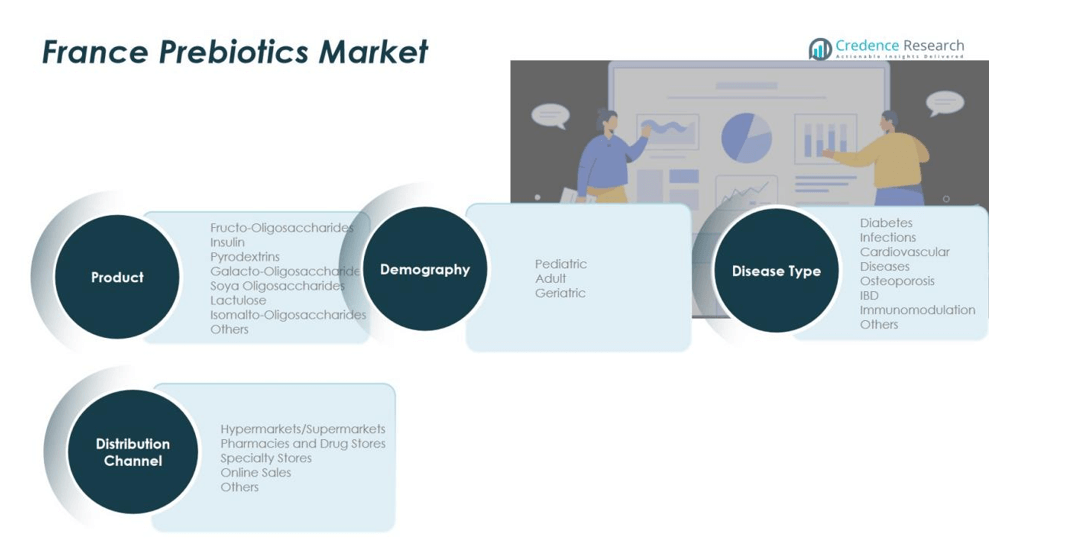
The France Prebiotics Market features a diverse product range led by inulin and fructo-oligosaccharides (FOS). These ingredients dominate due to their proven digestive and immune health benefits. Galacto-oligosaccharides (GOS) and lactulose are gaining demand in infant nutrition and dairy applications. Pyrodextrins and soya oligosaccharides contribute to functional bakery and beverage formulations. It continues to evolve through innovation in plant-based and fiber-enriched food solutions that align with clean-label trends.
- For instance, Roquette, a global leader in plant-based ingredients, launched its NUTRIOSE® FB06 soluble fiber formulation in bakery applications showcasing Mediterranean-style savory cakes with Nutri-Score A rating and featuring combined solutions with NUTRALYS® B85F pea protein delivering 8 grams of prebiotic fiber and 15 grams of plant-based protein per 3-ounce serving for functional beverage applications targeting GLP-1 health management.
By Disease Type Segment
The market shows strong adoption across diabetes management, cardiovascular health, and infection prevention segments. Prebiotics play a vital role in reducing inflammation, balancing glucose levels, and improving metabolic function. Demand for immunity and gut-related disease management further supports market expansion. It benefits from scientific validation and rising public awareness of preventive nutrition. Osteoporosis and inflammatory bowel disease (IBD) segments are witnessing increased interest among older consumers.
- For instance, a 2024 randomised controlled trial by Cambridge University reported that a 24-week intake of 20 g/day of a diverse prebiotic fiber by participants with pre-diabetes led to a 0.17% reduction in HbA1c and a 1.62-point improvement in insulin sensitivity, highlighting clinical efficacy in glucose control.
By Demography Segment
Prebiotic consumption in France spans across pediatric, adult, and geriatric populations. Adults remain the largest consumer base due to their focus on digestive wellness and balanced nutrition. Pediatric applications grow through fortified infant formulas and functional dairy products. The geriatric population drives demand for products supporting bone density and immune health. It highlights the broad demographic acceptance and long-term growth potential of prebiotics across all age groups.
Segmentations:
By Product Segment:
- Fructo-Oligosaccharides
- Inulin
- Pyrodextrins
- Galacto-Oligosaccharides
- Soya Oligosaccharides
- Lactulose
- Isomalto-Oligosaccharides
- Others
By Disease Type Segment:
- Diabetes
- Infections
- Cardiovascular Diseases
- Osteoporosis
- Inflammatory Bowel Disease (IBD)
- Immunomodulation
- Others
By Demography Segment:
- Pediatric
- Adult
- Geriatric
By Distribution Channel Segment:
- Hypermarkets/Supermarkets
- Pharmacies and Drug Stores
- Specialty Stores
- Online Sales
- Others
Regional Analysis:
Strong Market Presence in Northern and Western France
The France Prebiotics Market records strong dominance in Northern and Western regions, driven by advanced food processing infrastructure and higher consumer awareness. Paris, Normandy, and Brittany lead in consumption and production due to the concentration of functional food manufacturers and research institutions. It benefits from established retail distribution networks and a large base of health-conscious consumers. Demand for clean-label and plant-based products is particularly high in these areas. The presence of multinational brands and local startups supports continuous product innovation and regional revenue growth.
Emerging Growth Opportunities in Southern France
Southern France is rapidly developing into a promising growth region supported by expanding nutraceutical and dairy industries. Rising disposable incomes and increasing interest in fortified foods contribute to steady market expansion. The France Prebiotics Market in this region gains strength from tourism-driven demand for healthy beverages and snacks. It attracts new investments from food producers aiming to diversify product portfolios. Regional trade clusters and agricultural resources enhance the supply of natural raw materials for prebiotic production.
Expanding Distribution and Awareness Across Eastern and Central France
Eastern and Central France show growing adoption of prebiotic-enriched products, driven by urbanization and improved retail penetration. Consumers are becoming more aware of gut health benefits, supported by local promotional campaigns and educational initiatives. It benefits from government programs encouraging functional food innovation and sustainable agriculture. Expanding e-commerce platforms and pharmacy networks are widening product accessibility. The gradual rise in consumer engagement with natural supplements positions these regions for consistent future growth.
Key Player Analysis:
- Danone S.A.
- Yakult Honsha Co., Ltd.
- Nestlé S.A.
- OptiBac Probiotics Ltd.
- Archer Daniels Midland Company
- BioGaia AB
- Lallemand Inc.
- Kerry Group plc
- Hansen Holding A/S
- DuPont Nutrition & Biosciences
- General Mills Inc.
- Arla Foods amba
- Biotiful Gut Health Ltd.
Competitive Analysis:
The France Prebiotics Market features a competitive landscape led by multinational and regional players such as Danone S.A., Yakult Honsha Co., Ltd., Nestlé S.A., OptiBac Probiotics Ltd., Archer Daniels Midland Company, BioGaia AB, Lallemand Inc., and Kerry Group plc. These companies focus on product innovation, scientific validation, and expanding their prebiotic ingredient portfolios. It demonstrates steady competition in functional food, nutraceutical, and dairy-based applications. Strong emphasis on R&D supports the development of clean-label and plant-derived formulations aligned with consumer health trends. Companies are also strengthening distribution networks and forming collaborations to improve regional reach. The competitive environment continues to evolve with strategic mergers and product diversification aimed at sustaining market leadership and expanding consumer engagement.
Recent Developments:
- In October 2025, Yakult Honsha completed a merger between Yakult Europe B.V. and Yakult Oesterreich GmbH, effective October 1, 2025, to enhance operational efficiency and strengthen sales activities across Austria.
- In August 2025, Nestlé entered a partnership with IBM Research to develop sustainable food packaging using generative AI, aiming to reduce plastic use through advanced, data‑driven material science.
Report Coverage:
The research report offers an in-depth analysis based on Product, Disease Type, Demography and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The France Prebiotics Market is expected to witness strong expansion driven by rising health awareness and clean-label trends.
- Growing consumer preference for natural digestive health products will support steady product adoption.
- Food and beverage companies will expand their prebiotic-enriched offerings across dairy, bakery, and plant-based categories.
- The integration of prebiotics into functional snacks and drinks will attract younger consumers.
- R&D investments will focus on enhancing stability, taste, and compatibility of prebiotics in various formulations.
- Personalized nutrition solutions and digital health tools will increase targeted product recommendations.
- The pharmaceutical and nutraceutical sectors will adopt prebiotics for immunity and metabolic health support.
- Online retail and direct-to-consumer models will enhance product accessibility and brand visibility.
- Sustainability-focused sourcing and transparent labeling will strengthen consumer trust and market credibility.
- Strategic collaborations among manufacturers, research bodies, and food producers will drive innovation and long-term competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the France Prebiotics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate (CAGR) is the France Prebiotics Market expected to grow between 2024 and 2032?
Which product segment held the largest share of the France Prebiotics Market in 2024?
What are the primary factors driving growth in the France Prebiotics Market?
Who are the leading companies operating in the France Prebiotics Market?
Which region commanded the largest share of the France Prebiotics Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Prebiotics Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 France Prebiotics Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 221.41 million → 2032: USD 387.91 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Prebiotics Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Prebiotics Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Prebiotics Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 France Prebiotics Drivers
- 3.3 France Prebiotics Restraints & Challenges
- 3.4 France Prebiotics Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Prebiotics Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Prebiotics Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Prebiotics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Prebiotics Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. France Prebiotics Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to France Prebiotics in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Prebiotics Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 France Prebiotics Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 France Prebiotics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Prebiotics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in France Prebiotics
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. France Prebiotics – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. France Prebiotics – Priority Domestic Market 1
Chapter 10. France Prebiotics – Priority Domestic Market 2
Chapter 11. France Prebiotics – Priority Domestic Market 3
Chapter 12. France Prebiotics – Priority Domestic Market 4
Chapter 13. France Prebiotics Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
