
Market Overview
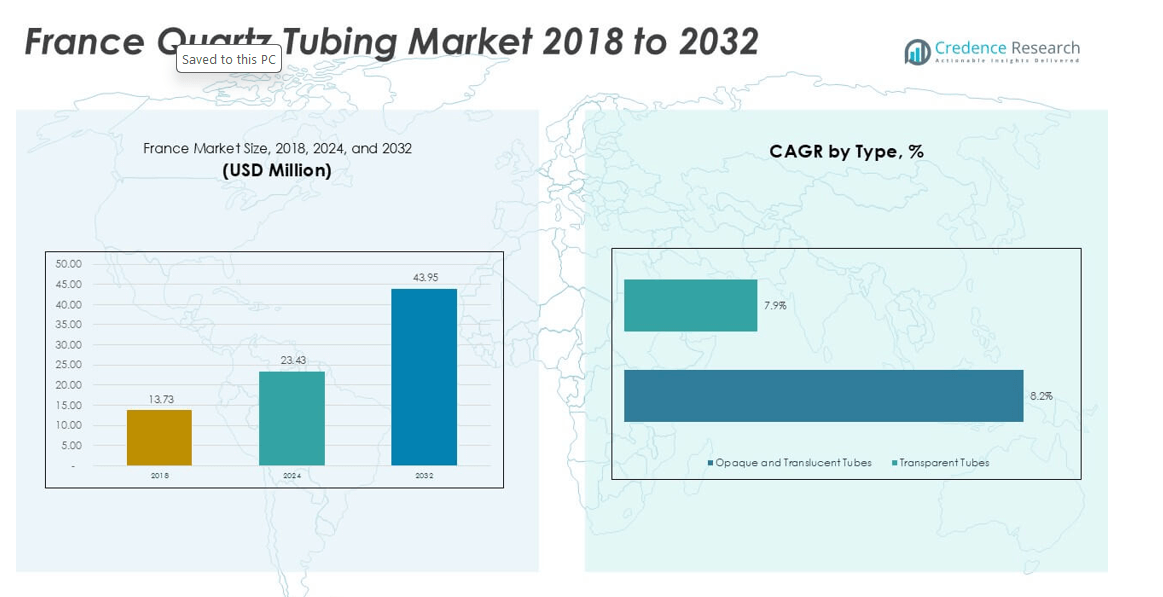
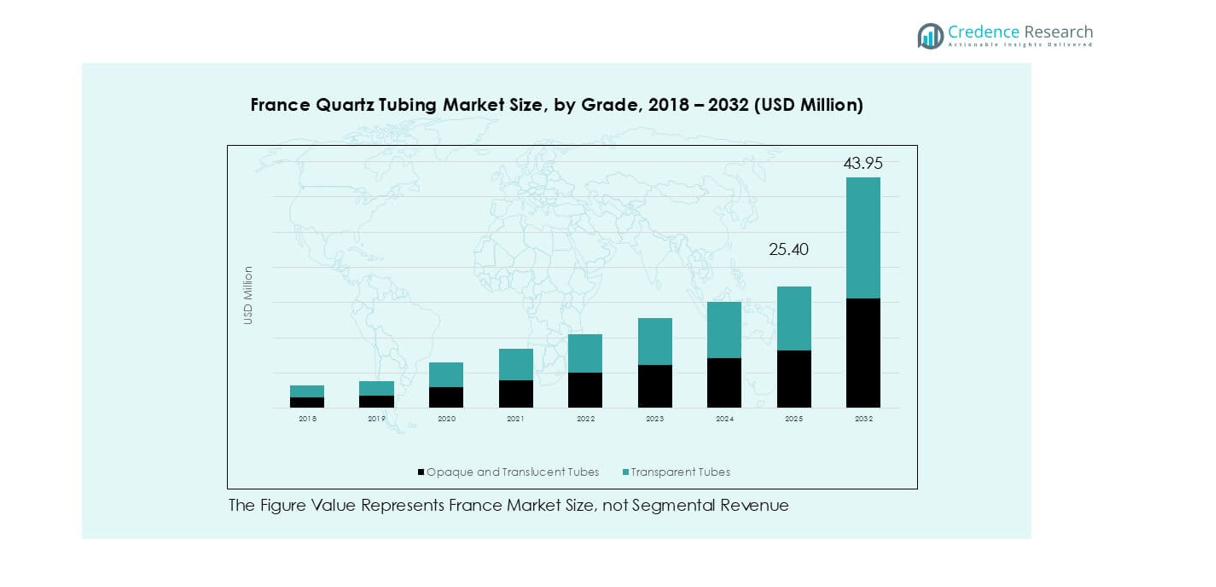
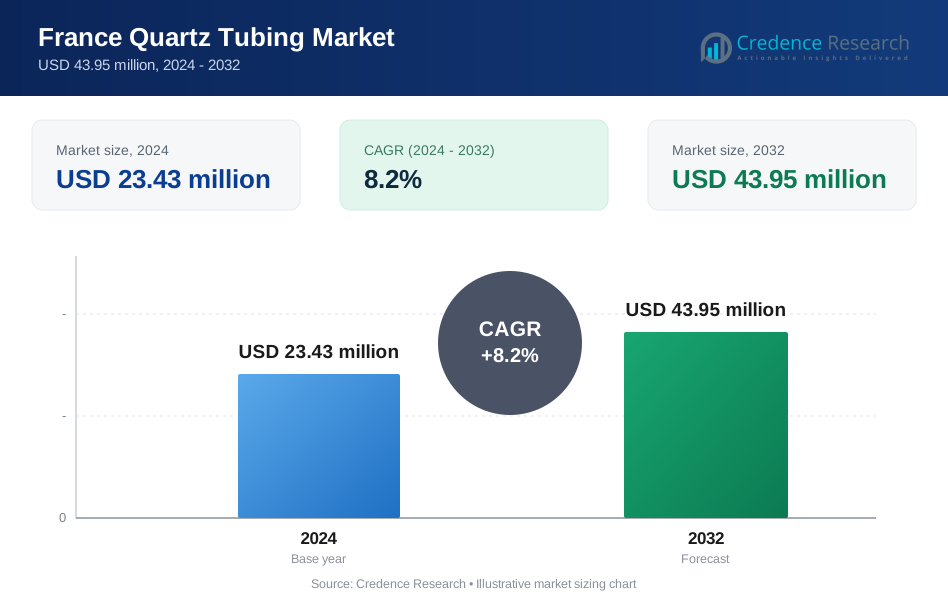
The France quartz tubing market was valued at USD 13.73 million in 2018 to USD 23.43 million in 2024 and is projected to hit USD 43.95 million by 2032, at a CAGR of 8.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Quartz Tubing Market Size 2024 | USD 23.43 million |
| France Quartz Tubing Market, CAGR | 8.2% |
| France Quartz Tubing Market Size 2032 | USD 43.95 million |
The France quartz tubing market features a mix of global leaders and specialized suppliers. Key players include Heraeus, John Moncrieff Ltd, WONIK Quartz Europe, proQuarz GmbH, and Sung Rim Europe GmbH. These companies compete on purity control, custom fabrication, and delivery reliability. Heraeus and WONIK Quartz Europe hold strong positions in high-purity semiconductor-grade tubing. John Moncrieff and proQuarz focus on industrial and laboratory applications. Regionally, Northern France leads the market with about 29% share, supported by advanced manufacturing clusters. Southern France follows with nearly 21%, driven by electronics and research demand. Eastern France holds around 18%, benefiting from cross-border industrial activity.
Market Insights
- The France quartz tubing market grew from USD 23.43 million in 2024 toward USD 43.95 million by 2032, at a CAGR of about 8.2%, driven by steady industrial and semiconductor demand.
- Market growth is supported by rising semiconductor fabrication, high-temperature industrial processing, and demand for high-purity quartz tubes in diffusion and furnace applications.
- Key trends include growing use of transparent quartz tubes, which hold around 62% segment share, and increasing demand for customized, high-purity tubing with precise dimensions.
- The competitive landscape remains moderately consolidated, with global players and European specialists competing on quality, customization, and technical support rather than price alone.
- Regionally, Northern France leads with about 29% share, followed by Southern France at 21% and Eastern France at 18%, while Western and Central France serve stable industrial and research-driven demand.
Market Segmentation Analysis:
By Type
Transparent quartz tubes dominate the France quartz tubing market, holding about 62% share. Semiconductor and precision industrial uses drive this lead. Transparent tubes offer high purity, low thermal expansion, and superior optical clarity. These features support diffusion, oxidation, and inspection processes. Chip fabrication and laboratory equipment rely on consistent light transmission and thermal stability. Opaque and translucent tubes serve niche uses, such as heating and insulation. However, demand grows slower due to limited optical needs. Ongoing investment in high-purity processing supports continued preference for transparent quartz tubes.
- For instance, Heraeus France supplies transparent fused-quartz tubes with thermal expansion near 0.55×10⁻⁶/K and hydroxyl levels under 10 ppm, supporting oxidation and inspection steps in semiconductor and analytical equipment.
By Application
Industrial applications lead with nearly 48% market share in France. This segment benefits from broad use in thermal processing, chemical handling, and high-temperature furnaces. Steel, chemicals, and advanced manufacturing drive steady demand. Semiconductor applications follow closely, supported by wafer fabrication and equipment upgrades. Growth remains strong due to capacity expansion and tighter purity standards. Lighting applications hold a smaller share as LED adoption reduces traditional quartz lamp demand. Still, specialty lighting and UV systems sustain baseline consumption within this segment.
- For instance, Saint-Gobain manufactures industrial fused-silica tubing used in high-temperature furnaces with continuous operating stability above 1,100 °C, enabling reliable performance in chemical and advanced manufacturing plants across France.
Key Growth Drivers
Expansion of Semiconductor Manufacturing and Equipment Upgrades
Rising semiconductor activity strongly drives the France quartz tubing market. Chipmakers require ultra-high-purity quartz tubes for diffusion and oxidation. Advanced nodes demand tight impurity control and thermal stability. Equipment upgrades increase replacement cycles for quartz components. Domestic fabs prioritize consistent material quality and traceability. Quartz tubing supports LPCVD, PECVD, and furnace processes. Growth in power electronics and sensors adds further demand. Automotive electrification strengthens local semiconductor needs. Government support for strategic chip production accelerates investment. These factors sustain long-term demand for precision quartz tubing solutions.
- For instance, QSIL supplies semiconductor-grade quartz tubes with metallic impurities below 1 ppm and certified operating stability above 1,050 °C, supporting diffusion and PECVD tools used in European wafer fabs.
Growth in High-Temperature Industrial Processing
Industrial thermal processing remains a major growth driver in France. Quartz tubing withstands extreme temperatures and aggressive chemicals. Steel, chemicals, and glass industries rely on such properties. Energy efficiency targets encourage replacement of legacy materials. Quartz improves heat transfer and process control. Waste treatment and specialty ceramics also increase usage. Continuous furnaces and pilot reactors need custom tube designs. Local manufacturers value shorter lead times from regional suppliers. Industrial modernization programs therefore boost steady quartz tubing consumption.
- For instance, Saint-Gobain produces fused-silica tubes for industrial furnaces with thermal expansion near 0.55 × 10⁻⁶/K and continuous-use capability above 1,100 °C, enabling reliable operation in French chemical and glass-processing facilities.
Demand for High-Purity and Customized Quartz Products
Demand shifts toward high-purity and application-specific quartz tubing. Semiconductor and research users require minimal contamination risk. Custom diameters and wall thicknesses improve equipment compatibility. Surface finish precision enhances yield and process repeatability. Suppliers invest in advanced purification and forming methods. Engineering support becomes a key buying factor. Customized products command higher margins and stronger customer loyalty. This trend favors suppliers with technical expertise and flexible production capabilities.
Key Trends & Opportunities
Localization of Supply Chains and Domestic Sourcing
Supply chain localization creates new opportunities in France. End users seek reduced dependence on imports. Domestic sourcing improves delivery reliability and risk control. Local suppliers offer faster customization and technical collaboration. Regulatory compliance also favors regional production. Public programs support strategic materials manufacturing. Partnerships with equipment OEMs strengthen long-term contracts. Localization enhances quality assurance and after-sales support. These advantages open stable growth avenues for French quartz tubing producers.
- For instance, Heraeus operates fused-silica production in Europe supplying quartz tubing rated for continuous use above 1,100 °C, enabling shorter lead times and tighter quality control for French semiconductor and industrial customers.
Adoption of Advanced Manufacturing and Digital Quality Control
Manufacturers adopt automation and digital inspection systems. Advanced forming improves dimensional consistency. Inline inspection detects defects early. Digital traceability supports semiconductor compliance needs. Process data analytics reduce scrap rates. These upgrades improve cost efficiency and product reliability. Customers increasingly favor suppliers with modern production lines. Technology adoption therefore strengthens competitiveness and market positioning.
- For instance, QSIL uses automated laser-measurement systems that control tube diameter within ±0.1 mm and optical inspection tools capable of detecting surface defects down to 50 µm, supporting high-precision quartz tubing for semiconductor and photonics applications.
Key Challenges
High Production Costs and Energy Intensity
High production costs pose a key challenge. Quartz purification and melting require significant energy. Energy price volatility impacts margins. Capital-intensive equipment raises entry barriers. Smaller players face scale disadvantages. Cost pressures limit pricing flexibility. Customers demand high quality without major price increases. Managing energy efficiency becomes critical. This challenge constrains profitability despite healthy demand.
Technical Barriers and Skilled Workforce Constraints
Quartz tubing production requires specialized technical skills. Precision forming and purity control demand experience. Skilled labor shortages affect output consistency. Training programs take time and investment. Process errors lead to high rejection rates. Equipment maintenance also requires expertise. Smaller suppliers struggle to retain talent. These constraints slow capacity expansion. Addressing workforce gaps remains essential for sustainable growth.
Regional Analysis
Northern France
Northern France holds about 29% of the France quartz tubing market. The region benefits from a strong industrial base and proximity to semiconductor and electronics clusters. Advanced manufacturing plants drive steady demand for high-purity quartz tubes used in thermal processing and equipment components. Well-developed logistics networks support efficient raw material sourcing and product distribution. Cross-border trade with Belgium and Germany further strengthens regional activity. Ongoing investments in industrial modernization and automation sustain replacement demand. The presence of skilled labor and research centers also supports customized quartz tubing production and technical collaboration.
Western France
Western France accounts for nearly 18% of the market. The region’s demand links closely to chemical processing, research laboratories, and specialty lighting applications. Universities and public research institutes increase consumption of transparent quartz tubing for experimental and pilot-scale setups. Port access supports import of raw materials and export of finished products. Industrial users value stable supply and moderate customization needs. Growth remains steady rather than rapid, driven by incremental capacity upgrades. Renewable energy research and UV-based systems also support niche demand, keeping Western France an important secondary market.
Southern France
Southern France represents around 21% of the France quartz tubing market. The region benefits from strong presence in electronics, aerospace, and advanced materials research. Semiconductor-related demand continues to rise due to power electronics and sensor applications. Industrial furnaces and specialty glass processing also contribute to consumption. Favorable climate supports research parks and technology hubs. Suppliers serve both industrial users and academic institutions. Growth remains supported by innovation-driven demand and pilot manufacturing activity. Southern France also attracts investment in clean technologies, which use quartz tubing in testing and thermal systems.
Central France
Central France holds approximately 14% market share. The region is driven mainly by industrial applications rather than semiconductors. Quartz tubing supports thermal processing in ceramics, metallurgy, and chemical pilot plants. Demand focuses on durable, opaque, and translucent tubes for high-temperature use. Central France benefits from lower operating costs and available industrial land. Manufacturers here emphasize cost efficiency and reliable supply. Growth is moderate but stable, supported by replacement demand and incremental upgrades. The region serves as a balancing market with consistent but less technology-intensive consumption patterns.
Eastern France
Eastern France accounts for about 18% of the market. Proximity to Germany and Switzerland strengthens cross-border industrial demand. The region supports advanced manufacturing, precision engineering, and specialty chemicals. Semiconductor equipment suppliers and furnace manufacturers drive demand for high-quality transparent quartz tubes. Strong technical standards favor premium products with tight tolerances. Export-oriented production enhances regional competitiveness. Energy-intensive industries also contribute to volume demand. Eastern France benefits from skilled labor and established industrial ecosystems, supporting steady growth and a strong position in high-spec quartz tubing applications.
Market Segmentations:
By Type
- Opaque and Translucent Tubes
- Transparent Tubes
By Application
- Industrial Applications
- Semiconductor
- Lighting
By Geography
- Northern France
- Western France
- Southern France
- Central France
- Eastern France
Competitive Landscape
The France quartz tubing market shows a moderately consolidated competitive landscape. Global players and specialized regional suppliers compete on purity, customization, and delivery reliability. Leading companies leverage advanced purification, precision forming, and strong quality systems to serve semiconductor and industrial customers. European suppliers benefit from proximity to end users and strict compliance standards. Asian manufacturers compete through cost advantages and expanding European footprints. Strategic focus centers on high-purity transparent tubes, custom dimensions, and technical support. Partnerships with equipment OEMs strengthen long-term supply agreements. Investment in automation and inspection improves yield and consistency. Competitive differentiation increasingly depends on engineering capability, responsiveness, and long-term customer collaboration rather than price alone.
Key Player Analysis
- John Moncrieff Ltd
- Heraeus
- Sung Rim Europe GmbH
- Labquartz Silica Pvt. Ltd.
- Fudong Lighting
- Aoxin Quartz
- Sentro Tech
- proQuarz GmbH
- WONIK Quartz Europe
- Multi-Lab Ltd
Recent Developments
- In Jan 2025, Heraeus combined high-performance materials units into Heraeus Covantics to expand its technology leadership in high-purity quartz and fused silica products.
- In Nov 2024, Momentive Technologies promoted two long-serving executives into global quartz and ceramics leadership roles, strengthening its quartz business focus
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Semiconductor manufacturing will remain a primary demand driver across high-purity quartz tubing applications.
- Industrial modernization will increase replacement demand for heat-resistant quartz components.
- Transparent quartz tubes will continue to gain share due to precision process requirements.
- Custom dimensions and tighter purity standards will shape product development priorities.
- Domestic sourcing will grow as end users seek supply chain stability.
- Automation and digital inspection will improve production efficiency and consistency.
- Research and laboratory demand will support steady baseline consumption.
- Energy efficiency pressures will influence material selection and process design.
- Skilled labor availability will remain critical for quality assurance and capacity expansion.
- Competition will intensify around engineering support, lead times, and long-term partnerships.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the France Quartz Tubing market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the France Quartz Tubing market projected to grow between 2024 and 2032?
Which France Quartz Tubing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the France Quartz Tubing market?
Who are the leading companies in the France Quartz Tubing market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Quartz Tubing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global France Quartz Tubing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 23.43 million → 2032: USD 43.95 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Quartz Tubing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Quartz Tubing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Quartz Tubing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 France Quartz Tubing Market Drivers
- 3.3 France Quartz Tubing Market Restraints & Challenges
- 3.4 France Quartz Tubing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Quartz Tubing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Quartz Tubing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Quartz Tubing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Quartz Tubing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. France Quartz Tubing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the France Quartz Tubing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Quartz Tubing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 France Quartz Tubing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 France Quartz Tubing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Quartz Tubing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New France Quartz Tubing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global France Quartz Tubing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America France Quartz Tubing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe France Quartz Tubing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific France Quartz Tubing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America France Quartz Tubing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East France Quartz Tubing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa France Quartz Tubing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. France Quartz Tubing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
