
Market Overview
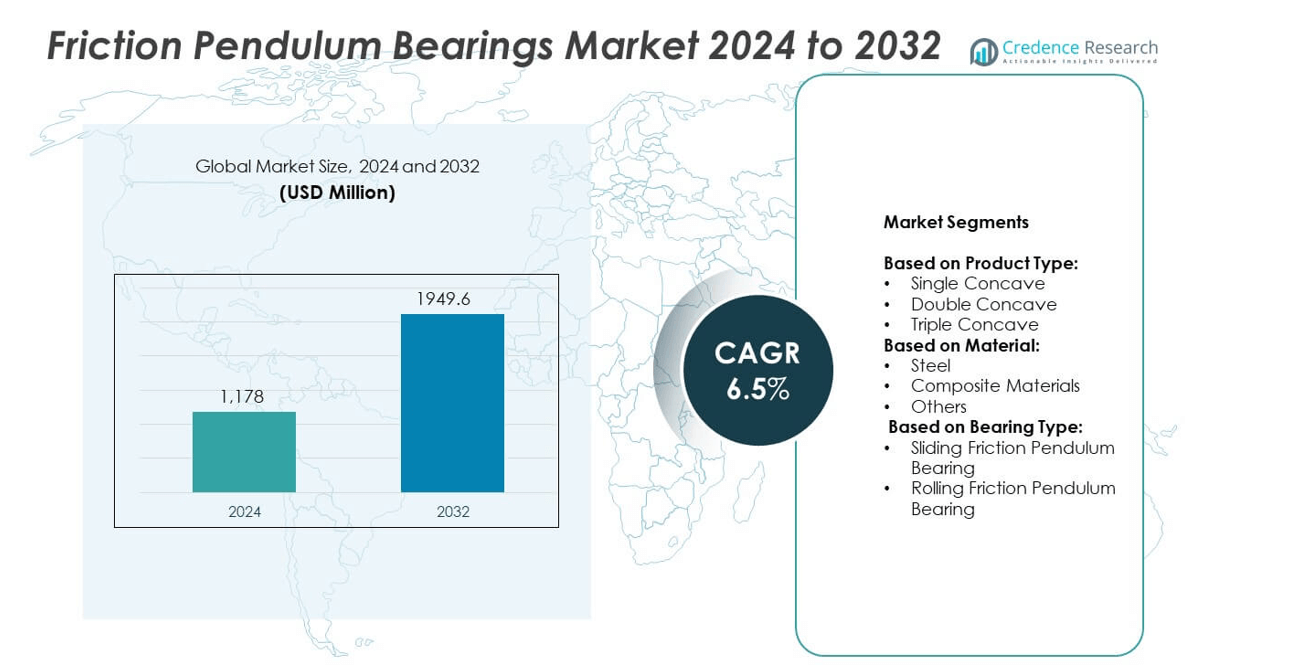
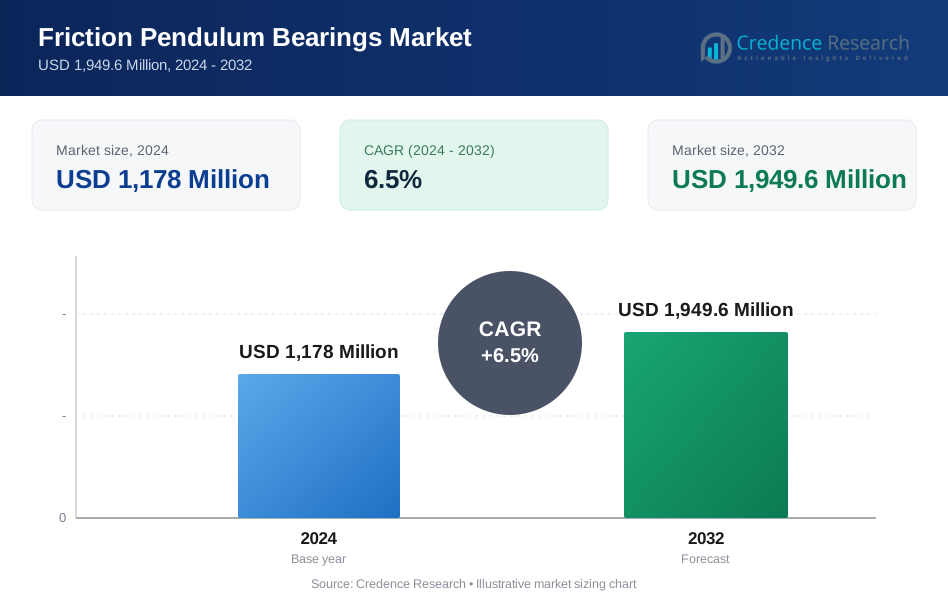
The Friction Pendulum Bearings market size was valued at USD 1,178 Million in 2024 and is expected to reach USD 1,949.6 Million by 2032, growing at a CAGR of 6.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Friction Pendulum Bearings Market Size 2024 | USD 1,178 Million |
| Friction Pendulum Bearings Market, CAGR | 6.5% |
| Friction Pendulum Bearings Market Size 2032 | USD 1,949.6 Million |
The Friction Pendulum Bearings market grows due to rising focus on seismic safety and resilient infrastructure. Governments enforce strict building codes, boosting adoption in bridges, hospitals, and public facilities. Demand rises from metro projects, airports, and industrial facilities in seismic zones. Manufacturers innovate with multi-concave designs and advanced materials to improve energy dissipation and durability. Integration of digital monitoring systems supports predictive maintenance. These factors collectively drive market expansion and strengthen confidence among engineers and project developers worldwide.
North America leads demand for friction pendulum bearings, driven by strict seismic safety codes and large-scale infrastructure projects. Europe follows with strong adoption in Italy, Turkey, and Greece for retrofitting schools and bridges. Asia-Pacific shows the fastest growth due to rapid urbanization and metro construction in Japan, China, and India. Key players include Zenith Technologies LLC (ZTech), WSP Group, Mabey Bridge, and NSK Ltd., focusing on innovative designs, material improvements, and collaborations to support resilient infrastructure development worldwide.
Market Insights
- The Friction Pendulum Bearings market was valued at USD 1,178 Million in 2024 and is projected to reach USD 1,949.6 Million by 2032 at a CAGR of 6.5%.
- Growth is fueled by rising demand for seismic-resilient infrastructure, strict building codes, and public funding support.
- Key trends include adoption of double and triple concave designs, use of composite materials, and integration of digital monitoring systems.
- Leading players such as Zenith Technologies LLC (ZTech), WSP Group, Mabey Bridge, NSK Ltd., and Trelleborg AB focus on innovation and global project partnerships.
- High installation costs and limited awareness in emerging regions act as restraints, slowing market penetration in cost-sensitive projects.
- North America leads demand due to robust seismic codes, while Asia-Pacific shows fastest growth supported by urban infrastructure and government mandates.
- Europe and Latin America emphasize retrofitting of aging bridges and hospitals, and Middle East & Africa increase adoption in high-risk seismic zones.
Market Drivers
Growing Demand for Seismic Resilient Infrastructure and Safety Standards
The Friction Pendulum Bearings market is driven by the rising focus on earthquake-resistant infrastructure. Governments and private developers invest heavily in base-isolated structures to protect lives and assets. It provides a proven solution to minimize structural damage during seismic events. Urbanization in earthquake-prone regions like Japan, India, and California fuels adoption. Infrastructure projects such as bridges, hospitals, and government buildings specify these bearings to meet stringent codes. This trend strengthens market growth and adoption across public and private construction sectors.
- For instance, Well-Link offers bearings with nominal vertical loads from 0.5 to 4000 tons, horizontal displacement of ±100 to ±1000 mm, and coefficient of friction between 0.01 and 0.05
Rising Investments in Smart Cities and Large-Scale Infrastructure Projects
Global investments in smart cities and transport networks are creating strong opportunities. The Friction Pendulum Bearings market benefits from increasing construction of metro stations, airports, and viaducts. It enhances structural resilience while reducing maintenance costs over the life cycle. Public-private partnerships accelerate deployment in developing nations with seismic risks. Funding support from multilateral banks and agencies encourages integration of advanced seismic isolation technology. Large infrastructure projects adopt these bearings to meet long-term durability requirements and ensure safety.
- For instance, in Japan-US research on Triple Friction Pendulum Bearings (TPBs), a five-story steel frame building specimen was excited 21 times using TPB system in tests, under real strong ground motions such as the 2011 Tohoku earthquake record.
Technological Advancements and Product Innovation Driving Adoption
Manufacturers are developing bearings with improved energy dissipation and load-carrying capacities. The Friction Pendulum Bearings market sees strong demand for double and triple concave designs. It allows buildings to withstand stronger quakes with minimal structural disruption. Research focuses on advanced composite materials to enhance wear resistance and service life. Digital monitoring systems are integrated for real-time performance tracking. These innovations increase confidence among engineers and regulators, encouraging broader adoption in critical infrastructure.
Regulatory Mandates and International Building Code Compliance
Compliance with global seismic design codes supports rapid market expansion. The Friction Pendulum Bearings market aligns with standards such as ASCE 7, Eurocode 8, and Indian IS codes. It ensures projects meet required safety levels for earthquake protection. Governments enforce building regulations for schools, hospitals, and bridges, boosting demand. Insurance firms encourage installation by offering lower premiums for isolated structures. Regulatory pressure combined with public safety awareness sustains long-term growth in multiple regions.
Market Trends
Adoption of Multi-Concave and Advanced Bearing Designs
The Friction Pendulum Bearings market is witnessing a clear shift toward double and triple concave designs. Engineers prefer these systems for their superior displacement capacity and energy dissipation. It enables structures to handle higher seismic forces without major damage. Multi-concave bearings also provide better re-centering after an earthquake. Research efforts focus on optimizing geometry for reduced friction losses. This trend improves performance and lowers lifecycle maintenance costs for critical infrastructure.
- For instance, the company JingTong Rubber Bridge Bearings produces vibration-resistant tensile friction pendulum bearings with a rated load capacity of 1,000 kN, coefficient of friction 0.05, and maximum displacement ±100 mm.
Integration of Digital Monitoring and Smart Sensors
Smart monitoring solutions are becoming common in seismic isolation projects. The Friction Pendulum Bearings market benefits from embedded sensors that track displacement, load, and wear. It allows asset owners to perform predictive maintenance and ensure long-term reliability. Real-time data helps engineers validate designs and improve safety protocols. Cloud-based systems offer centralized control and faster decision-making. Adoption of smart bearings supports the shift toward connected infrastructure.
- For instance, In tests done at the CCCC Highway Bridges National Engineering Research Centre, a friction pendulum bearing specimen with a design capacity of 10,000 kN was subjected to a vertical static force of 10,000 kN. The specimen was then tested under cyclic displacement cycles of 27 mm, 54 mm, and 81 mm to evaluate its rapid friction performance.
Growing Focus on Sustainable and Durable Material Selection
Material innovation is shaping the next generation of products. The Friction Pendulum Bearings market is seeing development of composite sliding surfaces and corrosion-resistant alloys. It increases lifespan while reducing replacement frequency. Manufacturers are reducing reliance on traditional steel-only components for better environmental performance. Coatings that resist extreme weather and chemical exposure gain traction. Demand grows for eco-friendly solutions that meet green building certifications.
Expansion in Emerging Economies with High Seismic Risks
Emerging markets are driving significant demand for base isolation systems. The Friction Pendulum Bearings market expands rapidly in Asia-Pacific, Latin America, and parts of the Middle East. It is supported by government programs focused on disaster-resilient infrastructure. Bridge construction, urban metro projects, and industrial facilities use bearings to safeguard assets. International suppliers form partnerships with local contractors to meet regional needs. Rising construction spending in earthquake-prone cities sustains this growth trend.
Market Challenges Analysis
High Initial Costs and Limited Awareness in Developing Regions
The Friction Pendulum Bearings market faces barriers due to high installation and material costs. Many infrastructure developers in emerging economies hesitate to adopt base isolation systems. It creates challenges for widespread implementation despite proven safety benefits. Limited awareness among contractors and engineers further slows market penetration. Training programs and demonstrations are often required to build confidence. Governments must provide financial incentives or subsidies to make these solutions more accessible.
Complex Design Requirements and Maintenance Considerations
Designing and installing these systems demands specialized expertise and precise engineering. The Friction Pendulum Bearings market must address concerns about inspection and long-term upkeep. It can be difficult to ensure proper maintenance in remote infrastructure projects. Failure to monitor bearings can lead to reduced performance during seismic events. Regulatory compliance adds complexity, requiring detailed documentation and approvals. Manufacturers must work with stakeholders to simplify design integration and provide reliable support services.
Market Opportunities
Rising Infrastructure Investments and Government Support Programs
The Friction Pendulum Bearings market is positioned to benefit from large-scale infrastructure expansion. Governments are prioritizing seismic safety for bridges, airports, and metro projects. It creates steady demand for advanced base isolation systems in both developed and developing nations. Public funding and international aid programs promote adoption in high-risk zones. Disaster-resilient infrastructure initiatives increase awareness and push project planners to specify these systems. This environment offers suppliers strong long-term growth potential.
Advancements in Smart Bearings and Material Innovation
Innovation in smart sensors and durable materials creates new opportunities for manufacturers. The Friction Pendulum Bearings market gains from digital monitoring that enables predictive maintenance and cost savings. It attracts asset owners looking for lifecycle efficiency and operational reliability. Advanced composites and corrosion-resistant coatings open possibilities in harsh climate applications. Integration with IoT platforms allows data-driven decision-making for infrastructure managers. These trends enhance product value and strengthen competitiveness in global projects.
Market Segmentation Analysis:
By Product Type:
The Friction Pendulum Bearings market is segmented into single concave, double concave, and triple concave designs. Single concave bearings hold a strong share due to their cost-effectiveness and simpler design, making them ideal for small and mid-scale projects. Double concave bearings are gaining popularity for their superior energy dissipation and higher displacement capacity. It allows critical infrastructure such as hospitals, bridges, and government buildings to maintain functionality during strong seismic events. Triple concave bearings serve highly specialized projects where maximum isolation and safety are required. Growing adoption of these advanced designs is supported by stricter seismic codes worldwide.
- For instance, in the “Sliding Isolation Pendulum” for seismic protection by WIT Press / UCSD / University of Armed Forces Munich, devices responded to vertical loads of 2,225 kN, 4,450 kN, and 6,675 kN at friction coefficients of 5%, 4%, and 3% respectively; displacement demands were calculated as ±201 mm.
By Material:
The market is divided into steel, composite materials, and others. Steel remains the most widely used material because of its strength and reliability. It offers proven performance in heavy-duty infrastructure and high-load applications. Composite materials are emerging as a fast-growing segment due to their lighter weight, corrosion resistance, and low maintenance requirements. These materials extend service life in coastal and humid environments where steel can degrade faster. Others include hybrid materials and advanced alloys developed for niche applications. Demand for durable and sustainable materials is expected to shape future innovations in this segment.
- For instance, Hengshui Jingtong Rubber Co., Ltd. supplies a Friction Pendulum Bearing model with rated load capacity 1,000 kN, coefficient of friction 0.05, and maximum displacement of ±100 mm.
By Bearing Type:
The market is categorized into sliding friction pendulum bearings and rolling friction pendulum bearings. Sliding bearings dominate due to their lower cost, simpler design, and widespread use in bridges and public infrastructure. It is favored for its proven ability to reduce seismic forces effectively. Rolling bearings, while more expensive, provide smoother motion and minimal wear, making them suitable for high-value structures where long service life is a priority. Manufacturers are investing in designs that minimize maintenance while improving re-centering performance. The combination of technology innovation and project-specific customization drives strong growth across both bearing types.
Segments:
Based on Product Type:
- Single Concave
- Double Concave
- Triple Concave
Based on Material:
- Steel
- Composite Materials
- Others
Based on Bearing Type:
- Sliding Friction Pendulum Bearing
- Rolling Friction Pendulum Bearing
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for 32% of the Friction Pendulum Bearings market, driven by high adoption of seismic isolation technologies in the United States and Canada. The region prioritizes earthquake resilience, especially in states like California, Oregon, and Washington where seismic activity is significant. It benefits from strict building codes such as ASCE 7, which encourage the use of base isolation systems for critical structures. Demand is strong in bridges, hospitals, data centers, and public infrastructure projects. Federal and state government funding supports retrofitting of existing assets with modern bearings to reduce risk. Research institutions and engineering firms in the region contribute to innovation, resulting in the development of high-performance multi-concave bearings. Growing investment in smart city infrastructure and resilient transport systems ensures sustained demand over the forecast period.
Europe
Europe represents 27% of the Friction Pendulum Bearings market, supported by widespread use in countries such as Italy, Greece, Turkey, and the United Kingdom. Seismic activity in Southern Europe creates a strong need for advanced isolation technologies. It is further supported by the enforcement of Eurocode 8 standards, which guide earthquake-resistant design. Governments actively fund infrastructure safety programs, with emphasis on retrofitting schools, cultural monuments, and public buildings. Demand is also increasing in Northern and Western Europe where aging bridges require seismic upgrades. Manufacturers in the region are focusing on corrosion-resistant and long-life materials to meet sustainability requirements. Integration of digital monitoring systems is gaining traction, allowing operators to track bearing performance throughout their service life.
Asia-Pacific
Asia-Pacific holds 30% of the Friction Pendulum Bearings market and is the fastest-growing regional segment. Countries like Japan, China, and India drive major demand due to frequent seismic events and rapid infrastructure development. It benefits from government-mandated seismic codes and major investments in metro rail projects, airports, and industrial facilities. Japan leads in technology adoption, with highly advanced multi-concave bearing systems used in high-rise buildings and nuclear facilities. China’s Belt and Road Initiative and urbanization efforts further create strong demand for resilient bridges and transport infrastructure. Local manufacturers are expanding production capacity to meet domestic needs and supply neighboring markets. Rising awareness of disaster preparedness fuels public and private investments in base-isolated structures across the region.
Middle East & Africa
The Middle East & Africa region accounts for 6% of the Friction Pendulum Bearings market, with demand concentrated in Turkey, Iran, and parts of North Africa. Turkey’s high seismic risk encourages large-scale deployment of base isolation systems in hospitals and public buildings. It is supported by government programs aimed at minimizing earthquake damage and ensuring post-disaster functionality. The Middle East invests in infrastructure resilience for critical projects, including airports, energy facilities, and commercial complexes. Africa shows gradual adoption, with South Africa leading initiatives for bridges and transportation hubs. Rising construction spending and growing awareness of seismic risks create a potential growth market. Partnerships between global suppliers and local contractors are helping improve access to high-quality bearing systems.
Latin America
Latin America contributes 5% of the Friction Pendulum Bearings market, with Chile and Mexico leading adoption due to their high exposure to earthquakes. Both countries have implemented strict seismic codes requiring advanced isolation systems for major infrastructure projects. It supports adoption in hospitals, bridges, and government buildings designed to remain operational after earthquakes. Brazil and Argentina show rising interest as awareness of earthquake risks increases. Regional governments and private developers are exploring cost-effective solutions for retrofitting critical infrastructure. International suppliers are collaborating with local firms to enhance availability and reduce costs. Expansion of transportation networks, including elevated highways and metro systems, drives additional opportunities in the region.
Key Player Analysis
- Zenith Technologies LLC (ZTech)
- WSP Group
- Mabey Bridge
- Reed Mallik Ltd.
- Zandonini spa
- NSK Ltd.
- Trelleborg AB
- ENEGI
- KELZA Engineering
- FIP Industriale
- WISON Engineering Ltd.
- Lombardi S.r.l.
- VibroAcoustic Consultants Inc.
- S Industrial Minerals
- Furukawa Electric Co., Ltd.
Competitive Analysis
The leading players in the Friction Pendulum Bearings market include Zenith Technologies LLC (ZTech), WSP Group, Mabey Bridge, Reed Mallik Ltd., Zandonini spa, NSK Ltd., Trelleborg AB, ENEGI, KELZA Engineering, FIP Industriale, WISON Engineering Ltd., Lombardi S.r.l., VibroAcoustic Consultants Inc., S Industrial Minerals, and Furukawa Electric Co., Ltd. These companies focus on providing high-performance seismic isolation solutions to meet global infrastructure needs. The market is competitive, with players emphasizing product reliability, multi-concave designs, and compliance with international seismic codes. It is characterized by significant investments in R&D to enhance energy dissipation capacity, durability, and monitoring capabilities. Many players collaborate with engineering firms and government agencies to supply bearings for large-scale projects such as metro systems, hospitals, and bridges. Strategic partnerships and joint ventures help expand presence in emerging economies with growing infrastructure demand. Companies also invest in manufacturing capacity and material innovation to lower costs and improve performance. The shift toward smart bearings with integrated sensors supports differentiation in a competitive market. Overall, competition drives continuous innovation and wider adoption, ensuring that global infrastructure projects meet higher safety and performance standards.
Recent Developments
- In 2024, Mabey Bridge reported a long-span Delta installed in South Lanarkshire, Scotland.
- In 2024, WSP engineers joined a Taiwan earthquake reconnaissance mission after the 7.2 quake
- In 2024, Furukawa Electric opened a laser processing solutions laboratory in Aichi.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Bearing Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily driven by rising seismic safety awareness.
- Governments will continue mandating base isolation systems for critical infrastructure projects.
- Adoption of double and triple concave bearings will increase for enhanced energy dissipation.
- Demand for digital monitoring solutions will expand to support predictive maintenance.
- Composite materials and corrosion-resistant alloys will gain share due to durability benefits.
- Infrastructure investments in Asia-Pacific will drive the fastest regional market growth.
- Retrofitting of aging bridges and public buildings will create long-term opportunities.
- Collaboration between global suppliers and local contractors will improve cost efficiency.
- Research will focus on developing smart bearings with real-time data tracking capabilities.
- Growing emphasis on climate resilience will encourage use of sustainable material solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Seismic Resilient Infrastructure and Safety Standards
Governments and private developers are increasingly investing in earthquake-resistant infrastructure, mandating the use of friction pendulum bearings in critical structures like bridges, hospitals, and public buildings to comply with stringent seismic codes and protect assets.
Rising Investments in Smart Cities and Large-Scale Infrastructure Projects
Global infrastructure expansion, especially in metro systems, airports, and viaducts, is driving adoption of friction pendulum bearings to ensure structural resilience and reduce long-term maintenance costs, supported by public funding and international aid.
Technological Advancements and Product Innovation
Manufacturers are introducing advanced double and triple concave designs, composite materials, and digital monitoring systems, which enhance energy dissipation, durability, and enable predictive maintenance, increasing confidence among engineers and regulators.
Regulatory Mandates and International Building Code Compliance
Strict enforcement of seismic design codes such as ASCE 7, Eurocode 8, and Indian IS codes is accelerating market growth, as compliance is required for new and retrofitted infrastructure in seismic-prone regions, often incentivized by insurance and government programs.
Expansion in Emerging Economies with High Seismic Risks
Rapid urbanization and government-backed disaster-resilient infrastructure initiatives in Asia-Pacific, Latin America, and the Middle East are creating significant new demand for friction pendulum bearings, especially in earthquake-prone cities and regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Friction Pendulum Bearings market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Friction Pendulum Bearings Market projected to grow between 2025 and 2032?
Which Friction Pendulum Bearings market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Friction Pendulum Bearings market?
Who are the leading companies in the Friction Pendulum Bearings Market?
Which region commanded the largest share of the Fried Onion market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Steel
- 1.2.2 Composite Materials
- 1.2.3 Others
- 1.3 By Bearing Type
- 1.3.1 Sliding Friction Pendulum Bearing
- 1.3.2 Rolling Friction Pendulum Bearing
- 1.4 By Product Type
- 1.4.1 Single Concave
- 1.4.2 Double Concave
- 1.4.3 Triple Concave
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,178 Million → 2032: USD 1,949.6 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Friction Pendulum Bearings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Friction Pendulum Bearings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Friction Pendulum Bearings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Friction Pendulum Bearings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Friction Pendulum Bearings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Friction Pendulum Bearings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Friction Pendulum Bearings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Friction Pendulum Bearings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,178 Million → 2032: USD 1,949.6 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Friction Pendulum Bearings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Steel
- 12.3.7.2 Composite Materials
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Bearing Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sliding Friction Pendulum Bearing
- 12.4.7.2 Rolling Friction Pendulum Bearing
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single Concave
- 12.5.7.2 Double Concave
- 12.5.7.3 Triple Concave
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Friction Pendulum Bearings Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Friction Pendulum Bearings Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Friction Pendulum Bearings Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Zenith Technologies LLC (ZTech)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 WSP Group
- 17.4 Mabey Bridge
- 17.5 NSK Ltd.
- 17.6 Trelleborg AB
- 17.7 FIP Industriale
- 17.8 Furukawa Electric Co., Ltd.
- 17.9 Zandonini spa
- 17.10 WISON Engineering Ltd.
- 17.11 Lombardi S.r.l.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

