
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Gastroenterology Devices Market Size 2024 | USD 9,753.8 million |
| Gastroenterology Devices Market, CAGR | 8.3% |
| Gastroenterology Devices Market Size 2032 | USD 18,458.71 million |
Market Overview:
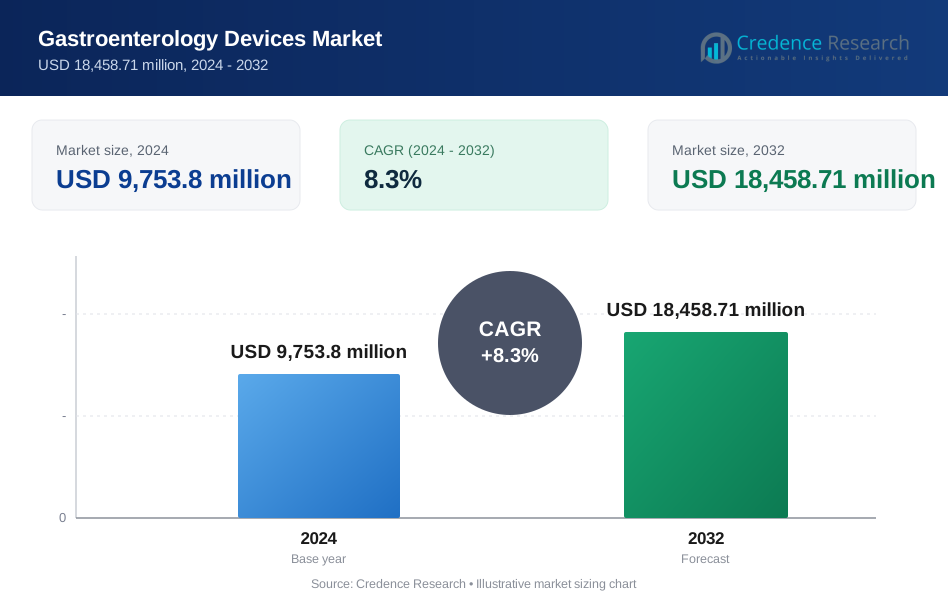
The Gastroenterology Devices Market valued at approximately USD 9,753.8 million in 2024, is projected to expand significantly, reaching an estimated USD 18,458.71 million by 2032. This growth, at a compound annual growth rate (CAGR) of 8.3% from 2024 to 2032, underscores the rising demand for advanced diagnostic and therapeutic devices in gastroenterology. These devices, including endoscopes, imaging systems, and biopsy tools, play a crucial role in diagnosing, monitoring, and treating gastrointestinal (GI) disorders, which are on the rise globally due to factors like aging populations, unhealthy diets, and increasing cases of colorectal cancer and inflammatory bowel disease (IBD). With greater awareness of early diagnosis and advances in minimally invasive procedures, the adoption of gastroenterology devices is accelerating across healthcare systems.
Several factors drive this market's growth, primarily the increasing prevalence of gastrointestinal disorders and the growing need for minimally invasive treatments. According to the World Health Organization (WHO), digestive diseases are among the top causes of morbidity globally. Additionally, technological advancements in endoscopic devices and imaging systems, including high-definition and AI-assisted endoscopy, enhance diagnostic accuracy and patient outcomes, boosting market demand. Rising healthcare spending and government initiatives to improve early diagnosis and treatment of GI diseases further support the expansion of the gastroenterology devices market.
Regionally, North America holds the largest market share, driven by a high prevalence of GI disorders, well-established healthcare infrastructure, and significant investment in medical technology. The United States, in particular, leads due to high healthcare spending and strong adoption of advanced gastroenterology devices. Europe follows closely, with countries like Germany and France showing substantial demand supported by government healthcare initiatives. The Asia-Pacific region is anticipated to experience the fastest growth due to a rapidly expanding healthcare infrastructure, increasing awareness of gastrointestinal health, and a rising elderly population. These regional trends highlight the global need for effective, innovative gastroenterology solutions to meet growing healthcare demands.
Market Drivers:
Rising Prevalence of Gastrointestinal Disorders:
The increasing prevalence of gastrointestinal (GI) disorders worldwide is a major driver for the gastroenterology devices market. According to the World Gastroenterology Organisation, over 20% of the global population suffers from chronic GI conditions such as irritable bowel syndrome (IBS) and inflammatory bowel disease (IBD). For instance, colorectal cancer remains the third most common cancer globally, with more than 1.9 million new cases reported in 2022. This high disease burden fuels the demand for diagnostic and therapeutic devices, as healthcare providers seek advanced tools for early detection and treatment.
Growing Preference for Minimally Invasive Procedures:
A growing preference for minimally invasive procedures has increased demand for advanced gastroenterology devices, particularly endoscopic tools. Minimally invasive techniques reduce recovery time, minimize post-operative complications, and enhance patient outcomes. For instance, studies show that minimally invasive endoscopic procedures have reduced hospital stays by nearly 30% compared to traditional surgeries. Companies like Olympus and Boston Scientific are continually innovating in this field, developing endoscopes with high-definition imaging and smaller diameters to improve patient comfort and diagnostic accuracy.
Technological Advancements in Endoscopic and Imaging Devices:
Technological advancements in endoscopy and imaging devices have revolutionized gastroenterology diagnostics and treatment. Innovations like AI-assisted endoscopy, which can detect polyps and abnormalities with 90% accuracy, significantly enhance diagnostic precision. Companies such as Fujifilm and Medtronic have introduced AI-integrated imaging systems, improving the accuracy of GI cancer screenings. Furthermore, high-definition imaging and capsule endoscopy offer enhanced visibility and ease, enabling physicians to examine hard-to-reach areas of the GI tract more effectively, boosting demand for these advanced devices.
Increasing Healthcare Expenditure and Government Support:
Increasing healthcare expenditure and supportive government initiatives drive the adoption of gastroenterology devices worldwide. In 2023, global healthcare spending reached USD 10 trillion, with substantial allocations toward medical technology and early diagnostics. Governments are also launching programs to encourage early screenings for GI conditions. For example, the U.S. Preventive Services Task Force recommends colorectal cancer screenings beginning at age 45. This focus on preventive care and early diagnosis underscores the critical role of advanced gastroenterology devices, pushing healthcare providers to adopt modern, effective technologies to meet patient needs.
Market Trends:
Integration of Artificial Intelligence in Diagnostic Tools:
The integration of artificial intelligence (AI) in gastroenterology devices is a transformative trend, enhancing diagnostic accuracy and efficiency. AI algorithms are now capable of identifying polyps and early-stage cancerous lesions with accuracy rates as high as 95%, according to a 2023 study by the American Gastroenterological Association. Companies like Olympus and Fujifilm are leading in this space, with AI-powered endoscopy systems that aid in real-time polyp detection, reducing missed diagnoses. AI’s potential to streamline diagnostic processes is expected to drive its continued adoption in the field.
Growth of Capsule Endoscopy for Non-Invasive Diagnostics:
Capsule endoscopy, a minimally invasive diagnostic approach, is increasingly popular for diagnosing disorders of the small intestine. For instance, A recent report indicated that capsule endoscopy usage has grown by 40% in the past five years, as patients and clinicians favor its non-invasive nature. Companies like Medtronic offer capsule endoscopy solutions that provide detailed images without requiring sedation or hospital stay. This technology enables a more comfortable experience for patients and is particularly useful for examining difficult-to-access areas of the gastrointestinal (GI) tract.
Rising Adoption of Single-Use Endoscopes:
The adoption of single-use endoscopes is rising, driven by growing concerns over infection control and cross-contamination. According to the U.S. Centers for Disease Control and Prevention (CDC), infection outbreaks related to reusable endoscopes have increased by nearly 20% in recent years. In response, single-use endoscopes are gaining traction in healthcare settings. Companies like Ambu and Boston Scientific have developed disposable endoscopes that eliminate the risk of infection transmission, addressing safety concerns and supporting regulatory compliance in infection control.
Telemedicine and Remote Monitoring for GI Care:
Telemedicine and remote monitoring are emerging as key trends in gastroenterology, driven by the need for accessible, continuous patient care. For instance, The American Telemedicine Association reported a 60% increase in telemedicine consultations for GI conditions from 2021 to 2023. Companies are now offering remote monitoring devices, such as pH and motility capsules, that patients can use at home to record GI metrics. This trend not only supports ongoing patient care but also reduces hospital visits, aligning with the healthcare industry’s shift towards value-based and patient-centered care solutions.
Market Challenges Analysis:
High Costs of Advanced Gastroenterology Devices:
One of the primary challenges facing the gastroenterology devices market is the high cost associated with advanced diagnostic and therapeutic devices. Technologies such as AI-integrated endoscopes, capsule endoscopy systems, and single-use endoscopes require significant investment, which can be prohibitive for smaller healthcare facilities. For instance, AI-powered endoscopes and advanced imaging systems are often costly, with prices reaching upwards of USD 50,000 per unit. These high costs limit adoption, particularly in regions where healthcare budgets are constrained or not subsidized by government programs.
Stringent Regulatory Standards and Approval Delays:
The market is subject to stringent regulatory standards, which can delay product approvals and add to development costs. Agencies like the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) require extensive testing and validation to ensure device safety and efficacy. While these regulations are essential for patient safety, they often extend the time and resources needed to bring new technologies to market. Compliance with these regulations, particularly for devices incorporating new technologies like AI, can be resource-intensive and result in longer approval timelines, impacting the timely introduction of innovative solutions.
Shortage of Skilled Gastroenterologists and Technicians:
A shortage of skilled gastroenterologists and trained technicians poses a significant challenge for the market. According to the American Society for Gastrointestinal Endoscopy, nearly 40% of healthcare facilities in the U.S. report difficulties in recruiting trained personnel to operate complex devices like advanced endoscopes and imaging systems. This shortage affects the efficient utilization of gastroenterology devices, leading to underuse in some facilities and contributing to procedural backlogs.
Infection Control and Reusability Concerns:
Despite their cost advantages, reusable endoscopes present challenges in terms of infection control. The U.S. Centers for Disease Control and Prevention (CDC) has reported a 20% increase in infections linked to reusable endoscopes over recent years. Ensuring proper sterilization is labour-intensive and requires strict adherence to protocols. Inadequate sterilization procedures can lead to cross-contamination, risking patient safety and imposing additional regulatory and operational challenges for healthcare providers, thereby encouraging a shift towards costlier single-use devices.
Market Segmentation Analysis:
By Type
The gastroenterology devices market is segmented by type into endoscopes, imaging systems, hemostasis devices, and others. Endoscopes represent the largest segment, owing to their essential role in diagnosing and treating gastrointestinal (GI) disorders. Imaging systems are also prominent, providing high-resolution visuals that enhance diagnostic accuracy in both screening and procedural settings. Hemostasis devices are critical in managing GI bleeding, a common complication in various GI diseases, supporting their consistent demand across healthcare facilities.
By Technology
By technology, the market includes capsule endoscopy, virtual colonoscopy, and AI-assisted imaging. Capsule endoscopy is increasingly favored for non-invasive visualization of the small intestine, addressing conditions that are challenging to diagnose with traditional methods. Virtual colonoscopy is gaining popularity as a less invasive alternative for colon cancer screening, reducing the need for sedation and minimizing patient discomfort. AI-assisted imaging is transforming the market, enabling precise identification of abnormalities such as polyps and early-stage cancers, significantly improving diagnostic outcomes.
By End User
End users of gastroenterology devices include hospitals, ambulatory surgical centers (ASCs), and specialty clinics. Hospitals hold the largest market share due to their broad patient base and access to advanced diagnostic infrastructure, essential for managing complex GI conditions. ASCs are experiencing growth as they offer efficient, cost-effective settings for minimally invasive GI procedures, aligning with the trend toward outpatient care. Specialty clinics, focusing on gastroenterology, also contribute to market demand, particularly in regions with high prevalence of GI disorders, underscoring their importance in delivering specialized care and procedures.
Segmentations:
By Device Type
- Endoscopic Devices
- Therapeutic Devices
- Diagnostic Devices
- Monitoring and Measurement Devices
By Application
- Gastrointestinal Endoscopy
- Gastrointestinal Surgery
- Enteral Feeding and Nutrition
- Gastrointestinal Imaging
By End-User
- Hospitals and Clinics
- Diagnostic Centers
- Ambulatory Care Centers
- Research Institutes and Academic Centers
By Geographic
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the gastroenterology devices market, accounting for approximately 40% of the global market. This dominance is driven by a well-established healthcare infrastructure, significant investments in medical technology, and a high prevalence of gastrointestinal (GI) disorders. The United States leads in this region, with strong adoption of advanced endoscopic and imaging technologies, supported by substantial healthcare spending and favorable reimbursement policies. The presence of leading medical device manufacturers, such as Boston Scientific and Medtronic, further strengthens the market. Canada also contributes, with increasing demand for innovative GI devices fueled by rising awareness of GI health and government support for advanced diagnostic capabilities.
Europe
Europe accounts for around 25% of the gastroenterology devices market, driven by a high demand for diagnostic and therapeutic devices across key countries such as Germany, France, and the United Kingdom. The region's healthcare systems are increasingly focused on early diagnosis and minimally invasive treatment options for GI diseases. Germany leads in adopting advanced endoscopic devices, supported by government initiatives and robust healthcare spending. France and the U.K. are also key contributors, with growing investments in healthcare technology and infrastructure. The European Union’s regulatory standards and guidelines encourage the adoption of safe and effective gastroenterology devices, promoting market growth.
Asia-Pacific
Asia-Pacific holds approximately 20% of the gastroenterology devices market and is expected to experience the fastest growth over the forecast period. Rising incidences of GI disorders, a rapidly aging population, and expanding healthcare infrastructure are key drivers of growth in this region. China, Japan, and India are major contributors. China’s large population and increasing focus on healthcare improvements support strong demand for advanced GI devices. Japan’s aging demographic is a key factor, as the elderly population typically has a higher prevalence of GI conditions, driving the need for diagnostic and therapeutic devices. Additionally, government initiatives in India to improve healthcare accessibility and infrastructure are supporting market expansion, making Asia-Pacific a vital region for growth in the gastroenterology devices market.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa together account for approximately 15% of the global gastroenterology devices market. In Latin America, Brazil and Mexico are leading in adoption, driven by an increasing prevalence of GI diseases and government initiatives to enhance healthcare capabilities. The region faces some challenges, including budget constraints and limited access to advanced technology in certain areas. However, growing awareness of GI health and demand for minimally invasive procedures support market expansion. In the Middle East & Africa, countries such as the United Arab Emirates and South Africa are investing in healthcare infrastructure, aiming to improve access to diagnostic technologies for GI diseases. Despite certain economic challenges, increased focus on healthcare development in these regions is expected to foster moderate growth in the gastroenterology devices market.
Key Player Analysis:
- Medtronic
- Boston Scientific Corporation
- Olympus Corporation
- Fujifilm Holdings Corporation
- Stryker Corporation
- CONMED Corporation
- Cook Medical
- KARL STORZ SE & Co. KG
- PENTAX Medical
- Johnson & Johnson
Competitive Analysis:
The gastroenterology devices market is highly competitive, with leading players such as Medtronic, Boston Scientific, Olympus Corporation, and Fujifilm Holdings dominating due to their expansive portfolios and continuous innovation. These companies invest significantly in R&D to introduce advanced endoscopic and imaging technologies that enhance diagnostic accuracy and therapeutic outcomes. Mid-sized players like CONMED and Cook Medical bring specialized products to the market, focusing on niche solutions in gastroenterology. Intense competition drives strategic mergers, acquisitions, and partnerships, as companies aim to expand their reach and enhance technological capabilities. Additionally, firms like Stryker and KARL STORZ leverage their strong distribution networks and brand reputation to maintain a competitive edge. This competitive landscape underscores the importance of technological advancements, reliability, and regulatory compliance as key factors for market leadership, as companies strive to meet the growing demand for minimally invasive and precise solutions for gastrointestinal diagnostics and treatments.
Recent Developments:
- In 2023, Medtronic introduced an AI-enhanced endoscopy system designed to improve polyp detection rates during colonoscopies, aiming to enhance early diagnosis and treatment outcomes.
- In 2022, Boston Scientific expanded its endoluminal surgery portfolio by acquiring Apollo Endosurgery, integrating advanced minimally invasive devices for gastrointestinal procedures.
- Olympus unveiled the EVIS X1 endoscopy system in 2022, featuring enhanced imaging capabilities and AI integration to assist clinicians in detecting gastrointestinal abnormalities more effectively.
- In 2024, Fujifilm announced the development of ultra-slim endoscopes aimed at improving patient comfort and expanding diagnostic reach, particularly in paediatric and narrow-lumen examinations.
Market Concentration & Characteristics:
The gastroenterology devices market exhibits moderate to high concentration, with major players like Medtronic, Boston Scientific, Olympus, and Fujifilm holding significant shares due to their extensive portfolios and continuous innovation in diagnostic and therapeutic devices. These companies leverage strong R&D capabilities to advance minimally invasive and AI-driven technologies, setting high standards in diagnostic accuracy and patient outcomes. The market is characterized by rapid technological advancements, particularly in endoscopy, imaging, and capsule endoscopy, which support effective, patient-centered care. Mid-sized companies such as CONMED and Cook Medical add competitive diversity by focusing on specialized solutions within gastroenterology. Strategic partnerships, acquisitions, and product innovation are prevalent, as companies aim to expand their reach and improve technological capabilities. This competitive landscape underscores the importance of innovation, regulatory compliance, and quality assurance as firms strive to meet the growing demand for precision and safety in gastrointestinal healthcare.
Report Coverage:
The research report offers an in-depth analysis based on Device Type, Application, End-User, and Geographic. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for gastroenterology devices will continue to rise as gastrointestinal disorders become more prevalent globally.
- Technological advancements, particularly in AI-assisted imaging, will improve diagnostic accuracy and enhance early detection of GI diseases.
- Minimally invasive procedures will drive growth in endoscopy devices, as patients and providers prefer options that reduce recovery time and complications.
- Capsule endoscopy is expected to gain popularity as a non-invasive alternative for diagnosing small intestine disorders.
- Single-use endoscopes will see increased adoption due to infection control concerns, especially in hospitals and high-volume clinics.
- Government funding and healthcare infrastructure improvements will support broader access to advanced GI diagnostics in emerging markets.
- Telemedicine integration and remote monitoring tools for GI care will expand, enabling continuous, accessible patient management.
- Rising awareness of colorectal cancer screening will increase the demand for devices supporting early-stage cancer diagnostics.
- Partnerships between healthcare providers and device manufacturers will strengthen, promoting the adoption of innovative, patient-centered technologies.
- The Asia-Pacific region is projected to experience rapid growth in this market due to expanding healthcare access, a rising elderly population, and increased awareness of GI health.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Gastroenterology Devices Market?
What factors are driving the growth of the Gastroenterology Devices Market?
What are some challenges faced by the Gastroenterology Devices Market?
Who are the major players in the Gastroenterology Devices Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,753.8 million → 2032: USD 18,458.71 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Gastroenterology Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Gastroenterology Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Gastroenterology Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Gastroenterology Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Gastroenterology Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Gastroenterology Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Gastroenterology Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Gastroenterology Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,753.8 million → 2032: USD 18,458.71 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Gastroenterology Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Gastroenterology Devices Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Gastroenterology Devices Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Gastroenterology Devices Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
