
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Gene Editing Tools Market Size 2024 | USD 677.76 million |
| Gene Editing Tools Market, CAGR | 18.05% |
| Gene Editing Tools Market Size 2032 | USD 2,556.25 million |
Market Overview
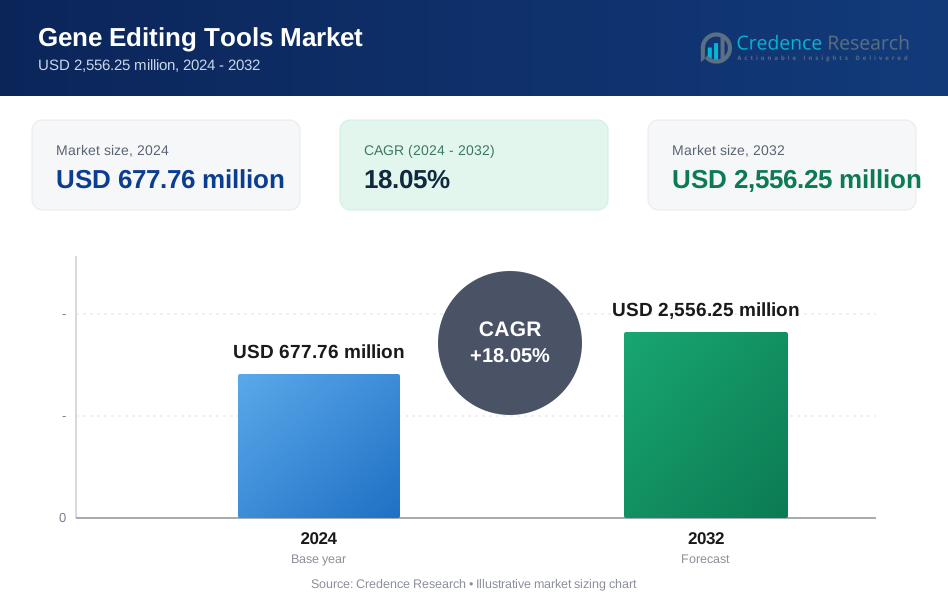
The Gene Editing Tools market is projected to grow from USD 677.76 million in 2024 to USD 2,556.25 million by 2032, reflecting a compound annual growth rate (CAGR) of 18.05%.
The Gene Editing Tools market is driven by increasing investments in genomics research, rising prevalence of genetic disorders, and advancements in CRISPR technology. Regulatory support and the growing adoption of gene editing in agriculture and biotechnology further bolster market growth. Trends include the development of more precise and efficient gene-editing techniques, expanding applications in personalized medicine, and collaborations between academic institutions and biotech companies. The market also benefits from technological innovations aimed at reducing costs and improving accessibility, ensuring a robust expansion over the forecast period.
The Gene Editing Tools market shows significant geographical diversity, with North America leading due to advanced research infrastructure and substantial funding. Europe follows, driven by strong regulatory support and growing biotech investments. The Asia Pacific region is rapidly expanding, attributed to increasing research activities and government initiatives. Key players such as Thermo Fisher Scientific, CRISPR Therapeutics, and Merck KGaA dominate the market, leveraging advanced technologies and strategic collaborations. Companies like Editas Medicine, Intellia Therapeutics, and New England Biolabs further bolster market growth through continuous innovation and expanding product portfolios.
Market Drivers
Growing Applications in Healthcare
Gene editing holds immense potential for treating a wide range of genetic disorders, offering hope for conditions that were previously considered untreatable. For example, in 2021 the FDA approved the first CRISPR-based therapy for sickle cell disease. A report by the National Institutes of Health estimates gene editing could potentially treat over 6,000 single-gene disorders affecting millions of people worldwide. It is also accelerating drug discovery and development by enabling precise manipulation of genetic sequences, which helps in identifying drug targets and understanding disease mechanisms. Additionally, the ability to tailor treatments based on individual genetic makeup is driving demand for personalized medicine. This customization ensures more effective and targeted therapies, contributing significantly to the market's expansion.
Agricultural and Food Industry Applications
Gene editing offers significant opportunities for improving crops and livestock, which is driving its adoption in the agricultural and food industries. For instance, 40 crops have been modified using CRISPR including rice (43 percent), tomato (12 percent), maize (9 percent), wheat (7 percent), and potato (4 percent). The USDA reports that as of 2022, over 70 gene-edited plant varieties have been approved for cultivation in the U.S., with traits like disease resistance and drought tolerance. It enables the development of crops with enhanced traits such as disease resistance and higher yield, contributing to food security and sustainability. In livestock, gene editing can improve animal health and productivity, addressing some of the major challenges in animal husbandry. The growing public awareness of gene editing is also fostering demand for transparent and ethical practices, while clear and supportive regulatory environments are essential for the market's growth. These frameworks ensure that innovations are safely and effectively integrated into the industry, supporting sustainable development.
Advancements in Gene Editing Technology
The emergence of CRISPR-Cas9 as a precise and efficient gene-editing tool has revolutionized the field of genetics. Its ability to make targeted changes in DNA sequences with high accuracy has opened up new possibilities for research and therapeutic applications. Ongoing technological refinements continue to enhance the accuracy and efficacy of gene editing techniques, making them more reliable and effective. These advancements are crucial for expanding the potential uses of gene editing in various sectors, ensuring robust growth in the market.
Increasing Research and Development Investments
Significant investments in gene editing research from both public and private sectors are fueling market growth. Governments and private organizations are recognizing the potential of gene editing and are providing substantial funding to support ongoing research and development efforts. Partnerships between academia and industry are accelerating innovation, facilitating the translation of research findings into practical applications. These collaborations are crucial for maintaining the momentum of technological advancements and ensuring that new discoveries are quickly integrated into marketable solutions.
Market Trends
Expanding Therapeutic Applications and Integration of Artificial Intelligence (AI)
The Gene Editing Tools market is witnessing significant advancements driven by the expanding therapeutic applications of gene editing. A particular focus is on developing gene therapies for rare genetic disorders that currently have limited treatment options, offering new hope to patients with conditions such as cystic fibrosis, muscular dystrophy, and hemophilia. For instance, a 2023 survey by the Alliance for Regenerative Medicine found that over 50% of gene therapy clinical trials now target rare genetic disorders. In oncology, the National Cancer Institute reports that CRISPR-based cancer therapies have entered clinical trials for over 20 different cancer types as of 2024. In oncology, gene editing is making strides by enabling cancer immunotherapy and targeted therapies, which can precisely attack cancer cells without harming healthy tissue. Moreover, innovative approaches are being explored for infectious diseases, utilizing gene editing to develop antiviral and antibacterial strategies that could revolutionize how we combat pathogens. Simultaneously, the integration of Artificial Intelligence (AI) is transforming the landscape of gene editing by enhancing data analysis, drug discovery, and predictive modeling. AI-powered tools are increasingly being used to analyze large-scale genomic data, helping researchers identify potential gene editing targets more efficiently. In drug discovery, AI-driven optimization of gene editing approaches accelerates the development of new therapies by predicting the most effective genetic modifications. Additionally, predictive modeling using AI allows scientists to anticipate the outcomes of gene editing experiments, thereby reducing the trial-and-error phase and increasing the success rate of therapeutic interventions. These advancements not only streamline research processes but also pave the way for more personalized and effective treatments.
Focus on Delivery, Safety, and Intellectual Property
A critical trend in the gene editing market is the focus on delivery systems and safety to ensure the efficacy and long-term viability of gene therapies. Researchers are developing more efficient methods for delivering gene editing tools to target cells, which is essential for achieving desired therapeutic outcomes. Techniques to minimize off-target effects are also being advanced to prevent unintended genetic modifications, thereby enhancing the precision and safety of gene editing. Rigorous studies are being conducted to assess the long-term safety and efficacy of gene editing therapies, which are crucial for gaining regulatory approval and public acceptance. In addition to technological advancements, the growing importance of intellectual property is shaping the competitive dynamics of the gene editing market. The patent landscape is highly competitive, with intense efforts to secure patent protection for innovative gene editing technologies. This has led to strategic partnerships and licensing agreements aimed at commercializing these innovations. Companies are actively engaging in patent battles and negotiations to secure their positions in the market. This focus on intellectual property not only drives innovation but also ensures that companies can capitalize on their research investments.
Market Challenges Analysis
Ethical and Regulatory Concerns
The Gene Editing Tools market faces significant ethical and regulatory challenges that impact its growth and acceptance. Public perception remains a major concern as there are widespread apprehensions about the ethical implications of gene editing, particularly when it involves human applications. Addressing these concerns requires transparent communication and ethical practices to gain societal acceptance. Additionally, navigating the complex and evolving regulatory landscapes poses a significant challenge. Regulatory hurdles vary across regions, making it difficult for companies to comply with diverse requirements and obtain necessary approvals. Ensuring that gene editing technologies adhere to stringent ethical and regulatory guidelines is crucial for building public trust and achieving long-term market success.
Cost, Accessibility, and Safety
The high development costs associated with gene editing therapies present a significant barrier to market growth. For instance, the first FDA-approved gene therapy for beta-thalassemia had an initial list price of $2.8 million per treatment in 2022. A survey by the American Society of Gene and Cell Therapy found that 72% of experts believe reducing costs is critical for wider adoption of gene therapies. The process of developing, testing, and bringing gene editing treatments to market is both expensive and time-consuming. Ensuring equitable access to these therapies is a challenge, as the high costs can limit their availability to only certain populations. Reimbursement issues further complicate accessibility, with healthcare providers and patients facing difficulties in obtaining coverage for gene editing treatments. This financial barrier underscores the need for strategies to make these advanced therapies more affordable and widely accessible.
Market Segmentation Analysis:
By Type:
The gene editing tools market is categorized by various types, each offering unique advantages and applications. Clustered Regularly Interspaced Short Palindromic Repeats (CRISPR/Cas9) dominate the market due to their precision, efficiency, and ease of use, making them the preferred choice for a wide range of genetic modifications. Zinc Finger Nucleases (ZFNs) and Transcription Activator-Like Effector Nucleases (TALENs) are also significant, known for their ability to target specific DNA sequences with high accuracy. Viral systems and transposon systems are employed for gene delivery purposes, leveraging their natural mechanisms to introduce genetic material into host cells. The 'others' category includes emerging and less common technologies that continue to evolve, contributing to the dynamic nature of the gene editing landscape. Each type of gene editing tool offers distinct features, enabling their application across various scientific and medical research domains.
By Application:
Gene editing tools find diverse applications across multiple fields, reflecting their versatility and transformative potential. In veterinary medicine, gene editing is used to enhance disease resistance and improve animal health. Cell line engineering benefits from these tools by enabling the development of more accurate models for drug testing and biomedical research. Bioremediation utilizes gene editing to create microorganisms capable of breaking down pollutants, contributing to environmental sustainability. The food and brewing industries apply gene editing to develop enhanced strains of yeast and other organisms, improving product quality and efficiency. Food waste management and bio-sensing development also see significant advancements through gene editing, enabling the creation of biosensors that detect contaminants and innovative solutions for reducing food waste. The 'others' category encompasses a broad range of additional applications, underscoring the extensive impact of gene editing technologies across various sectors. These applications demonstrate the far-reaching implications of gene editing tools in advancing both science and industry.
Segments:
Based on Type:
- Clustered Regularly Interspaced Short Palindromic Repeats (CRISPR/Cas9)
- Zinc Finger Nucleases (ZFNs)
- Transcription Activator-Like Effector Nucleases (TALENs)
- Viral Systems
- Transposon Systems
- Others
Based on Application:
- Veterinary Medicine
- Cell Line Engineering
- Bioremediation
- Food and Brewing Development
- Food Waste Management
- Bio-Sensing Development
- Others
Based on End User:
- Biotech and Pharma Companies
- Contract Research Organizations
- Academic and Research Institutes
- Food
- Others
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
North America
North America, commanding a substantial 45% market share. This region's dominance is primarily driven by the United States, which boasts a robust ecosystem of biotechnology companies, academic research institutions, and pharmaceutical giants actively engaged in gene editing research and development. The presence of key market players, significant investment in genomics research, and a supportive regulatory environment contribute to North America's leadership position. The region has witnessed rapid adoption of CRISPR-Cas9 technology across various applications, including drug discovery, agriculture, and therapeutic development. Furthermore, the high prevalence of genetic disorders and cancer in the region fuels the demand for innovative gene editing solutions. North America's advanced healthcare infrastructure and strong focus on personalized medicine also play crucial roles in accelerating the adoption of gene editing tools. The region continues to lead in patent filings and publications related to gene editing technologies, solidifying its position at the forefront of this revolutionary field.
Europe
Europe emerges as the second-largest market for gene editing tools, holding a 30% market share. The region's strong position is attributed to its well-established pharmaceutical and biotechnology sectors, particularly in countries like Germany, the United Kingdom, and Switzerland. European research institutions and companies have made significant contributions to the advancement of gene editing technologies, with a notable focus on developing improved CRISPR systems and exploring alternative gene editing approaches. For instance, the Horizon Europe program allocated €95.5 billion for research and innovation from 2021-2027, with a significant portion dedicated to health and biotechnology research, including gene editing. Europe's collaborative approach has facilitated cross-border research partnerships. The region benefits from supportive government initiatives and funding programs aimed at promoting genomics research and its applications in healthcare and agriculture. Europe's stringent regulatory framework for gene editing, while sometimes viewed as a challenge, has also fostered the development of high-quality, ethically-sound gene editing tools and applications. The region's collaborative approach, exemplified by initiatives like the European Research Council and Horizon Europe, has facilitated cross-border research partnerships and knowledge sharing in the field of gene editing.
Key Player Analysis
- New England Biolabs
- ERS Genomics
- Editas Medicine
- Thermo Fisher Scientific, Inc.
- Intellia Therapeutics, Inc.
- GE Healthcare Dharmacon Inc.
- Takara Bio USA
- GenScript Biotech Corporation
- CRISPR Therapeutics
- Merck KGaA
- Horizon Discovery Group plc
Competitive Analysis
The Gene Editing Tools market is highly competitive, dominated by leading players like Thermo Fisher Scientific, CRISPR Therapeutics, and Merck KGaA. Thermo Fisher Scientific stands out with its extensive product portfolio and robust distribution network, ensuring wide market reach. CRISPR Therapeutics leads in innovation, particularly with CRISPR/Cas9 technology, driving advancements in therapeutic applications. Merck KGaA excels in integrating gene editing tools with broader biotech solutions, enhancing its competitive edge. Editas Medicine and Intellia Therapeutics are at the forefront of developing novel gene therapies, securing strong patent portfolios to protect their innovations. New England Biolabs and GE Healthcare Dharmacon Inc. focus on providing high-quality reagents and tools, supporting research and development across various applications. Takara Bio USA and Horizon Discovery Group plc leverage strategic partnerships and acquisitions to expand their market presence. The intense competition drives continuous innovation, strategic collaborations, and diversification of product offerings, ensuring sustained market growth and technological advancements.
Recent Developments
- In April 2024, New England Biolabs announced a series of events to commemorate its 50th anniversary, including the 2024 Passion in Science Awards to recognize scientists making a difference through their work.
- In March 2024, ERS Genomics entered into a non-exclusive licensing agreement with Ricoh Company, Ltd. for access to CRISPR/Cas9 patent portfolio in the USA and Japan.
- In June 2024, Thermo Fisher Scientific launched a new mass spectrometry platform called Stellar at the American Society for Mass Spectrometry (ASMS) conference.
- In July 2024, Thermo Fisher Scientific completed its acquisition of Olink Holding AB, a provider of next-generation proteomics solutions, for approximately $3.1 billion.
- In June 2024, Takara Bio USA announced a global patent partnership with Jumpcode Genomics, focusing on genome technology solutions.
Market Concentration & Characteristics
The Gene Editing Tools market exhibits moderate to high market concentration, characterized by the dominance of a few key players such as Thermo Fisher Scientific, CRISPR Therapeutics, and Merck KGaA. These companies leverage extensive research capabilities, robust product portfolios, and strategic partnerships to maintain their competitive positions. The market is marked by rapid technological advancements, with a focus on precision, efficiency, and safety in gene editing techniques. Innovations like CRISPR/Cas9 continue to drive market growth, supported by substantial investments in research and development. The industry also benefits from a collaborative ecosystem involving academic institutions, biotech firms, and regulatory bodies, fostering a conducive environment for innovation. Additionally, the market is characterized by rigorous regulatory scrutiny, ensuring the ethical and safe application of gene editing technologies. As the demand for personalized medicine and biotechnological solutions increases, the market concentration may shift with the emergence of new entrants and the continual evolution of existing players.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The gene editing tools market is expected to experience robust growth driven by technological advancements in CRISPR/Cas9 and other gene-editing technologies.
- Increasing investments in genomics research will continue to propel market expansion.
- The application of gene editing in personalized medicine will significantly enhance treatment efficacy and patient outcomes.
- Growing interest in agricultural biotechnology will drive the development of genetically modified crops with improved traits.
- Regulatory frameworks will evolve to keep pace with technological advancements, ensuring safe and ethical use of gene editing tools.
- Emerging markets in Asia Pacific and Latin America will become key growth regions due to rising research activities and supportive government initiatives.
- Strategic collaborations and partnerships will accelerate innovation and market penetration.
- Enhanced delivery systems will improve the efficiency and safety of gene editing applications.
- Public awareness and acceptance of gene editing technologies will increase, fostering broader adoption.
- The competitive landscape will intensify with new entrants and continuous innovations from established players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Applications in Healthcare
Gene editing tools are increasingly used to develop therapies for genetic disorders, accelerate drug discovery, and enable personalized medicine, driving demand as these applications expand in clinical and research settings.
Agricultural and Food Industry Applications
The adoption of gene editing in agriculture for crop improvement, disease resistance, and livestock productivity is fueling market growth, supported by regulatory approvals and the need for sustainable food production.
Advancements in Gene Editing Technology
Continuous improvements in precision, efficiency, and safety - especially with CRISPR/Cas9 - are making gene editing tools more reliable and accessible, broadening their use across multiple sectors.
Increasing Research and Development Investments
Substantial funding from both public and private sectors, along with collaborations between academia and industry, is accelerating innovation and the commercialization of new gene editing solutions.
Regulatory Support and Evolving Frameworks
Supportive and evolving regulatory environments in key regions are facilitating the safe and ethical integration of gene editing technologies, encouraging broader adoption and market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Gene Editing Tools Market?
What factors are driving the growth of the Gene Editing Tools Market?
What are the key segments within the Gene Editing Tools Market?
What are some challenges faced by the Gene Editing Tools Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Clustered Regularly Interspaced Short Palindromic Repeats (CRISPR/Cas9)
- 1.2.2 Zinc Finger Nucleases (ZFNs)
- 1.2.3 Transcription Activator-Like Effector Nucleases (TALENs)
- 1.2.4 Viral Systems
- 1.2.5 Transposon Systems
- 1.2.6 Others
- 1.3 By End User
- 1.3.1 Biotech and Pharma Companies
- 1.3.2 Contract Research Organizations
- 1.3.3 Academic and Research Institutes
- 1.3.4 Food
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Veterinary Medicine
- 1.4.2 Cell Line Engineering
- 1.4.3 Bioremediation
- 1.4.4 Food and Brewing Development
- 1.4.5 Food Waste Management
- 1.4.6 Bio-Sensing Development
- 1.4.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 677.76 million → 2032: USD 2,556.25 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Gene Editing Tools Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Gene Editing Tools Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Gene Editing Tools Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Gene Editing Tools Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Gene Editing Tools Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Gene Editing Tools Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Gene Editing Tools Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Gene Editing Tools Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 677.76 million → 2032: USD 2,556.25 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Gene Editing Tools Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Clustered Regularly Interspaced Short Palindromic Repeats (CRISPR/Cas9)
- 12.3.7.2 Zinc Finger Nucleases (ZFNs)
- 12.3.7.3 Transcription Activator-Like Effector Nucleases (TALENs)
- 12.3.7.4 Viral Systems
- 12.3.7.5 Transposon Systems
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Biotech and Pharma Companies
- 12.4.7.2 Contract Research Organizations
- 12.4.7.3 Academic and Research Institutes
- 12.4.7.4 Food
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Veterinary Medicine
- 12.5.7.2 Cell Line Engineering
- 12.5.7.3 Bioremediation
- 12.5.7.4 Food and Brewing Development
- 12.5.7.5 Food Waste Management
- 12.5.7.6 Bio-Sensing Development
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Gene Editing Tools End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Gene Editing Tools Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Gene Editing Tools Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Gene Editing Tools Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 CRISPR Therapeutics
- 18.4 Merck KGaA
- 18.5 Editas Medicine
- 18.6 Intellia Therapeutics
- 18.7 New England Biolabs
- 18.8 ERS Genomics
- 18.9 Takara Bio USA
- 18.10 GE Healthcare Dharmacon Inc.
- 18.11 Horizon Discovery Group plc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

