
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| General Aviation Engines Market Size 2024 | USD 71,930.12 Million |
| General Aviation Engines Market, CAGR | 8.60% |
| General Aviation Engines Market Size 2032 | USD 139,171.21 Million |
Market Overview:
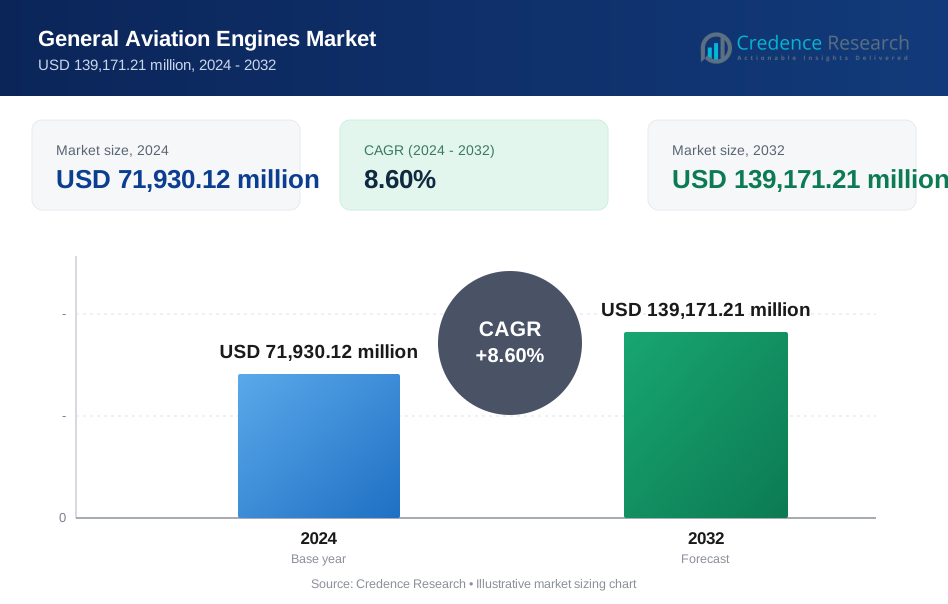
The general aviation engines market is poised for significant growth, with its market size projected to increase from USD 71,930.12 million in 2024 to USD 139,171.21 million by 2032, registering a compound annual growth rate (CAGR) of 8.60% over the forecast period. This growth is driven by the increasing demand for private aviation, rising air traffic for business purposes, and the expansion of the tourism industry. Additionally, the introduction of advanced engine technologies that enhance fuel efficiency, reduce emissions, and improve performance is further propelling market expansion. The ongoing trend towards modernization and upgrading of existing general aviation fleets, coupled with the growing popularity of light-sport and business jets, is also contributing to the robust growth of this market.
Key market drivers include the rising demand for fuel-efficient and environmentally friendly engines, driven by both regulatory pressures and consumer demand. The aviation industry is under increasing scrutiny to reduce its carbon footprint, leading to a surge in the development of engines that offer lower emissions and better fuel efficiency. Moreover, advancements in hybrid and electric propulsion technologies are expected to revolutionize the general aviation sector, offering more sustainable options for aircraft owners and operators. The growing interest in personal aviation, particularly in the post-pandemic era where there is a heightened emphasis on health and safety, is also fuelling demand for new aircraft and, consequently, new engines.
Regionally, North America dominates the general aviation engines market, accounting for a significant share of global revenue. This dominance is attributed to the region's well-established aviation infrastructure, high concentration of general aviation aircraft, and strong demand for business jets and private aircraft. The United States, in particular, leads the market due to its large fleet of general aviation aircraft and the presence of key industry players. Europe and Asia-Pacific are also key regions, with Europe focusing on sustainability and emissions reduction, while Asia-Pacific is witnessing rapid growth due to increasing wealth and expanding business aviation markets in countries like China and India. The Middle East and Africa are emerging regions, driven by growing investments in aviation infrastructure and the rising popularity of private aviation.
Market Drivers:
Demand for Fuel Efficiency and Emission Reduction:
The increasing focus on fuel efficiency and emission reduction is a significant driver in the general aviation engines market. The aviation industry is under growing pressure to minimize its environmental impact, leading to the development and adoption of more fuel-efficient engines. For instance, the U.S. Environmental Protection Agency (EPA) has implemented stringent emission standards for aircraft engines, prompting manufacturers to innovate and produce engines that meet these requirements. Companies like Rolls-Royce and Pratt & Whitney are leading the way by developing next-generation engines that offer improved fuel efficiency and reduced carbon emissions, aligning with global efforts to combat climate change.
Technological Advancements in Hybrid and Electric Propulsion:
Technological advancements in hybrid and electric propulsion are reshaping the general aviation sector. The push towards sustainable aviation has accelerated the development of hybrid and fully electric engines, which are seen as the future of aviation. For example, NASA’s X-57 Maxwell project aims to demonstrate the benefits of electric propulsion in general aviation, highlighting reduced operating costs and lower emissions. Similarly, companies like Pipistrel and Diamond Aircraft are pioneering electric aircraft engines, offering viable alternatives to traditional internal combustion engines. These innovations are crucial in addressing both environmental concerns and the rising costs of aviation fuel.
Increasing Demand for Private and Business Aviation:
The growing demand for private and business aviation is another key driver for the general aviation engines market. As global wealth increases, particularly in regions like Asia-Pacific and the Middle East, there is a rising demand for personal and business jets. This trend is supported by the need for flexible and convenient travel options, especially in the wake of the COVID-19 pandemic, which has heightened awareness around health, safety, and the benefits of private travel. For instance, Gulfstream and Bombardier have reported strong orders for business jets, driving the demand for high-performance engines that offer reliability and efficiency.
Modernization of General Aviation Fleets:
The ongoing modernization of general aviation fleets is driving the demand for new and upgraded engines. Many operators are investing in the replacement of older aircraft with newer models that feature advanced engines, offering better performance, lower maintenance costs, and compliance with modern environmental standards. Governments and regulatory bodies are also encouraging fleet modernization through incentives and updated regulations. For example, the Federal Aviation Administration (FAA) in the U.S. has introduced initiatives to promote the adoption of newer, more efficient aircraft, further boosting the demand for state-of-the-art engines in the general aviation market.
Market Trends:
Shift Towards Hybrid and Electric Engines:
A prominent trend in the general aviation engines market is the shift towards hybrid and electric engines. This transition is driven by the global push for sustainable aviation and the need to reduce dependency on fossil fuels. Companies like Pipistrel and magniX are at the forefront of developing electric propulsion systems, with several successful flight tests demonstrating the feasibility of these engines for general aviation. For instance, Pipistrel’s Velis Electro has become one of the first electric aircraft to receive type certification from the European Union Aviation Safety Agency (EASA), marking a significant milestone in the adoption of electric propulsion in aviation.
Emphasis on Noise Reduction Technologies:
Noise reduction has become a critical focus in the development of new general aviation engines. As airports and regulators impose stricter noise limits, manufacturers are investing in technologies that minimize engine noise without compromising performance. For example, Pratt & Whitney has introduced advanced fan designs and noise-reducing nacelles in their latest engine models to meet the stringent noise regulations of airports, particularly in urban areas. This trend aligns with broader efforts to reduce the environmental impact of aviation, making air travel more acceptable in noise-sensitive regions.
Adoption of Advanced Materials:
The use of advanced materials in engine construction is another key trend in the general aviation engines market. Manufacturers are increasingly using lightweight and heat-resistant materials, such as ceramic matrix composites (CMCs) and titanium alloys, to improve engine efficiency and durability. For instance, Rolls-Royce has incorporated CMCs into its latest engines to withstand higher temperatures, allowing for improved fuel efficiency and lower maintenance costs. This trend reflects the ongoing innovation in materials science, which is critical for the development of next-generation aviation engines.
Growth in Aftermarket Services:
The aftermarket services segment is experiencing significant growth as operators seek to extend the life of their existing engines and ensure compliance with new regulations. Engine manufacturers are expanding their maintenance, repair, and overhaul (MRO) services to meet this demand, offering tailored solutions that include predictive maintenance and digital twins. For example, GE Aviation has developed digital tools that allow operators to monitor engine health in real-time, enabling proactive maintenance and reducing downtime. This trend highlights the increasing importance of aftermarket services in maintaining engine performance and ensuring regulatory compliance in the general aviation sector.
Market Challenges Analysis:
High Development and Production Costs:
One of the primary restraints in the general aviation engines market is the high cost associated with the development and production of advanced engines. The process of designing, testing, and certifying new engine technologies, such as hybrid and electric propulsion systems, requires significant investment in research and development. Companies must also navigate the complex and costly process of meeting stringent regulatory standards imposed by aviation authorities like the Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA). These high costs can limit the ability of smaller manufacturers to compete and may slow down the adoption of innovative technologies in the market.
Stringent Regulatory Environment:
The general aviation engines market faces considerable challenges due to the stringent regulatory environment. Aviation authorities worldwide enforce rigorous safety, noise, and emissions standards, which require engine manufacturers to undergo extensive testing and certification processes. For example, achieving type certification for new engine designs can take several years and involve multiple iterations of testing to meet regulatory requirements. This regulatory burden can delay the introduction of new engines to the market, increase development costs, and pose significant barriers to entry for new players.
Technical Challenges in Adopting New Technologies:
The integration of new technologies, such as hybrid and electric propulsion systems, presents significant technical challenges for the general aviation engines market. These challenges include optimizing battery performance, ensuring reliability and safety, and integrating new propulsion systems with existing aircraft designs. Additionally, the current infrastructure, such as charging stations for electric aircraft, is not yet widely available, limiting the operational range and practicality of these new technologies. Overcoming these technical and infrastructure challenges will be critical for the widespread adoption of next-generation engines in the general aviation sector.
Economic Uncertainty and Market Volatility:
Economic uncertainty and market volatility also pose challenges for the general aviation engines market. Fluctuations in global economic conditions can impact the demand for new aircraft and, consequently, the demand for engines. During periods of economic downturn, investment in private aviation often decreases, leading to reduced orders for new engines and slower market growth. Additionally, the cyclical nature of the aviation industry means that the market is highly sensitive to changes in fuel prices, economic stability, and geopolitical factors, which can all affect the overall demand for general aviation engines.
Market Segmentation Analysis:
By Type
The general aviation engines market is segmented into turbofan, turboprop, turboshaft, and piston engines. Turbofan engines are widely used in business jets and regional aircraft due to their high efficiency and performance. Turboprop engines are preferred for short-haul flights and smaller aircraft, offering a balance between speed and fuel efficiency. Turboshaft engines are primarily used in helicopters, providing the necessary power and reliability. Piston engines, although less common, are still used in smaller, light aircraft for their simplicity and cost-effectiveness.
By Technology
Technological advancements are driving the growth of the general aviation engines market. Key technologies include conventional engines and hybrid engines. Conventional engines, which have been the industry standard for decades, continue to see improvements in fuel efficiency and emissions reduction. Hybrid engines, which combine traditional fuel-based propulsion with electric power, are gaining traction due to their potential for lower emissions and improved fuel efficiency.
By End User
The end users of the general aviation engines market include commercial aviation, military aviation, and recreational aviation. Commercial aviation, which encompasses business jets and regional airlines, is the largest segment, driven by the increasing demand for air travel and the need for efficient and reliable engines. Military aviation also represents a significant market, with engines used in various types of aircraft for defence and tactical operations. Recreational aviation, although smaller, is growing as more individuals and private entities invest in personal aircraft.
Segmentations:
By Technology
- Conventional Engine
- Electric/Hybrid Engine
By Type
- Platform
- Fixed Wing Aircraft
- Rotary Wing Aircraft
- Unmanned Ariel Vehicles
By Engine Type
- Turbofan
- Turboprop
- Turboshaft
- Piston
By Component
- Compressor
- Turbine
- Gearbox
- Exhaust System
- Fuel System
- Others
By End-user
- Commercial Aircraft
- Narrow-body Aircraft
- Wide-body Aircraft
- Business Jet
- General Aviation
- Helicopter
- Military Aircraft
- Fighter Aircraft
- Transport Aircraft
By Region
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the global general aviation engines market, accounting for approximately 40% of the total market. This dominance is primarily driven by the United States, which has the world’s largest general aviation fleet and a well-established aviation infrastructure. The presence of major engine manufacturers, such as Pratt & Whitney and General Electric Aviation, further strengthens the region’s leadership in the market. These companies are at the forefront of technological innovation, developing advanced engines that meet the stringent regulatory requirements set by the Federal Aviation Administration (FAA). Additionally, the high demand for business jets and private aircraft in the U.S. contributes significantly to the market’s growth, with a strong focus on enhancing fuel efficiency and reducing emissions.
Europe
Europe represents around 25% of the global market share, driven by its strong emphasis on sustainability and innovation in aviation. Countries like Germany, France, and the United Kingdom are key players in the region, with a robust aerospace industry and a commitment to developing environmentally friendly engine technologies. The European Union’s stringent emissions regulations, such as those enforced by the European Union Aviation Safety Agency (EASA), are pushing manufacturers to develop engines that offer lower emissions and better fuel efficiency. Companies like Rolls-Royce are leading the charge in this area, focusing on hybrid and electric propulsion systems that align with Europe’s broader goals of reducing the aviation sector’s environmental impact. The region’s strong regulatory framework and investment in research and development make it a significant contributor to the global market.
Asia-Pacific
Asia-Pacific accounts for approximately 20% of the global general aviation engines market and is the fastest-growing region. This growth is driven by the increasing wealth in countries like China and India, leading to a rising demand for private and business aviation. The expansion of the general aviation sector in these countries, coupled with significant investments in aviation infrastructure, is boosting the demand for advanced engines. China, in particular, is emerging as a key market, with government initiatives aimed at expanding its general aviation fleet and enhancing its manufacturing capabilities. The region’s focus on adopting the latest technologies and increasing the production of general aviation aircraft is expected to drive continued growth in the market.
Latin America, the Middle East, and Africa
Latin America, the Middle East, and Africa, holds approximately 15% of the global market share. These regions are witnessing emerging opportunities as governments and private sectors invest in aviation infrastructure and general aviation fleets. In the Middle East, countries like the United Arab Emirates and Saudi Arabia are investing heavily in private aviation, driven by the growing wealth and the need for business and luxury travel options. Latin America, with Brazil as a key player, is also expanding its general aviation sector, supported by economic growth and increasing demand for private aircraft. Africa, although currently a smaller market, is expected to see growth as infrastructure improves and general aviation becomes more accessible.
Key Player Analysis:
Top Key Players
- General Electric
- Rolls-Royce
- Safran
- Honeywell International Inc.
- Textron
- MTU Aero Engines
- Raytheon Technologies
- IHI Corporation
- Mitsubishi Heavy Industries (MHI)
- Lycoming Engines
Competitive Analysis:
The general aviation engines market is highly competitive, with several major players vying for market share through continuous innovation and technological advancements. Leading companies such as Pratt & Whitney, Rolls-Royce, and General Electric Aviation dominate the market with their extensive product portfolios, advanced R&D capabilities, and strong global presence. These companies focus on developing engines that meet the evolving demands for fuel efficiency, lower emissions, and enhanced performance. Additionally, emerging players like Safran and Honeywell Aerospace are intensifying competition by introducing innovative propulsion systems, including hybrid and electric engines, which are gaining traction as the industry shifts towards more sustainable aviation solutions. The competitive landscape is further shaped by strategic partnerships, mergers, and acquisitions, as companies seek to expand their technological capabilities and market reach, particularly in emerging markets across Asia-Pacific and the Middle East.
Recent Developments:
- In 2024, Pratt & Whitney made significant strides with its Hybrid-Electric Propulsion (HEP) flight demonstrator. The propulsion system, designed for a modified De Havilland Canada Dash 8-100 turboprop, successfully ran at full power. This system combines a 1-megawatt electric motor developed by Collins Aerospace with a fuel-burning engine specifically adapted for hybrid-electric operation. It aims to reduce fuel burn and CO2 emissions by up to 30%, representing a major advancement in sustainable aviation technologies.
- Rolls-Royce completed the first fuel burn of its new small gas turbine engine designed specifically for hybrid-electric flight in 2023. This engine, developed using novel combustion technology, is part of Rolls-Royce's broader efforts to support the aviation industry's move towards more sustainable power solutions, offering ultra-low emissions and setting a new standard for future hybrid-electric aircraft.
- In another 2023 development, Pratt & Whitney and Korean Air inducted the first GTF (Geared Turbofan) engine into service as part of their expanding MRO (Maintenance, Repair, and Overhaul) network. This milestone marks the 15th active location in their global network and reflects the company's commitment to increasing MRO capacity to support advanced engine technologies globally.
- Safran, in collaboration with other industry leaders, has been focusing on the development of hybrid-electric propulsion systems as part of the European Union's Clean Aviation initiative. This effort is aimed at optimizing aircraft efficiency across different phases of flight and is expected to play a significant role in reducing aviation's environmental footprint.
Market Concentration & Characteristics:
The general aviation engines market is moderately concentrated, with a few dominant players such as Pratt & Whitney, Rolls-Royce, and General Electric Aviation leading the market. These companies leverage their extensive R&D capabilities, advanced technology portfolios, and strong global distribution networks to maintain their competitive positions. The market is characterized by high barriers to entry, primarily due to the significant capital investment required for engine development, certification, and compliance with stringent regulatory standards. Additionally, the ongoing shift towards sustainable aviation solutions, including hybrid and electric propulsion systems, is driving innovation within the market. Despite the dominance of these established players, emerging companies and new technologies are gradually entering the market, adding a layer of dynamism and competition, particularly in the areas of sustainability and efficiency.
Report Coverage:
The research report offers an in-depth analysis based on Technology, Type, Engine Type, and Component. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The general aviation engines market will see increased adoption of hybrid and electric propulsion systems as the industry prioritizes sustainability.
- Ongoing advancements in materials science will lead to the development of lighter, more efficient engines.
- Regulatory pressures to reduce emissions will drive innovation in low-emission engine technologies.
- Aftermarket services, including maintenance and repair, will grow in importance as operators seek to extend the lifespan of existing engines.
- The market will experience heightened competition as new entrants introduce innovative propulsion solutions.
- The demand for engines in business and private aviation will increase, particularly in emerging markets such as Asia-Pacific.
- Technological integration, including digital engine monitoring systems, will become standard to enhance engine performance and reliability.
- The expansion of urban air mobility (UAM) solutions will create new opportunities for engine manufacturers.
- Collaborations and partnerships between aerospace companies will accelerate the development of next-generation engines.
- Investment in research and development will remain a priority as manufacturers seek to meet evolving market demands and regulatory requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Fuel Efficiency and Emission Reduction
Stringent environmental regulations and consumer expectations are pushing manufacturers to develop engines with lower emissions and higher fuel efficiency, driving innovation and adoption of advanced propulsion technologies.
Technological Advancements in Hybrid and Electric Propulsion
The push for sustainable aviation is accelerating the development and integration of hybrid and electric engines, which offer reduced operating costs and emissions, making them increasingly attractive for general aviation applications.
Increasing Demand for Private and Business Aviation
Rising global wealth, especially in Asia-Pacific and the Middle East, is fueling demand for private and business jets, which in turn increases the need for new, high-performance general aviation engines.
Modernization of General Aviation Fleets
Operators are replacing older aircraft with newer models equipped with advanced engines to improve performance, reduce maintenance costs, and comply with updated environmental standards, boosting engine sales.
Growth in Aftermarket Services
As operators seek to extend the lifespan and reliability of their existing engines, demand for maintenance, repair, and overhaul services is rising, supporting ongoing market growth and recurring revenue streams for engine manufacturers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the General Aviation Engines Market?
What factors are driving the growth of the General Aviation Engines Market?
What are some challenges faced by the General Aviation Engines Market?
Who are the major players in the General Aviation Engines Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Platform
- 1.2.1 Fixed Wing Aircraft
- 1.2.2 Rotary Wing Aircraft
- 1.2.3 Unmanned Aerial Vehicles
- 1.3 By Component
- 1.3.1 Compressor
- 1.3.2 Turbine
- 1.3.3 Gearbox
- 1.3.4 Exhaust System
- 1.3.5 Fuel System
- 1.3.6 Others
- 1.4 By Technology
- 1.4.1 Conventional Engine
- 1.4.2 Electric/Hybrid Engine
- 1.5 By Engine Type
- 1.5.1 Turbofan
- 1.5.2 Turboprop
- 1.5.3 Turboshaft
- 1.5.4 Piston
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 71,930.12 million → 2032: USD 139,171.21 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global General Aviation Engines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global General Aviation Engines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global General Aviation Engines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global General Aviation Engines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global General Aviation Engines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global General Aviation Engines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global General Aviation Engines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global General Aviation Engines Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 71,930.12 million → 2032: USD 139,171.21 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global General Aviation Engines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Platform - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fixed Wing Aircraft
- 12.3.7.2 Rotary Wing Aircraft
- 12.3.7.3 Unmanned Aerial Vehicles
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Compressor
- 12.4.7.2 Turbine
- 12.4.7.3 Gearbox
- 12.4.7.4 Exhaust System
- 12.4.7.5 Fuel System
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Conventional Engine
- 12.5.7.2 Electric/Hybrid Engine
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Engine Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Turbofan
- 12.6.7.2 Turboprop
- 12.6.7.3 Turboshaft
- 12.6.7.4 Piston
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global General Aviation Engines Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global General Aviation Engines Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global General Aviation Engines Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 General Electric
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Rolls-Royce
- 17.4 Safran
- 17.5 Honeywell International Inc.
- 17.6 Textron
- 17.7 MTU Aero Engines
- 17.8 Raytheon Technologies
- 17.9 IHI Corporation
- 17.10 Mitsubishi Heavy Industries
- 17.11 Lycoming Engines
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

