
Market Overview:
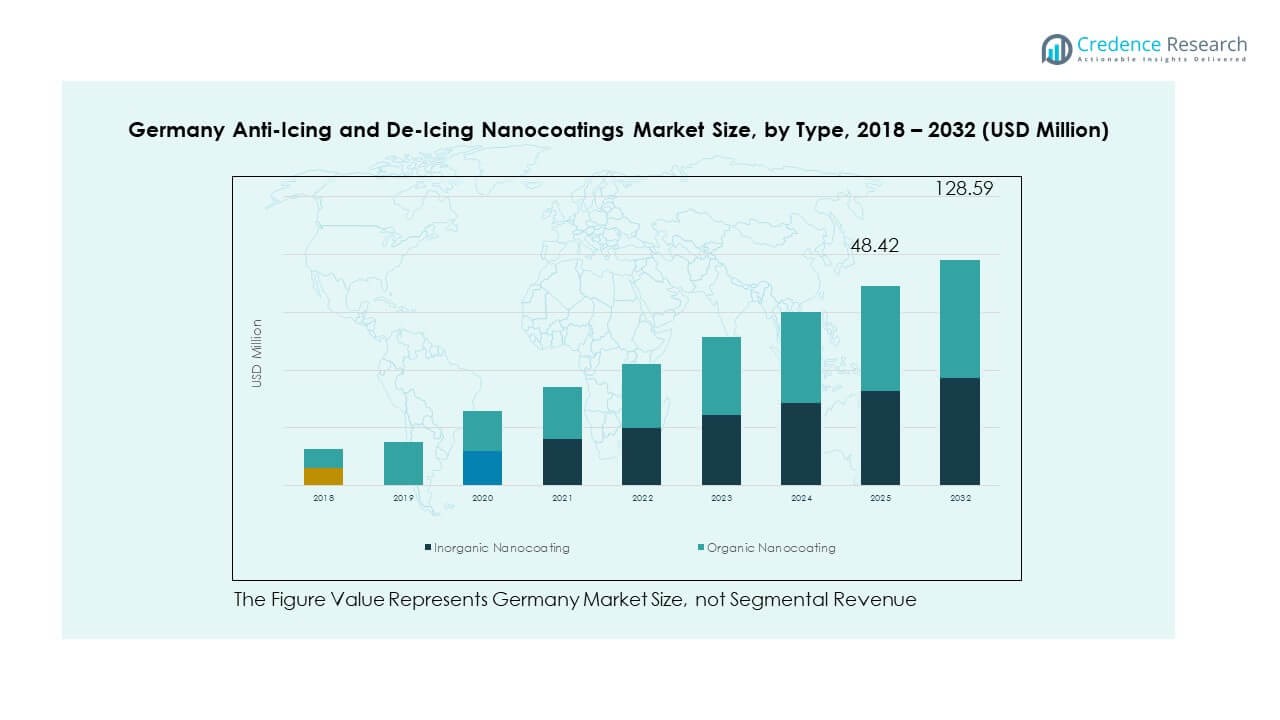
The Germany Anti-Icing and De-Icing Nanocoatings Market size was valued at USD 18.31 million in 2018 to USD 42.41 million in 2024 and is anticipated to reach USD 128.59 million by 2032, at a CAGR of 15.0% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany Anti-Icing and De-Icing Nanocoatings Market Size 2024 | USD 42.41 Million |
| Germany Anti-Icing and De-Icing Nanocoatings Market, CAGR | 15.0% |
| Germany Anti-Icing and De-Icing Nanocoatings Market Size 2032 | USD 128.59 Million |
Growth in the market is driven by rising demand for advanced coatings across aviation, transportation, and renewable energy sectors. Germany’s strong aerospace industry is integrating nanocoatings to improve safety and efficiency by reducing ice formation on aircraft surfaces. Wind energy projects in colder regions also increasingly adopt these solutions to enhance turbine performance and reduce downtime. The automotive sector further supports adoption by applying nanocoatings to vehicles, ensuring operational reliability during harsh winters.
Geographically, Germany holds a leading role in the European market due to its advanced industrial base and emphasis on innovation. Neighboring countries in Northern and Eastern Europe are emerging as growth hubs, particularly due to their exposure to severe winter conditions and expanding renewable energy installations. Western Europe continues to lead in adoption because of its mature aerospace and automotive sectors, while Nordic countries represent high-potential markets driven by strong wind energy deployment and infrastructure investments.
Market Insights:
- The Germany Anti-Icing and De-Icing Nanocoatings Market was valued at USD 18.31 million in 2018, grew to USD 42.41 million in 2024, and is projected to reach USD 128.59 million by 2032, registering a CAGR of 15.0%.
- Southern Germany led with 38% share in 2024, driven by its aerospace, automotive, and renewable energy hubs; Northern Germany followed with 27% share due to offshore wind capacity and logistics; Western and Eastern Germany together held 35% share, supported by infrastructure and industrial applications.
- Northern Germany is the fastest-growing region with 27% share, fueled by expansion of offshore wind farms, maritime industries, and port-related infrastructure.
- In 2024, inorganic nanocoatings accounted for 55% share of the Germany Anti-Icing and De-Icing Nanocoatings Market, reflecting strong adoption in aerospace, energy, and defense sectors.
- Organic nanocoatings captured 45% share in 2024, supported by demand in textiles, electronics, and packaging where flexibility and cost-effectiveness are key drivers.
Market Drivers
Strong adoption of nanocoatings across Germany’s aerospace and aviation industry to improve safety and operational reliability
The aviation sector in Germany drives strong demand for anti-icing and de-icing nanocoatings due to strict safety requirements. Airlines and aerospace manufacturers deploy advanced nanocoatings to minimize ice accumulation on aircraft surfaces during cold-weather operations. This innovation reduces risks of flight delays and cancellations linked to ice buildup. It also improves energy efficiency by limiting de-icing fluid usage, which aligns with sustainability goals. German aerospace companies actively invest in surface engineering technologies to enhance product reliability. Government and EU aviation safety standards further encourage widespread adoption. The Germany Anti-Icing and De-Icing Nanocoatings Market benefits from strong support by aviation regulators and operators. It ensures reliable performance under Europe’s challenging winter climate conditions.
- For example, German research institutes, such as Fraunhofer IGB, have developed nanostructured superhydrophobic coatings that reduce ice adhesion on surfaces by over 90% compared to uncoated materials.
Expanding renewable energy projects in Germany driving adoption of nanocoatings for wind turbine performance improvement
Germany’s renewable energy sector fuels market expansion with heavy reliance on wind power. Wind turbine blades in colder regions face ice-related losses, reducing energy efficiency and causing mechanical stress. Nanocoatings applied to turbine surfaces reduce ice formation, ensuring steady power output. Energy companies adopt these coatings to extend turbine lifespan and cut maintenance costs. The government’s focus on clean energy and emission targets supports large-scale wind energy deployment. Ice-resistant turbine blades improve reliability of offshore and onshore wind farms in extreme weather. The Germany Anti-Icing and De-Icing Nanocoatings Market gains momentum from strong renewable energy adoption. It reflects Germany’s leadership in renewable technology and energy transition.
Increasing demand in automotive applications to improve winter performance and ensure reliable mobility in cold conditions
The automotive sector contributes to market growth by using nanocoatings for improved safety. Vehicles equipped with ice-resistant coatings experience fewer disruptions in winter operations. German automakers integrate nanocoatings in premium vehicles to deliver advanced safety features. Ice-prevention solutions for windshields, mirrors, and sensors support the rise of autonomous and electric vehicles. These features enhance driver safety and ensure consistent performance in extreme winter conditions. Rising consumer expectations for durable and weather-resistant vehicles increase adoption of these technologies. The Germany Anti-Icing and De-Icing Nanocoatings Market leverages strong automotive innovation and manufacturing capabilities. It highlights Germany’s advanced approach to automotive safety and reliability.
- For example, Hydrophobic and superhydrophobic nanocoatings have shown in lab tests the ability to reduce ice adhesion into the single- to tens-kPa range, with some advanced coatings achieving ultra-low values close to 1–2 kPa.
Growing focus on infrastructure resilience to ensure reliable operations during harsh winter conditions
Infrastructure development projects in Germany adopt nanocoatings to safeguard transport networks and public assets. Bridges, railway systems, and power lines face severe challenges from ice accumulation during winter. Nanocoatings extend material durability, reduce operational disruptions, and limit costly maintenance. Public sector investments in modernizing transportation networks boost demand for these advanced solutions. The construction sector integrates nanocoatings into surfaces requiring long-term resistance against ice damage. The Germany Anti-Icing and De-Icing Nanocoatings Market benefits from infrastructure policies supporting smart and sustainable development. It positions nanocoatings as a long-term solution for climate resilience. Urban planners and engineers adopt these solutions to reduce risks from weather extremes.
Market Trends
Rising integration of nanocoatings into defense and military applications for advanced operational readiness
Germany’s defense sector explores nanocoatings to improve equipment reliability in extreme environments. Military vehicles, aircraft, and naval systems require coatings to prevent ice buildup and maintain efficiency. The defense industry values durability, precision, and reduced maintenance needs in harsh climates. Advanced coatings improve mission readiness by preventing disruptions during cold-weather operations. Research institutions collaborate with defense contractors to advance specialized nanocoating solutions. The Germany Anti-Icing and De-Icing Nanocoatings Market benefits from government defense budgets that emphasize technology upgrades. It showcases the alignment of coatings innovation with national security needs. Long-term adoption ensures consistent growth within the defense segment.
Increasing application of nanocoatings in electronics and consumer goods to support weather-resistant product development
Electronics and consumer goods industries integrate nanocoatings to improve product durability against frost and moisture. Smartphones, sensors, and outdoor devices require protection for reliable performance in low temperatures. Nanocoatings reduce risks of malfunction, ensuring longer product lifecycles. German electronics firms invest in research to deliver products that withstand extreme climates. Consumer demand for weather-resistant wearables and gadgets supports this adoption. The Germany Anti-Icing and De-Icing Nanocoatings Market gains traction by diversifying into electronics. It highlights the transition of coatings from industrial to consumer-focused applications. Manufacturers view nanocoatings as a competitive advantage in global markets.
- For example, Actnano opened its Munich Center of Excellence in 2022 to support European clients. Its Advanced nanoGUARD nanocoating protects electronics in millions of vehicles and extends to consumer devices like phones, headphones, and wearables.
Growing collaboration between industry and research institutions to accelerate innovation and product customization
Germany fosters collaboration among universities, research institutes, and industry leaders to advance nanocoating applications. Joint projects accelerate innovation, testing, and scalability of new materials. Customized nanocoating solutions emerge for specific sectors such as aerospace, energy, and transportation. Partnerships ensure faster commercial adoption and technology transfer. Public research funding enhances innovation pipelines across German industries. The Germany Anti-Icing and De-Icing Nanocoatings Market strengthens through collaborative ecosystems. It reflects Germany’s strong focus on research-led industrial progress. These alliances expand the scope of nanocoating technologies beyond traditional applications.
- For example, the Centre for Nanointegration Duisburg-Essen (CENIDE) and the University of Duisburg-Essen host the €46 million NanoEnergy Technology Centre. This facility supports both fundamental and applied nanotechnology research across multiple fields.
Increasing influence of sustainability goals driving eco-friendly nanocoating formulations across industrial applications
Sustainability goals shape material development strategies in the coatings industry. Manufacturers design eco-friendly nanocoatings that reduce reliance on chemical de-icing agents. These solutions align with EU regulations promoting green technologies. Companies adopt water-based and biodegradable formulations to reduce environmental impact. The Germany Anti-Icing and De-Icing Nanocoatings Market embraces innovation that balances performance with sustainability. It demonstrates Germany’s leadership in responsible industrial practices. Growing corporate and consumer awareness supports greener product adoption. Regulatory frameworks push the coatings sector to meet higher environmental standards.
Market Challenges Analysis
High production costs and scalability issues limiting widespread adoption of nanocoatings across end-use industries
The industry faces high production costs linked to advanced nanomaterial synthesis. Expensive manufacturing processes restrict large-scale adoption by mid-tier companies. Limited economies of scale slow down broader commercial deployment across industries. German firms struggle with balancing performance benefits and affordability in mass-market applications. High initial costs hinder adoption in sectors like automotive and consumer electronics. The Germany Anti-Icing and De-Icing Nanocoatings Market experiences delays in achieving cost competitiveness. It requires further R&D investments to improve production efficiency and cost control. Pricing challenges remain a critical barrier to expansion.
Stringent regulatory compliance and performance validation requirements creating barriers for new entrants and smaller firms
Nanocoatings face strict EU regulations regarding chemical composition and environmental impact. Compliance with these standards requires extensive testing and certification. Startups and smaller firms encounter financial and technical hurdles to meet compliance demands. Proving long-term performance in varied environmental conditions slows commercialization timelines. Certification delays increase time-to-market for innovative products. The Germany Anti-Icing and De-Icing Nanocoatings Market is shaped by regulatory oversight ensuring product safety. It creates a challenging entry path for new players seeking growth. Regulatory hurdles intensify the need for large-scale R&D collaboration.
Market Opportunities
Expansion of nanocoating applications into new industrial sectors creating untapped opportunities for innovation and growth
Nanocoatings are moving beyond aerospace and energy into new industrial domains. Healthcare, textiles, and logistics sectors explore nanocoatings for frost-resistant solutions. Textile firms adopt coatings for outdoor apparel with advanced ice-repellent performance. Logistics operators consider coatings for vehicles and containers to prevent weather-related delays. The Germany Anti-Icing and De-Icing Nanocoatings Market captures growth by diversifying into non-traditional industries. It strengthens its base through innovations tailored to unique needs. Future adoption may extend toward healthcare devices requiring frost-resistant properties. This diversification ensures sustained demand across multiple verticals.
Rising export potential for German nanocoating technologies in global markets with cold climate conditions
German firms hold strong opportunities to expand exports of nanocoating solutions. Countries with severe winters such as Canada, Russia, and Nordic regions represent high-demand markets. German manufacturers enjoy competitive advantages with advanced R&D and quality standards. The Germany Anti-Icing and De-Icing Nanocoatings Market leverages Germany’s strong export-oriented industrial base. It demonstrates international potential as climate challenges expand globally. Export growth creates stronger revenue streams for German suppliers. Partnerships with global aerospace and energy firms boost visibility of German innovations. The opportunity enhances Germany’s role as a global nanocoatings leader.
Market Segmentation Analysis:
By type, the Germany Anti-Icing and De-Icing Nanocoatings Market is divided into inorganic and organic coatings. Inorganic nanocoatings hold strong adoption due to their durability, chemical resistance, and ability to perform under extreme conditions. They are widely applied in aerospace, wind energy, and defense sectors where long-term reliability is essential. Organic nanocoatings gain traction for their flexibility, lightweight nature, and cost-effectiveness. They are preferred in consumer-oriented industries such as textiles, packaging, and electronics where ease of application and adaptability are valued. Both categories support innovation in performance and sustainability.
- For example, research indicates that ZnO nanoparticles especially those produced via green synthesis can impart antimicrobial and UV protection to textiles.
By application, transportation remains a dominant segment, driven by demand in aviation, automotive, and railways to reduce ice accumulation and improve safety. The energy sector follows with strong uptake in wind power projects, especially in colder regions, to ensure reliable turbine operation. Textiles show rising adoption through weather-resistant fabrics for outdoor wear and protective gear. Electronics benefit from coatings that shield sensitive sensors and components from frost and moisture damage. Food and packaging industries apply nanocoatings for extended product life and resistance to harsh storage conditions. Other applications, including infrastructure and logistics, reflect growing interest in surface protection. The Germany Anti-Icing and De-Icing Nanocoatings Market demonstrates broad application potential across industrial and consumer sectors, driven by performance needs and climate challenges.
- For instance, research in aviation explores nanocoatings for reducing drag, improving efficiency, and enhancing safety, with potential applications extending to automotive sectors.
Segmentation:
By Type
- Inorganic Nanocoating
- Organic Nanocoating
By Application
- Transportation
- Textiles
- Energy
- Electronics
- Food & Packaging
- Others
Regional Analysis:
Southern Germany holds 38% share of the Germany Anti-Icing and De-Icing Nanocoatings Market, driven by its strong automotive and aerospace hubs in Bavaria and Baden-Württemberg. These regions integrate nanocoatings to improve safety and performance across high-value industries. Wind energy deployment in Bavaria further supports adoption for turbine blades exposed to cold climates. Strong collaborations with research institutes in Munich and Stuttgart advance coating innovations and commercialization. The industrial strength of Southern Germany ensures consistent demand across both consumer and industrial applications. It benefits from a mix of manufacturing expertise and R&D intensity, making the region a leader in market adoption.
Northern Germany accounts for 27% share, with demand largely supported by the presence of offshore and onshore wind farms in Schleswig-Holstein and Lower Saxony. The ports of Hamburg and Bremen serve as gateways for export and logistics activities, creating opportunities for infrastructure coatings. Aerospace maintenance and maritime industries in this subregion adopt nanocoatings to improve resilience against harsh winter conditions. Universities and research clusters in Hamburg contribute to material testing and field validation. The Germany Anti-Icing and De-Icing Nanocoatings Market in this region reflects strong ties between renewable energy, logistics, and industrial applications. It highlights Northern Germany as a hub for sustainable technology adoption.
Western and Eastern Germany together represent 35% share, with applications spread across transportation, energy, and industrial infrastructure. Western Germany benefits from its industrial base in North Rhine-Westphalia, where coatings are applied to vehicles, bridges, and rail networks. Eastern Germany demonstrates rising adoption through renewable energy projects, particularly wind installations in Brandenburg and Saxony-Anhalt. Research institutions in Berlin foster innovation and partnerships with coating developers. It strengthens product testing and accelerates technology transfer into practical use cases.
Key Player Analysis:
- Battelle
- AkzoNobel
- Fraunhofer
- Hygratek
- NanoSonic
- Luna Innovations
- Nanovere Technologies
- NEI Corporation
- Cytonix
- Other Key Players
Competitive Analysis:
The Germany Anti-Icing and De-Icing Nanocoatings Market features a mix of global corporations, specialized coating firms, and research-driven organizations. Leading players such as AkzoNobel, Battelle, and Fraunhofer strengthen their position through extensive R&D capabilities and strong partnerships with aerospace, automotive, and energy industries. Companies such as NanoSonic, NEI Corporation, and Nanovere Technologies focus on niche innovations, delivering tailored solutions for defense, wind energy, and electronics applications. Competitive strategies often revolve around new product launches, advanced material formulations, and sustainability-driven coatings that align with EU regulations. It reflects a highly innovation-oriented competitive landscape with emphasis on performance validation and compliance. The market demonstrates a balance between established multinationals and emerging technology firms. Larger corporations leverage their financial strength and distribution networks to dominate in high-demand sectors such as aviation and energy. Smaller firms target specialized applications and build competitive advantage through agility and customization. The Germany Anti-Icing and De-Icing Nanocoatings Market experiences continuous collaborations between universities, research institutions, and private companies, ensuring faster innovation cycles. It highlights strong competition focused on technological leadership, product differentiation, and global expansion opportunities. Strategic mergers, acquisitions, and partnerships remain central in shaping the market’s competitive direction.
Recent Developments:
- In February 2025, PPG introduced its non-BPA HOBA Pro 2848 coatings for aluminum bottles at Paris Packaging Week, reinforcing its commitment to sustainable and innovative coating solutions while strengthening its position in advanced coatings markets.
- In January 2025, a Riga-based nanocoating startup, Naco Technologies, secured €1.5 million in a pre-Series A funding round co-led by Radix Ventures. It will use the funding to build a production facility in Poland and accelerate its international expansion, especially for coatings that improve hydrogen production efficiency.
- In October 2024, PPG announced a strategic portfolio shift by agreeing to sell its US and Canada architectural coatings business to American Industrial Partners, with the deal expected to close by early 2025. The move allows PPG to redirect resources toward high-growth segments such as advanced coatings, including anti-icing nanocoatings designed for Nordic climates.
Report Coverage:
The research report offers an in-depth analysis based on Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Germany Anti-Icing and De-Icing Nanocoatings Market is expected to expand with wider aerospace adoption to enhance flight safety and operational reliability.
- Growing reliance on renewable energy will increase the use of nanocoatings in wind turbines to prevent ice-related performance losses.
- Automotive manufacturers are likely to accelerate integration of nanocoatings for windshields, mirrors, and sensors to support advanced mobility solutions.
- Expansion of infrastructure modernization projects will create consistent demand for coatings on bridges, railways, and public transport networks.
- Defense and military sectors will invest in specialized coatings to ensure equipment durability and mission readiness in cold climates.
- Consumer electronics and wearable devices will adopt frost-resistant coatings, supporting product longevity and enhanced user experience.
- The market will witness stronger collaboration between German research institutes and industry leaders to drive material innovations.
- Eco-friendly nanocoating formulations will gain preference, aligning with EU regulations and Germany’s sustainability objectives.
- Export opportunities will grow as German suppliers expand their footprint in regions facing severe winter challenges.
- Competitive intensity will rise, with both large corporations and smaller innovators pursuing differentiation through technology and customization.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aerospace and Aviation Safety Requirements
Germany's robust aerospace sector is rapidly adopting anti-icing and de-icing nanocoatings to meet strict safety standards, reduce ice accumulation on aircraft, and improve operational reliability during harsh winters.
Expansion of Renewable Energy, Especially Wind Power
The growth of wind energy projects in colder German regions drives demand for nanocoatings that prevent ice buildup on turbine blades, ensuring consistent power generation and reducing maintenance costs.
Automotive Sector Innovation for Winter Performance
German automakers are integrating nanocoatings into vehicles to enhance safety and reliability in winter conditions, supporting advanced features for autonomous and electric vehicles and meeting rising consumer expectations.
Infrastructure Modernization and Resilience
Public and private investments in modernizing transport and energy infrastructure are increasing the use of nanocoatings to protect bridges, railways, and power lines from ice-related damage and operational disruptions.
Sustainability and Regulatory Compliance
EU and German regulations promoting eco-friendly, low-impact materials are accelerating the development and adoption of sustainable nanocoating formulations, reducing reliance on chemical de-icers and aligning with national climate goals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Germany Anti-Icing and De-Icing Nanocoatings Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Germany Anti-Icing and De-Icing Nanocoatings Market projected to grow between 2024 and 2032?
Which Germany Anti-Icing and De-Icing Nanocoatings Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Germany Anti-Icing and De-Icing Nanocoatings Market?
Who are the leading companies in the Germany Anti-Icing and De-Icing Nanocoatings Market?
Which region commanded the largest share of the Germany Anti-Icing and De-Icing Nanocoatings Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Inorganic Nanocoating
- 1.2.2 Organic Nanocoating
- 1.3 By Application
- 1.3.1 Transportation
- 1.3.2 Energy
- 1.3.3 Textiles
- 1.3.4 Electronics
- 1.3.5 Food & Packaging
- 1.3.6 Others
- 1.4 By End-Use Industry
- 1.4.1 Aerospace & Aviation
- 1.4.2 Automotive
- 1.4.3 Renewable Energy
- 1.4.4 Defense & Military
- 1.4.5 Consumer Goods & Electronics
- 1.4.6 Infrastructure & Construction
- 1.5 By Region (Germany)
- 1.5.1 Southern Germany
- 1.5.2 Northern Germany
- 1.5.3 Western Germany
- 1.5.4 Eastern Germany
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 42.41 million → 2032: USD 128.59 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Germany Anti-Icing and De-Icing Nanocoatings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Germany Anti-Icing and De-Icing Nanocoatings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Germany Anti-Icing and De-Icing Nanocoatings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Germany Anti-Icing and De-Icing Nanocoatings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Germany Anti-Icing and De-Icing Nanocoatings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Germany Anti-Icing and De-Icing Nanocoatings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Germany Anti-Icing and De-Icing Nanocoatings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Germany Anti-Icing and De-Icing Nanocoatings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 42.41 million → 2032: USD 128.59 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Germany Anti-Icing and De-Icing Nanocoatings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Inorganic Nanocoating
- 12.3.7.2 Organic Nanocoating
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Transportation
- 12.4.7.2 Energy
- 12.4.7.3 Textiles
- 12.4.7.4 Electronics
- 12.4.7.5 Food & Packaging
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Aerospace & Aviation
- 12.5.7.2 Automotive
- 12.5.7.3 Renewable Energy
- 12.5.7.4 Defense & Military
- 12.5.7.5 Consumer Goods & Electronics
- 12.5.7.6 Infrastructure & Construction
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Region (Germany) - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Southern Germany
- 12.6.7.2 Northern Germany
- 12.6.7.3 Western Germany
- 12.6.7.4 Eastern Germany
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Germany Anti-Icing and De-Icing Nanocoatings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Germany Anti-Icing and De-Icing Nanocoatings Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Germany Anti-Icing and De-Icing Nanocoatings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Germany Anti-Icing and De-Icing Nanocoatings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AkzoNobel
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Battelle
- 18.4 Fraunhofer
- 18.5 PPG Industries
- 18.6 NanoSonic
- 18.7 NEI Corporation
- 18.8 Nanovere Technologies
- 18.9 Cytonix
- 18.10 Hygratek
- 18.11 Actnano
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

