
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Germany Interior Design Market Size 2023 | USD 8,887.25 million |
| Germany Interior Design Market, CAGR | 4.97% |
| Germany Interior Design Market Size 2032 | USD 13,764.17 million |
Market Overview:
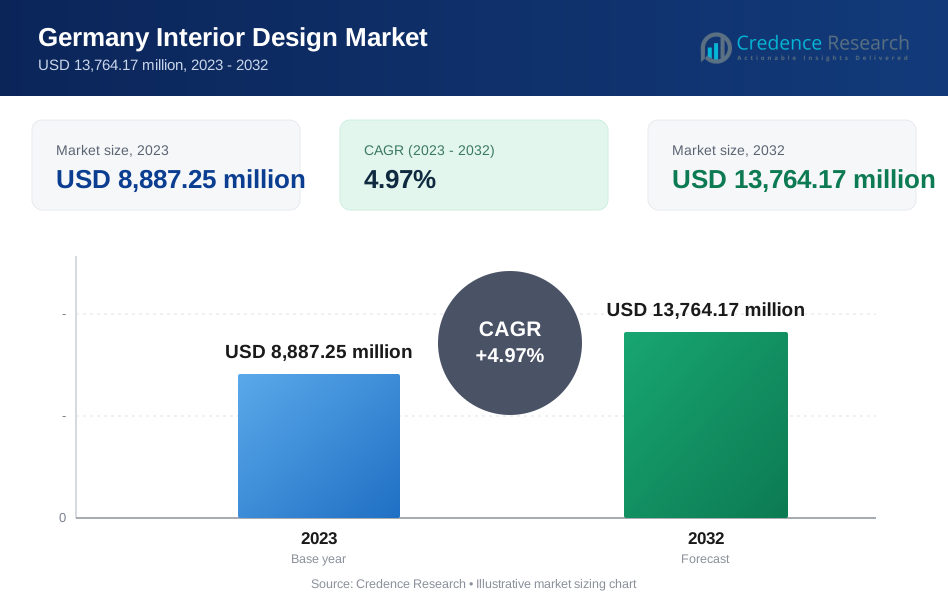
Germany Interior Design Market size was valued at USD 8,887.25 million in 2023 and is anticipated to reach USD 13,764.17 million by 2032, at a CAGR of 4.97% during the forecast period (2023-2032).
Several factors contribute to the expansion of the interior design market in Germany. The real estate sector's growth, driven by rising investments in residential, commercial, and hospitality spaces, significantly boosts demand for interior design services. The shift towards sustainable and eco-friendly interiors is also a major trend, with consumers and businesses opting for energy-efficient lighting, recycled materials, and green building certifications. Additionally, the increasing influence of digitalization and virtual interior designing solutions is transforming the market, enabling consumers to visualize and customize their spaces using 3D modeling and virtual reality (VR) technology. The demand for luxury and high-end interior solutions is further amplified by a rising affluent consumer base willing to invest in premium furnishings and design expertise.
Germany's interior design market is concentrated in key metropolitan regions, including Berlin, Munich, Hamburg, and Frankfurt, where high-income populations and corporate expansions fuel demand. Berlin, known for its modern and contemporary designs, leads in innovation and artistic interior concepts. Munich and Hamburg, with their affluent populations, showcase strong demand for luxury interior solutions, particularly in residential and commercial real estate. Frankfurt, a major financial hub, witnesses growing demand for corporate interior designs, emphasizing functionality, aesthetics, and brand representation. Additionally, regions like Baden-Württemberg and North Rhine-Westphalia are emerging as strong markets due to increased urbanization and residential development. The presence of skilled interior designers, architecture firms, and high-end furniture manufacturers further strengthens Germany’s position as a leading European market for interior design.
Market Insights:
- The Germany interior design market was valued at USD 8,887.25 million in 2023 and is projected to reach USD 13,764.17 million by 2032, growing at a CAGR of 4.97% during the forecast period.
- The real estate boom in cities like Berlin, Munich, Hamburg, and Frankfurt is driving demand for high-quality, functional, and aesthetically appealing interiors across residential, commercial, and hospitality sectors.
- Sustainability and smart home integration are transforming the market, with consumers opting for eco-friendly materials, energy-efficient lighting, and smart automation to align with Germany’s strong environmental regulations.
- Technological advancements, including 3D visualization, virtual reality (VR), and augmented reality (AR), are revolutionizing the industry, allowing designers and clients to visualize interiors before execution.
- The luxury interior segment is expanding, particularly in Munich and Hamburg, where high-net-worth individuals invest in premium furnishings, bespoke designs, and exclusive materials.
- Challenges such as high costs, skilled labor shortages, and regulatory compliance impact market growth, making luxury interiors less accessible to middle-income consumers.
- Berlin leads in contemporary and innovative designs (25% market share), Munich dominates the luxury interior segment (30%), while Frankfurt and Hamburg see growing demand for corporate and residential interiors.
Market Drivers:
Growing Real Estate and Construction Sector
Germany's interior design market is witnessing significant growth, primarily fueled by the expansion of the real estate and construction industries. Rapid urbanization and increasing investments in residential, commercial, and hospitality projects are driving the demand for interior design services. As homeownership rates rise and businesses expand their office spaces, there is a growing emphasis on well-designed, functional, and aesthetically appealing interiors. Developers and property owners are increasingly recognizing the value of high-quality interior solutions in enhancing property appeal, marketability, and overall user experience. The rising trend of luxury real estate and premium housing further accelerates the demand for exclusive interior designs, reinforcing the market's upward trajectory. . For instance, the German Design Award 2024 recognized projects like the "Villa Luxemburg" by Bernd Gruber Kitzbühel, showcasing exceptional interior architecture that aligns with the trend towards luxury and customization
Rising Consumer Preference for Sustainable and Smart Interiors
Sustainability and smart home integration are reshaping the interior design landscape in Germany. Consumers are actively seeking eco-friendly materials, energy-efficient lighting, and sustainable furniture to reduce their environmental footprint. For instance, the demand for green building certifications, such as LEED and DGNB, has encouraged interior designers to incorporate sustainable design principles into their projects. Additionally, the rapid advancement of smart home technology is influencing interior design choices, with homeowners integrating automation systems, intelligent lighting, and energy-efficient appliances into their spaces. This convergence of sustainability and technology not only enhances functionality but also aligns with Germany’s strong commitment to environmental responsibility and innovation.
Technological Advancements in Interior Design
Digital transformation is revolutionizing the interior design sector in Germany, with innovative tools such as 3D visualization, augmented reality (AR), and virtual reality (VR) playing a crucial role in the design process. These technologies allow designers and clients to create and visualize interiors in a virtual environment before execution, minimizing errors and enhancing efficiency. AI-driven design solutions are also gaining traction, offering data-driven insights and personalized design recommendations based on consumer preferences. For instance, HOMEE AI introduced the world's first AI interior designer at CES 2024, utilizing spatial computing technology to allow users to scan and redesign rooms in 3D with real-time adjustments. The rise of e-commerce platforms for furniture and decor is further streamlining the design process, enabling designers and consumers to access a wide range of products and materials with greater convenience. The adoption of digital solutions is improving customer engagement, reducing project timelines, and optimizing resource utilization, making interior design more accessible and cost-effective.
Increasing Demand for Customized and Luxury Interiors
Germany’s interior design market is also driven by a growing preference for personalized and high-end interior solutions. Consumers, particularly in urban centers such as Berlin, Munich, and Hamburg, are increasingly investing in bespoke furniture, premium materials, and unique design elements that reflect their personal tastes and lifestyles. Luxury brands and design studios are responding to this demand by offering exclusive, tailor-made solutions that cater to affluent clientele seeking individuality and sophistication in their living and working spaces. For instance, the German Design Award 2023 recognized Continental for its Luxury Minimalism Concept, which integrates elegantly restrained design with innovative display solutions like the 5K Natural 3D Display, showcasing how luxury and technology can coexist to create a feel-good atmosphere. Additionally, the hospitality sector’s emphasis on unique and immersive guest experiences is fueling the demand for high-quality interior designs in hotels, restaurants, and luxury resorts. The pursuit of elegance, comfort, and exclusivity continues to shape the evolving trends within Germany’s interior design industry.
Market Trends:
Emphasis on Minimalist and Functional Designs
Germany's interior design market is experiencing a strong shift towards minimalist and functional aesthetics, reflecting the country’s architectural heritage and modern lifestyle preferences. Consumers are favoring clean lines, open spaces, and neutral color palettes that promote simplicity and efficiency without compromising on elegance. The Scandinavian-inspired design approach, which emphasizes functionality, sustainability, and a clutter-free environment, is particularly popular among urban homeowners. Additionally, the demand for multifunctional furniture and space-saving solutions is rising, especially in compact apartments and urban residences, where optimizing space has become a priority. For instance, Kaashni, a trailblazer in architectural hardware, has integrated technology into its products to enhance functionality. For instance, their Pearl Concept showroom uses cutting-edge technology to provide an immersive experience, allowing for precise customization of spaces with features like automated lighting and climate control systems. This trend highlights a broader movement towards practical yet aesthetically refined interiors, catering to both residential and commercial markets.
Growth of Hybrid and Flexible Workspaces
The rise of hybrid work models and remote working trends has significantly influenced Germany’s interior design market, particularly in the commercial sector. Companies are reimagining office spaces to enhance flexibility, collaboration, and employee well-being, leading to a surge in demand for adaptable interior designs. Office spaces are now integrating modular furniture, ergonomic workstations, and biophilic design elements to create a more dynamic and engaging work environment. In addition, home office setups have become a crucial focus, with individuals investing in personalized workspace solutions that blend comfort, functionality, and aesthetics. For instance, Schneider Electric unveiled the Back-UPS BE Series - 900 & 1050 VA in 2024, designed for remote work and smart home needs. This shift in workplace design is reshaping both corporate and residential interiors, as businesses and professionals seek to create inspiring and productive spaces.
Integration of Artisanal and Locally Sourced Materials
A growing appreciation for artisanal craftsmanship and locally sourced materials is shaping interior design trends in Germany. Consumers are increasingly valuing handcrafted furniture, natural textures, and regionally produced materials, which add a unique and authentic touch to interior spaces. The use of wood, stone, and organic textiles has gained traction, reflecting a preference for high-quality, durable, and sustainable interior solutions. Additionally, the revival of traditional craftsmanship, combined with contemporary design sensibilities, is leading to the rise of customized and bespoke interiors. For instance, companies like Pfleiderer have been recognized for their sustainable practices, winning the German Sustainability Award 2024 in the Basic Materials / Wood Processing category. This trend not only supports local artisans and businesses but also aligns with Germany’s focus on sustainability, reducing carbon footprints associated with imported materials.
Increasing Adoption of Smart Lighting and Home Automation
Technological advancements in smart home automation are significantly influencing interior design choices across Germany. The integration of smart lighting, voice-controlled systems, and AI-driven home management solutions is becoming a standard feature in modern interiors. Consumers are prioritizing energy-efficient lighting systems, automated shading solutions, and temperature control technologies that enhance convenience, security, and sustainability. Additionally, the incorporation of wireless and app-controlled systems allows homeowners to personalize and manage their living spaces with greater ease. For instance, Philips Hue offers smart bulbs with a wide range of colors that can be controlled by voice through an app, providing energy-efficient lighting solutions that can be adjusted to match mood or decor. This increasing adoption of technology-driven interior solutions is creating a seamless blend of design, functionality, and innovation, shaping the future of the interior design market in Germany.
Market Challenges Analysis:
High Costs of Premium Interior Solutions
One of the major challenges in Germany’s interior design market is the high cost associated with premium and customized design solutions. The increasing preference for luxury interiors, sustainable materials, and high-end furnishings significantly raises project expenses, making it difficult for middle-income consumers to afford professional interior design services. Additionally, the rising costs of raw materials, labor, and imported decor elements further contribute to price inflation. While there is a strong demand for unique and high-quality interiors, budget constraints limit market accessibility, particularly for small businesses and cost-conscious consumers.
Shortage of Skilled Interior Designers and Craftsmen
Germany's interior design industry faces a shortage of highly skilled professionals, including interior designers, architects, and artisans specializing in custom furnishings and handcrafted decor. The demand for personalized, sustainable, and technologically integrated interior solutions requires expertise in multiple disciplines, from traditional craftsmanship to digital design tools. However, the availability of trained professionals has not kept pace with market growth, leading to project delays and increased service costs. This talent gap poses a significant challenge for design firms looking to scale their operations and meet the evolving demands of clients.
Impact of Economic Uncertainty on Consumer Spending
Economic fluctuations and inflationary pressures influence consumer spending patterns, directly impacting the interior design market. During periods of economic uncertainty, both businesses and homeowners tend to postpone or downscale renovation and design projects, leading to a slowdown in market activity. Additionally, fluctuations in real estate investment and construction projects can create an unpredictable demand for interior design services. While the market remains resilient, external economic pressures continue to pose a challenge for steady growth.
Regulatory Compliance and Sustainability Standards
Germany has stringent regulations regarding building materials, energy efficiency, and environmental sustainability, which interior designers must adhere to when executing projects. Compliance with these regulations can be complex and costly, requiring extensive planning, certification processes, and specialized materials. Meeting these sustainability standards is essential for long-term growth; however, navigating regulatory requirements adds an additional layer of complexity to interior design projects, particularly for smaller firms and independent designers.
Market Opportunities:
Germany's interior design market presents significant growth opportunities, driven by evolving consumer preferences and advancements in technology. The increasing demand for sustainable and eco-friendly interiors provides a lucrative avenue for designers and businesses to develop innovative, energy-efficient solutions. As sustainability becomes a key factor in purchasing decisions, there is an opportunity for market players to focus on green-certified materials, recycled furniture, and smart home integrations that align with Germany’s strong environmental policies. Additionally, the expanding luxury real estate and premium hospitality sectors create a growing market for high-end interior solutions, offering interior designers the chance to cater to affluent consumers seeking bespoke, sophisticated designs.
Another promising opportunity lies in the digital transformation of the interior design industry. The adoption of virtual reality (VR), augmented reality (AR), and artificial intelligence (AI)-driven design solutions is reshaping client interactions, allowing for enhanced visualization and customization. Interior design firms leveraging these technologies can streamline their processes, reduce project costs, and expand their reach beyond local markets. Furthermore, the rise of e-commerce platforms for furniture, decor, and interior solutions provides an additional revenue stream for designers, enabling them to collaborate with manufacturers and sell curated design packages online. As urbanization continues and modern living spaces evolve, the demand for functional, aesthetically appealing, and technology-driven interiors will continue to rise, positioning Germany as a key market for interior design innovation and growth.
Market Segmentation Analysis:
The Germany Interior Design Market is segmented across multiple dimensions, reflecting the diverse needs of consumers, businesses, and institutions.
By Project Type, the residential sector dominates due to rising homeownership rates and increasing investments in personalized interiors. The commercial and hospitality segments are experiencing strong growth, driven by corporate expansions, luxury hotels, and coworking spaces. Healthcare and educational facilities are prioritizing functional, patient-friendly, and student-centric interiors, while retail and public buildings emphasize aesthetic appeal and user experience.
By Service Type, interior design consulting and space planning are highly sought after, particularly in commercial and high-end residential projects. Furniture & fixture selection, lighting design, and color consultation are essential in creating cohesive and visually appealing spaces, influencing consumer preferences across all project types.
By Budget Range, projects vary from small-scale renovations under $10,000 to luxury developments exceeding $500,000. Mid-range budgets between $10,000 and $100,000 dominate, particularly in residential and commercial segments, while high-end budgets cater to luxury real estate and premium hospitality projects.
By Project Complexity, simple refurbishments and major renovations are common in residential and retail sectors, while new builds and high-end luxury designs are prevalent in commercial and hospitality developments.
By Client Type, the market serves homeowners, businesses, architects, contractors, developers, and property managers. While homeowners drive residential demand, businesses and developers are key clients in the commercial and hospitality sectors, seeking innovative and high-quality interior solutions.
Segmentation:
By Project Type
- Residential
- Commercial
- Hospitality
- Healthcare
- Retail
- Educational
- Public Buildings
By Service Type
- Interior Design Consulting
- Interior Decoration
- Space Planning
- Furniture & Fixture Selection
- Lighting Design
- Color Consultation
By Budget Range
- Under $10,000
- $10,000-$50,000
- $50,000-$100,000
- $100,000-$250,000
- $250,000-$500,000
- Over $500,000
By Project Complexity
- Simple Refurbishment
- Major Renovation
- New Build
- High-End Luxury
By Client Type
- Homeowners
- Businesses
- Architects
- Contractors
- Developers
- Property Managers
Regional Analysis:
Germany's interior design market exhibits significant regional variations, with major cities such as Munich, Berlin, Hamburg, and Frankfurt leading in market share and growth. These urban centers are characterized by robust economic activities, affluent populations, and dynamic real estate developments, all of which contribute to the demand for interior design services.
Munich
Munich stands at the forefront of Germany's luxury interior design market, commanding approximately 30% of the market share. The city's status as one of the wealthiest in Germany drives a consistent demand for high-end residential and commercial interior design services. The booming real estate sector, marked by a surge in luxury housing and commercial projects, fuels this demand. Affluent residents in Munich are inclined to invest in personalized, upscale interiors that blend modern design elements with classic German aesthetics. Additionally, Munich serves as a hub for international businesses and luxury retail, further contributing to the need for premium office spaces and luxury showrooms. The growing preference for sustainable, wellness-oriented living spaces also influences the market in this region, making it a primary driver of overall market growth.
Berlin
Berlin, renowned for its cultural vibrancy and progressive urban development, holds a market share of around 25%. The city's luxury interior design market is primarily driven by the influx of high-net-worth individuals and expatriates seeking bespoke design services for high-end apartments and residential properties. Real estate development in Berlin has accelerated, with numerous luxury residences being constructed in the city center and surrounding areas. The demand for luxury commercial spaces, including hospitality venues and high-end offices, is also on the rise as Berlin becomes an increasingly important business and cultural hub. Furthermore, the city's younger, design-conscious population is pushing for more sustainable, tech-savvy, and personalized interior design solutions, contributing to the market's growth.
Hamburg and Frankfurt
Hamburg and Frankfurt also play significant roles in Germany's interior design landscape. While specific market share data for these cities is less defined, both are recognized for their economic significance and demand for interior design services. Hamburg, with its strong maritime heritage and status as a media hub, sees considerable activity in both residential and commercial interior design projects. Frankfurt, as a major financial center, experiences substantial demand for corporate interior designs that emphasize functionality, aesthetics, and brand representation. The presence of international corporations and a growing expatriate community in these cities further stimulates the market for innovative and high-quality interior design solutions.
Key Player Analysis:
- Gensler
- Jacobs Engineering Group Inc.
- Perkins and Will
- Stantec Inc
- Areen Design Services Ltd
- IA Interior Architects
- Cannon Design
- Hirsch Bedner Associates
- Brucknerinnen
- Philipp Mainzer Office for Architecture and Design
- SUSANNE KAISER ARCHITECTURE & INTERIOR DESIGN
Competitive Analysis:
Germany's interior design market is highly competitive, with a mix of established design firms, independent designers, and international luxury brands vying for market share. Leading players such as Kitzig Interior Design, JOI-Design, and Seel Bobsin Partner dominate the high-end segment, offering bespoke and innovative design solutions for residential, commercial, and hospitality spaces. These firms leverage their expertise in sustainable design, digital visualization, and premium craftsmanship to cater to affluent clientele and corporate clients. For instance, JOI-Design integrates state-of-the-art technical solutions and natural materials, exemplified by their 100-year-old villa renovation in Germany. The market also sees competition from local boutique studios and freelance designers, who provide personalized services at competitive pricing, appealing to mid-range and niche markets. Additionally, international luxury interior brands and furniture manufacturers continue to expand their presence, collaborating with German designers to offer premium solutions. As digitalization and e-commerce reshape consumer engagement, companies that integrate technology-driven design tools and smart home solutions gain a competitive edge, reinforcing their position in this evolving market.
Recent Developments:
- Stantec announced in November 2023 its agreement to acquire ZETCON Engineering, a 645-person engineering firm headquartered in Bochum, Germany. This acquisition provides Stantec with a significant platform in Germany, focusing on infrastructure planning, inspection, project management, and construction management. ZETCON's expertise in bridge certification, project management of tunnels, roads, and rail infrastructure, combined with Stantec's global capabilities, aims to diversify and grow their business in the German market.
Market Concentration & Characteristics:
The Germany Interior Design Market is moderately concentrated, with a mix of large design firms, boutique studios, and independent professionals driving industry growth. Leading firms such as Kitzig Interior Design, JOI-Design, and Seel Bobsin Partner dominate the high-end segment, catering to luxury residential, corporate, and hospitality clients. However, the market remains fragmented due to the presence of numerous mid-sized and small-scale interior design firms specializing in customized and niche services. The market is characterized by a strong emphasis on sustainability, technological integration, and personalization. With increasing consumer demand for eco-friendly materials, energy-efficient designs, and smart home solutions, interior design companies are incorporating digital visualization tools such as 3D modeling, augmented reality (AR), and artificial intelligence (AI) to enhance client engagement. Additionally, Germany’s rich architectural heritage and evolving urban landscapes influence design trends, leading to a balance between modern minimalism and classic elegance in interior spaces.
Report Coverage:
The research report offers an in-depth analysis based on By Project Type, By Service Type, By Budget Range , By Project Complexity and By Client Type It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to grow steadily, driven by rising disposable incomes and increasing demand for premium interior solutions.
- Sustainability will remain a key focus, with eco-friendly materials, energy-efficient designs, and green certifications shaping future trends.
- Technological advancements, including AI-driven design, virtual reality (VR), and 3D visualization, will enhance customization and client engagement.
- The growing luxury real estate sector will continue to drive demand for high-end, bespoke interior design services.
- The expansion of hybrid work models will increase demand for flexible, ergonomic home office and corporate workspace solutions.
- Urbanization and compact living trends will fuel the market for multifunctional furniture and space-saving interior solutions.
- Increasing collaborations between interior designers and smart home technology providers will integrate automation into modern interiors.
- Boutique design firms and independent designers will gain market share by offering personalized, niche, and cost-effective design solutions.
- The rise of e-commerce in interior design will enable consumers to access customized decor and furniture solutions online.
- Regulatory compliance and sustainability policies will continue to influence material choices, design processes, and overall market direction.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size and growth forecast for the Germany Interior Design Market?
What are the key factors driving market growth?
Which regions in Germany have the highest demand for interior design services?
What challenges does the German interior design market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany Interior Design Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Germany Interior Design Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 8,887.25 million → 2032: USD 13,764.17 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany Interior Design Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany Interior Design Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany Interior Design Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Germany Interior Design Market Drivers
- 3.3 Germany Interior Design Market Restraints & Challenges
- 3.4 Germany Interior Design Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany Interior Design Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany Interior Design Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany Interior Design category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany Interior Design Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Germany Interior Design Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Germany Interior Design market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany Interior Design Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Germany Interior Design Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Germany Interior Design Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany Interior Design (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Germany Interior Design Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Germany Interior Design Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Germany Interior Design Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Germany Interior Design Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Germany Interior Design Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Germany Interior Design Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Germany Interior Design Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Germany Interior Design Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Germany Interior Design Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
