
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Germany Interior Design Software Market Size 2023 | USD 429.22 million |
| Germany Interior Design Software Market, CAGR | 12.41% |
| Germany Interior Design Software Market Size 2032 | USD 1,231.22 million |
Market Overview:
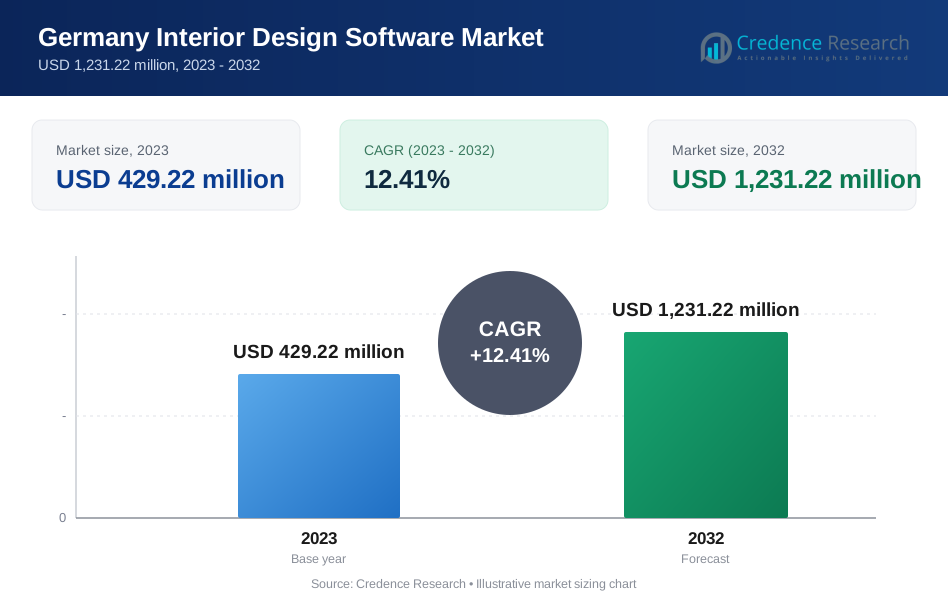
Germany Interior design software market size was valued at USD 429.22 million in 2023 and is anticipated to reach USD 1,231.22 million by 2032, at a CAGR of 12.41% during the forecast period (2023-2032).
One of the key drivers of the Germany Interior Design Software Market is the increasing adoption of virtual reality (VR) and augmented reality (AR) technologies. These technologies enable clients to experience real-time, immersive visualizations of interior spaces, helping in better decision-making and reducing design alterations. Additionally, AI-driven automation is enhancing software capabilities by providing predictive design recommendations, space optimization solutions, and cost estimations, making the software indispensable for professionals. Another significant factor is the rising demand for smart homes and sustainable interior designs. Consumers and businesses alike are seeking eco-friendly materials, energy-efficient layouts, and smart home integrations, all of which require advanced software for precise planning. The growing real estate and construction industry in Germany is also contributing to the market, as builders and developers increasingly rely on interior design software for space planning and customization.
Germany's interior design software market is concentrated in major urban regions, with Berlin, Munich, Hamburg, and Frankfurt emerging as key hubs for industry adoption. These cities have a high concentration of architectural firms, real estate developers, and tech-savvy consumers, driving the demand for advanced design solutions. The southern regions, particularly Bavaria and Baden-Württemberg, are witnessing increased adoption due to strong construction activity and a growing number of luxury residential projects. In Western Germany, cities like Cologne and Düsseldorf are experiencing rising investments in interior renovation and commercial real estate projects, further boosting market growth. Meanwhile, Eastern Germany is gradually catching up, with increasing investments in infrastructure development and real estate modernization.
Market Insights:
- The Germany Interior Design Software Market was valued at USD 429.22 million in 2023 and is projected to reach USD 1,231.22 million by 2032, growing at a CAGR of 12.41%.
- Virtual reality (VR) and augmented reality (AR) are transforming the industry by providing real-time, immersive visualizations that enhance client decision-making and reduce design alterations.
- AI-driven automation is revolutionizing software capabilities by offering predictive design recommendations, smart space planning, and automated cost estimations, improving efficiency for professionals.
- The rising demand for smart home integrations and sustainable interior solutions is increasing the adoption of interior design software, enabling energy-efficient and eco-friendly space planning.
- Germany's real estate and construction boom is driving software adoption in urban areas, particularly for customized interiors, commercial spaces, and high-end residential projects.
- High initial investment costs and a steep learning curve for advanced software solutions remain key challenges, limiting adoption among smaller design firms and independent professionals.
- Major urban hubs such as Berlin, Munich, Hamburg, and Frankfurt lead the market, while southern and western Germany are experiencing rapid growth due to increased investments in real estate modernization and luxury development.
Market Drivers:
Rising Adoption of Digitalization in Interior Design
The increasing digital transformation in the architecture, engineering, and construction (AEC) sector is a major driver for the growth of the Germany Interior Design Software Market. Interior designers, architects, and real estate developers are rapidly adopting digital tools to enhance design precision, improve efficiency, and minimize errors. For instance, Vectorworks 2025's German version introduced advanced features including Object Level Visibility and Cloud Drawing Reviewer, enabling real-time document viewing and commenting capabilities. Traditional design methods are being replaced by AI-powered solutions, 3D modeling software, and cloud-based platforms that allow real-time collaboration and instant modifications. The growing emphasis on virtual walkthroughs and 3D rendering is further pushing professionals to invest in advanced interior design software, ensuring a seamless design-to-execution process.
Integration of Artificial Intelligence and Automation
AI-driven innovations in interior design software are reshaping the industry by streamlining complex processes. Modern software solutions are integrating machine learning algorithms to provide automated design suggestions based on space dimensions, lighting conditions, and user preferences. These smart tools help designers generate optimized layouts, material recommendations, and cost estimates, significantly reducing project completion times. For instance, V Starr Interiors LLC's Palazzo platform, launched in March 2024, demonstrates the latest AI capabilities, featuring element-specific image editing and a personalized style quiz to enhance user preference understanding. The ability to leverage AI-powered automation for predictive design analytics, smart furniture placement, and automated compliance checks is attracting both independent designers and large-scale architectural firms. As German professionals seek greater efficiency and accuracy, the demand for AI-integrated interior design solutions continues to expand.
Growth in Smart Home and Sustainable Interior Design Trends
The increasing popularity of smart home technologies and sustainable interior solutions is accelerating the adoption of interior design software. Homeowners and developers are focusing on energy-efficient layouts, eco-friendly materials, and smart lighting systems, all of which require precise planning and integration. Software solutions equipped with sustainability assessment tools are enabling designers to create environmentally responsible spaces while ensuring compliance with Germany’s stringent building regulations. For instance, Ecotect, a sustainability analysis tool, is used by German firms like Transsolar to evaluate energy efficiency and environmental impact in design projects. Additionally, the rise of Internet of Things (IoT) integration in home automation is driving the need for customized digital design platforms that can seamlessly incorporate smart devices, making interior design software an essential tool for the modern home.
Expansion of the Real Estate and Construction Industry
Germany's booming real estate and construction sector is creating significant demand for interior design software, particularly in urban regions such as Berlin, Munich, and Hamburg. With an increasing number of residential, commercial, and hospitality projects, developers and contractors are turning to digital design tools for better planning and execution. For instance, companies like Züblin and HOCHTIEF are utilizing tools like Revit and ArchiCAD for large-scale residential and commercial projects. The growing trend of customized interiors, flexible workspaces, and luxury home renovations is further fueling the market. Additionally, government initiatives promoting sustainable urban development and smart city projects are encouraging the use of data-driven design solutions, enabling professionals to efficiently manage large-scale projects. As the construction landscape continues to evolve, interior design software remains a critical component in ensuring high-quality, cost-effective, and visually appealing spaces.
Market Trends:
Increased Adoption of Cloud-Based Design Platforms
The shift toward cloud-based interior design software is transforming the market in Germany, as professionals seek more flexible, scalable, and collaborative solutions. For instance, Nemetschek Group, a leading German software provider, offers BIMcloud, a cloud-based platform that enables real-time collaboration among architects, designers, and contractors. Cloud-based platforms enable designers, architects, and clients to work on projects remotely, ensuring seamless access to design files and real-time updates. This trend is particularly beneficial for large architectural firms managing multiple projects simultaneously, as cloud integration improves workflow efficiency and project management. With advancements in cloud computing and cybersecurity, companies are increasingly confident in adopting cloud solutions to enhance design accessibility while maintaining data security.
Growing Popularity of Virtual Reality (VR) and Augmented Reality (AR)
VR and AR technologies are becoming integral to the interior design process, allowing clients to experience immersive 3D walkthroughs before finalizing their designs. For instance, companies like RIEGL, a German leader in 3D scanning and visualization, provide tools that integrate with VR platforms to create immersive design experiences. This innovation significantly enhances customer engagement by providing a realistic visualization of spaces, helping homeowners and businesses make informed decisions. The ability to test different layouts, colors, and materials in a virtual environment reduces costly design modifications and increases overall project satisfaction. As hardware and software capabilities in VR/AR continue to advance, German interior designers are integrating these tools into their workflow, making digital visualization a standard practice in modern design.
Customization and AI-Powered Personalization
Consumers in Germany are increasingly demanding personalized interior design solutions, driving software developers to integrate AI-powered customization features. Advanced algorithms analyze user preferences, space dimensions, and functional requirements to generate optimized design recommendations. These tools allow designers to tailor layouts, color palettes, and furnishings to match individual client expectations, enhancing creativity and efficiency. For instance, Morpholio Board, used by German interior designers, employs AI to simulate real-time material changes and color palettes, allowing clients to experiment with different styles. Additionally, real-time material simulations and automated furnishing suggestions are improving decision-making processes, enabling users to experiment with various styles before finalizing their selections. As AI continues to evolve, interior design software is expected to offer more intuitive and data-driven personalization, catering to both residential and commercial markets.
Sustainability-Driven Design Innovations
Sustainability has become a key focus area in Germany’s interior design industry, influencing the development of software solutions that promote eco-friendly practices. Modern design software is incorporating sustainability assessment tools that help architects and designers evaluate energy consumption, carbon footprint, and material efficiency during the planning phase. For instance, Dassault Systèmes, through its 3DEXPERIENCE platform, provides tools for evaluating energy efficiency and material sustainability in design projects. The demand for sustainable building materials, energy-efficient lighting solutions, and low-emission furniture is driving software companies to develop features that support green building certifications and compliance with environmental regulations. As the German government continues to push for sustainable construction and smart urban planning, interior design software is playing a crucial role in ensuring eco-conscious design solutions that align with both regulatory requirements and consumer expectations.
Market Challenges Analysis:
High Initial Investment and Software Learning Curve
One of the primary challenges facing the Germany Interior Design Software Market is the high cost of advanced software solutions. Professional-grade interior design software often comes with expensive licensing fees, subscription costs, and additional charges for premium features, making it a significant investment for small and independent designers. While large firms can justify these expenses, freelancers and smaller architectural studios may struggle to allocate budgets for high-end software, limiting adoption rates. Additionally, the steep learning curve associated with complex design platforms poses another challenge. Many AI-integrated and 3D modeling software solutions require specialized training and expertise, which can deter new users from fully utilizing their capabilities. The lack of technical proficiency and the time required for software mastery can slow adoption rates among professionals, impacting market growth.
Compatibility Issues and Data Security Concerns
As interior design projects involve multiple stakeholders, software interoperability and compatibility with other architectural tools remain significant challenges. Many legacy systems and traditional CAD tools lack seamless integration with cloud-based or AI-driven interior design software, leading to inefficiencies in workflow and data transfer. The need for standardized file formats and smooth collaboration between different software ecosystems is essential but remains a persistent issue. Additionally, data security concerns pose a major restraint in the industry. With the increasing use of cloud storage and online collaboration tools, professionals are concerned about intellectual property theft, cyber threats, and unauthorized access to confidential design files. As digital transformation continues to reshape the industry, ensuring robust cybersecurity measures and secure data management practices is critical for overcoming these challenges and maintaining industry trust.
Market Opportunities:
The Germany Interior Design Software Market presents significant growth opportunities driven by the rising demand for AI-powered and cloud-based design solutions. The increasing preference for remote collaboration and real-time project visualization is pushing software developers to enhance their platforms with cloud integration, augmented reality (AR), and virtual reality (VR) features. These innovations allow designers to offer interactive experiences to clients, improving decision-making and reducing project revisions. Additionally, as the smart home industry continues to expand, the need for interior design software that seamlessly integrates with IoT-based home automation systems is growing. This shift is expected to create lucrative opportunities for software providers to develop solutions tailored for energy-efficient, technology-driven home designs.
Another key opportunity lies in Germany’s increasing emphasis on sustainability and eco-friendly construction. The adoption of green building standards and energy-efficient interior designs is rising, encouraging the development of software tools that support sustainable material selection, carbon footprint calculations, and compliance with environmental regulations. Moreover, the real estate sector’s demand for highly customized and modular interior spaces is driving interest in software solutions that offer AI-powered space planning and automated cost estimation. As interior design becomes more data-driven, companies that provide personalized, analytics-driven, and regulation-compliant solutions will gain a competitive edge in the evolving German market.
Market Segmentation Analysis:
The Germany Interior Design Software Market is segmented based on features, application, end-user, pricing model, and deployment model, each contributing to the market’s growth and adoption trends.
By Features, 3D view, virtual tour, and collaboration tools are becoming essential components, allowing architects and designers to create immersive experiences. The ability to visualize designs in real-time 3D enhances client engagement and improves decision-making, while collaboration tools streamline project communication among stakeholders.
By Application, real-time 3D modeling and space planning hold a dominant share, as professionals prioritize efficiency and precision in design execution. Floor plan creation and furniture & fixture designing are widely used for both residential and commercial projects, while visualization tools enable better material selection and aesthetic planning.
By End-User, the residential sector is a significant market driver, fueled by the growing trend of customized home interiors and smart living spaces. The non-residential sector, including corporate offices, hospitality, and retail spaces, is also witnessing strong demand for interior design solutions to enhance space utilization and brand aesthetics.
By Pricing Model, subscription-based software is gaining popularity, offering cost-effective and scalable solutions, particularly for small and mid-sized design firms. Perpetual licensing models remain relevant among large enterprises seeking long-term ownership and full access to advanced features.
By Deployment Model, cloud-based solutions are leading the market, driven by their remote accessibility, scalability, and ease of collaboration. However, on-premises deployment continues to be preferred by organizations with strict data security requirements and offline operational needs.
Segmentation:
By Features
- 3D View
- Collaboration Tools
- Virtual Tour
By Application
- Floor Plan Creation
- Furniture And Fixture Designing
- Real-Time 3D Modeling
- Space Planning
- Visualization
By End-user
- Residential Sector
- Non-Residential Sector
By Pricing Model
- Perpetual Licensing
- Subscription-Based
By Deployment Model
- Cloud-Based
- On-Premises
Regional Analysis:
Berlin and Eastern Germany: Emerging Digital Hubs
Berlin serves as a major center for the interior design software market in Germany, driven by its rapidly expanding tech ecosystem and real estate sector. The city accounts for approximately 22.5% of the market share, as architectural firms and startups increasingly adopt AI-driven and cloud-based design solutions. The demand for modern, technology-integrated residential and commercial spaces is fueling the adoption of advanced software tools. Eastern Germany, including cities such as Dresden and Leipzig, is also witnessing growth as investment in infrastructure development and real estate modernization increases. With government initiatives supporting digital transformation in the construction sector, this region is expected to see further market expansion.
Southern Germany: Stronghold of Premium Architectural Solutions
Southern Germany, particularly Munich and Stuttgart, holds a dominant 27.8% share of the interior design software market, fueled by its strong architectural presence, luxury housing market, and commercial real estate expansion. The region is home to high-end architectural firms that prioritize AI-powered design tools, 3D modeling, and VR-driven visualization solutions to cater to premium clientele. Additionally, Bavaria and Baden-Württemberg lead in the adoption of sustainability-focused design software, as stricter energy efficiency regulations drive demand for eco-friendly construction planning tools. As smart city initiatives continue to grow in Munich, software providers focusing on AI-integrated and green design solutions have a significant opportunity in this region.
Western Germany: Commercial and Industrial Expansion
Western Germany, particularly Cologne, Düsseldorf, and Frankfurt, represents around 25.4% of the market share, driven by the high demand for commercial interior design software. As major financial and business hubs, these cities see increasing adoption of enterprise-grade design solutions that facilitate space optimization, workflow automation, and smart office integrations. The rise of flexible workspaces, co-working environments, and mixed-use developments is driving companies to invest in customizable interior design platforms. Additionally, Frankfurt’s prominence in the real estate sector, supported by a growing number of commercial projects, is further contributing to the market’s expansion in this region.
Northern Germany: Steady Growth in Residential Renovation
Northern Germany, including Hamburg and Bremen, holds a market share of approximately 24.3%, largely supported by the increasing demand for home renovation and refurbishment projects. The trend toward modernized residential interiors and sustainable home designs is fueling the adoption of digital design tools and smart material selection software. Hamburg, being a significant port city with a strong commercial sector, is also seeing steady adoption of software solutions tailored for retail, hospitality, and office interiors. As property renovation projects increase, the region is expected to maintain a steady demand for interior design software solutions that facilitate real-time visualization and AI-assisted planning.
Key Player Analysis:
- Ashampoo 3D CAD
- Autodesk
- Cedreo
- Chief Architect
- Coohom
- DecoSoftware
- Floorplanner
- Home Designer Suite
- HomeByMe ‘
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis:
The Germany Interior Design Software Market is characterized by a mix of global software providers and regional players, each competing to offer innovative, AI-driven, and cloud-based solutions. The market is witnessing increasing competition among large multinational firms, emerging startups, and specialized industry-focused developers aiming to enhance software efficiency, usability, and customization. Leading software providers are investing in AI-powered automation, virtual reality (VR) integration, and cloud-based collaboration tools to cater to the growing demand for smart and sustainable interior design solutions. For instance, Nemetschek Group, leader in construction and design software, provides tools like Allplan and Vectorworks, which are widely used in Germany for their advanced 3D modeling and cloud collaboration features. Additionally, regional players are focusing on localized compliance, German-language interfaces, and tailored solutions for the luxury residential and commercial segments. As real estate modernization and smart city projects accelerate, companies with advanced data analytics, energy-efficient design capabilities, and seamless interoperability with construction software are gaining a competitive edge. The market is expected to see further innovation as technology adoption increases across Germany’s architectural and interior design industries.
Recent Developments:
- Ashampoo® 3D CAD Architecture 11 was launched on February 20, 2024. This software is for home design and 3D construction on Windows PCs.
- In March 2022, Autodeskmade a significant move by acquiring HIVE Software, a leader in virtual reality design tools for architecture, engineering, and construction professionals. This acquisition is expected to enhance Autodesk’s offerings in the interior design software space, allowing for more immersive client presentations and improved design experiences. The integration of HIVE's technology is anticipated to strengthen Autodesk's position in the competitive landscape of interior design software
Market Concentration & Characteristics:
The Germany Interior Design Software Market is moderately concentrated, with a combination of global technology firms and regional software developers competing to meet the growing demand for AI-powered, cloud-based, and automation-driven design solutions. Established international players dominate the market, leveraging advanced 3D modeling, virtual reality (VR), and real-time collaboration features to enhance user experience and project efficiency. The market is characterized by high digital adoption rates, increasing demand for sustainable design solutions, and a growing focus on smart home integration. The adoption of AI-driven customization, predictive design analytics, and automated cost estimation is becoming a key differentiator among software providers. Additionally, the market benefits from Germany’s strong regulatory environment, which encourages software developers to integrate energy-efficient and compliance-driven features. As real estate modernization and architectural innovation continue to shape the industry, the market is expected to see steady technological advancements and increasing competition.
Report Coverage:
The research report offers an in-depth analysis based on By Features, By Application, By End-user, By Pricing Model and By Deployment Model. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-powered design tools will enhance predictive analytics, automated space planning, and real-time customization.
- Cloud-based interior design software will see higher adoption, enabling seamless collaboration and remote accessibility.
- Virtual and augmented reality will improve customer engagement through immersive 3D visualization and interactive design experiences.
- Sustainability-focused software features will support energy-efficient planning, eco-friendly material selection, and regulatory compliance.
- Interior design software will increasingly integrate with IoT connectivity, allowing seamless incorporation of smart home automation systems.
- AI-driven personalization will enable users to create highly customized interiors based on preferences, functionality, and aesthetics.
- The expanding real estate sector will drive demand for software tailored for large-scale residential, commercial, and office projects.
- Software developers will integrate compliance tools to meet Germany’s strict building regulations and environmental standards.
- Subscription-based SaaS models will grow, offering flexible pricing and accessibility for independent designers and small businesses.
- Advancements in AI, cloud computing, and digital design will drive market consolidation through mergers and acquisitions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Adoption of VR and AR Technologies
The integration of virtual reality (VR) and augmented reality (AR) in interior design software allows clients and professionals to visualize spaces in real time, improving decision-making and reducing costly design changes. This immersive experience is driving higher adoption rates among German architects and designers.
AI-Driven Automation and Predictive Design
AI-powered features such as automated space planning, predictive design recommendations, and cost estimation are streamlining workflows and enhancing the efficiency of design professionals. These capabilities are making advanced software indispensable for both large firms and independent designers.
Growth in Smart Home and Sustainable Design Trends
The rising demand for smart home integrations and sustainable, energy-efficient interiors is pushing the need for advanced software that can precisely plan and simulate eco-friendly layouts and IoT device integration, aligning with Germany’s strict environmental regulations.
Expansion of Real Estate and Construction Sector
Germany’s booming real estate and construction industry, especially in urban centers, is fueling demand for interior design software to support customized interiors, commercial projects, and luxury residential developments, driving overall market growth.
Shift to Cloud-Based and Collaborative Platforms
The move toward cloud-based design solutions is enabling remote collaboration, real-time updates, and scalable project management, which is particularly attractive to firms managing multiple projects and seeking flexible, secure access to design tools.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Germany Interior Design Software Market?
What factors are driving the growth of the Germany Interior Design Software Market?
What are some challenges faced by the Germany Interior Design Software Market?
Which regions are leading in the Germany Interior Design Software Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Residential Sector
- 1.2.2 Non-Residential Sector
- 1.3 By Features
- 1.3.1 3D View
- 1.3.2 Collaboration Tools
- 1.3.3 Virtual Tour
- 1.4 By Application
- 1.4.1 Floor Plan Creation
- 1.4.2 Furniture And Fixture Designing
- 1.4.3 Real-Time 3D Modeling
- 1.4.4 Space Planning
- 1.4.5 Visualization
- 1.5 By Deployment Model
- 1.5.1 Cloud-Based
- 1.5.2 On-Premises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 429.22 million → 2032: USD 1,231.22 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Germany Interior Design Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Germany Interior Design Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Germany Interior Design Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Germany Interior Design Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Germany Interior Design Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Germany Interior Design Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Germany Interior Design Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Germany Interior Design Software Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 429.22 million → 2032: USD 1,231.22 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Germany Interior Design Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Base-Year Market Share, 2023
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Residential Sector
- 12.3.6.2 Non-Residential Sector
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Features - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Base-Year Market Share, 2023
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 3D View
- 12.4.6.2 Collaboration Tools
- 12.4.6.3 Virtual Tour
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Base-Year Market Share, 2023
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Floor Plan Creation
- 12.5.6.2 Furniture And Fixture Designing
- 12.5.6.3 Real-Time 3D Modeling
- 12.5.6.4 Space Planning
- 12.5.6.5 Visualization
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Deployment Model - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Base-Year Market Share, 2023
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Cloud-Based
- 12.6.6.2 On-Premises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Germany Interior Design Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Germany Interior Design Software Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Germany Interior Design Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Germany Interior Design Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Autodesk
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Nemetschek Group
- 18.4 Ashampoo
- 18.5 Cedreo
- 18.6 Chief Architect
- 18.7 Coohom
- 18.8 Floorplanner
- 18.9 Home Designer Suite
- 18.10 HomeByMe
- 18.11 DecoSoftware
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

