
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany Medical Device Contract Manufacturing Market Size 2023 | USD 3,611.52 million |
| Germany Medical Device Contract Manufacturing Market, CAGR | 11.97% |
| Germany Medical Device Contract Manufacturing MarketSize 2032 | USD 8,921.25 million |
Market Overview
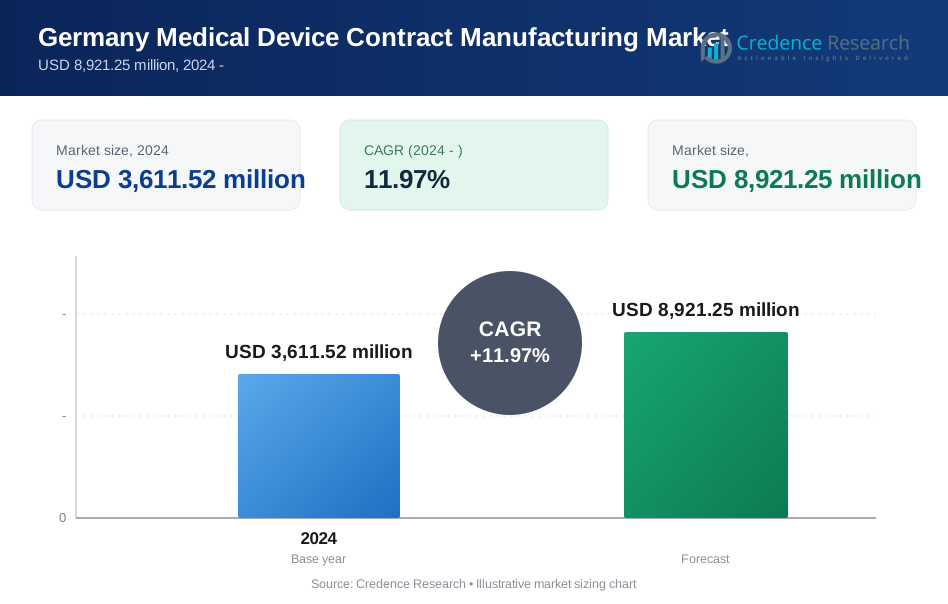
Germany Medical Device Contract Manufacturing market size was valued at USD 3,611.52 million in 2024 and is anticipated to reach USD 8,921.25 million by 2032, at a CAGR of 11.97% during the forecast period (2024-2032).
The Germany medical device contract manufacturing market is driven by several key factors, including the rising demand for innovative medical technologies, an aging population, and increasing healthcare needs. Advancements in digital health, such as IoT integration and personalized medicine, further fuel the market's growth. Manufacturers are also embracing automation and smart manufacturing processes to improve efficiency and reduce costs. The growing preference for outsourcing production to specialized contract manufacturers enables healthcare companies to focus on core competencies while benefiting from reduced operational expenses. Additionally, Germany's strong regulatory framework and well-established healthcare infrastructure make it an attractive destination for medical device manufacturing. The rise in chronic diseases and the expansion of minimally invasive procedures also contribute to the increasing demand for high-quality, precise medical devices. These trends indicate sustained market growth and evolving opportunities for innovation in the medical device manufacturing sector.
Germany’s medical device contract manufacturing industry is geographically diversified, with major hubs located in Berlin, Munich, Hamburg, and Bremen. These regions benefit from strong industrial infrastructure, research institutions, and skilled labor, making them ideal locations for medical device production and innovation. Berlin and Munich lead in technological advancement and R&D collaboration, while Hamburg excels in logistics and export capabilities. Bremen is gaining prominence for its precision manufacturing expertise. The industry is supported by a robust network of key players that includes global giants like Medtronic, alongside specialized firms such as Vention Medical, Sartorius Stedim Biotech, Fiedler GmbH, and Hapman GmbH. These companies play a vital role in shaping the market by offering end-to-end manufacturing services, from component production to final device assembly. Their strategic focus on innovation, compliance, and quality assurance continues to drive Germany’s reputation as a leading hub for high-performance medical device contract manufacturing in Europe.
Market Insights
- The Germany medical device contract manufacturing market was valued at USD 3,611.52 million in 2024 and is projected to reach USD 8,921.25 million by 2032, growing at a CAGR of 11.97% from 2024 to 2032.
- The global medical device contract manufacturing market was valued at USD 79,181.52 million in 2024 and is expected to reach USD 1,90,413.88 million by 2032, growing at a CAGR of 11.59% during the forecast period (2024-2032).
- Rising demand for advanced, cost-efficient, and personalized medical devices is a major factor driving market growth.
- Integration of Industry 4.0 technologies, such as AI, robotics, and 3D printing, is enhancing production precision and efficiency.
- Strong competition among key players like Medtronic, Sartorius Stedim Biotech, and Vention Medical is encouraging innovation and strategic partnerships.
- Regulatory complexities under the EU MDR framework present challenges in compliance and product approvals.
- Berlin, Munich, Hamburg, and Bremen are key regional hubs, each contributing uniquely through innovation, logistics, and technical expertise.
- The market is shifting towards full-service contract manufacturing, with increasing emphasis on quality assurance, traceability, and sustainability.
Report Scope
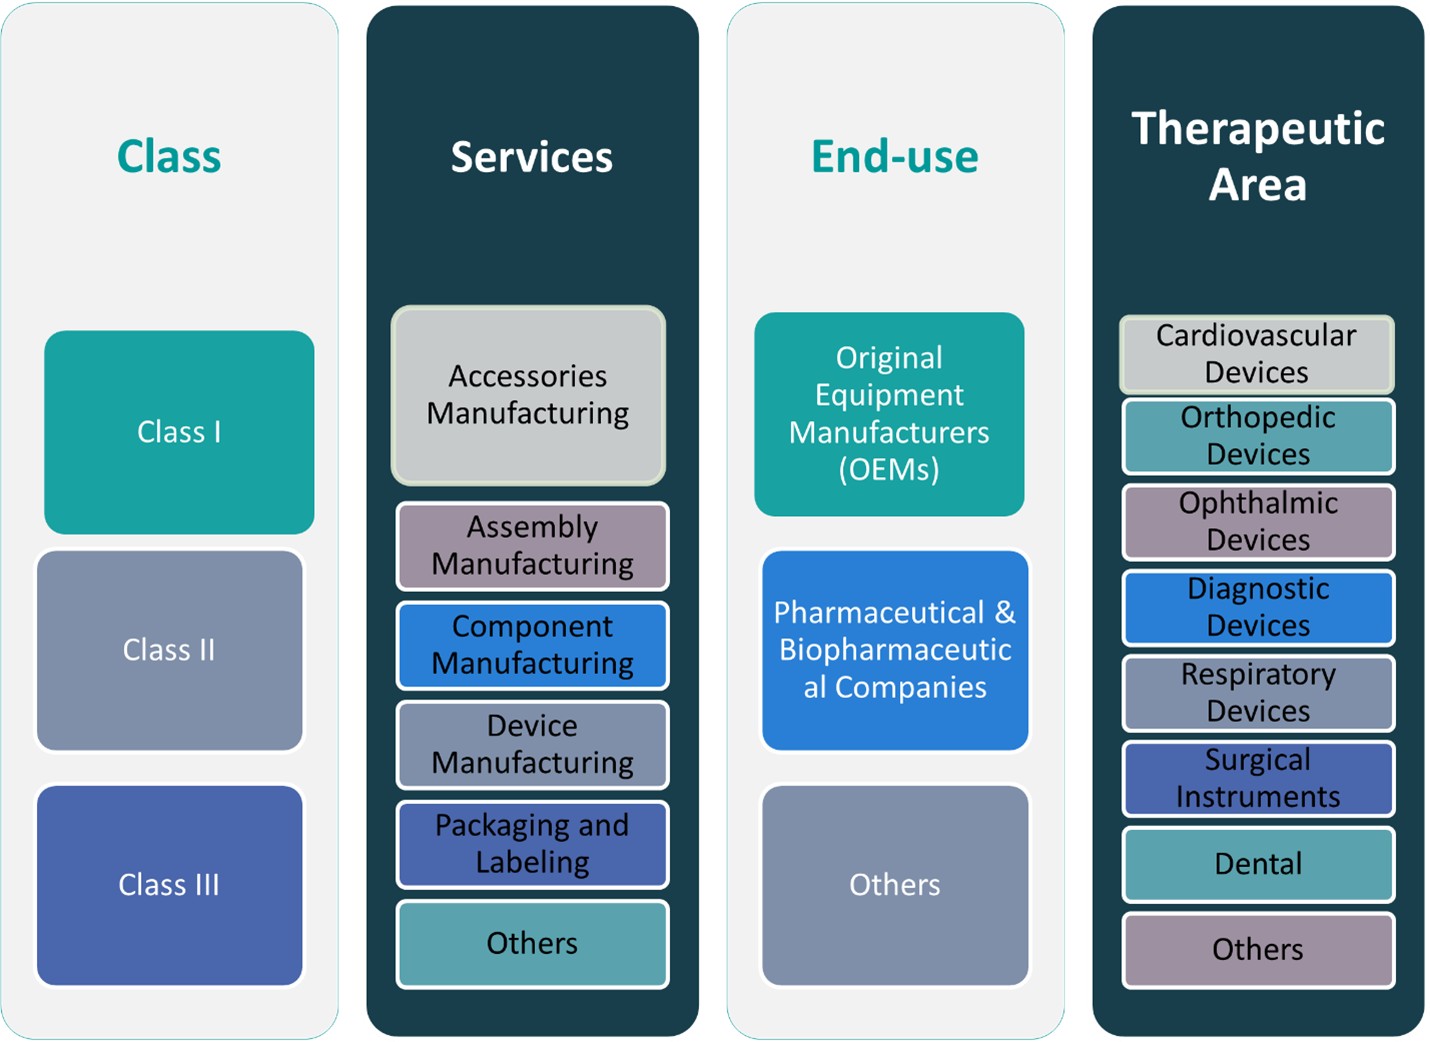
This report segments the Germany Medical Device Contract Manufacturing market as follows:
Market Drivers
Growing Demand for Advanced Medical Technologies
The increasing demand for advanced medical technologies is a significant driver for the growth of the medical device contract manufacturing market in Germany. As healthcare systems evolve, there is a greater emphasis on high-tech medical devices that offer better diagnostics, treatments, and patient outcomes. For instance, Germany's strong engineering sector has fostered innovation in medical technology, with reports highlighting advancements in robotic surgery instruments and wearable health monitors. Devices such as robotic surgery instruments, wearable health monitors, and diagnostic imaging systems are seeing a surge in demand, which necessitates advanced manufacturing capabilities. Germany, known for its strong engineering sector, offers a solid foundation for manufacturers to develop these sophisticated products. The demand for precision and technological advancements in medical devices pushes the need for specialized contract manufacturers that can meet these stringent requirements.
Aging Population and Increasing Healthcare Needs
Germany's aging population is another key driver for the medical device contract manufacturing market. As the population of elderly individuals increases, the prevalence of chronic diseases such as diabetes, cardiovascular conditions, and musculoskeletal disorders also rises. This demographic shift creates a growing need for medical devices that can manage, treat, and monitor these conditions. Contract manufacturers are essential in meeting this demand, as they offer the flexibility and expertise required to produce a wide range of devices tailored to these health needs. Moreover, the focus on improving the quality of life for the elderly through advanced medical technologies fuels the demand for devices that support aging populations, such as assistive mobility devices, hearing aids, and wearable health monitors.
Outsourcing of Production to Specialized Manufacturers
Outsourcing production to contract manufacturers is becoming an increasingly popular strategy for medical device companies in Germany. This approach allows healthcare organizations to focus on their core competencies, such as research and development or marketing, while leveraging the specialized expertise of contract manufacturers for production. By outsourcing, companies can reduce operational costs, increase flexibility, and benefit from faster time-to-market for new products. Contract manufacturers offer critical services such as design, prototyping, regulatory compliance, and scaling production, all of which are essential to meet the complex requirements of the medical device industry. Additionally, outsourcing to a country like Germany, which has a robust regulatory environment and advanced manufacturing infrastructure, provides companies with a competitive edge in the global market.
Regulatory Compliance and Quality Assurance
Germany's strict regulatory standards and commitment to quality assurance significantly contribute to the country's position as a leading hub for medical device contract manufacturing. Germany's regulatory framework, including the European Medicines Agency (EMA) and the German Medical Devices Act (MPG), ensures high safety and efficacy standards for medical devices. Manufacturers in Germany are accustomed to navigating these regulations, making them trusted partners for companies seeking to bring their products to market. Contract manufacturers in Germany are adept at ensuring that devices comply with both European Union and international standards, which is critical for market approval and success. Their ability to meet these stringent regulatory requirements while maintaining high levels of product quality enhances the appeal of Germany as a key location for medical device manufacturing.
Market Trends
Integration of Advanced Manufacturing Technologies
The adoption of cutting-edge manufacturing technologies is a prominent trend shaping the future of the Germany medical device contract manufacturing market. For instance, Germany's medical device sector has embraced Industry 4.0 technologies, including robotics, AI, and IoT, to enhance production efficiency. Robotics and automation enable manufacturers to streamline production lines, reducing human error and increasing efficiency. AI-driven systems help monitor production quality in real-time, optimizing workflows and minimizing defects. Moreover, 3D printing has gained significant traction in the medical device sector, allowing for the creation of highly personalized, patient-specific products that meet precise medical requirements.
Emphasis on Regulatory Compliance and Quality Assurance
Regulatory compliance remains a crucial trend driving the medical device contract manufacturing market in Germany. For instance, Germany's medical device industry operates under strict regulatory frameworks, including the EU MDR and IVDR, ensuring high safety and efficacy standards. Manufacturers in Germany are increasingly focusing on meeting these regulations, which require comprehensive documentation, rigorous testing, and post-market surveillance. Adherence to these standards ensures that devices are safe for use and that manufacturers can achieve market access not only in Germany but also across the European Union and beyond.
Shift Towards Outsourcing and Strategic Partnerships
Outsourcing medical device manufacturing to specialized contract manufacturers is an increasingly popular trend in Germany. As the complexity of medical devices increases, OEMs are turning to contract manufacturers that have the necessary expertise and resources to produce high-quality products efficiently. By outsourcing, medical device companies can focus on core activities such as research, design, and marketing, while relying on contract manufacturers to handle the production, regulatory compliance, and logistics. This strategic approach not only reduces operational costs but also accelerates time-to-market for new products. The growing complexity of medical devices, particularly those requiring specialized manufacturing capabilities, has prompted a surge in strategic partnerships between OEMs and contract manufacturers. These partnerships enable both parties to leverage their strengths—OEMs in design and innovation, and contract manufacturers in efficient, high-quality production.
Focus on Sustainability and Environmental Responsibility
Sustainability is becoming an increasingly important focus in the medical device contract manufacturing market in Germany. With growing concerns over environmental impact, there is a rising demand for sustainable production practices within the medical device industry. Manufacturers are adopting eco-friendly measures, such as using renewable energy sources, reducing waste during production, and utilizing recyclable or biodegradable materials for packaging and components. Germany, known for its commitment to environmental responsibility, has set high standards in sustainability practices, and medical device manufacturers are increasingly aligning their operations with these expectations. For example, some manufacturers are adopting circular economy principles, where products are designed for reuse, recycling, or repurposing, thereby minimizing waste and reducing environmental footprint.
Market Challenges Analysis
Regulatory Complexity and Compliance Challenges
One of the primary challenges facing the medical device contract manufacturing market in Germany is the complexity of regulatory requirements. For instance, Germany's medical device industry operates under the European Union’s Medical Device Regulation (MDR), which enforces stringent safety and quality requirements. Manufacturers must navigate a labyrinth of regulations that vary across regions and device categories, which can complicate the approval process and delay time-to-market. Furthermore, the recent updates to the MDR have introduced more stringent documentation, post-market surveillance, and clinical evaluation requirements. This regulatory landscape demands continuous investment in compliance processes and quality assurance systems, creating significant operational challenges for contract manufacturers. Ensuring that devices meet these evolving regulatory standards while maintaining cost-effectiveness can be resource-intensive, posing a challenge for companies striving to remain competitive in the global market.
Rising Production Costs and Supply Chain Disruptions
Rising production costs and supply chain disruptions represent another significant challenge for Germany's medical device contract manufacturing sector. As raw material prices increase and labor costs rise, manufacturers face pressures to maintain profitability while adhering to high-quality standards. Additionally, global supply chain disruptions, exacerbated by geopolitical factors and the COVID-19 pandemic, have resulted in delays and uncertainties in sourcing components and raw materials. The need to manage an increasingly complex global supply chain while ensuring timely production is a key concern for medical device manufacturers. These disruptions have led to inventory shortages and increased lead times, ultimately affecting the ability to meet market demand efficiently. As a result, contract manufacturers must invest in more resilient supply chain strategies, such as diversifying suppliers or implementing more robust inventory management systems, to mitigate these risks and maintain production continuity.
Market Opportunities
Germany’s medical device contract manufacturing market presents numerous growth opportunities driven by technological advancements and evolving healthcare needs. As the demand for highly specialized and innovative medical devices continues to rise, there is significant potential for manufacturers to capitalize on advancements in areas such as 3D printing, artificial intelligence, and automation. These technologies enable the creation of personalized medical devices, offering a competitive edge in producing patient-specific solutions, particularly in areas like orthopedic implants, prosthetics, and diagnostic tools. The integration of smart manufacturing processes enhances production efficiency and reduces costs, making it an attractive option for medical device companies seeking to optimize their supply chain operations. Furthermore, Germany’s strong regulatory framework ensures that manufacturers can meet rigorous standards, providing an opportunity for contract manufacturers to offer high-quality, compliant solutions to both local and international markets.
Additionally, the ongoing shift towards outsourcing production presents a substantial market opportunity for contract manufacturers in Germany. As OEMs increasingly focus on core competencies such as research and development, they are outsourcing manufacturing to specialized providers with expertise in regulatory compliance, quality assurance, and scalability. This trend is especially prevalent in the production of complex medical devices that require advanced manufacturing capabilities. With a highly skilled workforce, cutting-edge technology, and a well-established reputation for quality, Germany is well-positioned to attract both domestic and global medical device companies seeking reliable and cost-effective manufacturing solutions. As the healthcare sector continues to expand, the demand for efficient and flexible contract manufacturing services will likely continue to grow, creating long-term opportunities for manufacturers in Germany’s competitive medical device market.
Market Segmentation Analysis:
By Class:
The Germany medical device contract manufacturing market is segmented into Class I, Class II, and Class III devices, based on their level of risk and regulatory oversight. Class I devices, which include low-risk products such as bandages and handheld surgical instruments, represent a significant portion of manufacturing volume due to their high demand and relatively simple production processes. However, Class II devices—moderate-risk products such as infusion pumps and diagnostic imaging tools—are experiencing substantial growth as they require greater precision and quality assurance, aligning well with Germany’s advanced manufacturing capabilities. Class III devices, including life-sustaining or life-supporting implants like pacemakers and stents, represent the highest value segment despite their lower volume. These high-risk products demand stringent regulatory compliance and advanced engineering expertise, making Germany’s robust regulatory infrastructure and skilled labor market ideal for their production. As innovation and demand for technologically sophisticated devices grow, the Class II and Class III segments are expected to see accelerated expansion, driven by clinical advancements and increasing patient care standards.
By Services:
The services segment of the Germany medical device contract manufacturing market is diverse, encompassing accessories manufacturing, assembly manufacturing, component manufacturing, device manufacturing, packaging and labelling, and other ancillary services. Device manufacturing holds the largest share, driven by increased outsourcing of full-scale production by OEMs seeking to reduce operational complexities. Component and accessories manufacturing are also vital, especially as companies look to streamline costs and improve product customization. Assembly manufacturing continues to grow due to the demand for modular and multi-component devices. Additionally, packaging and labeling services are gaining prominence, influenced by evolving regulatory requirements that mandate traceability, accurate labeling, and tamper-proof packaging. This has created opportunities for manufacturers offering end-to-end solutions, from design to final packaging. The “Others” segment, which includes testing, sterilization, and supply chain logistics, is also expanding, as manufacturers increasingly seek integrated service providers to enhance efficiency. As OEMs demand comprehensive, regulatory-compliant, and high-quality services, full-service contract manufacturers in Germany are well-positioned for growth across all service categories.
Segments:
Based on Class:
- Class I
- Class II
- Class III
Based on Services:
- Accessories Manufacturing
- Assembly Manufacturing
- Component Manufacturing
- Device Manufacturing
- Packaging and Labelling
- Others
Based on End- Use:
- Original Equipment Manufacturers (OEMs)
- Pharmaceutical & Biopharmaceutical Companies
- Others
Based on Therapeutic Area:
- Cardiovascular Devices
- Orthopedic Devices
- Ophthalmic Devices
- Diagnostic Devices
- Respiratory Devices
- Surgical Instruments
- Dental
- Others
Based on the Geography:
- Berlin
- Munich
- Hamburg
- Bremen
Regional Analysis
Berlin
Berlin holds the largest share in the Germany medical device contract manufacturing market, accounting for approximately 32% of the total market. As the nation’s capital and a leading center for healthcare innovation, Berlin benefits from a strong infrastructure that supports advanced medical research, development, and manufacturing. The region hosts numerous biomedical technology parks, research institutions, and universities that foster innovation and collaboration between academia and industry. Berlin’s highly skilled workforce and the availability of cutting-edge facilities make it a preferred location for both domestic and international companies seeking contract manufacturing services. Moreover, the city’s supportive regulatory and funding environment attracts startups and established manufacturers alike, contributing to sustained investment and market growth. Berlin’s strategic location also enables efficient logistics and distribution across Germany and the broader European Union, further solidifying its position as a central hub for medical device contract manufacturing.
Munich
Munich represents around 26% of the Germany medical device contract manufacturing market and is a significant driver of innovation in the southern region of the country. The city is known for its strong industrial base and advanced engineering capabilities, which are crucial for the production of complex and high-risk medical devices, such as Class III implants and surgical systems. Munich is home to a cluster of medical device companies and research centers that collaborate closely to bring advanced technologies to market. The presence of globally recognized institutions and a favorable investment climate contribute to Munich’s leadership in specialized contract manufacturing services, including device design, assembly, and component production. In addition, the Bavarian government actively supports the life sciences sector through grants and infrastructure development, further enhancing Munich’s attractiveness as a manufacturing hub.
Hamburg
Hamburg holds a 22% share of the national medical device contract manufacturing market and is recognized for its well-developed logistics and export infrastructure. As one of Germany’s primary port cities, Hamburg serves as a key gateway for international trade, making it an ideal location for manufacturers focused on global distribution. The city hosts several manufacturing firms specializing in device assembly, packaging, and labelling services, particularly for export-oriented products. Hamburg's proximity to Northern European markets and its strong transportation network allow for efficient movement of goods, reducing lead times and logistics costs. Additionally, the region’s commitment to innovation in healthcare technologies and its expanding medical technology ecosystem position Hamburg as a rising player in the contract manufacturing space, especially for companies targeting cross-border operations.
Bremen
Bremen contributes approximately 20% to Germany’s medical device contract manufacturing market and is emerging as a growing center for precision manufacturing and innovation. Known for its expertise in aerospace and engineering, Bremen has successfully transferred its technical capabilities to the medical sector, supporting the production of high-precision components and devices. The region is increasingly attracting investment in biomedical engineering and contract manufacturing services, particularly in the area of customized and minimally invasive devices. Bremen’s academic institutions and innovation clusters provide a strong foundation for research and workforce development, enabling the city to meet the sophisticated demands of modern medical device production. Though smaller in scale compared to Berlin and Munich, Bremen’s niche focus and technical strengths make it a competitive and strategically important player in Germany’s medical device manufacturing landscape.
Key Player Analysis
- Medtronic
- Vention Medical
- Sartorius Stedim Biotech
- Fiedler GmbH
- Hapman GmbH
Competitive Analysis
The competitive landscape of the Germany medical device contract manufacturing market is characterized by the presence of both global leaders and specialized domestic players. Leading companies such as Medtronic, Vention Medical, Sartorius Stedim Biotech, Fiedler GmbH, and Hapman GmbH are driving market growth through innovation, strategic partnerships, and expanded service offerings. These players compete primarily on technological expertise, regulatory compliance, and the ability to deliver high-quality, customized manufacturing solutions. Companies in this space are continuously investing in advanced technologies such as robotics, AI, and precision engineering to meet the growing demand for complex and customized medical devices. The ability to offer integrated services from component production to final assembly and packaging—has become a key differentiator, allowing manufacturers to cater to OEMs seeking streamlined and cost-effective solutions. Compliance with the European Union’s Medical Device Regulation (MDR) also plays a critical role in shaping competition, as only companies with robust quality management systems and documentation processes can maintain market access. Furthermore, partnerships, acquisitions, and collaborations are commonly used strategies to expand capabilities and enter new market segments. As demand increases for high-performance, patient-specific medical devices, competition continues to intensify, pushing manufacturers to enhance both technical capabilities and operational efficiency.
Recent Developments
- In February 2025, Jabil completed the acquisition of Pii, a contract development and manufacturing organization (CDMO) specializing in aseptic filling, lyophilization, and oral solid dose manufacturing.
- In November 2024, Integer completed the sale of its non-medical Electrochem business for $50 million, making it a pure-play medical technology company and allowing it to redeploy capital into high-growth medtech markets.
- In October 2024, At CPHI Milan 2024, Thermo Fisher launched its Accelerator Drug Development platform, a 360° CDMO and CRO offering. This service provides customizable manufacturing, clinical research, and supply chain solutions for small molecules, biologics, and cell and gene therapies, covering the full drug development lifecycle.
Market Concentration & Characteristics
The Germany medical device contract manufacturing market exhibits a moderate to high level of market concentration, characterized by the presence of a few well-established players that dominate key service segments. These companies possess advanced technological capabilities, strong regulatory expertise, and the infrastructure required to handle complex, high-precision manufacturing processes. The market is shaped by high entry barriers due to stringent EU regulatory requirements, capital-intensive operations, and the need for specialized technical knowledge. As a result, established firms maintain a competitive edge through integrated service offerings, including design support, prototyping, manufacturing, packaging, and regulatory compliance. Despite the dominance of larger players, opportunities exist for smaller and mid-sized firms to thrive in niche areas such as customized components, rapid prototyping, or eco-friendly device solutions. The industry is defined by its focus on innovation, quality assurance, and strategic partnerships with OEMs, with a growing emphasis on automation, sustainability, and digital integration to meet evolving healthcare demands.
Report Coverage
The research report offers an in-depth analysis based on Class, Services, End-Use, Therapeutic Area and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Germany's medical device contract manufacturing sector is expected to experience steady growth due to increasing demand for high-quality healthcare products.
- Technological advancements, such as automation and AI integration, will significantly enhance production efficiency and reduce costs.
- Regulatory compliance and quality standards will remain central to the industry, with manufacturers needing to adapt to evolving European Union medical device regulations.
- Outsourcing manufacturing to Germany will continue to attract global companies due to its advanced infrastructure and skilled workforce.
- The rising aging population in Europe will drive the need for innovative medical devices, further boosting contract manufacturing opportunities.
- There will be an increasing focus on sustainable and eco-friendly manufacturing processes, aligning with global environmental goals.
- Collaborative partnerships between device manufacturers and contract manufacturers will intensify, fostering innovation and expanding product portfolios.
- Customization and personalized medicine will become more prevalent, requiring flexible manufacturing capabilities to meet diverse customer needs.
- The COVID-19 pandemic has highlighted the need for rapid response manufacturing, driving investments in agile production systems.
- The demand for precision manufacturing, particularly in areas like implants and diagnostic equipment, will fuel growth in Germany's medical device contract manufacturing market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Germany Medical Device Contract Manufacturing?
What factors are driving the growth of the Germany Medical Device Contract Manufacturing?
What are the key segments within the Germany Medical Device Contract Manufacturing?
Who are the major players in the Germany Medical Device Contract Manufacturing?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany Medical Device Contract Manufacturing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Germany Medical Device Contract Manufacturing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 3,611.52 million → forecast year: USD 8,921.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany Medical Device Contract Manufacturing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany Medical Device Contract Manufacturing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany Medical Device Contract Manufacturing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Germany Medical Device Contract Manufacturing Market Drivers
- 3.3 Germany Medical Device Contract Manufacturing Market Restraints & Challenges
- 3.4 Germany Medical Device Contract Manufacturing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany Medical Device Contract Manufacturing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany Medical Device Contract Manufacturing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany Medical Device Contract Manufacturing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany Medical Device Contract Manufacturing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Germany Medical Device Contract Manufacturing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Germany Medical Device Contract Manufacturing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany Medical Device Contract Manufacturing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Germany Medical Device Contract Manufacturing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Germany Medical Device Contract Manufacturing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany Medical Device Contract Manufacturing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Germany Medical Device Contract Manufacturing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Germany Medical Device Contract Manufacturing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Germany Medical Device Contract Manufacturing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Germany Medical Device Contract Manufacturing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Germany Medical Device Contract Manufacturing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Germany Medical Device Contract Manufacturing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Germany Medical Device Contract Manufacturing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Germany Medical Device Contract Manufacturing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Germany Medical Device Contract Manufacturing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
