
Buyers pay for verified footprints as green steel scales
The green steel market was valued at USD 10.88 billion in 2025 and is projected to increase from USD 12.53 billion in 2026 to USD 58.60 billion by 2035, registering a CAGR of 18.34% during 2025–2035. Demand comes from carmakers with supply-chain emissions targets, builders facing carbon limits and buyers that need labels they can verify, even though world crude steel output fell 2.0% in 2025. Europe held the largest regional share, 33.7% in 2025, because buyers there pay the highest premiums. Scrap-based electric arc furnaces running on low-carbon power supplied most of 2025 value, and hydrogen-based plants matter more for the forecast than for the base. The main regulatory change is the EU Carbon Border Adjustment Mechanism, which entered its definitive regime on Jan. 1, 2026, and puts a carbon price on imported iron and steel.
Which steel counts as green, and who pays the premium?
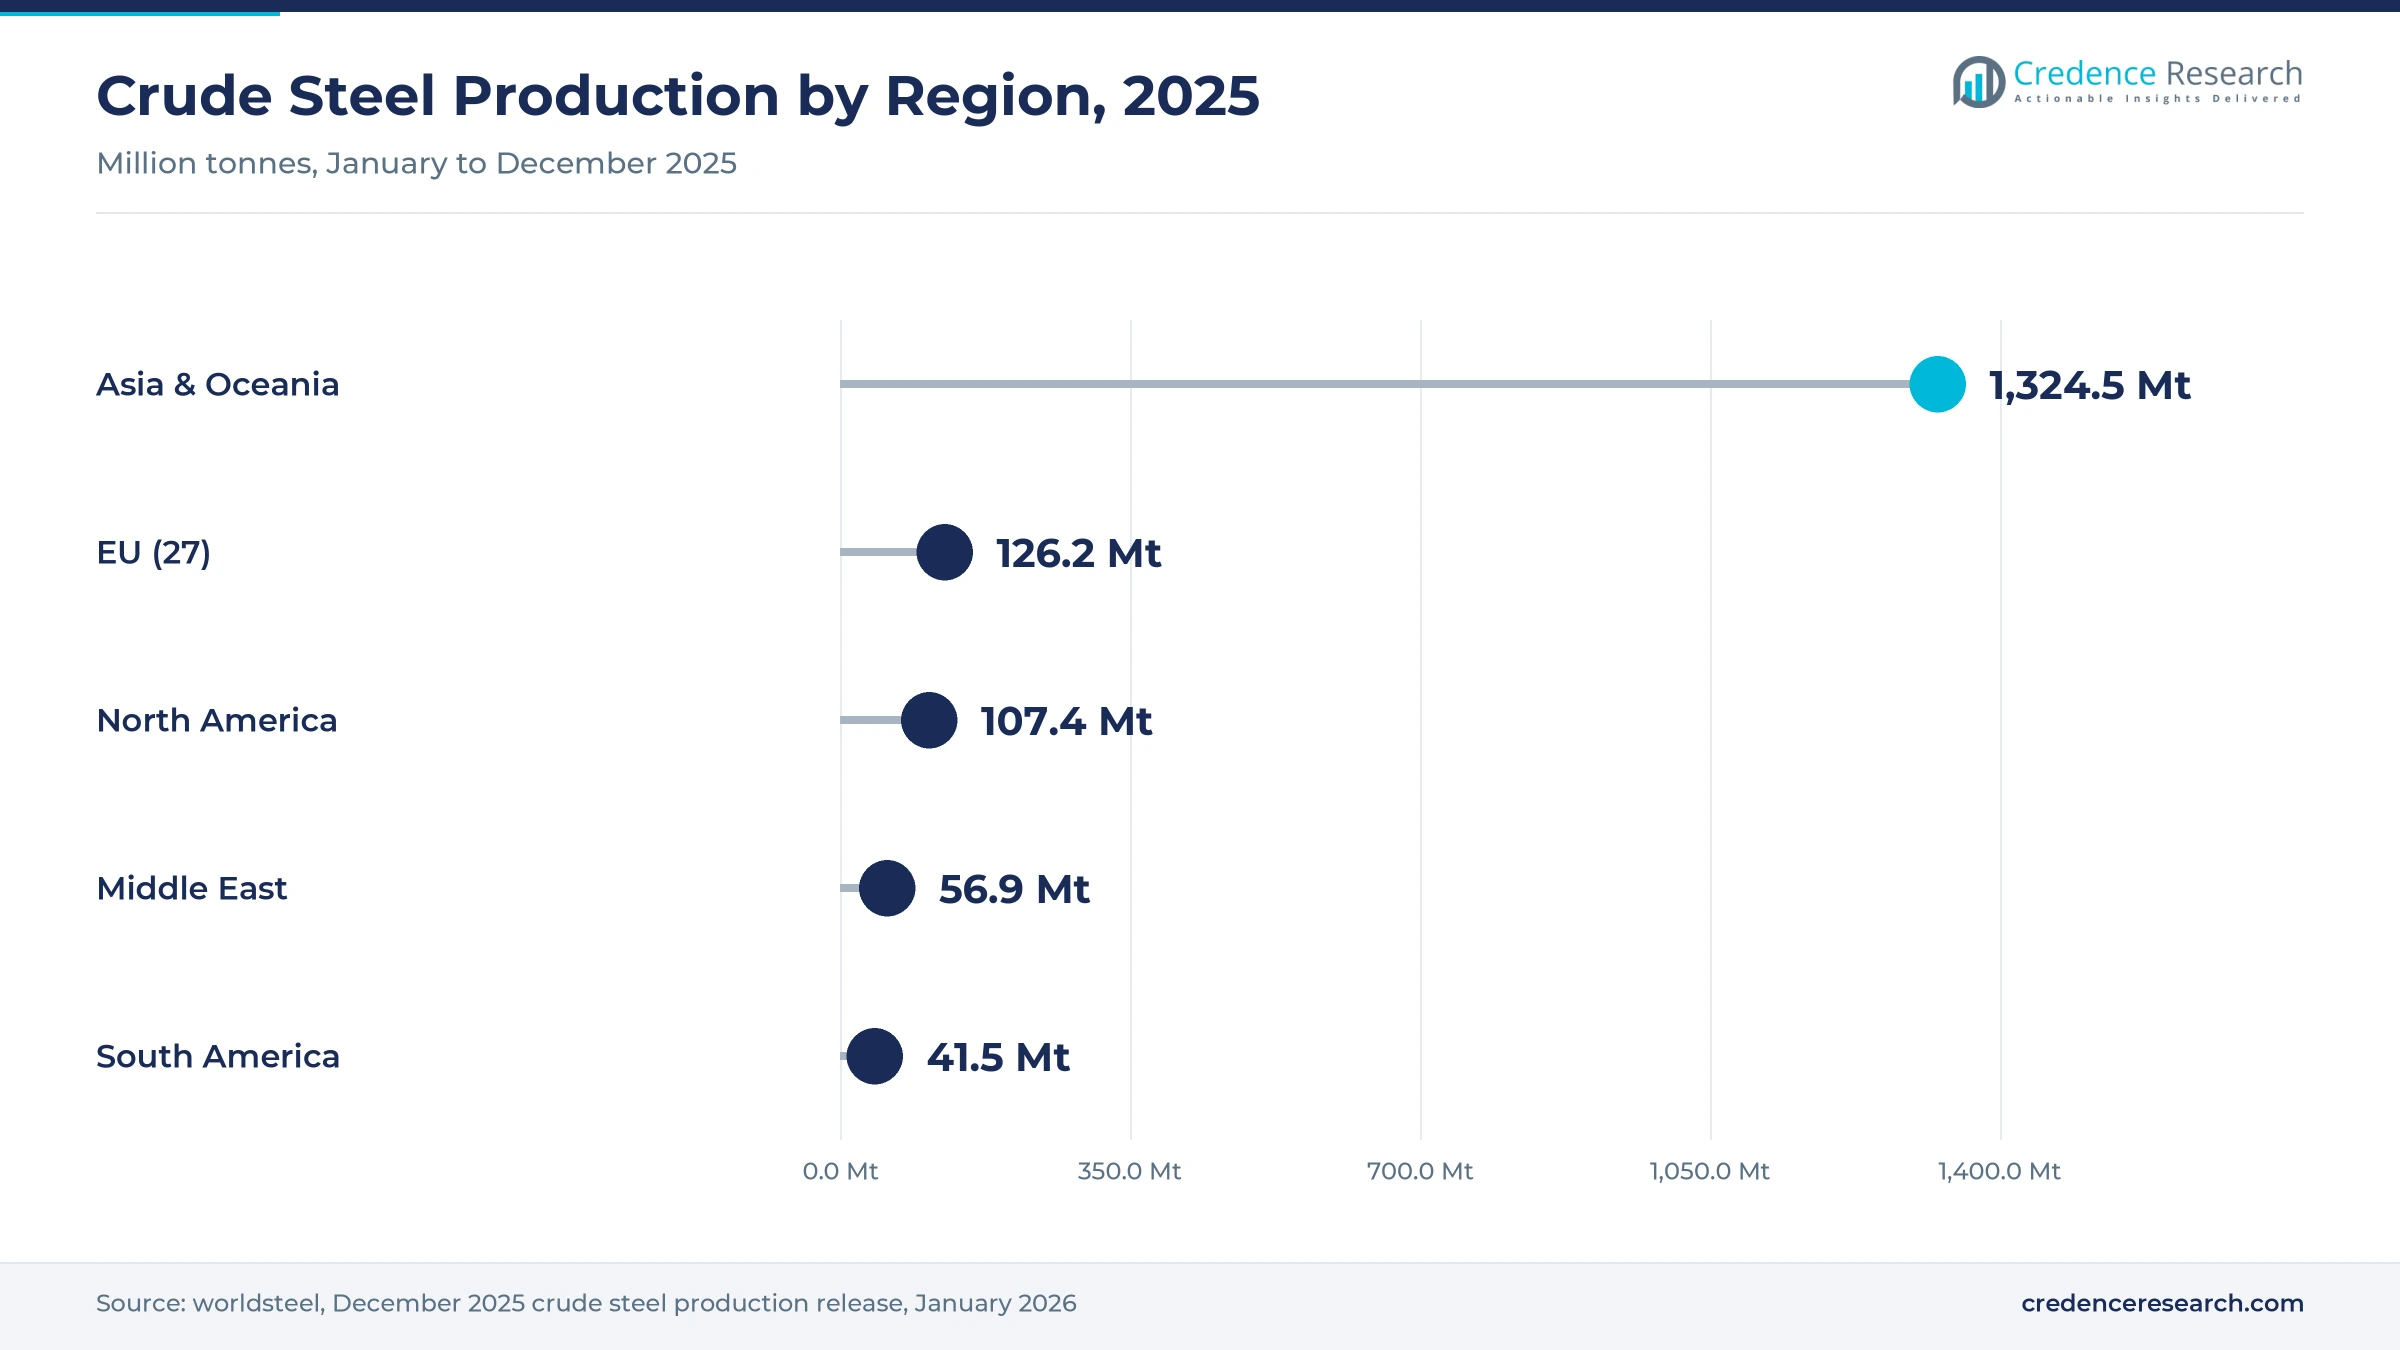
Green steel is a thin slice of a very large industry, as worldsteel reported 1,803.8 million metric tons of crude steel from 70 reporting countries in 2025, and only a small part of electric-furnace output is sold with a verified claim and a premium. Buyers include carmakers, builders, machinery makers and companies outside steel that buy environmental attribute certificates, and producers earn the premium only when a customer can verify the footprint.
The scope covers 4 production routes, namely scrap-based electric arc furnace steel on low-carbon power, steel from hydrogen or gas-based direct reduced iron melted in electric furnaces, steel from plants that capture most process carbon dioxide, and emerging routes such as molten oxide electrolysis. It excludes mass-balance and offset-only blast furnace steel, ordinary electric-furnace steel sold without a claim, and merchant iron.
Green Steel Market Insights
- The green steel market is projected to rise from USD 12.53 billion in 2026 to USD 58.60 billion by 2035, an 18.34% CAGR, even as world crude steel output fell in 2025.
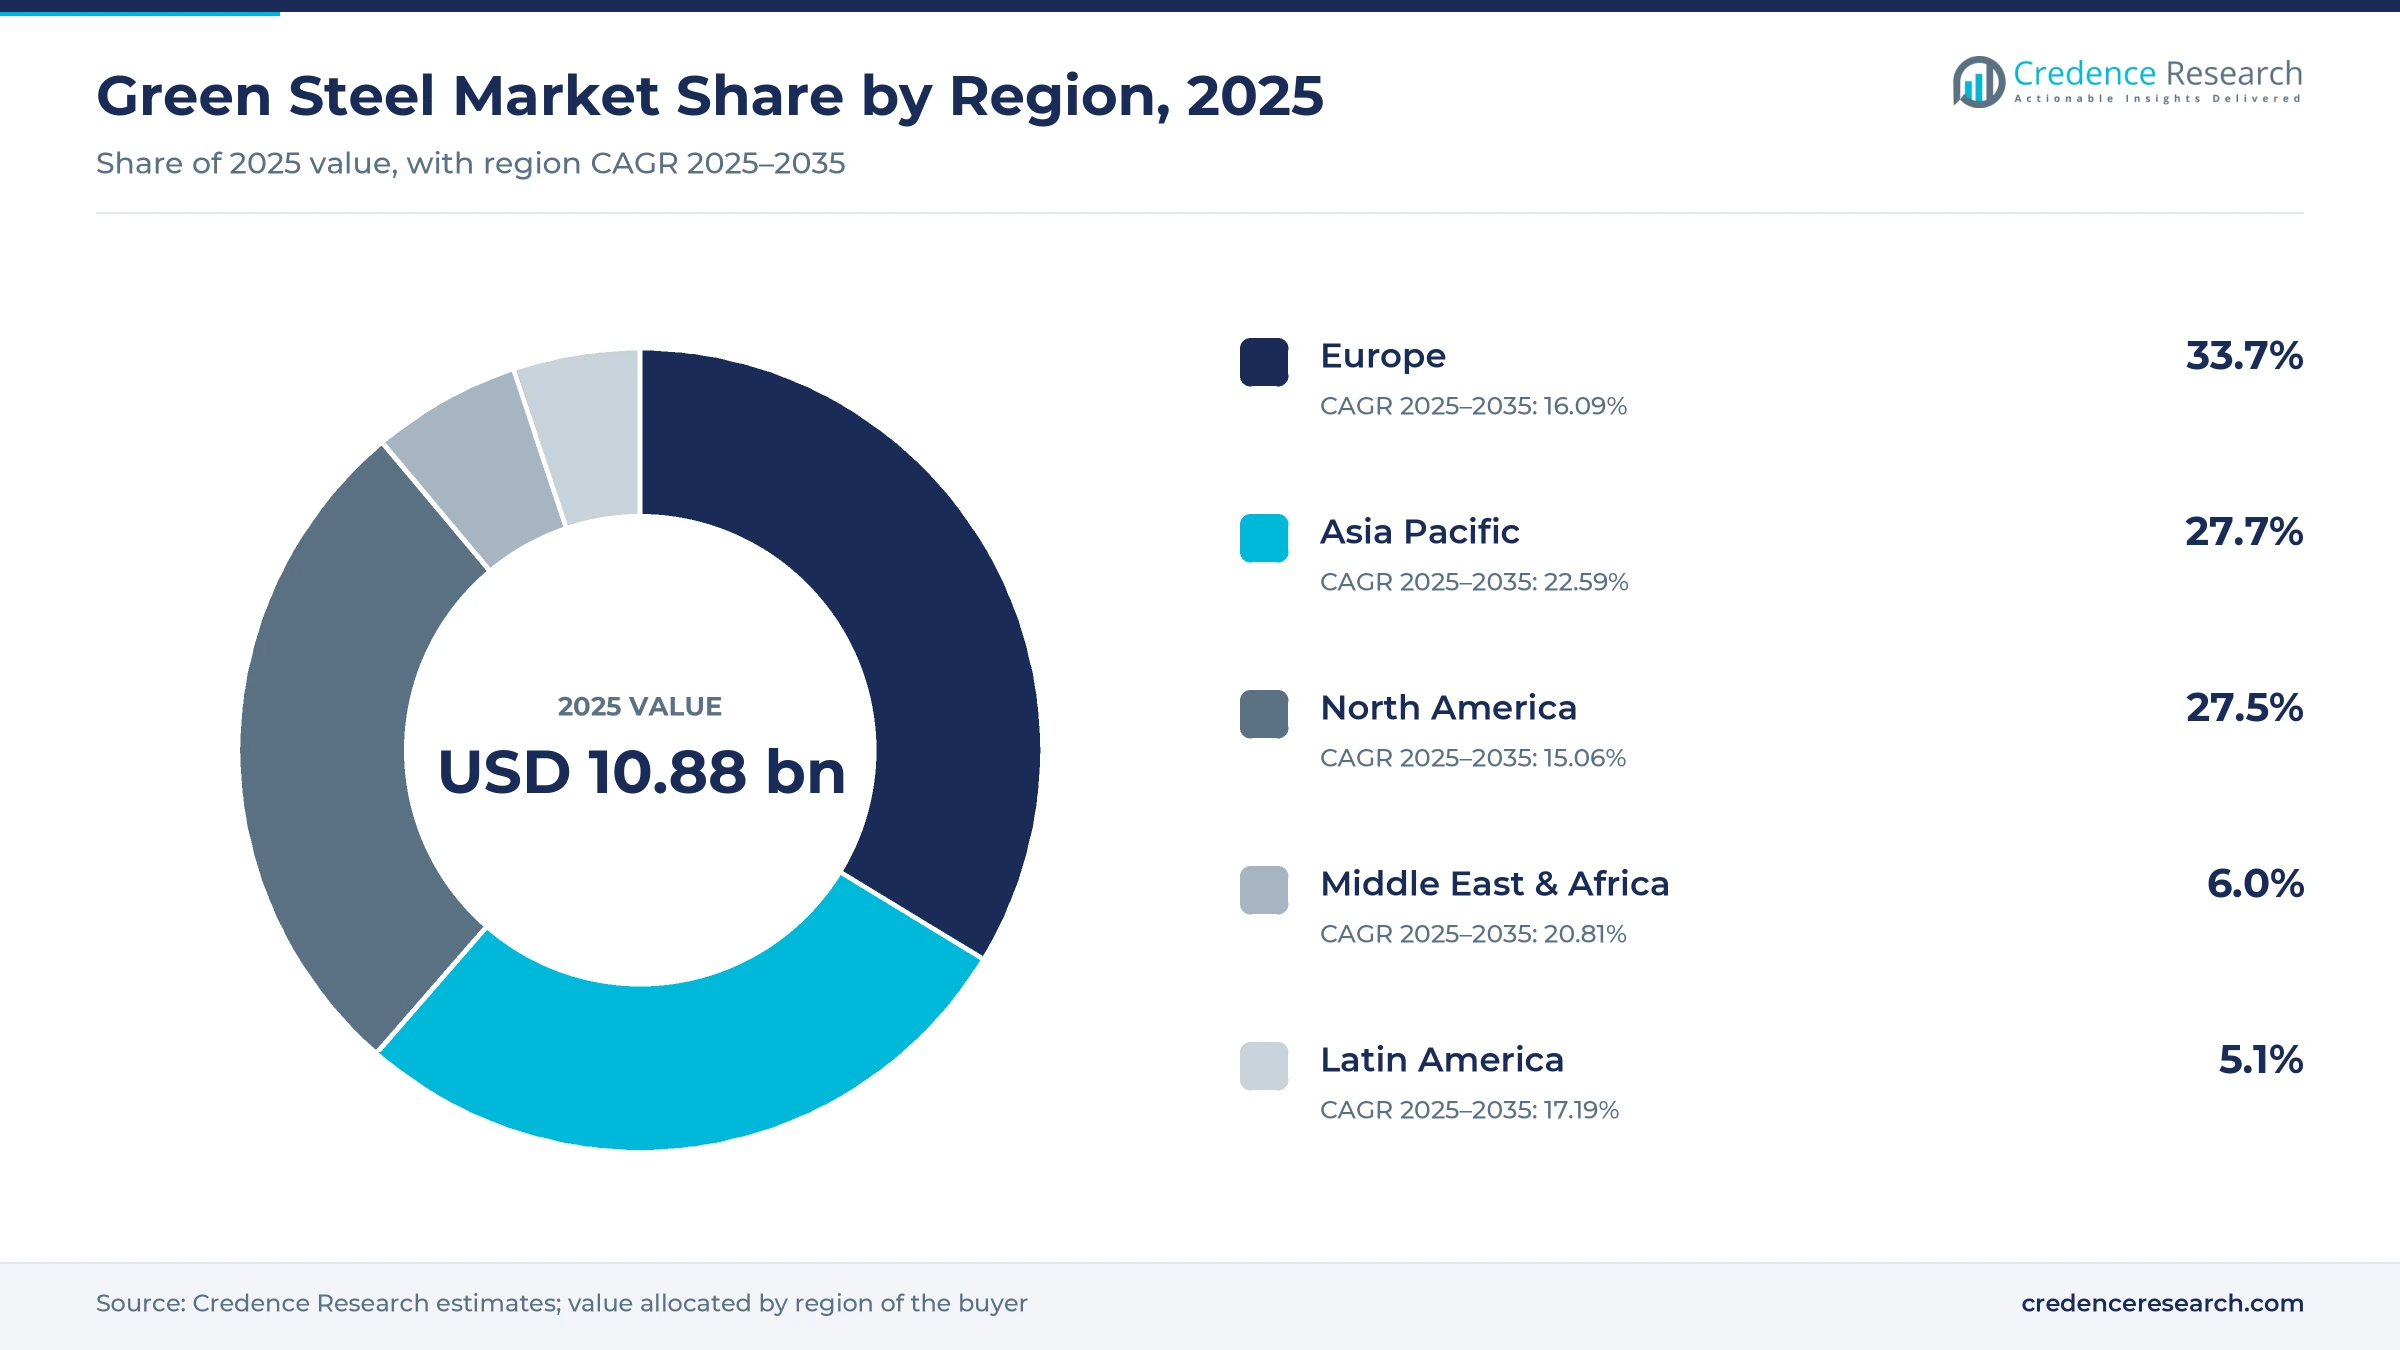
- Europe held 33.7% of 2025 value, the largest regional share, because carbon border pricing and automaker contracts give European buyers the highest willingness to pay.
- Scrap-based electric arc furnace steel on low-carbon power accounted for 86.2% of 2025 value, the largest route, because it needs only clean power and a credible label.
- Supply is shifting from labels to new iron, as hydrogen and gas-based DRI-EAF steel is the fastest-growing route at 33.76% a year through 2035.
- In September 2026, Google signed an agreement with Stegra for environmental attribute certificates tied to Boden steel, bringing a large buyer from outside steel into the market.
Scrap furnace steel leads while hydrogen iron sets the pace
Scrap-based electric furnaces lead the technology mix while hydrogen and gas DRI grows fastest
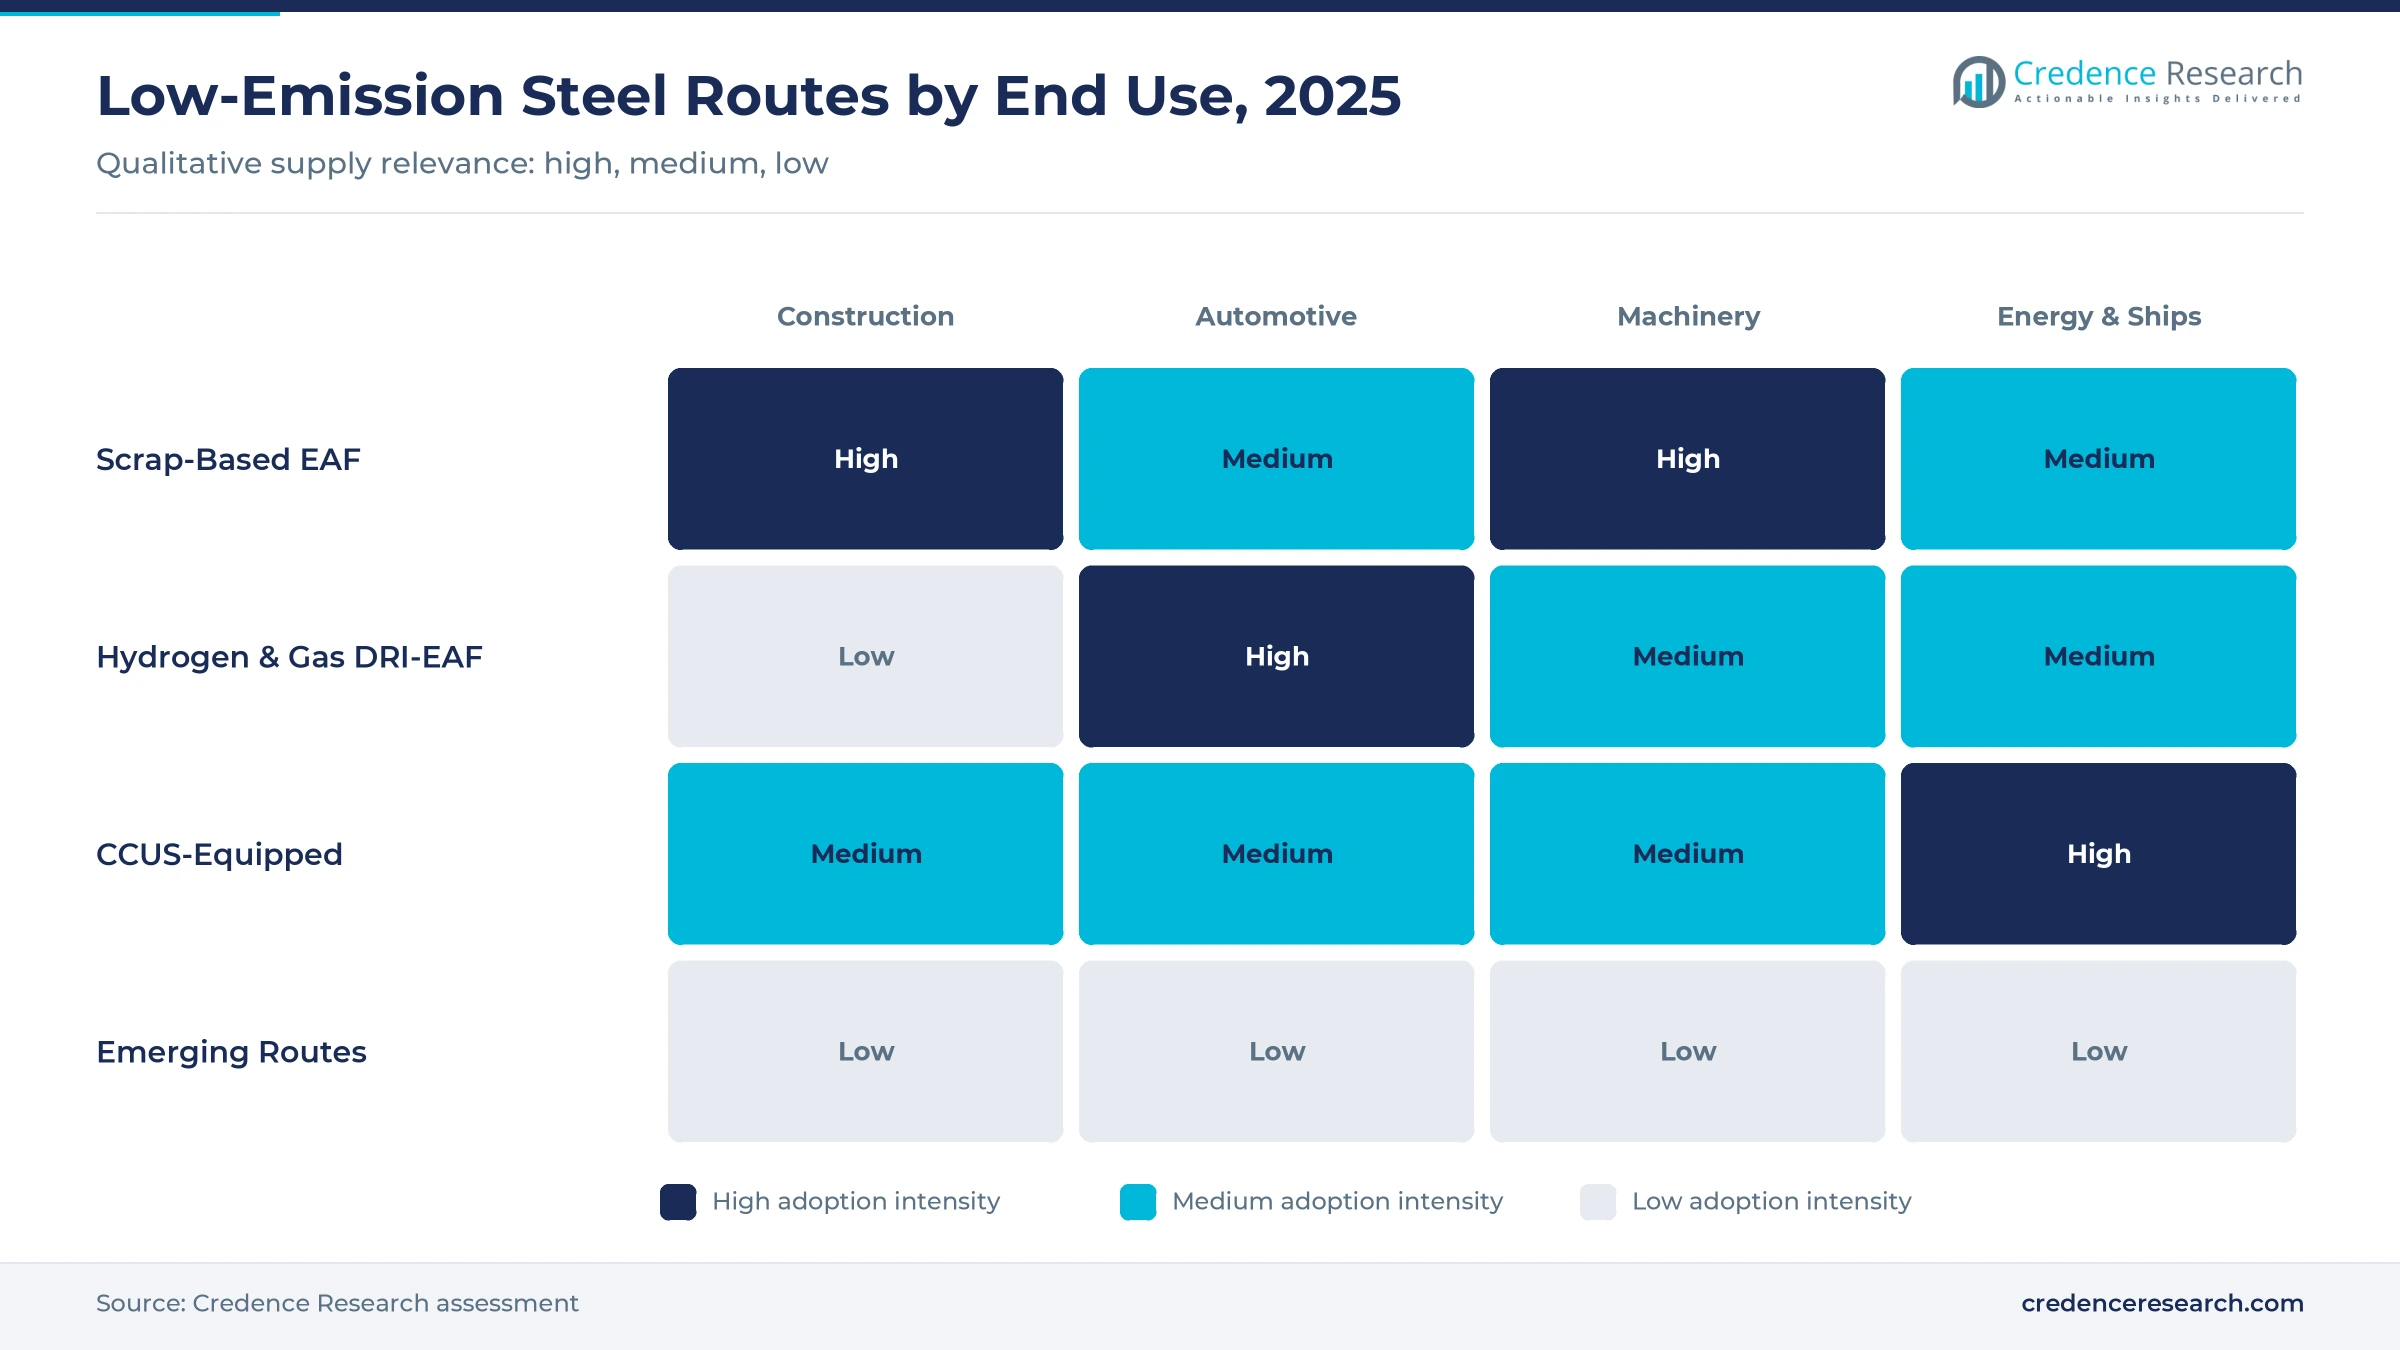
Based on technology, the market is categorized into scrap-based EAF with low-carbon power, hydrogen and gas-based DRI-EAF, CCUS-equipped steelmaking and emerging routes. Scrap-based EAF steel led with 86.2% of 2025 value, because it is the cheapest proven route to a low footprint and supplies most long products sold as green. Hydrogen and gas-based DRI-EAF grows fastest at 33.76% a year as plants at Boden, Duisburg and Zhanjiang ramp up, which favors producers with cheap power and pellets.
Construction leads by end use while automotive grows fastest
Based on end-use industry, the market is categorized into construction, automotive, machinery and equipment, and others, which include energy, shipbuilding and appliances. Construction led with 37.4% of 2025 value, because rebar and sections are made mostly from scrap and building carbon rules reward them. Automotive grows fastest at 19.86% a year, as carmakers need high-quality flat steel and anchor offtake for new hydrogen-based iron plants.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Technology | Scrap-Based EAF with Low-Carbon Power | 86.2% | Hydrogen & Gas-Based DRI-EAF | 33.76% |
| By End-Use Industry | Construction | 37.4% | Automotive | 19.86% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Border carbon prices, carmakers and certificates lift demand
The EU carbon border mechanism puts a price on embedded emissions
Since Jan. 1, 2026, the EU Carbon Border Adjustment Mechanism has applied under its definitive regime, and iron and steel are 1 of its six sectors. Importers now pay for the emissions embedded in steel at a price linked to the EU emissions trading system, and as free allowances for EU producers phase out, the same cost reaches domestic blast furnaces. As a result, low-emission steel now competes with blast furnace steel on a cost line buyers can calculate, which keeps Europe the largest region.
Carmakers sign multi-year offtake deals to meet supply-chain targets
Steel is one of the largest sources of embedded emissions in a car, and automakers cannot meet their supply-chain targets with blast furnace steel alone. Carmakers therefore sign multi-year supply deals, pay premiums and accept early volumes from new plants. For example, Nucor supplies Econiq RE steel for Mercedes-Benz in Alabama. As a result, automotive grows fastest among end uses at 19.86% a year, ahead of construction and machinery.
Converging definitions lower the cost of proving a claim
In November 2024, the International Energy Agency reviewed definitions for near-zero and low-emissions steel and found the main proposals converging on similar thresholds. ResponsibleSteel certifies sites against four progress levels, and sites need at least level 1 to market certified steel. Nucor has sold its Econiq net-zero certification since October 2021. These shared thresholds matter most for scrap-based electric furnace producers, which hold 86.2% of 2025 value and need only a credible label to earn a premium.
Certificate buyers outside steel fund early near-zero volumes
In September 2026, Google signed an agreement with Stegra to buy environmental attribute certificates tied to near-zero steel from Boden, Sweden, to address steel-related emissions from its own operations, including datacenter construction. Under this model, the physical steel goes to one buyer without green claims and the certificates to another, so the cut is counted once. Book-and-claim lets early plants sell their emissions advantage before nearby buyers can absorb the full volume, and partners are building a registry to track each claim.
Furnace swaps lead while gas-fed iron bridges to hydrogen
European mills shift from blast furnaces to electric furnaces
On July 28, 2026, Salzgitter's HKM subsidiary signed with Tenova for an electric arc furnace in Duisburg due for completion in 2029, and on Sept. 19, 2026, HKM tapped Blast Furnace A for the last time. Tata Steel is building a large electric furnace at Port Talbot and SSAB another at Oxelösund. In June 2025, ArcelorMittal Europe said it would not proceed with DRI projects at Bremen and Eisenhüttenstadt and planned its next furnace at Dunkirk.
Natural gas bridges the gap to hydrogen iron
Thyssenkrupp states that green hydrogen is unlikely to be available when its Duisburg direct reduction plant starts, so the plant will run on natural gas first and switch later at a pace set by pipelines and the hydrogen electrolyzer build-out. The company targets climate-neutral steelmaking by 2045 at the latest. Gas-fed DRI already cuts emissions sharply, and the route grows fastest at 33.76% a year.
Near-zero lines in China and Korea open an opportunity
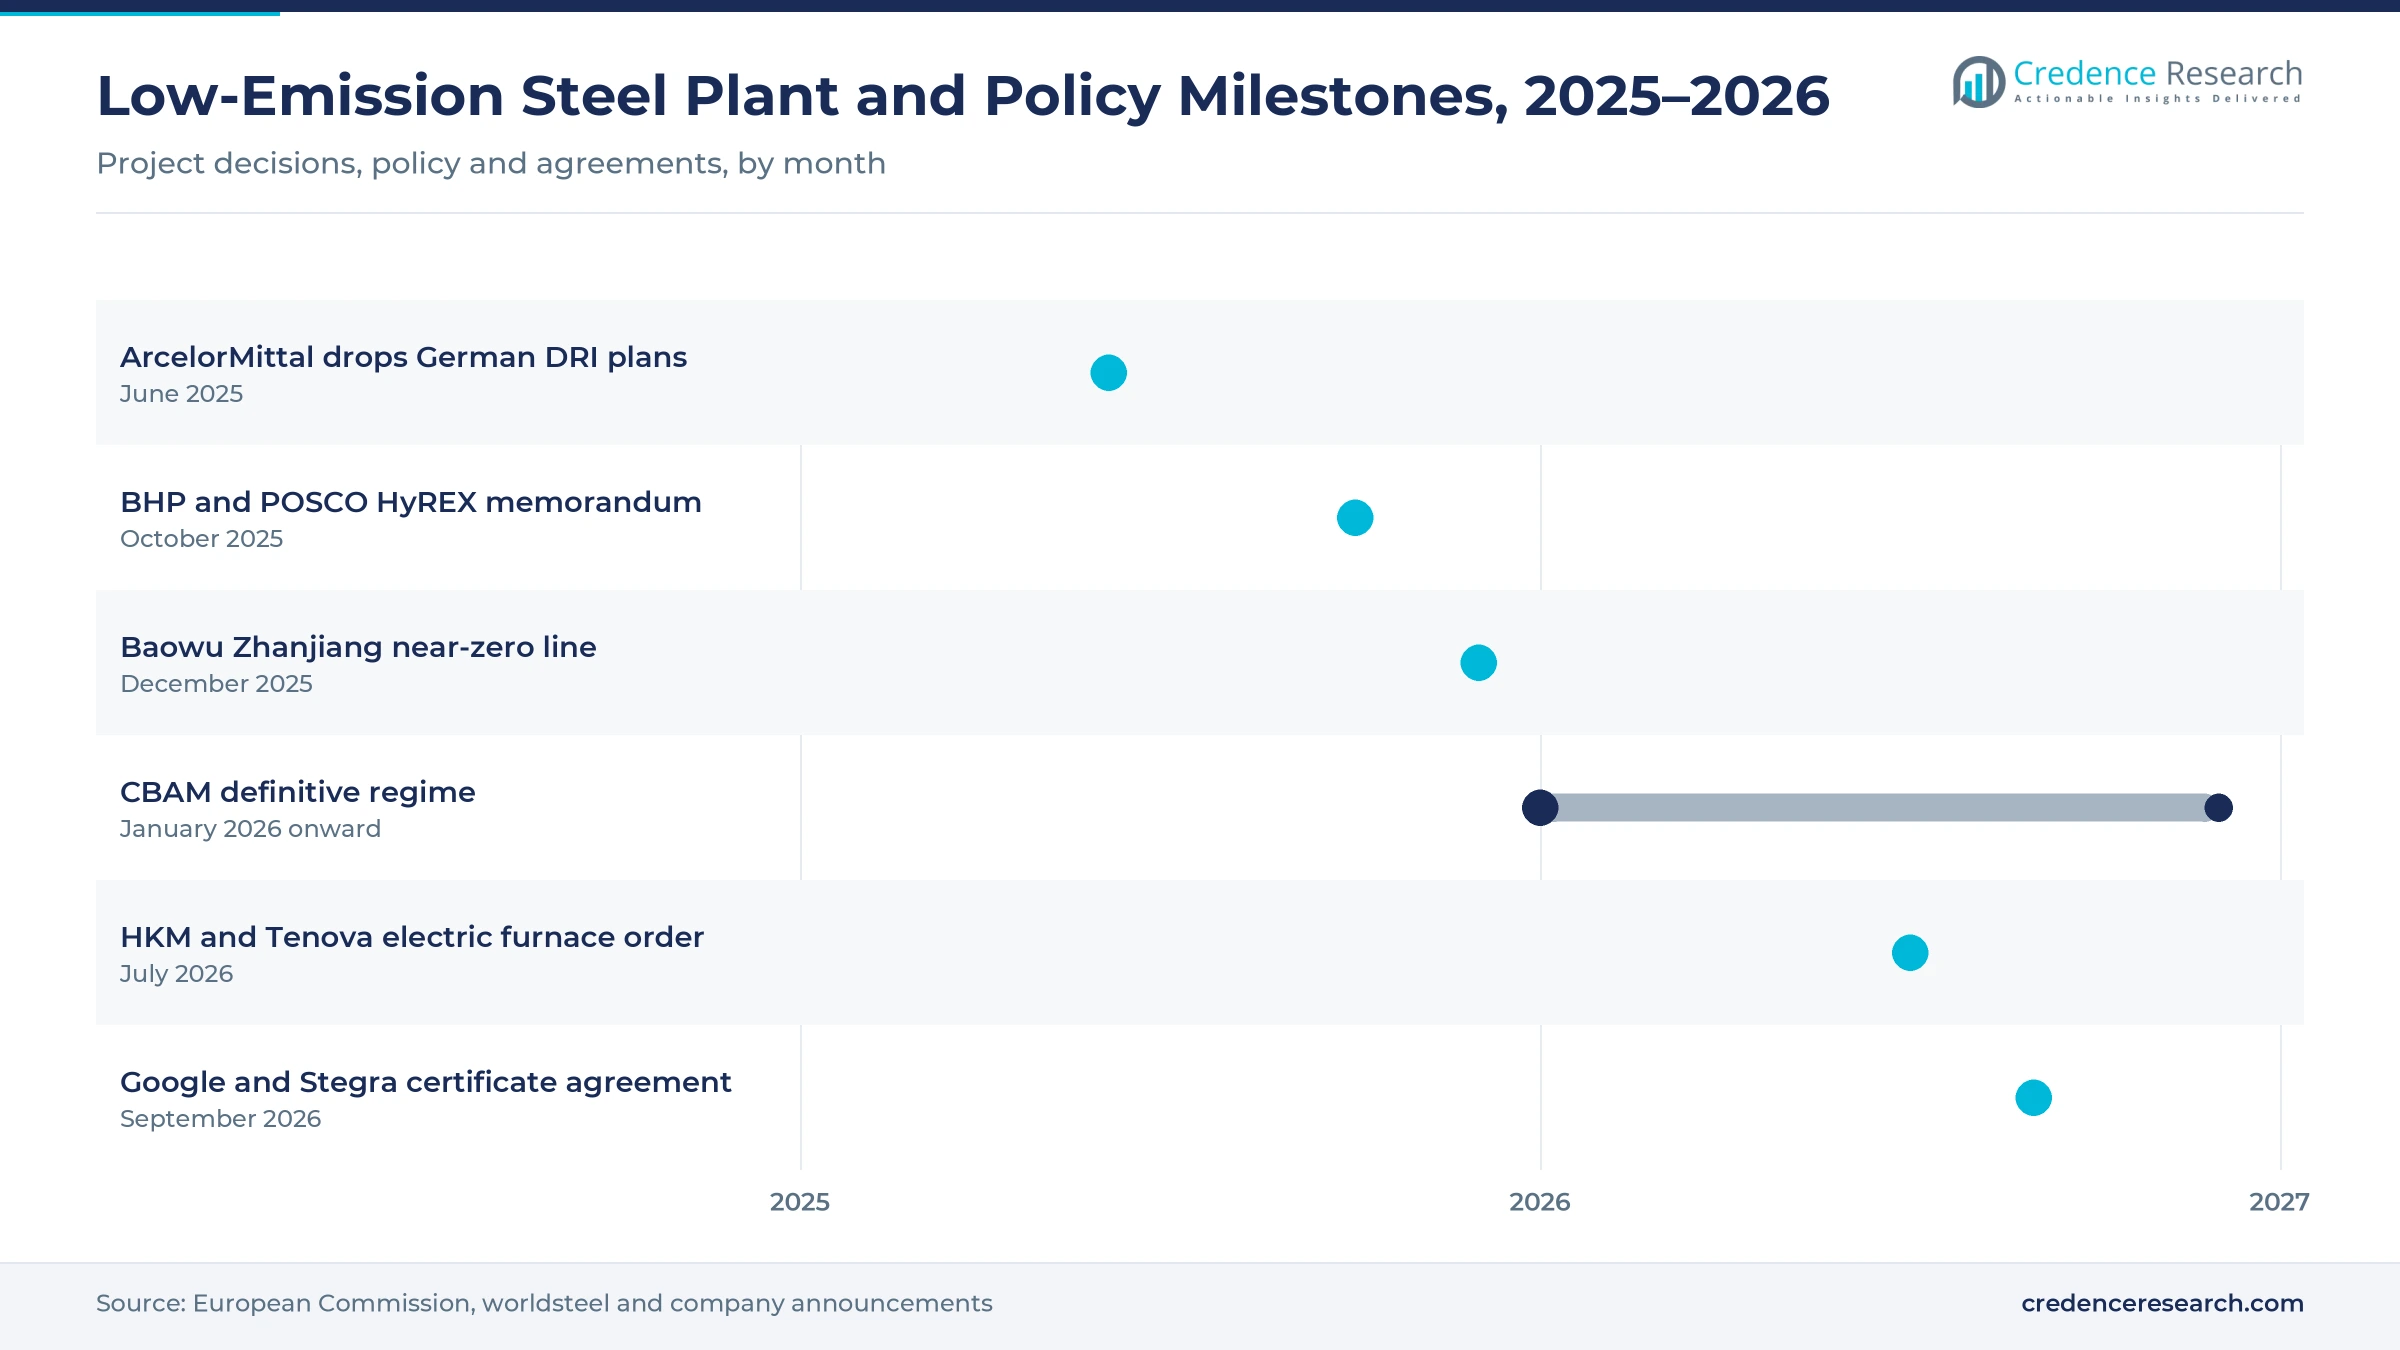
In December 2025, China Baowu fully connected China's first large near-zero-carbon line at Zhanjiang, pairing a hydrogen-based shaft furnace with electric furnaces and reporting emission cuts of 50% to 80%. China made about 52% of world crude steel in 2025, so small shifts there move global supply. In October 2025, BHP and POSCO signed a memorandum to advance HyREX, with commissioning targeted for 2028, and projects like these help Asia Pacific grow fastest at 22.59% a year.
Gulf iron plants have an opportunity to sell into Europe
Where cheap gas, solar power and iron ore meet, new primary capacity can serve European buyers under the border mechanism. Emirates Steel Arkan pairs direct reduction with carbon capture in Abu Dhabi, and the Middle East & Africa grows at 20.81% a year. Ore quality is the constraint, because direct reduction needs high-grade pellets. Producers that secure pellet supply and long offtake contracts can export low-emission steel or iron at scale.
Late flagships, weak output and costly power slow the shift
Flagship hydrogen plants run late on financing, permits and grids
Stegra closed a financing round led by Wallenberg Investments on June 24, 2026, and said its project timeline was under review, and on Oct. 6, 2026, it reorganized the Boden project into delivery areas. SSAB reported on May 11, 2026, that appeals over species protection would delay the grid connection for its Oxelösund furnace, and together these delays push hydrogen-based volume into the 2030s. Producers respond by phasing delivery and starting with electric furnaces fed by scrap.
Falling steel output limits room for a premium
World crude steel output from the 70 countries reporting to worldsteel fell 2.0% to 1,803.8 million metric tons in 2025, and European mills face high imports and weak construction. Many buyers still pay a premium only for small volumes, and ArcelorMittal cited weak demand when it dropped its German DRI plans. Producers mitigate the risk with multi-year offtake contracts, certificate sales and the cost support that border carbon pricing gives low-emission steel inside the EU.
Costly power and tight scrap grades cap electric routes
Electric routes need cheap, firm low-carbon power and in much of Europe power prices remain high. Scrap is tight in the grades suited to flat products for cars, so mills blend in virgin iron units. Both limits slow growth outside the Nordics, the Gulf and parts of North America, where the region grows at 15.06% a year. Producers respond with long-term power purchase agreements, scrap sorting and imported direct reduced iron that dilutes impurities.
Competing labels blur what buyers are paying for
Mass-balance products, offset-based claims and physical low-emission steel are sold side by side under similar names. Buyers who mix them up pay a premium for very different emissions cuts, which can undermine trust and slow procurement. Converging definitions and site certification reduce that risk, and this report excludes mass-balance and offset-only products so that value reflects steel whose production route changed.
Europe pays most while Asian near-zero lines grow fastest
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| Europe | 33.7% | 16.09% |
| Asia Pacific | 27.7% | 22.59% |
| North America | 27.5% | 15.06% |
| Middle East & Africa | 6.0% | 20.81% |
| Latin America | 5.1% | 17.19% |
Europe earns the highest premiums on border carbon pricing and automaker demand
Europe held 33.7% of 2025 value and grows at 16.09% a year. The border mechanism, automaker demand and Nordic hydrogen projects support the region, while delays at Boden and Oxelösund and the German DRI cancellations slow primary output. The Dutch state, Noord-Holland and Tata Steel signed a letter of intent on Sept. 29, 2025, to cut emissions at IJmuiden.
Asia Pacific starts near-zero lines from a large production base
Asia Pacific held 27.7% of 2025 value and is the fastest-growing region at 22.59% a year. China Baowu's Zhanjiang line, POSCO's HyREX demonstration targeted for 2028 commissioning and India's green steel taxonomy drive growth from the world's largest production base, as China alone made about 52% of world crude steel in 2025. Scrap supply in China will rise as steel built over two decades of construction returns as scrap, which supports electric furnace output and lowers the cost of low-emission long products.
North America already relies on electric furnaces for most steelmaking
North America held 27.5% of 2025 value and grows at 15.06% a year. Electric furnaces dominate U.S. steelmaking, so certified low-emission steel builds on an existing scrap-based base rather than new plants. Nucor sells Econiq-certified products, including renewable-powered Econiq RE for Mercedes-Benz in Alabama, and SSAB Americas sells SSAB Zero from its U.S. mills. Slower growth reflects the absence of a border carbon price in the region, which keeps premiums below European levels.
Middle East & Africa and Latin America build on gas-based iron and charcoal ironmaking
The Middle East & Africa held 6.0% of 2025 value and grows at 20.81% a year, as Gulf DRI plants with cheap gas, solar power and carbon capture, led by Emirates Steel Arkan, target buyers in Europe. Latin America held 5.1% of 2025 value and grows at 17.19% a year. Brazil's scrap-based mills and charcoal-based ironmaking give it a low-footprint base, with Gerdau the largest supplier.
Border pricing, near-zero lines, furnace orders, 2025–2026
| Development | Status and market relevance |
|---|---|
| In September 2026, Google signed an agreement with Stegra for environmental attribute certificates tied to steel from Boden, Sweden. | Signed. Brings a large buyer from outside steel into the market. |
| In July 2026, Salzgitter's HKM subsidiary signed with Tenova for an electric arc furnace in Duisburg, due for completion in 2029. | Ordered. Replaces blast furnace capacity with electric steelmaking. |
| In January 2026, the EU Carbon Border Adjustment Mechanism entered its definitive regime, covering iron and steel imports. | In force. Puts a carbon price on steel entering the EU. |
| In December 2025, China Baowu fully connected its hydrogen-based near-zero-carbon line at Zhanjiang. | Operating. Brings China into primary low-emission steel at scale. |
| In October 2025, BHP and POSCO signed a memorandum of understanding to advance HyREX, with commissioning targeted for 2028. | Planned. Tests hydrogen reduction of fine ore without pelletizing. |
Hydrogen reduction, scrap refining and carbon capture ahead
- Hydrogen reduction in shaft furnaces and fluidized-bed processes such as HyREX reduces iron ore with hydrogen, starting on natural gas where hydrogen is scarce.
- Scrap refining through better sorting and blending with direct reduced iron lets electric furnaces make flat grades for cars from recycled steel.
- Carbon capture suits DRI plants with concentrated carbon dioxide streams, as in Abu Dhabi, and integrated mills near storage sites.
- Emerging routes such as molten oxide electrolysis, low-temperature iron electrolysis and biocarbon reduction remain at pilot or early commercial scale before 2030.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Furnace incumbents, converting mills and start-ups compete
Supply sits with three groups, the first being large electric furnace producers that already sell most volume under low-emission labels, including Nucor through Econiq, ArcelorMittal through XCarb, SSAB through SSAB Zero and HYBRIT-based fossil-free steel, and Celsa Group and Gerdau in scrap-based long products. Integrated mills are converting blast furnace sites, mostly through electric furnaces and some through gas or hydrogen DRI, including Thyssenkrupp, Salzgitter, Tata Steel and China Baowu Steel Group; POSCO is building its HyREX demonstration and Emirates Steel Arkan pairs DRI with carbon capture. A small group of start-ups, led by Stegra, is building near-zero plants from scratch. Credence Research estimates that the top five sellers hold well under half of 2025 value, though concentration is higher in primary low-emission steel.
Companies profiled and their roles
| Company | Type | Role in the market |
|---|---|---|
| Nucor | Electric furnace producer | Econiq net-zero and Econiq RE certified steel |
| ArcelorMittal | Integrated and electric furnace producer | XCarb products; next electric furnace planned at Dunkirk |
| SSAB | Integrated and electric furnace producer | SSAB Zero and HYBRIT-based fossil-free steel; electric furnace at Oxelösund |
| Stegra | Hydrogen steel start-up | Integrated hydrogen, DRI and steel plant in Boden |
| Thyssenkrupp | Converting integrated mill | Duisburg direct reduction plant starting on natural gas |
| Salzgitter | Converting integrated mill | SALCOS program; HKM electric furnace due in 2029 |
| China Baowu Steel Group | Converting integrated mill | Hydrogen-based shaft furnace line at Zhanjiang |
| POSCO | Converting integrated mill | HyREX hydrogen reduction demonstration at Pohang |
| Tata Steel | Converting integrated mill | Electric furnace at Port Talbot; IJmuiden conversion plan |
| Emirates Steel Arkan | Gas-based DRI producer | DRI with carbon capture in Abu Dhabi |
| Gerdau | Electric furnace producer | Scrap-based long products and charcoal ironmaking in Brazil |
| Celsa Group | Electric furnace producer | Scrap-based long products in Europe |
Scrap carries the decade while hydrogen iron arrives late
Credence Research's view is that green steel grows from the bottom up, through scrap-based electric furnace steel with credible labels, rather than from flagship hydrogen plants. Those plants matter for the decade after 2028, when primary low-emission iron shifts the mix toward flat steel for cars. The largest new revenue lies in automotive offtake, border-priced imports into Europe and certificates sold to buyers outside steel. The main risk is project delay, so buyers should watch carbon border prices and plant start-ups.
How labeled sales and plant pipelines built the estimate
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built from labeled low-emission sales by producer and route and from plants under construction or with investment decisions; segment and regional splits are Credence Research estimates. Supporting evidence comes from worldsteel output data, agency definitions, company announcements and policy documents.
Primary iron plants shift the mix after 2028
Through 2035, scrap-based electric furnace steel will remain the largest source of low-emission supply, while hydrogen and gas-based iron plants lift primary output after 2028. Carmakers will anchor offtake for flat steel, and builders, whose construction segment held 37.4% of 2025 value, will follow as carbon limits tighten. Asia Pacific, which held 27.7% of 2025 value, and the Middle East & Africa, at 6.0%, will gain share as near-zero lines and Gulf iron plants scale, while Europe keeps the highest premiums. The pace will depend on power prices, project financing and how far border carbon pricing spreads.
Frequently Asked Questions
What was the size of the green steel market in 2025?
What is the forecast value and CAGR of the green steel market?
What drives demand for green steel?
Which region holds the largest share of the green steel market?
Which production route leads the green steel market?
Who are the major companies in the green steel market?
How does the EU carbon border mechanism affect green steel?
Why are hydrogen-based green steel plants delayed?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Scrap-Based EAF with Low-Carbon Power
- 1.2.2 Hydrogen & Gas-Based DRI-EAF
- 1.2.3 CCUS-Equipped Steelmaking
- 1.2.4 Emerging Routes (MOE, Electrolysis, Biocarbon)
- 1.3 By End-Use Industry
- 1.3.1 Construction
- 1.3.2 Automotive
- 1.3.3 Machinery & Equipment
- 1.3.4 Others (Energy, Shipbuilding, Appliances)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 10.88 billion → 2035: USD 58.60 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Green Steel Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Green Steel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Green Steel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Green Steel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Green Steel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Green Steel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Green Steel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Green Steel Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 10.88 billion → 2035: USD 58.60 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Green Steel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Scrap-Based EAF with Low-Carbon Power
- 12.3.7.2 Hydrogen & Gas-Based DRI-EAF
- 12.3.7.3 CCUS-Equipped Steelmaking
- 12.3.7.4 Emerging Routes (MOE, Electrolysis, Biocarbon)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Construction
- 12.4.7.2 Automotive
- 12.4.7.3 Machinery & Equipment
- 12.4.7.4 Others (Energy, Shipbuilding, Appliances)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Green Steel End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Green Steel Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Green Steel Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Green Steel Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nucor
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ArcelorMittal
- 18.4 SSAB
- 18.5 Stegra
- 18.6 Thyssenkrupp
- 18.7 Salzgitter
- 18.8 China Baowu Steel Group
- 18.9 POSCO
- 18.10 Tata Steel
- 18.11 Emirates Steel Arkan
- 18.12 Gerdau
- 18.13 Celsa Group
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

