
Market Overview:
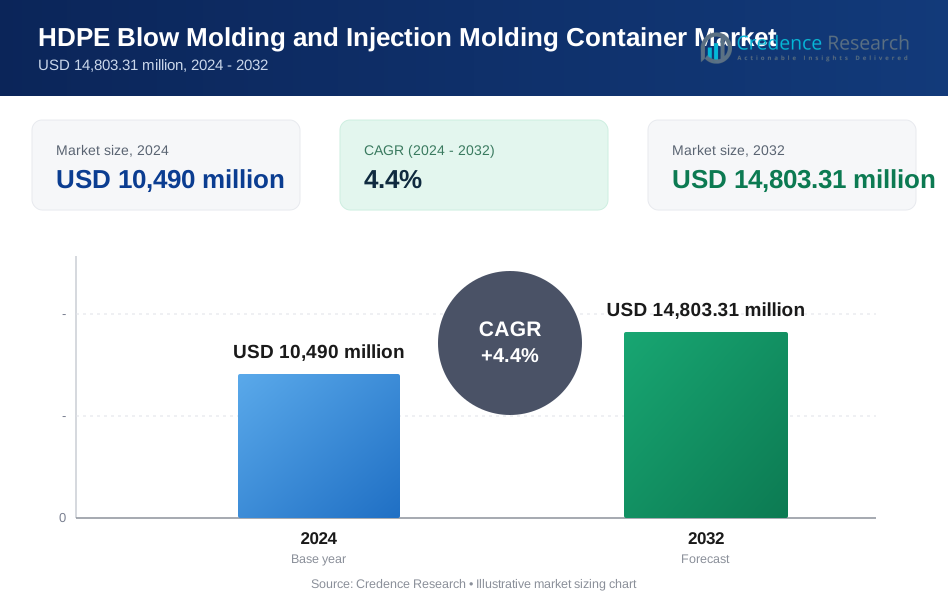
The HDPE Blow Molding and Injection Molding Container Market is projected to grow from USD 10,490 million in 2024 to USD 14,803.31 million by 2032. The market is expected to expand at a CAGR of 4.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| HDPE Blow Molding and Injection Molding Container Market Size 2024 | USD 10,490 million |
| HDPE Blow Molding and Injection Molding Container Market, CAGR | 4.4% |
| HDPE Blow Molding and Injection Molding Container Market Size 2032 | USD 14,803.31 million |
Market growth is driven by rising demand for safe and lightweight packaging solutions. Food and beverage brands favor HDPE for hygiene and shelf stability. Pharmaceutical firms rely on HDPE for chemical resistance and product safety. Personal care brands adopt molded containers for design flexibility. Industrial chemicals require leak-resistant and impact-tolerant packaging. Recycling compatibility supports sustainability goals. Cost-effective mass production strengthens adoption. Automation in molding improves output consistency. Brand owners also value customization options. These combined factors sustain steady market expansion.
Asia Pacific leads the market due to strong manufacturing activity and large consumer bases. China and India drive volume through food, chemical, and household product demand. North America remains a key market with advanced packaging standards and automation. The United States leads in pharmaceutical and personal care usage. Europe shows steady demand driven by sustainability compliance. Germany and France remain important contributors. Latin America and Southeast Asia emerge due to urbanization. Middle East demand grows with industrial packaging needs.

Market Insights:
- The market stood at USD 10,490 million in 2024 and is projected to reach USD 14,803.31 million by 2032, expanding at a CAGR of 4.4%, supported by steady demand from food, pharmaceutical, and industrial packaging sectors.
- Asia Pacific leads with about 34% share due to large-scale manufacturing and consumer goods output, followed by North America at nearly 28% driven by advanced packaging standards, and Europe at around 24% supported by strong regulatory compliance and pharmaceutical demand.
- Asia Pacific also represents the fastest-growing region with its 34% share, driven by capacity expansion in China and India, cost-efficient production, and rising packaged product consumption.
- By container type, blow molding containers account for roughly 65% share due to dominance in bottles and drums, while injection molding containers hold about 35% supported by closures and precision packaging needs.
- By end-use industry, food and beverages contribute nearly 38% share due to high-volume usage, while pharmaceuticals hold around 22% driven by safety, compliance, and consistent demand.
Market Drivers:
Rising Demand For Durable And Chemical-Resistant Rigid Packaging Solutions
The HDPE Blow Molding and Injection Molding Container Market benefits from rising demand for durable packaging. Manufacturers select HDPE due to strong impact resistance. Chemical stability supports safe storage of corrosive products. Food producers rely on barrier protection for hygiene. Pharmaceutical firms trust consistent material performance. Household chemical brands need leak-proof formats. Industrial users prefer long service life. These requirements sustain steady demand growth.
- For instance, Berry Global reports HDPE containers passing ASTM D256 impact resistance tests and chemical compatibility across acids, alkalis, and detergents used in home care products.
Expanding Use Across Food, Beverage, And Pharmaceutical End-Use Segments
The HDPE Blow Molding and Injection Molding Container Market gains support from packaged goods expansion. Urban lifestyles increase packaged food consumption. Beverage producers favor lightweight containers for transport. Pharmaceutical packaging requires high hygiene standards. HDPE supports tamper-evident designs. Injection molding ensures precise closures. Blow molding enables high-volume bottle supply. End-use diversity supports market stability.
- For instance, Amcor supplies HDPE pharma bottles compliant with US FDA 21 CFR and EU food contact standards for solid oral dose packaging.
Cost Efficiency And High-Speed Manufacturing Capability Of HDPE Containers
The HDPE Blow Molding and Injection Molding Container Market benefits from production efficiency. HDPE resin offers stable cost performance. High-speed molding lines increase throughput. Automation reduces labor dependency. Material reuse limits production waste. Manufacturers achieve economies of scale. Output consistency supports large contracts. Cost efficiency strengthens supplier competitiveness.
Regulatory Acceptance And Safety Compliance Across Multiple Industries
The HDPE Blow Molding and Injection Molding Container Market gains confidence from regulatory approval. Food authorities approve HDPE contact safety. Pharmaceutical regulators accept it for primary packaging. Material uniformity supports compliance audits. Low migration risk improves safety trust. Global standards enable cross-border trade. Brand owners reduce regulatory risk. Compliance stability supports long-term adoption.
Market Trends:
Shift Toward Lightweight Container Designs For Logistics Optimization
The HDPE Blow Molding and Injection Molding Container Market reflects logistics-driven design changes. Brands seek lower transport weight. Lightweight containers reduce freight costs. Optimized wall thickness maintains strength. Stackable designs improve storage efficiency. Retailers prefer easy handling formats. Warehouses gain space efficiency. Logistics focus shapes container engineering.
- For instance, ALPLA reports lightweight HDPE bottle designs achieving material reductions while maintaining top-load strength validated through internal compression testing.
Growing Customization In Container Shapes And Closure Compatibility
The HDPE Blow Molding and Injection Molding Container Market shows strong design customization trends. Brands demand distinct container profiles. Injection molding enables precise neck finishes. Blow molding supports ergonomic bottle shapes. Custom designs improve shelf appeal. Closure compatibility enhances dispensing control. Branding strategy drives tooling upgrades. Visual differentiation supports market presence.
- For instance, Silgan Plastics manufactures HDPE containers with standardized neck finishes compatible with multiple closure systems used in food and chemical packaging.
Integration Of Advanced Automation And Smart Molding Equipment
The HDPE Blow Molding and Injection Molding Container Market adopts advanced manufacturing systems. Smart machines improve process control. Sensors support real-time quality checks. Digital systems reduce defect rates. Predictive maintenance improves uptime. Automation supports workforce efficiency. Consistency improves customer confidence. Technology investment strengthens competitiveness.
Rising Focus On Recyclability And Circular Packaging Practices
The HDPE Blow Molding and Injection Molding Container Market aligns with circular packaging goals. HDPE supports high recycling rates. Brands prefer mono-material designs. Clear resin improves recycling efficiency. Recyclable labeling gains importance. Waste recovery systems expand regionally. Sustainability reporting influences material choice. Circular focus shapes packaging strategies.
Market Challenges Analysis:
Volatility In Raw Material Supply And Resin Price Stability Concerns
The HDPE Blow Molding and Injection Molding Container Market faces resin supply uncertainty. Petrochemical feedstock prices fluctuate frequently. Supply disruptions affect production planning. Price swings reduce margin predictability. Smaller manufacturers face higher risk. Long-term contracts become complex. Inventory control demands precision. Cost volatility challenges pricing strategies.
Increasing Competition From Alternative Packaging Materials And Formats
The HDPE Blow Molding and Injection Molding Container Market competes with substitute materials. Flexible packaging gains adoption in some uses. Paper-based formats attract sustainability focus. Glass holds premium product segments. Metal serves select industrial needs. Material substitution limits volume growth. Innovation pressure increases across suppliers. Differentiation becomes essential.
Market Opportunities:
Expansion In Emerging Economies With Growing Consumer Goods Production
The HDPE Blow Molding and Injection Molding Container Market finds growth in emerging regions. Urbanization increases packaged goods demand. Local manufacturing capacity expands steadily. Consumer goods firms scale operations. HDPE containers support mass distribution. Cost efficiency suits price-sensitive markets. Infrastructure development improves logistics. Regional growth supports volume expansion.
Development Of High-Performance And Value-Added Container Solutions
The HDPE Blow Molding and Injection Molding Container Market benefits from advanced product development. High-barrier containers protect sensitive contents. Precision molding supports dosing accuracy. Value-added features improve user convenience. Smart closures enhance product safety. Custom solutions attract premium brands. Innovation supports margin improvement. Product upgrades open new applications.
Market Segmentation Analysis:
By Container Type
The HDPE Blow Molding and Injection Molding Container Market shows clear segmentation by container type. Blow molding containers dominate large-volume packaging due to design flexibility. These containers suit bottles, drums, and jerry cans. Manufacturers prefer blow molding for hollow shapes and high output. Injection molding containers serve precision-driven applications. This type supports caps, lids, and rigid containers with tight tolerances. Injection molding ensures dimensional accuracy and surface finish. Both container types support scalable production needs across industries.
- For instance, Mauser Packaging Solutions produces blow-molded HDPE drums certified under UN performance standards for hazardous material transport.
By End-Use Industry
The HDPE Blow Molding and Injection Molding Container Market serves a wide range of end-use industries. Food and beverage companies rely on HDPE for hygiene and shelf stability. Pharmaceutical packaging demands chemical resistance and compliance assurance. Personal care and cosmetics brands value design versatility and product protection. Health care applications require safe storage and easy handling. Chemicals and petrochemicals depend on leak resistance and impact strength. Other industrial and household uses benefit from durability and cost efficiency. End-use diversity supports balanced and sustained market demand.
- For instance, SABIC supplies HDPE grades approved for food contact and chemical packaging, meeting EU Regulation No. 10/2011 requirements.
Segmentation:
By Container Type
- Blow molding containers
- Injection molding containers
By End-Use Industry
- Food & beverages
- Pharmaceuticals
- Personal care & cosmetics
- Health care
- Chemicals & petrochemicals
- Other industrial and household applications
By Geography
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The HDPE Blow Molding and Injection Molding Container Market shows strong presence in North America with nearly 28% market share. The United States leads regional demand due to mature packaging industries. Food, pharmaceutical, and chemical sectors drive steady container consumption. Advanced molding automation supports high production efficiency. Regulatory clarity supports long-term material adoption. Brand owners prefer standardized packaging formats. Stable replacement demand sustains regional performance.
Europe
The HDPE Blow Molding and Injection Molding Container Market holds around 24% market share in Europe. Germany, France, and the United Kingdom lead regional usage. Strong focus on product safety supports HDPE container demand. Pharmaceutical and personal care industries remain key consumers. Sustainability rules influence container design choices. Manufacturers invest in recyclable mono-material solutions. Industrial packaging demand supports steady volumes.
Asia Pacific, Latin America, And Middle East & Africa
The HDPE Blow Molding and Injection Molding Container Market records the largest share in Asia Pacific at about 34%. China and India drive volume through food, chemical, and household sectors. Manufacturing scale and cost efficiency strengthen regional output. Latin America accounts for nearly 8% share, led by Brazil and Mexico. Consumer goods expansion supports demand growth. Middle East & Africa contribute close to 6% share. Industrial packaging and chemicals drive regional uptake.
Key Player Analysis:
- Greif, Inc.
- Mauser Group (Mauser Group B.V.)
- Schütz
- Time Technoplast Ltd.
- Duplas Al Sharq LLC
- Greiner Packaging International GmbH
- Saudi Can Manufacturing Company Ltd.
- Pampa Industries
- Takween Advanced Industries
- National Plastic Factory LLC
- H&O Plastics Ltd.
- Singa Plastics Limited
- WERIT Kunststoffwerke
- SKS Bottle & Packaging
- Berry Global
Competitive Analysis:
The HDPE Blow Molding and Injection Molding Container Market shows moderate consolidation with global and regional players. Leading companies focus on scale, process efficiency, and product reliability. Firms invest in automated molding lines to improve output quality. Portfolio breadth across food, pharmaceutical, and industrial containers supports competitive strength. Custom design capability helps suppliers secure long-term contracts. Regional players compete through cost efficiency and local supply advantages. Sustainability alignment strengthens brand positioning. Strategic capacity expansion supports volume growth. Competitive rivalry remains stable due to high entry barriers.
Recent Developments:
- In December 2025, Mauser Packaging Solutions announced the acquisition of Siena Plastics LLC, a manufacturer of small high-performance containers. This strategic acquisition strengthened Mauser's product portfolio and created new opportunities to deliver high-quality packaging solutions to its expanding customer base.
- In November 2025, Time Technoplast strengthened its financial position through a successful ₹800 crore Qualified Institutional Placement (QIP). The capital was strategically allocated toward debt reduction (₹400 crore), capital expenditure for automation and re-engineering (₹89.37 crore), investment in subsidiary Time Ecotech for recycling operations (₹54.89 crore), and inorganic growth initiatives (₹240.95 crore). The company committed to converting 75% of electricity consumption to green energy within two years, targeting cost savings of ₹10-12 crore initially with potential annual savings of ₹30 crore.
- In August 2025, Ball Corporation completed a strategic partial divestment of its joint venture in Saudi Arabia. Ball sold 41% of its 51% ownership stake in Ball United Arab Can Manufacturing Co. to a subsidiary of ORG Technology Co. (Beijing-based) for approximately $70 million, reducing Ball's stake to 10%. This transaction, initially agreed upon in November 2024, deepened Ball's relationship with ORG and reflected the company's focus on disciplined, returns-oriented portfolio management while maintaining collaborative manufacturing partnerships in the Kingdom of Saudi Arabia and broader Middle East region.
Report Coverage:
The research report offers an in-depth analysis based on By Container Type and By End-Use Industry segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising packaged food and beverage demand will support steady container consumption.
- Pharmaceutical packaging needs will sustain long-term volume stability.
- Automation adoption will improve production efficiency and quality control.
- Lightweight container designs will gain wider acceptance for logistics efficiency.
- Recycling-focused product development will align with sustainability goals.
- Emerging economies will attract new manufacturing capacity investments.
- Custom container formats will strengthen brand differentiation strategies.
- Industrial chemical packaging will remain a consistent demand segment.
- Regional supply chains will strengthen to improve delivery reliability.
- Technology upgrades will enhance long-term competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Durable and Chemical-Resistant Packaging
HDPE containers offer strong impact resistance and chemical stability, making them ideal for storing corrosive products, pharmaceuticals, and industrial chemicals. This durability and safety profile drives adoption across sectors requiring reliable, long-lasting packaging.
Growth in Packaged Food, Beverage, and Pharmaceutical Sectors
Urbanization and changing lifestyles are increasing consumption of packaged foods and beverages, while pharmaceutical packaging requires high hygiene and compliance standards. HDPE containers meet these needs with tamper-evident, hygienic, and regulatory-compliant solutions.
Cost Efficiency and High-Speed Manufacturing
HDPE resin supports stable cost structures and enables high-speed, automated molding processes, reducing labor dependency and production waste. This cost efficiency allows manufacturers to scale up production and remain competitive in price-sensitive markets.
Regulatory Acceptance and Safety Compliance
HDPE is widely approved by food and pharmaceutical authorities for direct contact applications, supporting cross-border trade and reducing regulatory risks for brand owners. This broad acceptance underpins long-term market stability.
Sustainability and Recyclability Focus
HDPE's compatibility with recycling systems and the trend toward mono-material, recyclable packaging align with brand and regulatory sustainability goals. This drives preference for HDPE containers among environmentally conscious companies and consumers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for HDPE Blow Molding and Injection Molding Container Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the HDPE Blow Molding and Injection Molding Container Market projected to grow between 2025 and 2032?
Which HDPE Blow Molding and Injection Molding Container Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the HDPE Blow Molding and Injection Molding Container Market?
Who are the leading companies in the HDPE Blow Molding and Injection Molding Container Market?
Which region commanded the largest share of the HDPE Blow Molding and Injection Molding Container Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Container Type
- 1.2.1 Blow molding containers
- 1.2.2 Injection molding containers
- 1.3 By End-Use Industry
- 1.3.1 Food & beverages
- 1.3.2 Pharmaceuticals
- 1.3.3 Personal care & cosmetics
- 1.3.4 Health care
- 1.3.5 Chemicals & petrochemicals
- 1.3.6 Other industrial and household applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,490 million → 2032: USD 14,803.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global HDPE Blow Molding and Injection Molding Container Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global HDPE Blow Molding and Injection Molding Container Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global HDPE Blow Molding and Injection Molding Container Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global HDPE Blow Molding and Injection Molding Container Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global HDPE Blow Molding and Injection Molding Container Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global HDPE Blow Molding and Injection Molding Container Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global HDPE Blow Molding and Injection Molding Container Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global HDPE Blow Molding and Injection Molding Container Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,490 million → 2032: USD 14,803.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global HDPE Blow Molding and Injection Molding Container Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Container Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Blow molding containers
- 12.3.7.2 Injection molding containers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food & beverages
- 12.4.7.2 Pharmaceuticals
- 12.4.7.3 Personal care & cosmetics
- 12.4.7.4 Health care
- 12.4.7.5 Chemicals & petrochemicals
- 12.4.7.6 Other industrial and household applications
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global HDPE Blow Molding and Injection Molding Container End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global HDPE Blow Molding and Injection Molding Container Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global HDPE Blow Molding and Injection Molding Container Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global HDPE Blow Molding and Injection Molding Container Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Greif, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mauser Group
- 18.4 Schütz
- 18.5 Time Technoplast Ltd.
- 18.6 Berry Global
- 18.7 Greiner Packaging International GmbH
- 18.8 Silgan Plastics
- 18.9 Duplas Al Sharq LLC
- 18.10 Singa Plastics Limited
- 18.11 WERIT Kunststoffwerke
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

