
Market Overview
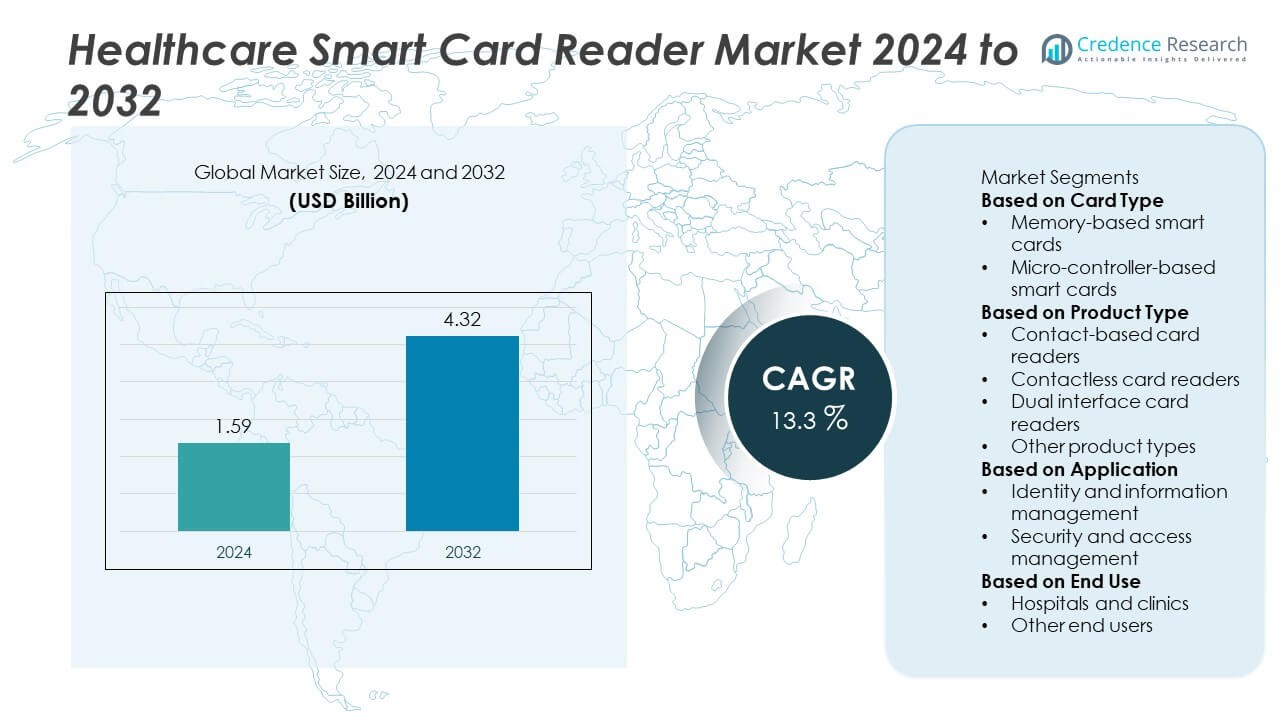
The Healthcare Smart Card Reader Market was valued at USD 1.59 billion in 2024 and is projected to reach USD 4.32 billion by 2032, growing at a CAGR of 13.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Healthcare Smart Card Reader Market Size 2024 | USD 1.59 Billion |
| Healthcare Smart Card Reader Market, CAGR | 13.3% |
| Healthcare Smart Card Reader Market Size 2032 | USD 4.32 Billion |
The Healthcare Smart Card Reader Market is led by major companies including IDENTOS, CHERRY, HID Global Corporation, CardLogix, Ingenico, FEITIAN Technologies, Advantech, Identiv, Advanced Card Systems, and IDEMIA. These players focus on developing secure, efficient, and interoperable card reader systems to support healthcare digitalization. North America dominated the market with a 39% share in 2024, driven by strong regulatory frameworks and widespread use of electronic health record systems. Europe followed with 31%, supported by GDPR-driven security compliance and national eHealth programs. Asia-Pacific held 23% share, emerging as the fastest-growing region due to expanding healthcare infrastructure and government-backed digital health initiatives.
Market Insights
- The Healthcare Smart Card Reader Market was valued at USD 1.59 billion in 2024 and is projected to reach USD 4.32 billion by 2032, growing at a CAGR of 13.3%.
- Growth is driven by the rising need for secure patient identification and digital healthcare transformation supported by government-backed eHealth initiatives.
- Contactless and dual-interface readers are gaining traction as hospitals prioritize hygiene and faster authentication, especially in post-pandemic environments.
- Key players such as HID Global Corporation, IDEMIA, Identiv, and Ingenico are focusing on cybersecurity, interoperability, and smart connectivity to enhance healthcare data management.
- North America led with 39% share in 2024, followed by Europe with 31% and Asia-Pacific with 23%, while micro-controller-based smart cards held the largest 61% segment share, supported by their superior data security and integration capabilities in healthcare systems.
Market Segmentation Analysis:
By Card Type
Micro-controller-based smart cards dominated the Healthcare Smart Card Reader Market with a 61% share in 2024. These cards are preferred for their advanced processing capabilities, higher data storage, and enhanced security features. They enable authentication, encryption, and secure access to patient information, making them ideal for hospitals and insurance verification systems. Memory-based smart cards hold a smaller share, mainly used for basic data storage. Growing concerns over data breaches and compliance with healthcare security standards such as HIPAA and GDPR are driving the shift toward micro-controller-based smart card adoption.
- For instance, IDEMIA developed its ID-One PIV 243 micro-controller smart card featuring an embedded chip with NIST FIPS 140-3 Level 2 validation. The card supports on-chip cryptographic key generation and 2048-bit RSA encryption, ensuring secure access control in government, enterprise, and other environments.
By Product Type
Contact-based card readers led the market with a 49% share in 2024, driven by their wide availability, cost-effectiveness, and compatibility with existing healthcare IT infrastructure. Hospitals and diagnostic centers favor these readers for secure data transfer and patient identification. However, contactless and dual-interface readers are gaining traction due to faster authentication and hygiene benefits, especially after the COVID-19 pandemic. Increasing deployment of RFID and NFC-enabled systems across modern healthcare networks is expected to boost the adoption of contactless technologies over the coming years.
- For instance, HID Global offers the OMNIKEY SE Reader Core module, which integrates RFID, BLE, and NFC capabilities for secure authentication in various systems, including healthcare environments. This module can read a range of high and low-frequency credentials, including those on mobile phones with Apple Wallet support.
By Application
The identity and information management segment accounted for a 57% share in 2024, making it the dominant application in the Healthcare Smart Card Reader Market. These systems streamline patient identification, reduce administrative errors, and ensure secure medical data exchange between facilities. Growing implementation of electronic health record (EHR) systems and digital insurance verification drives demand for smart card-based identity solutions. Security and access management applications are also expanding rapidly as healthcare institutions prioritize secure entry and patient data protection within connected digital ecosystems.
Key Growth Drivers
Rising Digitalization in Healthcare Systems
The growing adoption of digital health infrastructure and electronic health records (EHR) is a major driver of the Healthcare Smart Card Reader Market. Hospitals and clinics are increasingly integrating smart card systems to ensure secure and accurate patient identification. Governments worldwide are encouraging eHealth initiatives to improve data management and reduce fraud. The demand for efficient access to medical data and improved administrative efficiency continues to accelerate smart card reader deployment across healthcare facilities.
- For instance, Identiv SCR3310v2.0 smart card readers are widely used in healthcare, including for EHR authentication. The device supports a standard USB interface and is fully compliant with industry standards like ISO/IEC 7816 and FIPS 201, which are important for secure applications.
Growing Need for Data Security and Authentication
With increasing healthcare data breaches, security has become a top priority for medical organizations. Smart card readers enable encrypted data access, protecting sensitive patient information from unauthorized entry. Their integration supports regulatory compliance with data protection standards such as HIPAA and GDPR. As healthcare providers digitize more records, the need for strong authentication systems will continue to drive market demand for secure smart card technologies.
- For instance, FEITIAN Technologies introduced its R502 Dual Interface Reader equipped with ISO/IEC 14443 Type A/B compliance, which supports encrypted firmware upgrades and enables multi-factor authentication for applications like healthcare databases, thus helping to reduce access breach incidents in medical institutions.
Government Initiatives and eHealth Programs
Government-backed health ID programs and national eHealth policies are fueling market growth. Countries are implementing smart health cards for insurance verification, patient tracking, and digital health record management. These initiatives enhance interoperability between healthcare providers and streamline billing and data sharing. Financial incentives and infrastructure investments in digital healthcare systems further strengthen the adoption of smart card readers across both public and private healthcare institutions.
Key Trends & Opportunities
Adoption of Contactless and Dual-Interface Readers
Healthcare organizations are rapidly adopting contactless and dual-interface readers for faster and safer data exchange. These systems improve hygiene by eliminating physical contact while maintaining high-speed authentication. The trend gained momentum after the pandemic as healthcare facilities prioritized non-contact verification solutions. Continuous innovation in RFID and NFC technology is expected to open new opportunities for smart card reader manufacturers targeting large hospital networks and diagnostic chains.
- For instance, CHERRY introduced its KC 1000 SC keyboard-integrated contact smart card reader. The device supports ISO 7816 protocols and provides secure workstation access in hospitals and laboratories through secure PIN entry and authentication.
Integration with Cloud and IoT Platforms
The integration of smart card readers with IoT-enabled devices and cloud-based data systems is transforming healthcare management. These systems allow real-time patient monitoring, remote data access, and seamless information sharing between departments. Manufacturers are developing solutions compatible with modern hospital IT infrastructure, improving interoperability and efficiency. The shift toward connected and automated health management platforms offers long-term growth potential for the industry.
- For instance, Advantech developed its HIT-W183 Cloud IoT medical terminal integrated with a smart card reader and RFID connectivity. The unit features an Intel Celeron N4200 processor, a default of 4 GB RAM (with a maximum capacity of 8 GB), and dual isolated Ethernet for secure data traffic.
Key Challenges
High Implementation and Maintenance Costs
The initial setup and integration costs of smart card reader systems can be high, particularly for small healthcare centers. Maintenance, software upgrades, and system compatibility issues add to operational expenses. This cost barrier restricts adoption in developing regions with limited healthcare budgets. Manufacturers are working on cost-effective models and flexible deployment solutions to address this challenge.
Interoperability and Technical Integration Issues
Many healthcare facilities face challenges integrating smart card systems with existing IT infrastructure and EHR platforms. Lack of standardized communication protocols and differing data formats create compatibility problems. These technical barriers delay full-scale adoption and limit system efficiency. Continuous efforts toward global interoperability standards and unified data frameworks are essential to overcome these issues and enhance market growth.
Regional Analysis
North America
North America dominated the Healthcare Smart Card Reader Market with a 39% share in 2024. The region’s leadership is driven by the high adoption of digital health infrastructure and strong emphasis on patient data security. The United States leads due to extensive healthcare IT spending, electronic health record integration, and advanced hospital networks. Government regulations such as HIPAA promote secure patient identification systems, boosting demand for smart card readers. Increasing partnerships between healthcare providers and IT firms are further enhancing market penetration across hospitals, clinics, and insurance platforms.
Europe
Europe held a 31% share of the Healthcare Smart Card Reader Market in 2024, supported by widespread eHealth initiatives and stringent data protection laws. Countries such as Germany, the United Kingdom, and France are key adopters, driven by regulatory frameworks like GDPR ensuring secure health data management. Healthcare providers across Europe are rapidly implementing contactless and dual-interface smart card readers for identity verification and insurance processing. Public funding for healthcare digitalization and interoperability projects continues to strengthen market growth across both private and government healthcare institutions.
Asia-Pacific
Asia-Pacific accounted for 23% of the global market share in 2024 and is projected to grow fastest during the forecast period. Rapid healthcare infrastructure development, rising patient populations, and digital transformation initiatives are fueling adoption. China, India, Japan, and South Korea are major contributors due to expanding hospital networks and government-backed eHealth programs. Increasing focus on data security, insurance digitization, and electronic health card deployment drives regional demand. Growing investment by local IT and medical device firms in secure health data technologies further accelerates market expansion across the region.
Latin America
Latin America captured a 4% share of the Healthcare Smart Card Reader Market in 2024. Growth is driven by improving healthcare systems and increasing adoption of electronic health identification in countries such as Brazil, Mexico, and Chile. The need for accurate patient data handling and reduced medical fraud is encouraging hospitals to integrate smart card-based authentication. Gradual digital transformation in healthcare infrastructure, coupled with support from international health technology providers, is strengthening market penetration. However, limited funding and uneven digital maturity across the region continue to constrain faster growth.
Middle East & Africa
The Middle East & Africa held a 3% share of the Healthcare Smart Card Reader Market in 2024. Expansion in the region is supported by healthcare modernization initiatives and growing awareness of digital data management. GCC nations, including the UAE and Saudi Arabia, are leading adoption through national health identification programs and smart hospital investments. In Africa, digital health programs backed by government and global aid organizations are improving patient record systems. Despite slow adoption rates in rural areas, infrastructure investments and rising healthcare IT integration are enhancing long-term growth prospects.
Market Segmentations:
By Card Type
- Memory-based smart cards
- Micro-controller-based smart cards
By Product Type
- Contact-based card readers
- Contactless card readers
- Dual interface card readers
- Other product types
By Application
- Identity and information management
- Security and access management
By End Use
- Hospitals and clinics
- Other end users
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Healthcare Smart Card Reader Market features key players such as IDENTOS, CHERRY, HID Global Corporation, CardLogix, Ingenico, FEITIAN Technologies, Advantech, Identiv, Advanced Card Systems, and IDEMIA. These companies focus on enhancing data security, interoperability, and system integration across healthcare facilities. Leading players are developing advanced contactless and dual-interface readers to meet growing demand for fast and hygienic patient identification. Strategic collaborations with hospitals, IT service providers, and government agencies strengthen their market presence. Product innovations incorporating encryption, biometric verification, and cloud-based connectivity are key areas of investment. North American and European manufacturers emphasize regulatory compliance and technological precision, while Asia-Pacific companies are targeting cost-effective and scalable smart card reader solutions. Continuous R&D and integration with electronic health record systems are expected to shape competitive positioning in the coming years.
Key Player Analysis
- IDENTOS
- CHERRY
- HID Global Corporation
- CardLogix
- Ingenico
- FEITIAN Technologies
- Advantech
- Identiv
- Advanced Card Systems
- IDEMIA
Recent Developments
- In September 2025, IDEMIA launched its SMART-E kiosks in Pennsylvania and Colorado, achieving a fingerprint rejection rate under 2% during civil applicant processing.
- In August 2025, HID Global unveiled its OMNIKEY SE Plug Reader, enabling secure authentication across FIDO2, smart card, and multi-factor credentials.
- In July 2025, IDEMIA’s ID-One PIV 243 smart cards earned NIST FIPS 140-3 Level 2 validation and entered the U.S. GSA Approved Products List.
- In April 2024, HID Global introduced the OMNIKEY SE Reader Core module supporting RFID, Apple Wallet, BLE, and future-ready embedded desktop integration.
Report Coverage
The research report offers an in-depth analysis based on Card Type, Product Type, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for contactless smart card readers will continue to grow in healthcare facilities.
- Integration with electronic health record systems will strengthen digital identity management.
- Governments will expand national eHealth programs promoting smart card-based authentication.
- Hospitals will adopt dual-interface readers for improved speed and hygiene in patient verification.
- AI and IoT integration will enhance real-time data access and interoperability.
- Manufacturers will focus on stronger encryption and biometric-enabled card reader solutions.
- Asia-Pacific will experience the fastest growth due to rapid healthcare digitalization.
- Partnerships between healthcare IT providers and smart card firms will increase.
- Cost-efficient and portable reader models will gain popularity among small clinics.
- Continuous innovation in secure, cloud-based healthcare identification systems will drive market expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Healthcare Smart Card Reader Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Healthcare Smart Card Reader Market projected to grow between 2025 and 2032?
Which Healthcare Smart Card Reader Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Healthcare Smart Card Reader Market?
Who are the leading companies in the Healthcare Smart Card Reader Market?
Which region commanded the largest share of the Healthcare Smart Card Reader Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Healthcare Smart Card Reader Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Healthcare Smart Card Reader Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1.59 billion → 2032: USD 4.32 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Healthcare Smart Card Reader Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Healthcare Smart Card Reader Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Healthcare Smart Card Reader Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Healthcare Smart Card Reader Market Drivers
- 3.3 Healthcare Smart Card Reader Market Restraints & Challenges
- 3.4 Healthcare Smart Card Reader Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Healthcare Smart Card Reader Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Healthcare Smart Card Reader Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Healthcare Smart Card Reader category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Healthcare Smart Card Reader Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Healthcare Smart Card Reader Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Healthcare Smart Card Reader. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Healthcare Smart Card Reader Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Healthcare Smart Card Reader Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Healthcare Smart Card Reader Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Healthcare Smart Card Reader (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Healthcare Smart Card Reader
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Healthcare Smart Card Reader Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Healthcare Smart Card Reader Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Healthcare Smart Card Reader Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Healthcare Smart Card Reader Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Healthcare Smart Card Reader Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Healthcare Smart Card Reader Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Healthcare Smart Card Reader Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Healthcare Smart Card Reader Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
