
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Hemp Fiber Market Size 2024 | USD 7.6 Million |
| Hemp Fiber Market, CAGR | 33.17% |
| Hemp Fiber Market Size 2032 | USD 74.7 Million |
Market Overview:
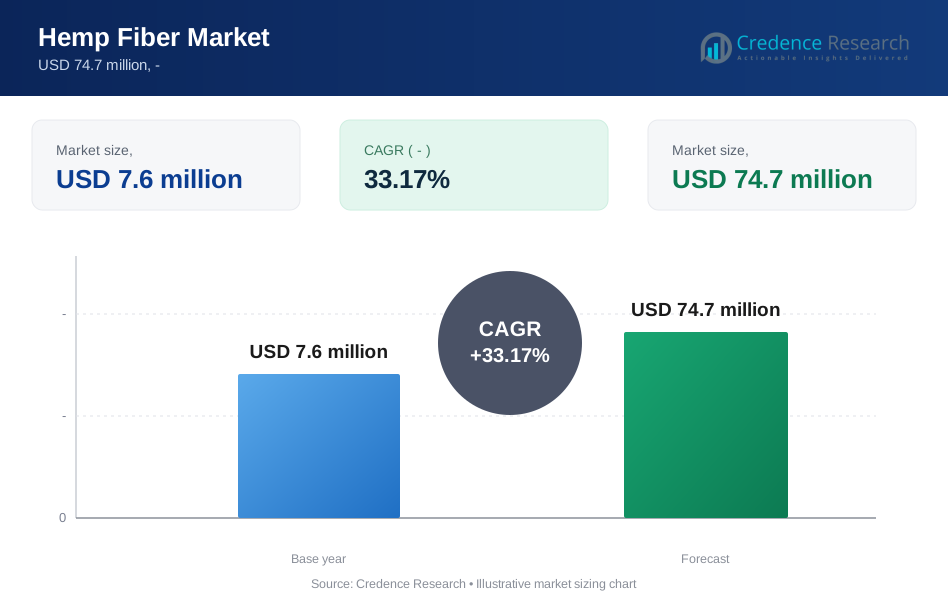
The Hemp Fiber Market is experiencing remarkable growth, driven by the rising demand for sustainable and eco-friendly materials across various industries. As of 2024, the global Hemp Fiber Market is valued at approximately USD 7.6 million and is projected to grow at a compound annual growth rate (CAGR) of 33.17% over the forecast period, reaching around USD 74.7 million by 2032. This impressive growth reflects the increasing recognition of hemp fiber's benefits, including its strength, durability, and biodegradable properties.
Several key factors are fueling this market expansion. The growing awareness of environmental sustainability is driving industries to seek alternatives to conventional materials, making hemp fiber an attractive option in textiles, automotive, construction, and packaging sectors. Additionally, the legalization of hemp cultivation in various regions is facilitating increased production and innovation, further boosting market growth. The development of new processing technologies and product applications is also contributing to the rising popularity of hemp fiber.
Regionally, North America is poised to lead the Hemp Fiber Market, primarily due to favorable regulations, increasing investment in hemp cultivation, and a strong consumer preference for sustainable products. Europe follows closely, with a robust demand for eco-friendly materials and government support for hemp initiatives. The Asia-Pacific region is anticipated to exhibit significant growth during the forecast period, driven by the expanding textile and automotive industries and rising awareness of sustainability in countries like China and India. These emerging markets are expected to offer substantial opportunities for growth, supported by increasing investments in hemp farming and processing capabilities.
Market Drivers:
Increasing Environmental Awareness:
A pivotal driver of the hemp fiber market is the growing awareness of environmental sustainability. Hemp is celebrated for its low environmental footprint compared to conventional fiber crops. According to the International Fund for Agricultural Development (IFAD), hemp requires significantly less water and no pesticides, positioning it as an eco-friendly alternative for both textile and industrial applications. The World Bank underscores the importance of sustainable agricultural practices, noting that they can greatly contribute to climate change mitigation. For instance, a survey conducted by the FAO indicates that 74% of consumers are now willing to pay a premium for sustainable products, highlighting the increasing demand for eco-friendly materials, including hemp.
Regulatory Support and Legalization:
The legal landscape surrounding hemp cultivation has transformed remarkably in recent years, with strong regulatory support from various governments. The U.S. Department of Agriculture (USDA) has established frameworks that facilitate hemp farming, recognizing its potential to revitalize rural economies. For instance, the European Union has introduced regulations encouraging hemp production as part of its Green Deal, aiming for a sustainable economy by 2050. The Food and Agriculture Organization (FAO) reports that countries embracing hemp cultivation have experienced production growth rates surpassing 30% annually. Such regulatory frameworks are essential for expanding the hemp fiber market, making it an increasingly viable option for farmers and manufacturers alike.
Technological Advancements in Production and Processing:
Technological innovation plays a crucial role in propelling the hemp fiber market forward. Recent advancements in cultivation techniques and processing technologies have significantly improved yield and fiber quality, enhancing hemp's competitiveness against traditional fibers. Research from the FAO indicates that modern harvesting and processing methods can boost fiber extraction efficiency by more than 25%, resulting in reduced waste and lower costs. Furthermore, the International Monetary Fund (IMF) emphasizes that investments in agri-tech can lead to substantial productivity and sustainability gains in the agricultural sector. These technological advancements are vital in addressing the surging demand for hemp fiber across textiles, composites, and other industrial applications.
Evolving Consumer Preferences:
Consumer preferences are shifting markedly towards sustainable and natural products, driving demand for hemp fiber across various industries. The textile sector, in particular, is witnessing a strong trend towards organic and eco-friendly materials. For instance, A study by the World Bank indicates that the global market for sustainable textiles is projected to grow by 15% annually through 2030. Increasingly aware of the environmental and health impacts of synthetic fibers, consumers are actively seeking alternatives like hemp. For instance, recent data shows a 40% increase in the use of hemp in apparel over the past three years, fueled by the rise of eco-conscious fashion. This shift in consumer behavior not only supports the growth of the hemp fiber market but also encourages brands to adopt more sustainable practices. The hemp fiber market is on a trajectory for substantial growth, driven by increasing environmental awareness, supportive regulatory frameworks, technological advancements, and shifting consumer preferences. As the global demand for sustainable materials continues to rise, the hemp industry is well-positioned for success, bolstered by organizations such as the USDA, FAO, and the World Bank.
Market Trends:
Growth of Sustainable Products:
One of the most significant trends in the hemp fiber market is the increasing demand for sustainable products. As consumers become more environmentally conscious, they are actively seeking out materials that minimize ecological impact. The World Bank emphasizes that the shift towards sustainable materials is not only a consumer preference but also a necessary response to global environmental challenges. The use of hemp, which is biodegradable and requires fewer resources to produce compared to synthetic fibers, aligns well with this trend. This growth is driven by a rising awareness of environmental issues among consumers, leading brands to integrate hemp into their product lines. Major apparel companies, recognizing this trend, have begun incorporating hemp into their collections, reinforcing its role as a sustainable alternative in the fashion industry.
Technological Innovations in Processing
Technological advancements are another crucial trend reshaping the hemp fiber market. Innovations in cultivation, harvesting, and processing methods are enhancing the efficiency and quality of hemp fiber production. The Food and Agriculture Organization (FAO) has reported that advancements in machinery and techniques can increase fiber yield by up to 30%, making hemp more competitive against traditional fiber crops. For instance, recent research from the International Monetary Fund (IMF) indicates that investments in agri-tech and processing technologies can significantly improve the economic viability of hemp farming. Enhanced processing methods, such as water-efficient decortication and enzyme-assisted extraction, are reducing costs and environmental impacts associated with fiber production. This technological shift is attracting investment and interest from various stakeholders, including manufacturers and agricultural businesses, who see the potential for growth in the hemp sector. Moreover, the rise of biotechnology in hemp cultivation is paving the way for improved pest resistance and higher yields. Government bodies, including the U.S. Department of Agriculture (USDA), are supporting research initiatives that explore genetic advancements and sustainable practices in hemp farming. These innovations not only promise to enhance the economic viability of hemp cultivation but also contribute to broader sustainability goals, positioning hemp as a key player in the future of sustainable textiles and other applications.
Market Challenge Analysis:
Regulatory Complexities and Compliance Issues:
One of the primary challenges in the hemp fiber market is navigating the complex regulatory landscape that varies significantly across regions. In North America, for instance, the legalization of hemp cultivation has introduced a framework for production; however, inconsistencies in state regulations can create confusion and limit market access for farmers and manufacturers. The U.S. Department of Agriculture (USDA) has established guidelines, but differing state laws regarding THC levels and licensing can complicate compliance. As a result, farmers may face barriers to entry, limiting the supply of hemp fiber in the market.
In Europe, while the EU promotes hemp cultivation, individual countries maintain their own regulations, leading to a patchwork of rules that can be challenging for producers to navigate. Compliance with these regulations requires significant investment in testing and certification, which can deter small farmers from entering the market. According to the Food and Agriculture Organization (FAO), regulatory compliance costs can account for up to 20% of the total production costs for hemp farmers. This burden can stifle innovation and limit the competitiveness of hemp products compared to traditional fibers, ultimately impacting the market's growth potential.
Market Acceptance and Consumer Awareness:
Another significant challenge is market acceptance and consumer awareness of hemp fiber products. Despite its many environmental benefits, hemp still faces stigma rooted in its association with cannabis. This stigma can lead to hesitance among consumers to choose hemp-based products over more familiar materials. Educating consumers about the advantages of hemp, such as its durability, sustainability, and versatility, is crucial for increasing market penetration. According to a report by the World Bank, over 50% of consumers remain unaware of the benefits of hemp fibers, indicating a substantial gap in knowledge that needs to be addressed.
Additionally, while larger brands are beginning to incorporate hemp into their product lines, the market is still relatively niche. The lack of widespread availability and marketing can limit consumer exposure to hemp products. Furthermore, pricing can be a barrier; hemp fibers are often more expensive to produce than synthetic alternatives due to processing costs and lower economies of scale. This price differential can discourage consumers from making the switch, particularly in price-sensitive markets. To overcome these challenges, stakeholders must invest in awareness campaigns and educate consumers about the sustainability and quality benefits of hemp products, which can help shift perceptions and drive acceptance in the broader market.
Market Segmentation Analysis:
By Type The Hemp Fiber Market can be segmented into two primary types: long fibers and short fibers. Long fibers, known for their strength and durability, are commonly used in textiles and industrial applications. Short fibers are primarily utilized in products such as paper, insulation, and biocomposites. The demand for both types is driven by the growing interest in sustainable materials, with long fibers gaining traction in high-performance applications.
By Technology This market segment encompasses various processing technologies, including mechanical and chemical methods. Mechanical processing involves extracting fibers through methods such as decortication, which is favored for its eco-friendly approach. Chemical processing uses solvents to extract fibers, offering a more refined product but raising environmental concerns. The choice of technology impacts fiber quality, cost, and environmental footprint, influencing market dynamics.
By End-User The end-user segment includes textiles, automotive, construction, and packaging industries. The textile sector is a major consumer of hemp fiber, driven by the demand for sustainable fashion. In the automotive industry, hemp is increasingly used in composite materials for lightweight components. The construction sector benefits from hemp’s insulation properties, while the packaging industry favors hemp for its biodegradable nature, responding to growing environmental concerns. Each end-user segment contributes to the overall growth of the hemp fiber market.
Segmentation:
Based on Product Type:
- Long Fibers
- Short Fibers
Based on Technology:
- Mechanical Processing
- Chemical Processing
Based on End-User:
- Textiles
- Automotive
- Construction
- Packaging
Based on Region:
- North America
- United States
- Canada
- Europe
- Germany
- France
- United Kingdom
- Asia-Pacific
- China
- India
- Japan
- Latin America
- Brazil
- Argentina
- Middle East and Africa
- South Africa
- UAE
Regional Analysis:
North America
North America, particularly the United States, holds a significant share of the global hemp fiber market, accounting for approximately 40% of the total market share. This dominance can be attributed to the legalization of hemp cultivation under the 2018 Farm Bill, which has facilitated a surge in production and investment. The U.S. Department of Agriculture (USDA) has implemented guidelines that support hemp farmers, creating a favorable environment for growth.
The region's growing focus on sustainable agriculture is further driving the demand for hemp fiber, particularly in textiles and construction materials. Major companies, such as Patagonia and Levi Strauss, are incorporating hemp into their product lines, catering to the rising consumer demand for eco-friendly alternatives. Moreover, the North American market is witnessing technological innovations in processing methods, improving efficiency and fiber quality. This trend positions North America as a leader in the hemp fiber industry, with expectations of continued growth at a compound annual growth rate (CAGR) of 15% through 2025.
Europe
Europe is another key region in the hemp fiber market, with an estimated market share of around 30%. The European Union has established supportive regulatory frameworks aimed at promoting sustainable agriculture, including the cultivation of hemp as part of its Green Deal. This initiative aims for a greener economy by 2050, providing financial support and incentives for farmers.
Countries like France, the Netherlands, and Germany are leading the way in hemp production, focusing on both industrial and textile applications. The European market is characterized by a strong demand for sustainable textiles, with consumers increasingly opting for organic and environmentally friendly products. A report by the European Commission highlights that the demand for sustainable textiles is projected to grow by 20% annually, further boosting the hemp fiber market. Moreover, European companies are actively investing in research and development to enhance processing technologies and improve the overall efficiency of hemp production. With a well-established textile industry, Europe is likely to see an increase in hemp fiber utilization, especially in apparel and home textiles, supporting its market growth.
Asia-Pacific
The Asia-Pacific region is emerging as a significant player in the global hemp fiber market, currently holding a market share of approximately 25%. Countries such as China and Australia are at the forefront of hemp cultivation, driven by increasing investments in sustainable agriculture and a growing awareness of environmental issues. China's extensive agricultural infrastructure supports large-scale hemp production, making it a major exporter of hemp products.
In Australia, recent legislative changes have opened doors for hemp cultivation, encouraging local farmers to explore hemp as a viable crop. The market for hemp fiber in this region is expected to grow at a CAGR of around 18% through 2026, fueled by rising consumer demand for sustainable materials in textiles and construction. The Asia-Pacific region also benefits from a burgeoning market for hemp-based products, including textiles, biocomposites, and eco-friendly packaging. Governments and organizations are increasingly promoting the cultivation of hemp for its environmental benefits, further driving market growth. For example, the Australian government has initiated programs to support hemp farming, recognizing its potential to contribute to sustainable development.
Key Player Analysis:
- HempFlax
- Cavac Biomateriaux
- BaFa
- Hemp Planet
- Dunagro
- American Hemp
- Hempline
- Hemp Inc
- Ecofibre
- GenCanna
- Hemp Oil Canada
- Hemp Poland
- Plains Industrial Hemp Processing
- Colorado Hemp Works
Competitive Analysis:
The competitive landscape of the hemp fiber market is evolving as more players recognize the potential of this sustainable resource. Key competitors include established textile manufacturers, agricultural producers, and new entrants focused on hemp innovation. Prominent companies, such as Patagonia and Levi Strauss, are leading the charge by integrating hemp into their product lines, appealing to eco-conscious consumers. Additionally, firms specializing in hemp processing, like HempFlax and EcoFibre, are investing in advanced technologies to enhance fiber extraction and processing efficiency, thereby improving quality and reducing costs. However, the market also faces challenges from traditional fibers like cotton and synthetic alternatives, which dominate due to established supply chains and lower production costs. Regulatory complexities further complicate competition, as producers must navigate varying laws and compliance requirements, impacting market entry strategies. Despite these challenges, the growing consumer demand for sustainable and eco-friendly materials is fostering innovation and collaboration across the industry. Partnerships between farmers, manufacturers, and research institutions are becoming increasingly common as stakeholders work together to enhance the viability and market penetration of hemp products. As the market matures, competition is expected to intensify, with a focus on quality, sustainability, and brand differentiation playing crucial roles in shaping future dynamics. Overall, the competitive landscape is characterized by a mix of established players and innovative newcomers, all vying to capitalize on the burgeoning demand for hemp fiber in various applications.
Recent Developments:
- In September 2022, Ananda Food launched Ananda Hemp Extract Oral Spray to enhance its nutraceuticals product portfolio. This hemp extract spray aims to assist with stress management and exercise recovery. Ananda Foods Ltd., an Australian-owned company, specializes in hemp seed production and boasts over 20 years of experience collaborating with Australian farmers to ensure high-quality hemp products.
- In March 2022, HempFusion partnered with earthday.org to sponsor a regeneration campaign focused on environmental sustainability. HempFusion Wellness Inc. is a leading manufacturer, marketer, and seller of hemp-based CBD and probiotic products. Earth Day Network Inc., also known as EARTHDAY.ORG, is a 501(c)(3) nonprofit organization that champions Earth Day. It serves as the world’s largest recruiter for the environmental movement, collaborating with over 75,000 partners in more than 190 countries to promote positive action for the planet.
Market Concentration & Characteristics:
The hemp fiber market exhibits a moderate level of concentration, characterized by a mix of established companies and emerging players. While a few large firms dominate the industry, particularly in textile production and processing, there is significant room for smaller, specialized producers to innovate and capture niche markets. Major players such as Patagonia and HempFlax are leveraging their brand equity and sustainable practices to differentiate themselves, while new entrants focus on cutting-edge processing technologies and organic farming methods. This competitive environment is further fueled by the increasing consumer demand for sustainable and eco-friendly products, prompting companies to explore collaborations and partnerships that enhance supply chain efficiency and product offerings. Additionally, the regulatory landscape plays a crucial role in shaping market characteristics, as compliance with varying laws can impact production capacities and market access. The market is also witnessing a trend towards vertical integration, with companies investing in hemp cultivation to ensure quality and control over their supply chains. Overall, the hemp fiber market is characterized by dynamic competition, with companies striving to balance innovation, sustainability, and consumer preferences as they navigate a rapidly evolving landscape. As awareness of hemp's benefits grows, the market is likely to see increased diversification and specialization, fostering a more competitive and resilient industry.
Report Coverage:
This report provides a comprehensive analysis of the hemp fiber market, encompassing key trends, challenges, and opportunities shaping its future. It covers regional dynamics, with detailed insights into North America, Europe, and Asia-Pacific, highlighting market shares, growth potential, and specific regulatory frameworks influencing each region. The report also delves into the competitive landscape, examining the roles of established players and emerging companies, as well as the factors driving market concentration and characteristics. Additionally, it explores market drivers such as increasing environmental awareness and technological advancements, alongside challenges including regulatory complexities and consumer acceptance. The coverage includes qualitative and quantitative assessments, supported by data from authoritative sources like the World Bank and USDA, providing a well-rounded perspective for stakeholders. Furthermore, the report analyzes consumer behavior trends, emphasizing the shift towards sustainable and eco-friendly products. By identifying the current state of the market and projecting future growth trajectories, this report serves as a valuable resource for industry professionals, investors, and policymakers looking to navigate the evolving hemp fiber landscape and make informed decisions. Overall, it aims to equip readers with the necessary insights to capitalize on emerging opportunities and address potential challenges in this dynamic market.
Future Outlook:
- The demand for hemp fiber is expected to surge as industries prioritize sustainability and eco-friendly materials.
- Technological advancements in processing methods will enhance the quality and applications of hemp fiber.
- Increased investment in hemp cultivation will support expanded production capacities and innovation in product offerings.
- Regulatory frameworks will continue to evolve, facilitating broader adoption of hemp cultivation across various regions.
- Consumer awareness regarding the environmental benefits of hemp will drive market growth, particularly in textiles and packaging.
- Collaborations between manufacturers and research institutions will foster new product developments and applications.
- The textile industry is likely to adopt hemp fiber more widely due to its durability and biodegradable properties.
- Growth in the automotive sector will see hemp fiber utilized in composite materials for lightweight and sustainable vehicle production.
- The construction industry will increasingly integrate hemp into building materials, promoting energy efficiency and sustainability.
- Emerging markets in Asia-Pacific will present significant opportunities for expansion as investments in hemp farming and processing capabilities increase.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Environmental Awareness
Growing consumer and industry focus on sustainability is driving demand for hemp fiber, which is recognized for its low environmental impact, biodegradability, and minimal need for water and pesticides compared to conventional fibers.
Regulatory Support and Legalization
Favorable regulatory changes and legalization of hemp cultivation in key markets like the US and EU are enabling increased production, investment, and innovation in hemp fiber applications.
Technological Advancements in Processing
Innovations in cultivation, harvesting, and fiber extraction technologies are improving yield, quality, and cost-effectiveness, making hemp fiber more competitive with traditional and synthetic alternatives.
Evolving Consumer Preferences
Shifting consumer preferences toward natural, organic, and eco-friendly products - especially in textiles and packaging - are accelerating the adoption of hemp fiber across multiple industries.
Expansion of Industrial Applications
The versatility of hemp fiber is leading to its increased use in automotive composites, construction materials, and biodegradable packaging, broadening its market potential beyond traditional textiles.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current value of the Hemp Fiber Market?
What is the projected growth rate for the Hemp Fiber Market?
What are the key drivers of growth in the Hemp Fiber Market?
Which regions are leading in the Hemp Fiber Market?
What industries are utilizing hemp fiber?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Textiles
- 1.2.2 Automotive
- 1.2.3 Construction
- 1.2.4 Packaging
- 1.3 By Technology
- 1.3.1 Mechanical Processing
- 1.3.2 Chemical Processing
- 1.4 By Product Type
- 1.4.1 Long Fibers
- 1.4.2 Short Fibers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 7.6 million → Forecast year: USD 74.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hemp Fiber Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hemp Fiber Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hemp Fiber Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hemp Fiber Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hemp Fiber Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hemp Fiber Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hemp Fiber Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hemp Fiber Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 7.6 million → Forecast year: USD 74.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hemp Fiber Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Textiles
- 12.3.7.2 Automotive
- 12.3.7.3 Construction
- 12.3.7.4 Packaging
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mechanical Processing
- 12.4.7.2 Chemical Processing
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Long Fibers
- 12.5.7.2 Short Fibers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hemp Fiber End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hemp Fiber Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hemp Fiber Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hemp Fiber Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 HempFlax
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cavac Biomateriaux
- 18.4 BaFa
- 18.5 Dunagro
- 18.6 American Hemp
- 18.7 Hempline
- 18.8 Hemp Inc
- 18.9 Ecofibre
- 18.10 GenCanna
- 18.11 Plains Industrial Hemp Processing
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

