
Market Overview
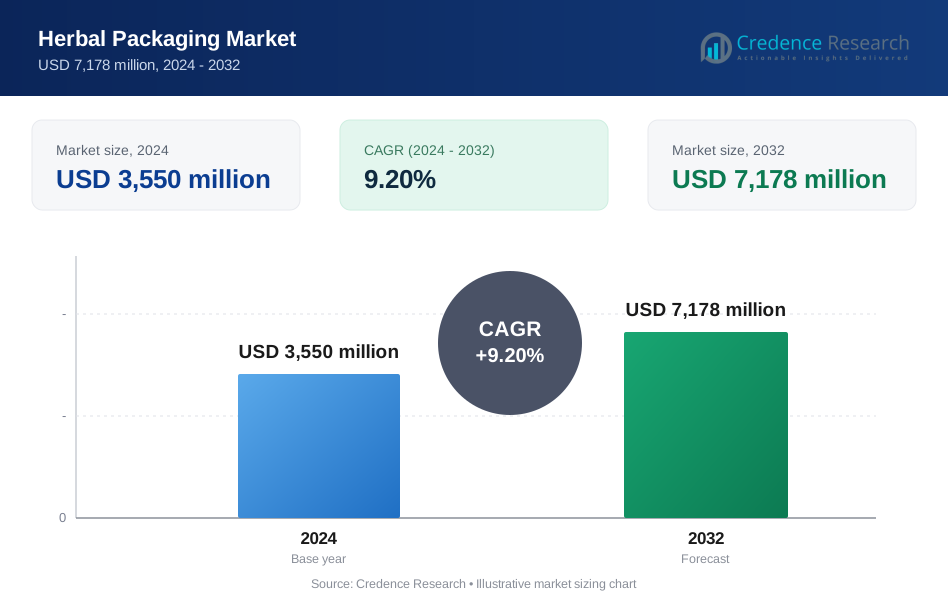
The botanical packaging market is projected to grow from USD 3,550 million in 2024 to USD 7,178 million by 2032, registering a CAGR of 9.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Herbal Packaging Market Size 2024 | USD 3,550 million |
| Herbal Packaging Market, CAGR | 9.2% |
| Herbal Packaging Market Size 2032 | USD 7,178 million |
The botanical packaging market is driven by the increasing consumer demand for sustainable, plant-based alternatives to conventional plastic packaging. Rising environmental concerns, coupled with stringent government regulations on single-use plastics, are encouraging manufacturers to adopt biodegradable and compostable materials derived from sources such as hemp, bamboo, cornstarch, and seaweed. The growing popularity of clean-label and eco-conscious products in industries such as cosmetics, food & beverages, and personal care is further supporting market growth. Brands are leveraging botanical packaging to enhance product appeal, align with green marketing strategies, and meet evolving consumer preferences. Trends include the integration of smart labeling for traceability, the use of minimalistic and recyclable designs, and innovations in material engineering to improve barrier properties and shelf life. Advances in bio-compound processing technologies and the rise of circular economy initiatives are also reshaping packaging strategies across sectors, positioning botanical packaging as a competitive and environmentally responsible solution in the global market.
The botanical packaging market shows strong regional dynamics, with Asia-Pacific leading at 36% market share in 2024, driven by manufacturing strength and regulatory support in countries like China and India. North America follows with 28%, backed by eco-conscious consumers and advanced packaging infrastructure in the U.S. and Canada. Europe holds 22% share, propelled by strict EU regulations and circular economy initiatives across Germany, France, and the Netherlands. The Rest of the World accounts for 14%, with growth emerging in Latin America, the Middle East, and Africa. Key players operating in the market include Uflex Ltd., WestRock Company, Gerresheimer AG, Constantia Flexibles Group, Amcor Limited, Smurfit Kappa Group, Ball Corporation, DS Smith Plc, Ardagh Group, Mondi Group, Tetra Pak International S.A., and Bemis Company, Inc. These companies focus on sustainable innovation, regulatory compliance, and strategic expansion to strengthen their global presence.
Market Insights
- The botanical packaging market is projected to grow from USD 3,550 million in 2024 to USD 7,178 million by 2032, registering a CAGR of 9.2%.
- Rising demand for eco-friendly, plant-based materials like hemp, bamboo, cornstarch, and seaweed is driving market adoption across food, cosmetics, and personal care industries.
- Clean-label and organic product categories are fueling adoption, as brands align packaging with consumer expectations for sustainability and transparency.
- Technological advancements in bio-compound materials are improving moisture resistance, durability, and scalability, enabling wider industrial use.
- Government bans on single-use plastics and support for circular economy models are fostering innovation and long-term market expansion.
- High production costs, limited infrastructure, and performance constraints in moisture-sensitive environments remain key challenges to growth.
- Asia-Pacific leads with 36% share, followed by North America (28%), Europe (22%), and the Rest of the World (14%), reflecting strong global momentum and regional adoption drivers.
Market Drivers
Rising Demand for Sustainable and Eco-Friendly Packaging Solutions
The botanical packaging market is driven by the global shift toward sustainability and environmental responsibility. Increasing awareness of plastic pollution and its harmful effects has led consumers and businesses to seek biodegradable and compostable packaging options. Botanical materials such as hemp, bamboo, and cornstarch offer natural alternatives that reduce reliance on fossil-fuel-based plastics. Governments worldwide are imposing stricter regulations on single-use plastics, compelling companies to explore plant-based packaging solutions. It supports corporate sustainability goals and brand differentiation. Companies across sectors are increasingly integrating botanical packaging into their operations to align with consumer values and environmental standards.
- For instance, Ecovative Design uses mycelium, the root structure of mushrooms, to create packaging that replaces synthetic foams, offering a fully biodegradable option for protecting electronics and furniture.
Expansion of Clean-Label and Organic Product Categories
Growing consumer interest in organic and clean-label products is fueling demand in the botanical packaging market. Natural and organic food, beverage, and personal care brands often choose packaging that reflects their product values. Botanical packaging complements the eco-conscious branding of these products, enhancing shelf appeal and consumer trust. It offers a visual and material extension of the product’s natural identity. Retailers and e-commerce platforms are also promoting such packaging to cater to health-conscious buyers. This shift reinforces the link between sustainable content and responsible packaging across the supply chain.
- For instance, Grind, a specialty coffee brand, uses home-compostable, plant-based pods in packaging that reinforces its sustainable ethos while maintaining strong brand recognition.
Advances in Bio-Based Material Technologies
echnological innovation in bio-compound development is expanding the performance capabilities of botanical packaging. Research into biopolymers and fiber-based composites has improved moisture resistance, durability, and transparency. It enables broader application across industries, including food preservation and pharmaceutical packaging. Manufacturers are investing in R&D to overcome traditional material limitations and scale production efficiently. The botanical packaging market benefits from these innovations by offering cost-effective, high-performance alternatives to conventional materials. This development accelerates the commercial viability and adoption of plant-based packaging worldwide.
Support from Government Policies and Circular Economy Initiatives
Policy support and waste-reduction mandates play a crucial role in accelerating growth in the botanical packaging market. National bans on plastic bags and packaging taxes are pushing businesses to transition toward compostable and renewable packaging materials. Governments and environmental agencies are funding pilot programs and certifications to ensure material safety and compostability standards. It creates a favorable regulatory environment for companies adopting botanical solutions. Public-private partnerships are promoting circular economy models centered on renewable resources. These measures collectively foster long-term market adoption and innovation in botanical packaging.
Market Trends
Integration of Botanical Packaging into Premium and Niche Product Lines
Brands are incorporating botanical packaging into premium and niche product categories to align with sustainability-driven consumer values. High-end cosmetics, gourmet food products, and artisanal goods now feature plant-based packaging to reinforce eco-conscious brand narratives. This trend reflects a strategic move to connect packaging aesthetics with product purity and ethical sourcing. The botanical packaging market benefits from this alignment by expanding its presence in lifestyle-oriented segments. It allows brands to create differentiation in crowded markets while reinforcing authenticity and transparency. Consumers are willing to pay a premium for products that match sustainability claims, including packaging.
Adoption of Minimalist and Recyclable Design Aesthetics
Design trends in the botanical packaging market are shifting toward minimalist visuals and recyclable structures. Simple, clean designs communicate purity, environmental responsibility, and product safety. Brands are removing excessive dyes, coatings, and multilayered formats to ensure recyclability and biodegradability. It enhances the product's environmental profile while streamlining production costs. Transparent labeling, embossed logos, and natural color tones are now common features. These design principles support sustainability messaging and strengthen shelf appeal without compromising functionality or durability.
- For instance, skincare brand NOTO utilizes biodegradable and recycled materials for both products and shipping, coupled with minimalistic, transparent branding-demonstrating a unified focus on environmental responsibility and streamlined production.
Growth in Smart and Traceable Packaging Applications
The integration of smart technologies into botanical packaging is emerging as a key trend, especially in regulated sectors like food and pharmaceuticals. Brands are embedding QR codes, NFC tags, and blockchain identifiers to offer traceability, supply chain transparency, and product authentication. It enhances consumer trust and enables efficient inventory management. The botanical packaging market is responding by incorporating intelligent features into biodegradable formats. This convergence of digital and sustainable packaging opens new opportunities for innovation. It also supports compliance with traceability regulations in global trade.
- For instance, Rubitel, a US company, embeds real-time sensors into packaging materials used for pharmaceuticals, allowing businesses to monitor temperature-sensitive medicines throughout the supply chain and thus prevent spoilage and ensure efficacy.
Investment in Scalable Manufacturing and Supply Chain Ecosystems
Investments in scalable production technologies and regional supply chains are shaping the future of the botanical packaging market. Companies are establishing local sourcing and decentralized manufacturing hubs to reduce carbon footprints and supply risks. It supports faster turnaround times and greater resilience in material procurement. Automation, 3D printing, and modular systems are improving efficiency and flexibility in plant-based packaging production. Strategic partnerships between bio-material suppliers and packaging firms are also expanding market access. These developments are making botanical packaging more competitive with conventional materials on cost, volume, and performance.
Market Challenges Analysis
High Production Costs and Limited Infrastructure
One of the primary challenges in the botanical packaging market is the high cost of raw materials and processing technologies. Plant-based polymers and fibers often require specialized equipment and labor-intensive methods, which drive up production expenses. Many regions lack the necessary manufacturing infrastructure to support large-scale operations, leading to reliance on imports and higher logistics costs. It limits the competitiveness of botanical packaging against conventional plastic solutions. Small and medium-sized enterprises face barriers to entry due to capital-intensive setup requirements. These constraints hinder widespread market penetration despite rising consumer demand.
Performance Limitations and Shelf Life Concerns
Another key challenge is the performance limitations of certain botanical materials when exposed to moisture, temperature fluctuations, or prolonged storage. Many bio-based packaging solutions struggle to match the barrier properties, strength, or longevity of synthetic alternatives. It creates difficulties in sectors such as pharmaceuticals and food, where stringent preservation standards are required. Ensuring consistent material quality and regulatory compliance remains a hurdle for manufacturers. The need for additives or multi-layer combinations can complicate recyclability and increase costs. Addressing these technical shortcomings is essential for scaling adoption in high-volume, performance-sensitive applications.
Market Opportunities
Expansion into Emerging Markets and New End-Use Sectors
The botanical packaging market holds strong growth potential in emerging economies where regulatory reforms and consumer awareness are advancing rapidly. Countries in Asia-Pacific, Latin America, and the Middle East are increasing investments in sustainable infrastructure and waste management. It creates favorable conditions for the adoption of eco-friendly packaging alternatives. New opportunities are emerging in sectors such as ready-to-eat foods, wellness products, and specialty beverages, where demand for natural and ethical packaging is rising. Government support for green manufacturing and incentives for biodegradable solutions further enhance market prospects. These factors position botanical packaging as a viable choice for diverse applications beyond traditional niches.
Innovation in Material Science and Circular Business Models
Advancements in bio-based material research are unlocking new possibilities for improving the performance and scalability of botanical packaging. Startups and research institutions are developing compostable composites with enhanced strength, flexibility, and moisture resistance. It enables application in high-demand industries such as pharmaceuticals, electronics, and industrial packaging. The shift toward circular economy models presents another opportunity, where companies adopt closed-loop systems that integrate reuse, recycling, and organic waste recovery. These approaches reduce environmental impact and align with corporate ESG goals. Collaborative innovation across supply chains will drive commercialization and expand the market’s reach.
Market Segmentation Analysis:
By Material
The botanical packaging market features a wide range of eco-friendly materials tailored to meet sustainability goals and performance needs. Paper-based and cardboard packaging dominate due to their cost-effectiveness and recyclability. Biodegradable and compostable materials such as cornstarch-based polymers and bamboo fibers are gaining popularity for their low environmental footprint. Sustainable or recycled materials are being adopted by brands targeting zero-waste practices. It supports compliance with green labeling standards and appeals to environmentally conscious consumers. Each material type offers distinct advantages in terms of texture, shelf appeal, and regulatory approval.
- For instance, the Magical Mushroom Company® produces mushroom-based packaging for brands like BA Kitchens and Castrads; this material, grown from mycelium and agricultural waste, is home-compostable and aims to fully replace polystyrene in protective packaging for household goods and industrial components
By Packaging Type
Packaging type in the botanical packaging market spans across various formats designed for durability, functionality, and brand differentiation. Boxes, tubes, and cartons are widely used for retail and gifting applications due to their rigidity and visual impact. Pouches and bags provide lightweight, flexible solutions for bulk items and refillable goods. Jars and bottles are ideal for essential oils, extracts, and cosmetics, offering protective barriers and reusable formats. It allows brands to align product nature with packaging sustainability. Selection depends on storage needs, moisture resistance, and consumer handling preferences.
- For instance, Amcor plc developed paper-based cartons for Nestlé’s YES! snack bars in Europe, successfully shifting to paper instead of traditional plastics while ensuring strength and shelf life, and meeting recyclability standards.
By Product Type
The botanical packaging market serves a diverse product range including herbal teas, supplements, and essential oils. Each product type requires tailored packaging to preserve aroma, potency, and shelf life. Herbal cosmetics and extracts demand UV-resistant and leak-proof formats, while dried herbs and spices benefit from breathable yet protective solutions. It enables companies to deliver natural products with minimal ecological impact. The segment's expansion reflects consumer shifts toward holistic wellness and environmentally aligned product experiences.
Segments:
Based on Material
- Paper-based packaging
- Cardboard packaging
- Biodegradable/compostable materials
- Sustainable or recycled materials
Based on Packaging Type
- Boxes
- Tubes
- Pouches
- Bags
- Jars
- Bottles
- Cartons
Based on Product Type
- Herbal teas
- Herbal supplements
- Essential oils
- Herbal cosmetics
- Dried herbs and spices
- Herbal extracts
Based on Application
- Food and beverages
- Pharmaceuticals
- Cosmetics and personal care
- Nutraceuticals
- Aromatherapy
Based on Labeling and Branding
- Custom labels
- Brand-specific designs
- Sustainable packaging certifications
- Eco-friendly messaging
Based on Channel
- Retail stores
- E-commerce
- Specialty stores
- Pharmacies and health stores
Based on Size
- Small packaging (samples, travel size)
- Standard packaging
- Bulk packaging
Based on Sustainability Features
- Recyclability
- Compostability
- Biodegradability
- Renewable materials
Based on Packaging Functionality:
- Moisture resistance
- Airtight/sealed packaging
- UV protection
- Child-resistant packaging
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific leads the botanical packaging market, holding 36% of the global share in 2024. Strong manufacturing capacity, growing environmental regulations, and high consumer demand for sustainable products support regional dominance. Countries like China, India, and Japan are investing in biodegradable packaging technologies and local sourcing of botanical materials. It benefits from rising awareness around eco-packaging in food, personal care, and wellness sectors. Rapid urbanization and e-commerce growth are accelerating demand for plant-based alternatives. Government bans on single-use plastics across the region further boost market expansion.
North America
North America accounts for 28% of the global botanical packaging market in 2024. The region is driven by advanced packaging infrastructure, high consumer awareness, and strong presence of organic product manufacturers. The United States leads in adoption across herbal supplements, cosmetics, and natural food packaging. It benefits from supportive regulatory policies, green certifications, and brand-driven sustainability goals. Investment in R&D for high-performance bio-based materials strengthens innovation. Retailers and e-commerce platforms in the region are prioritizing eco-friendly packaging for market positioning and regulatory compliance.
Europe
Europe holds 22% of the global botanical packaging market share in 2024. The region demonstrates strong alignment with circular economy goals and aggressive sustainability mandates from the EU. Countries like Germany, France, and the Netherlands are encouraging compostable, recyclable, and plant-derived packaging materials. It supports innovation through public-private partnerships and funding for green packaging initiatives. Consumer demand for ethical products reinforces the shift toward botanical formats in cosmetics, herbal teas, and supplements. Local sourcing and closed-loop systems are gaining momentum across industries.
Rest of the World
The Rest of the World contributes 14% to the global botanical packaging market in 2024. Latin America, the Middle East, and Africa are witnessing gradual growth due to rising awareness and government-led environmental programs. It faces infrastructure and cost-related challenges but offers long-term potential through sustainable development efforts and expanding wellness sectors.
Key Player Analysis
- Uflex Ltd.
- WestRock Company
- Gerresheimer AG
- Constantia Flexibles Group
- Amcor Limited
- Smurfit Kappa Group
- Ball Corporation
- DS Smith Plc
- Ardagh Group
- Mondi Group
- Tetra Pak International S.A.
- Bemis Company, Inc.
Competitive Analysis
The botanical packaging market is moderately competitive, with key players focusing on innovation, material sustainability, and regional expansion. Companies such as Uflex Ltd., WestRock Company, Gerresheimer AG, and Constantia Flexibles Group invest in plant-based materials and biodegradable solutions to meet rising demand for eco-friendly packaging. It sees active collaboration between packaging firms and natural product brands to develop tailored formats for herbal teas, supplements, and cosmetics. Amcor Limited, Ball Corporation, and Mondi Group leverage advanced technologies to enhance barrier performance and visual appeal. Tetra Pak and DS Smith focus on recyclable and compostable packaging for the food and beverage sector. Players prioritize regulatory compliance and certifications to maintain market presence across North America, Europe, and Asia-Pacific. Strategic partnerships, mergers, and product diversification continue to shape competition, while smaller firms capitalize on niche offerings and local sourcing strategies to gain market share. The market encourages continuous investment in R&D and supply chain optimization.
Recent Developments
- In January 2024, Sealed Air Corporation launched its first bio-based and compostable protein packaging tray at IPPE 2024, designed to suit existing food processing equipment.
- In June 2025, Wildsmith, a botanical skincare brand, partnered with Shellworks to introduce its Hydrating Light Cream in fully compostable Vivomer packaging as part of its sustainability efforts.
- In February 2024, Berry Global unveiled a reusable tableware range aimed at addressing the growing demand for sustainable solutions in the foodservice industry.
- In September 2024, Novolex announced the acquisition of assets from American Twisting, a producer of twisted-paper handles used in paper bag manufacturing, to enhance its sustainable packaging portfolio.
Market Concentration & Characteristics
The botanical packaging market exhibits moderate concentration, with a mix of global leaders and regional players competing through innovation, sustainability, and product differentiation. Key companies such as Amcor Limited, WestRock Company, Mondi Group, and Gerresheimer AG hold significant market influence due to their established supply chains, R&D capabilities, and global reach. It features strong focus on biodegradable and compostable materials sourced from renewable plants like hemp, bamboo, and cornstarch. Market participants emphasize regulatory compliance, cost optimization, and performance improvements to stay competitive. The market is characterized by rising demand for clean-label and eco-conscious packaging, especially in the food, cosmetics, and wellness sectors. It shows a shift toward minimalist, recyclable, and traceable designs aligned with evolving consumer values. Entry barriers remain moderate due to high raw material costs and infrastructure demands, but innovation and strategic partnerships offer room for new entrants. Market growth depends on sustainability mandates, material innovation, and regional production capabilities.
Report Coverage
The research report offers an in-depth analysis based on Material, Packaging Type, Product Type, Application, Labeling and Branding, Channel, Size, Sustainability Feature, Packaging Functionality and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumer preference for plant-based, biodegradable packaging will continue to drive product innovation and material development.
- Brands will increasingly adopt botanical packaging to align with sustainability goals and regulatory requirements.
- Demand will rise across herbal supplements, cosmetics, and food segments due to the natural positioning of these products.
- Investment in local manufacturing and bio-material sourcing will expand to reduce supply chain risks.
- Companies will integrate smart labeling and traceability features to enhance product transparency and safety.
- Research in bio-compounds will improve barrier properties, enabling broader applications in moisture-sensitive sectors.
- Governments will implement stricter bans on plastic use, pushing businesses toward botanical alternatives.
- Retailers and e-commerce platforms will prioritize eco-friendly packaging to strengthen brand positioning.
- Collaboration between packaging companies and natural product brands will accelerate customized, plant-based solutions.
- Emerging markets will witness faster adoption due to regulatory reforms and growing environmental awareness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Sustainable and Eco-Friendly Packaging Solutions
Increasing consumer and regulatory pressure to reduce plastic waste is driving manufacturers to adopt biodegradable and compostable botanical packaging materials, such as hemp, bamboo, and cornstarch, to meet sustainability goals and differentiate their brands.
Expansion of Clean-Label and Organic Product Categories
Brands in food, beverage, and personal care are increasingly choosing botanical packaging to align with the natural and organic positioning of their products, enhancing consumer trust and shelf appeal while supporting eco-conscious branding.
Advances in Bio-Based Material Technologies
Ongoing R&D in biopolymers and fiber-based composites is improving the performance, durability, and scalability of botanical packaging, enabling its use in more demanding applications such as food preservation and pharmaceuticals.
Support from Government Policies and Circular Economy Initiatives
Stricter regulations on single-use plastics and incentives for compostable and renewable packaging are compelling companies to transition to botanical solutions, while public-private partnerships and circular economy models foster innovation and long-term adoption.
Integration of Smart and Traceable Packaging Features
The adoption of smart labeling, QR codes, and traceability technologies in botanical packaging is enhancing supply chain transparency and product authentication, particularly in regulated sectors like food and pharmaceuticals, further driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the botanical packaging market?
What are the key segments within the botanical packaging market?
What are some challenges faced by the botanical packaging market?
Who are the major players in the botanical packaging market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Paper-based packaging
- 1.2.2 Cardboard packaging
- 1.2.3 Biodegradable/compostable materials
- 1.2.4 Sustainable or recycled materials
- 1.3 By Application
- 1.3.1 Food and beverages
- 1.3.2 Pharmaceuticals
- 1.3.3 Cosmetics and personal care
- 1.3.4 Nutraceuticals
- 1.3.5 Aromatherapy
- 1.4 By Product Type
- 1.4.1 Herbal teas
- 1.4.2 Herbal supplements
- 1.4.3 Essential oils
- 1.4.4 Herbal cosmetics
- 1.4.5 Dried herbs and spices
- 1.4.6 Herbal extracts
- 1.5 By Packaging Type
- 1.5.1 Boxes
- 1.5.2 Tubes
- 1.5.3 Pouches
- 1.5.4 Bags
- 1.5.5 Jars
- 1.5.6 Bottles
- 1.5.7 Cartons
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,550 million → 2032: USD 7,178 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Herbal Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Herbal Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Herbal Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Herbal Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Herbal Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Herbal Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Herbal Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Herbal Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,550 million → 2032: USD 7,178 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Herbal Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Paper-based packaging
- 12.3.7.2 Cardboard packaging
- 12.3.7.3 Biodegradable/compostable materials
- 12.3.7.4 Sustainable or recycled materials
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food and beverages
- 12.4.7.2 Pharmaceuticals
- 12.4.7.3 Cosmetics and personal care
- 12.4.7.4 Nutraceuticals
- 12.4.7.5 Aromatherapy
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Herbal teas
- 12.5.7.2 Herbal supplements
- 12.5.7.3 Essential oils
- 12.5.7.4 Herbal cosmetics
- 12.5.7.5 Dried herbs and spices
- 12.5.7.6 Herbal extracts
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Boxes
- 12.6.7.2 Tubes
- 12.6.7.3 Pouches
- 12.6.7.4 Bags
- 12.6.7.5 Jars
- 12.6.7.6 Bottles
- 12.6.7.7 Cartons
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Herbal Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Herbal Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Herbal Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Herbal Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Uflex Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 WestRock Company
- 18.4 Gerresheimer AG
- 18.5 Constantia Flexibles Group
- 18.6 Amcor Limited
- 18.7 Smurfit Kappa Group
- 18.8 Ball Corporation
- 18.9 DS Smith Plc
- 18.10 Ardagh Group
- 18.11 Mondi Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

