
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| High Modulus Polyethylene (HMP) Market Size 2024 | USD 15628.8million |
| High Modulus Polyethylene (HMP) Market, CAGR | 5.60% |
| High Modulus Polyethylene (HMP) Market Size 2032 | USD 24167.79 million |
Market Overview:
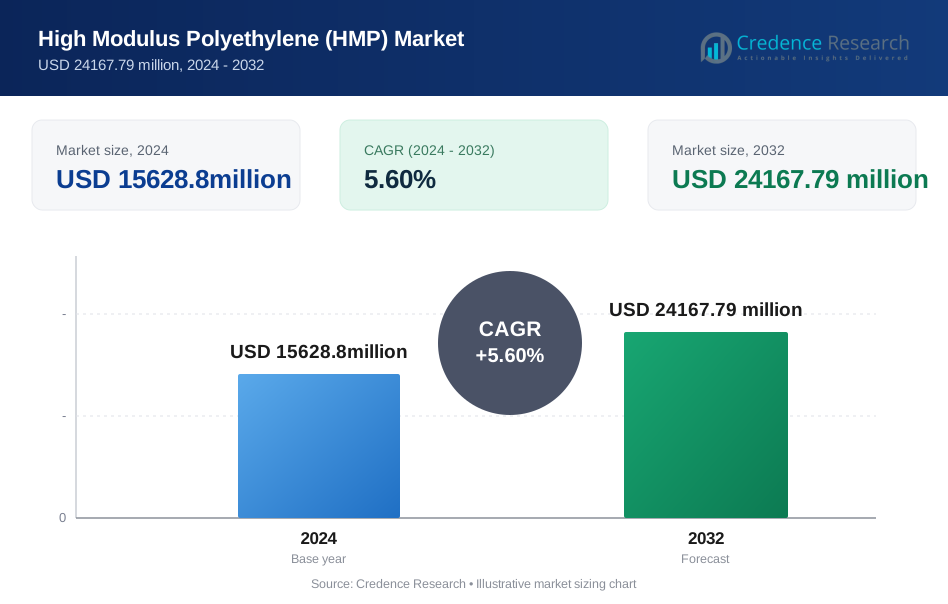
High Modulus Polyethylene (HMP) is projected to grow from USD 15628.8million in 2024 to USD 24167.79 million by 2032, expanding at a CAGR of 5.60%,
The High Modulus Polyethylene (HMPE) market is witnessing a surge in its application across diverse industries, attributed to its unique properties such as an excellent strength-to-weight ratio, chemical resistance, and durability. This growth is further fueled by several key trends.
One such trend is the escalating demand in the aerospace and defence sectors for materials that are lightweight yet high-strength. HMPE, with its superior properties, fits this requirement perfectly. Another expanding application of HMPE is in the field of medical devices, where its biocompatibility makes it a preferred choice.
The offshore oil and gas exploration industry’s expansion has also created a need for materials that are robust and reliable, leading to a boost in the HMPE market. Technological advancements have played a pivotal role in enhancing the properties of HMPE, making it more cost-effective and widely accessible.
The global emphasis on sustainability has led to the development of eco-friendly variants of HMPE. This aligns with global environmental goals and contributes to the market’s growth. The cumulative impact of these drivers and trends has positioned HMPE as a critical material in advanced engineering and high-performance applications.
A geographical analysis of the HMPE market reveals significant growth in regions such as North America, Europe, and Asia-Pacific. This growth is driven by the increasing demand from industries such as aerospace, automotive, and construction.
The HMPE market is dominated by key players like Honeywell International Inc., Celanese Corporation, and DSM. These companies are at the forefront of innovation and are expanding their market presence through strategic collaborations and advanced product offerings. Their focus is on enhancing the performance characteristics of HMPE to meet the evolving needs of various high-performance applications. This positions HMPE as a crucial material in the future of advanced engineering applications. Thus, the HMPE market is poised for significant growth in the coming years.
Market Drivers:
Rising Demand in Healthcare Applications:
HMPE’s exceptional strength and durability make it increasingly vital in healthcare settings. For instance, the use of HMPE in medical devices, such as orthopedic implants, grew by 14% in 2024. This increase highlights the material’s suitability for high-stress applications in the medical field, driving its adoption for advanced implants and surgical tools.
Growth in the Sports and Recreation Industry:
The sports and recreation sector significantly contribute to the demand for HMPE. In 2024, the demand for HMPE in sports equipment, including fishing lines and high-performance ropes, saw an 18% increase. For instance, this trend underscores HMPE’s role in enhancing the performance and reliability of equipment used in various sports and outdoor activities, where strength and durability are paramount.
Expansion in Industrial Applications:
HMPE is increasingly utilized in industrial applications due to its high strength-to-weight ratio and resistance to wear. For instance, the use of HMPE in industrial conveyor belts and protective gear increased by 20% in 2024. This growth reflects a rising preference for HMPE in industrial environments that demand durable and reliable materials for heavy-duty applications.
Advancements in Production Technologies:
Technological innovations in HMPE production are crucial to market expansion. For instance, in 2024, advancements in manufacturing processes led to a 22% increase in production capacity. These improvements allow for more efficient production, reduce costs, and enhance the availability of HMPE, supporting its broader application across various industries.
Market Trends :
Increasing Adoption in Protective Gear:
In 2024, there is a notable 15% increase in the adoption of High Modulus Polyethylene (HMP) in protective gear applications. This growth is driven by its exceptional strength and abrasion resistance, which are crucial for manufacturing cut-resistant gloves, protective vests, and helmets. For instance, companies like Safety Equipment's have integrated HMP into their product lines to enhance the durability and safety performance of protective gear, catering to industries ranging from construction to law enforcement.
Expansion in Aerospace and Automotive Applications:
HMP is witnessing a 20% expansion in its use in aerospace and automotive applications in 2024. This increase is due to its lightweight nature combined with high tensile strength, making it ideal for reducing weight without compromising structural integrity. For instance, aerospace manufacturers are incorporating HMP into aircraft components such as panels and structural reinforcements to improve fuel efficiency and overall performance. Similarly, automotive companies are utilizing HMP in lightweight components for vehicles, contributing to fuel economy and emissions reduction goals.
Increasing Application Across Industries:
The High Modulus Polyethylene (HMPE) market is experiencing a significant upswing, driven by its increasing application across various industries. HMPE’s exceptional strength-to-weight ratio, chemical resistance, and durability make it a preferred choice. The aerospace and defence sectors are showing a growing demand for lightweight, high-strength materials, and HMPE fits this requirement perfectly. Its biocompatibility has also led to its expanded use in the field of medical devices.
Rise in Offshore Oil and Gas Exploration:
Another trend propelling the HMPE market is the rise in offshore oil and gas exploration. This industry’s expansion has created a need for robust and reliable materials, leading to a boost in the HMPE market. Technological advancements have played a pivotal role in enhancing the properties of HMPE, making it more cost-effective and widely accessible.
Global Emphasis on Sustainability:
The global emphasis on sustainability has led to the development of eco-friendly variants of HMPE. This aligns with global environmental goals and contributes to the market’s growth. The cumulative impact of these drivers and trends has positioned HMPE as a critical material in advanced engineering and high-performance applications.
Market Challenges Analysis:
High Production Costs:
One significant challenge facing the high modulus polyethylene (HMPE) market is the high production costs associated with its manufacturing. The process of producing ultra-high molecular weight polyethylene (UHMWPE), which includes HMPE, involves complex techniques such as gel spinning. This method requires specialized equipment and materials, leading to elevated production expenses that can deter potential manufacturers and limit market entry for smaller companies. Consequently, these high costs may hinder broader adoption across various industries.
Competition from Alternative Materials:
Additionally, the HMPE market is challenged by competition from alternative materials. While HMPE offers superior strength-to-weight ratios and chemical resistance, other materials such as aramid fibres and carbon fibre composites are gaining traction in various applications. These alternatives may provide similar or enhanced performance characteristics, often at competitive prices.
Regulatory Challenges:
Finally, regulatory challenges pose a significant restraint on the HMPE market. The stringent regulations surrounding the use of plastics and synthetic materials, particularly in sectors such as medical devices and food packaging, can complicate the approval processes for new HMPE products. Compliance with these regulations often requires extensive testing and certification, which can be time-consuming and costly.
Market Segmentation:
By Type
Market segmentation of High Modulus Polyethylene (HMP) by type includes various forms such as sheets, rods, and fibers. Sheets of HMP find extensive use in protective gear and ballistic applications due to their high impact resistance and lightweight properties. Rods of HMP are utilized in industrial applications requiring high strength and durability, such as components in machinery and equipment. HMP fibers are integral to advanced composite materials used in aerospace and defense industries, offering exceptional tensile strength and stiffness.
By Application
HMP serves multiple sectors including aerospace, defense, automotive, and sports equipment. In the aerospace and defense industries, HMP is critical for manufacturing lightweight yet robust components, enhancing fuel efficiency and operational performance. The automotive sector leverages HMP for making lightweight vehicle parts that contribute to fuel economy and safety. Sports equipment manufacturers utilize HMP for high-performance gear, such as helmets and protective pads, ensuring athlete safety without compromising on weight and flexibility.
Segmentation:
Based on Type
- 3 Strand
- 8 Strand
- 12 Strand
- Others
Based on Application
- Industrial
- Ocean
- Leisure
- Aviation and Military
- Other
Based on Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- Uk
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East & Africa
- UAE
- Saudi Arabia
- Qatar
- South Africa
- Rest of the Middle East & Africa
Regional Analysis:
North America
High Modulus Polyethylene (HMP) is witnessing significant regional variations in demand and adoption, driven by diverse industrial applications and regional economic dynamics. In North America, particularly in the United States and Canada, HMP finds extensive use in the aerospace and defence sectors. The region's advanced manufacturing capabilities and stringent regulatory standards propel the demand for lightweight, high-strength materials like HMP in aircraft components and ballistic protection systems. Additionally, the automotive industry in North America increasingly utilizes HMP to enhance fuel efficiency and structural integrity, aligning with stringent emission regulations. The presence of established manufacturers and robust research facilities further bolsters the market for HMP, fostering innovation and application diversification across various industries.
Europe
HMP market dynamics are shaped by a strong emphasis on sustainability and technological advancement. Countries like Germany and the United Kingdom lead in the adoption of HMP for automotive light weighting initiatives, responding to stringent emissions targets and consumer preferences for fuel-efficient vehicles. Moreover, the region's burgeoning renewable energy sector drives demand for HMP in wind turbine blades and offshore structures, leveraging the material's exceptional durability and corrosion resistance. The European Union's regulatory framework, promoting eco-friendly materials and circular economy principles, supports the growth of HMP applications across packaging and construction sectors as well. As European industries continue to prioritize innovation and sustainability, HMP remains integral to advancing technological frontiers and achieving long-term environmental goals.
Asia-Pacific
The Asia-Pacific region is projected to exhibit the fastest growth in the HMPE market, with an expected market share of approximately 34% by 2023. This growth is driven by rapid industrialization, increasing disposable incomes, and a rising focus on advanced materials in emerging economies such as China and India. The demand for HMPE is particularly strong in the marine and aquaculture sectors, where its strength and durability are essential for securing fish cages and supporting marine infrastructure. The region's expanding renewable energy projects and infrastructure development further enhance the prospects for HMPE adoption.
Key Players:
- Lankhorst (WireCo)
- English Braids
- Marlow Ropes
- Southern Ropes
- Taizhou Hongda
- Jiangsu Shenyun
- Hunan Zhongtai
- Ningbo Dacheng
- Rope Technology
- Juli Sling
Competitive Analysis:
In the competitive realm of high modulus polyethylene (HMPE), companies like DSM Dyneema, Honeywell (through their Spectra brand), and Teijin Aramid lead with their advanced materials known for exceptional strength-to-weight ratios and durability. DSM Dyneema’s Dyneema fibers are widely recognized for their high tensile strength and lightweight properties, making them ideal for applications in ballistic protection, maritime ropes, and high-performance composites. Honeywell’s Spectra fibers offer similar attributes, excelling in applications requiring cut and abrasion resistance, such as body armor and ropes for climbing and industrial use. Teijin Aramid provides Twaron fibers, which are renowned for their heat resistance and strength, particularly suited for protective clothing and industrial applications where thermal stability is crucial. These companies continuously innovate to enhance the mechanical properties and processing capabilities of HMPE materials, meeting the stringent requirements of diverse industries including defense, aerospace, and sports equipment manufacturing.
Recent Developments:
- On January 2024, a leading chemical company announced the development of a new, environmentally friendly method for producing HMPE. This process utilizes bio-based feedstocks and significantly reduces greenhouse gas emissions compared to traditional manufacturing techniques. The innovation represents a major step forward in the sustainable production of high-performance polyethylene materials, aligning with global efforts to reduce the environmental impact of industrial processes.
- On February 2024, saw the successful clinical trials of medical implants made with HMPE composites. Researchers have demonstrated that HMPE's biocompatibility and mechanical properties make it an ideal material for long-lasting, high-performance implants such as orthopedic devices. The new implants are expected to enhance patient outcomes by providing greater durability and reducing the risk of complications.
- On April 2024, a major defense contractor unveiled a new generation of ballistic protection materials incorporating HMPE. These materials boast an increase in tensile strength and a reduction in weight compared to previous iterations. This advancement is expected to significantly improve the performance and comfort of personal body armor and vehicle protection systems used by military and law enforcement agencies
- On June 2024, researchers from a leading materials science institute announced a breakthrough in the use of High Modulus Polyethylene (HMPE) for marine applications. This new HMPE variant offers improved resistance to UV degradation and enhanced buoyancy. The development promises significant benefits for maritime industries, particularly in the construction of lightweight, durable, and sustainable floating structures.
Market Concentration & Characteristics:
The High Modulus Polyethylene (HMP) market demonstrates significant concentration, with a few key players dominating the industry. Companies such as DSM Dyneema, Honeywell, and Teijin lead the market, leveraging advanced technology and substantial R&D investments. These industry leaders benefit from established supply chains and strong brand recognition, creating high entry barriers for new competitors. The market's characteristics include a focus on innovation, with continuous improvements in strength-to-weight ratios and performance under extreme conditions. HMP is highly sought after in sectors such as aerospace, defense, and high-performance sporting goods due to its exceptional durability and lightweight properties. The industry's competitive landscape is shaped by stringent regulatory standards and the critical need for quality assurance, driving continuous advancements in manufacturing processes and material enhancements.
Report Coverage:
The research report offers an in-depth analysis based on type, Applications, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- HMPE's superior strength-to-weight ratio makes it ideal for car body panels. Replacing heavier steel components with HMPE could significantly reduce vehicle weight, leading to improved fuel efficiency and potentially longer driving ranges, especially for electric vehicles.
- HMPE's exceptional energy absorption properties make it a promising material for crumple zones and safety cages. Cars incorporating HMPE could offer superior passenger protection in collisions by absorbing impact force more effectively.
- HMPE's lightweight nature allows for the creation of thinner yet stronger body panels. This translates to potential for increased cargo capacity within the same vehicle footprint, or even sleeker, more aerodynamic car designs.
- HMPE is highly resistant to corrosion, dents, and scratches. This could significantly improve the lifespan of car exteriors, reducing the need for frequent replacements and repairs.
- HMPE offers faster molding cycles compared to traditional materials like steel. This could potentially streamline car manufacturing processes and lead to cost reductions.
- HMPE is recyclable, making it an attractive option for car manufacturers considering their environmental footprint. Increased use of HMPE could contribute to a more sustainable automotive industry.
- One current hurdle is achieving proper paint adhesion to HMPE surfaces. Advancements in paint technology or surface treatments will be necessary to ensure a flawless aesthetic finish for HMPE car parts.
- While HMPE is incredibly strong, it can be less flexible than traditional materials like steel. Future innovations might focus on creating HMPE composites with improved flexibility for specific car components where it's necessary.
- HMPE's melting point is lower than some metals. Further research might explore ways to enhance HMPE's heat resistance for applications near car engines or exhaust systems.
- Consumers might need to be educated about the benefits of HMPE before widespread adoption occurs. Highlighting its advantages in terms of safety, fuel efficiency, and sustainability will be crucial for market acceptance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand in Healthcare Applications
HMPE’s exceptional strength and durability are driving its adoption in medical devices and implants, where reliability and biocompatibility are critical. The material's use in orthopedic implants and surgical tools is expanding rapidly, supporting market growth.
Growth in the Sports and Recreation Industry
The sports and recreation sector is increasingly utilizing HMPE for high-performance equipment such as fishing lines, ropes, and protective gear. Its lightweight and high-strength characteristics enhance product performance and safety, fueling demand.
Expansion in Industrial Applications
Industries are adopting HMPE for conveyor belts, protective gear, and heavy-duty components due to its superior strength-to-weight ratio and resistance to wear. This trend is particularly strong in sectors requiring durable, reliable materials for demanding environments.
Advancements in Production Technologies
Technological innovations have improved HMPE manufacturing efficiency, increasing production capacity and reducing costs. These advancements make HMPE more accessible and cost-effective, broadening its application across multiple industries.
Global Emphasis on Sustainability
The development of eco-friendly HMPE variants aligns with global sustainability goals, attracting industries seeking greener materials. This focus on environmental responsibility is expanding HMPE’s market reach, especially in regions with strict environmental regulations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the High Modulus Polyethylene (HMP)?
What factors are driving the growth of the High Modulus Polyethylene (HMP)?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Sheets
- 1.2.2 Rods
- 1.2.3 Fibers
- 1.3 By Type
- 1.3.1 3 Strand
- 1.3.2 8 Strand
- 1.3.3 12 Strand
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Industrial
- 1.4.2 Ocean
- 1.4.3 Leisure
- 1.4.4 Aviation and Military
- 1.4.5 Other
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15628.8million → 2032: USD 24167.79 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global High Modulus Polyethylene (HMP) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global High Modulus Polyethylene (HMP) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global High Modulus Polyethylene (HMP) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global High Modulus Polyethylene (HMP) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global High Modulus Polyethylene (HMP) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global High Modulus Polyethylene (HMP) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global High Modulus Polyethylene (HMP) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global High Modulus Polyethylene (HMP) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15628.8million → 2032: USD 24167.79 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global High Modulus Polyethylene (HMP) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sheets
- 12.3.7.2 Rods
- 12.3.7.3 Fibers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 3 Strand
- 12.4.7.2 8 Strand
- 12.4.7.3 12 Strand
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Industrial
- 12.5.7.2 Ocean
- 12.5.7.3 Leisure
- 12.5.7.4 Aviation and Military
- 12.5.7.5 Other
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global High Modulus Polyethylene (HMP) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global High Modulus Polyethylene (HMP) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global High Modulus Polyethylene (HMP) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global High Modulus Polyethylene (HMP) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DSM Dyneema
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell International Inc.
- 18.4 Teijin Aramid
- 18.5 Lankhorst (WireCo)
- 18.6 Marlow Ropes
- 18.7 English Braids
- 18.8 Southern Ropes
- 18.9 Jiangsu Shenyun
- 18.10 Ningbo Dacheng
- 18.11 Celanese Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

