
Market Overview:
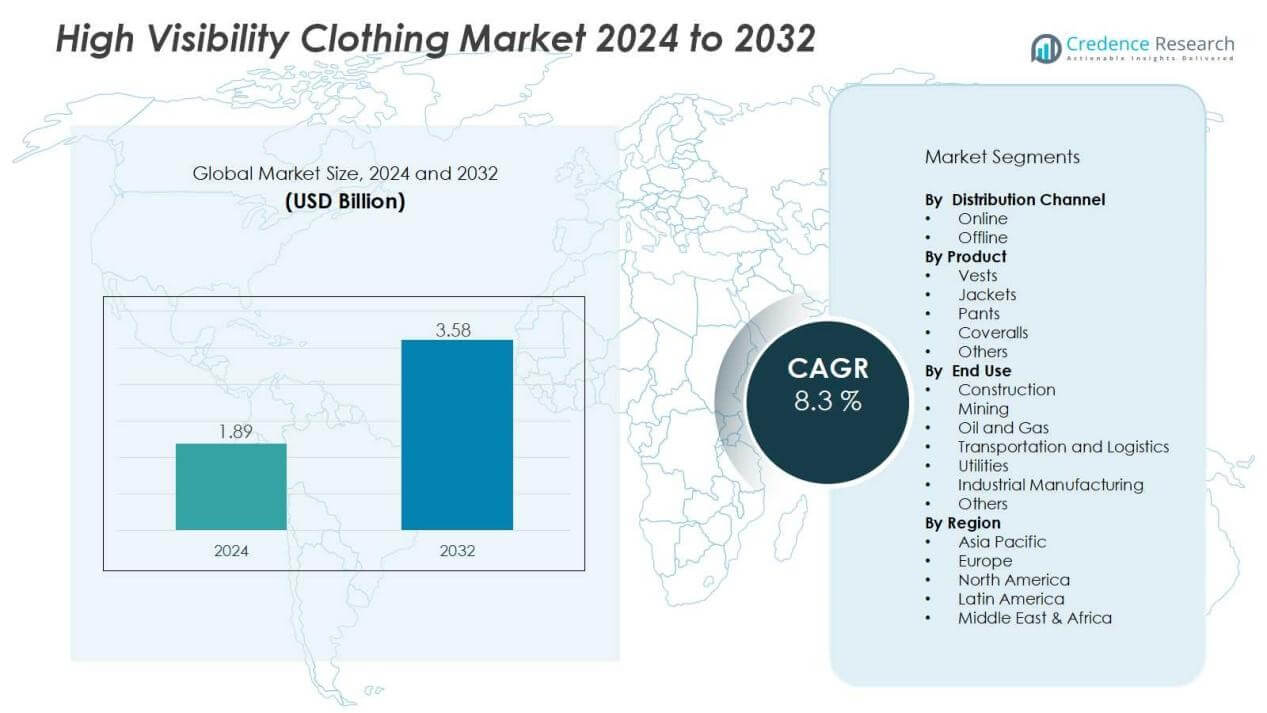
The high visibility clothing market size was valued at USD 1.89 billion in 2024 and is anticipated to reach USD 3.58 billion by 2032, at a CAGR of 8.3 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| High Visibility Clothing Market Size 2024 | USD 1.89 Billion |
| High Visibility Clothing Market, CAGR | 8.3% |
| High Visibility Clothing Market Size 2032 | USD 3.58 Billion |
Key drivers include strict occupational safety norms, growing infrastructure projects, and heightened worker safety awareness. Advancements in fabric technology, such as breathable materials and flame-resistant blends, further support adoption. Additionally, the rise in urbanization and industrialization has increased employment in high-risk environments, strengthening demand for protective workwear. The integration of reflective materials with ergonomic designs enhances worker comfort while meeting safety standards, fostering broader usage across industries.
Regionally, North America leads the market due to strict OSHA regulations and large-scale construction activity. Europe follows with strong adoption supported by stringent EN ISO standards and a mature industrial base. The Asia-Pacific region is poised for the fastest growth, driven by rapid industrialization, expanding infrastructure development, and growing workforce safety initiatives in China, India, and Southeast Asia. Latin America and the Middle East & Africa show gradual adoption, supported by infrastructure investments and government-driven safety campaigns.
Market Insights:
- The high visibility clothing market was valued at USD 1.89 billion in 2024 and is projected to reach USD 3.58 billion by 2032, reflecting a CAGR of 8.3% between 2024 and 2032.
- Strict occupational safety regulations, including OSHA in the U.S. and EN ISO in Europe, drive consistent adoption of certified reflective gear across high-risk industries.
- Expanding infrastructure projects across construction, mining, and transportation sectors in emerging economies continue to create steady demand for protective apparel.
- Technological advancements such as breathable fabrics, flame-resistant blends, and lightweight designs improve worker comfort while ensuring compliance.
- Rising safety awareness among employers and governments supports long-term investment in high visibility workwear, reinforcing workplace safety standards.
- High costs and limited durability of advanced garments, combined with fragmented regulations and low awareness in emerging economies, remain significant challenges.
- North America led with 38% share in 2024, Europe followed with 32%, and Asia-Pacific secured 24% supported by industrialization, infrastructure growth, and expanding workforce safety programs.
Market Drivers:
Stringent Workplace Safety Regulations Driving Demand:
The high visibility clothing market benefits from global enforcement of strict safety regulations. Organizations such as OSHA in the U.S. and EN ISO standards in Europe mandate the use of reflective gear for workers in high-risk sectors. Compliance requirements push employers to invest consistently in certified protective apparel. This regulatory framework ensures steady adoption across industries where safety is a priority.
- For Instance, DuPont's Tychem 6000 SFR lightweight coverall provides at least 30 minutes of protection against more than 250 chemical challenges and offers secondary flame resistance when worn over primary flame-resistant garments.
Expanding Infrastructure and Industrial Projects Creating Opportunities:
Massive infrastructure development across emerging economies increases the demand for protective apparel. Governments continue to launch large-scale construction, mining, and transportation projects that expose workers to hazardous environments. The high visibility clothing market gains traction through rising workforce participation in these industries. It supports safety goals while helping companies meet legal and operational standards.
- For Instance, 3M Scotchlite™ Reflective Material 8906 silver fabric trim has an initial average coefficient of retroreflection of 500 cd/lux/m², as tested according to international high-visibility standards such as ISO 20471.
Technological Advancements in Materials Enhancing Adoption:
Continuous innovation in fabrics improves durability, comfort, and visibility. Modern high visibility clothing integrates features like breathable materials, flame resistance, and lightweight construction. These improvements address worker needs for comfort while maintaining strict compliance with safety standards. It makes safety apparel more practical for long shifts in difficult conditions.
Rising Awareness of Worker Safety Supporting Growth:
Employers and governments place stronger emphasis on reducing workplace accidents and injuries. Safety training programs highlight the role of protective clothing in minimizing risks. The high visibility clothing market expands as awareness drives consistent investment in certified apparel. It strengthens long-term demand by linking safety culture with regulatory compliance and operational efficiency.
Market Trends:
Integration of Smart and Sustainable Fabrics Transforming Market Dynamics:
The high visibility clothing market is shifting toward advanced fabrics that combine safety with sustainability. Manufacturers introduce garments using recycled polyester, organic cotton, and eco-friendly dyes to address environmental concerns. It strengthens adoption among companies focused on corporate sustainability goals. Smart textiles with embedded sensors are also emerging, allowing monitoring of worker health and environmental conditions. These features enhance safety and align with digital transformation in industrial operations. Reflective coatings are now designed for higher durability and reduced maintenance, making them cost-effective over longer usage cycles. Growing investment in research supports this evolution across multiple sectors.
- For instance, Instacoat Premium Products (IPP) introduced the Silicone Roof Restoration System featuring 250 HS High Solids Silicone roof coating, which provides a seamless and weatherproof membrane while offering long-term renewable warranties and significant ongoing energy savings due to superior reflectivity.
Customization and Fashion Influence Expanding Market Appeal:
The high visibility clothing market is experiencing increased demand for customizable and stylish options. Employers seek branded safety gear that reflects corporate identity while ensuring compliance with safety standards. It encourages suppliers to offer flexible designs, varied colors, and ergonomic fits tailored to workforce needs. Fashion influence is visible in improved garment aesthetics, making apparel more acceptable for daily wear. Rising adoption of multi-functional workwear with weather resistance, flame protection, and enhanced comfort also shapes purchasing decisions. E-commerce platforms support this trend by providing easy access to varied product ranges with customization options. Growing consumer expectations for comfort and design continue to influence future innovations.
- For instance, Reflective Apparel Inc. offers over 50 different color and design combinations for high-visibility jackets and vests, supporting ergonomic fits and company branding for clients such as road maintenance services and airports as of 2024.
Market Challenges Analysis:
High Costs and Limited Durability Restricting Broader Adoption:
The high visibility clothing market faces cost-related challenges that limit wider adoption. Premium garments with advanced features such as flame resistance, breathable fabrics, or sensor integration often carry high price tags. Small and medium enterprises struggle to afford large-scale procurement, creating barriers to consistent adoption. It also faces durability concerns, as frequent washing, exposure to harsh weather, and wear on construction sites reduce garment lifespan. Employers must replace clothing more often, increasing operational costs. This combination of expense and limited longevity slows market penetration in cost-sensitive regions.
Lack of Standardization and Low Awareness Hindering Growth:
The high visibility clothing market encounters issues due to fragmented standards across regions. Regulations differ between the U.S., Europe, and Asia, creating uncertainty for manufacturers operating globally. It complicates compliance and slows product approvals in multiple geographies. Low awareness among workers and small contractors further restricts demand, especially in emerging economies. Some workers underestimate the role of reflective gear in preventing accidents, reducing voluntary use. Distribution challenges in rural and remote areas also limit product reach. These barriers reduce the market’s ability to achieve consistent global expansion.
Market Opportunities:
Growing Infrastructure Investments and Industrial Expansion Offering Growth Potential :
The high visibility clothing market is positioned to benefit from rising infrastructure projects worldwide. Governments in Asia-Pacific, the Middle East, and Africa continue to allocate significant budgets for roads, railways, and energy facilities. It supports consistent demand for certified protective apparel in construction, transportation, and utilities. Industrial expansion in mining, oil and gas, and manufacturing also creates opportunities for suppliers. Companies that provide durable and specialized safety gear stand to secure long-term contracts. Public-private partnerships for large-scale development further strengthen adoption across both developed and developing economies. This ongoing expansion ensures steady growth opportunities for market players.
Technological Integration and E-Commerce Channels Expanding Reach:
The high visibility clothing market is seeing opportunities through smart clothing and digital distribution. Integration of sensor-based fabrics enables monitoring of worker health, fatigue, and exposure levels. It enhances value beyond compliance by linking safety apparel with workplace efficiency. Online sales platforms expand product access for small contractors and remote regions, increasing market penetration. E-commerce also allows companies to offer customized designs and quick deliveries at competitive prices. Adoption of multi-functional garments combining weather resistance, visibility, and ergonomic comfort broadens applications. These innovations, supported by digital channels, create strong opportunities for global market growth.
Market Segmentation Analysis:
By Distribution Channel:
The high visibility clothing market is segmented into online and offline channels. Offline channels, including specialty stores and distributors, dominate due to direct access and bulk procurement from industries. It supports strong engagement with employers seeking certified products. Online channels are expanding quickly with e-commerce platforms offering customization, competitive pricing, and convenient delivery. Growth in digital adoption among small contractors and remote buyers strengthens this segment further.
- For Instance, the Portwest PW3 Hi-Vis 3-in-1 jacket, available through major online safety retailers, uses lightweight and flexible HiVisTex Pro segmented reflective tape and is often certified to a Class 3 visibility standard.
By Product:
The market includes vests, jackets, pants, coveralls, and others. Vests hold a major share because of their widespread use in construction and traffic management. Jackets and coveralls gain traction in colder regions where workers need thermal protection combined with visibility. Pants and multi-functional workwear add value for industries requiring full-body safety gear. It benefits from product innovations such as flame resistance and breathable fabrics. Demand continues to grow across multiple industrial applications.
- For Instance, 3M supplies Scotchlite reflective material to apparel manufacturers, who then produce high-visibility vests for various applications, including U.S. infrastructure projects, that comply with standards like ANSI/ISEA 107.
By End Use:
Key end-use sectors include construction, mining, oil and gas, transportation, and others. Construction dominates due to large workforce requirements and strict compliance mandates. Mining and oil and gas sectors adopt durable, flame-resistant clothing for high-risk environments. Transportation and logistics show rising demand for reflective gear to ensure roadside and warehouse safety. It gains steady adoption across utilities and industrial manufacturing, supported by strict workplace safety culture worldwide.
Segmentations:
By Distribution Channel:
- Online
- Offline
By Product:
- Vests
- Jackets
- Pants
- Coveralls
- Others
By End Use:
- Construction
- Mining
- Oil and Gas
- Transportation and Logistics
- Utilities
- Industrial Manufacturing
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America held 38% market share in 2024, supported by strict OSHA enforcement and industrial adoption. The high visibility clothing market in this region grows steadily with ongoing infrastructure projects and high construction activity. It benefits from advanced product offerings, including flame-resistant and weather-adapted fabrics. The U.S. remains the largest contributor due to strong regulatory compliance and workforce safety culture. Canada shows consistent growth with investments in mining and energy projects requiring protective apparel. Mexico contributes through manufacturing and industrial expansion, strengthening regional demand. Strategic partnerships with distributors enhance product accessibility across urban and industrial hubs.
Europe:
Europe accounted for 32% market share in 2024, driven by strict EN ISO standards across industries. The high visibility clothing market here gains momentum through demand in construction, utilities, and transportation. It thrives on innovation in sustainable fabrics and eco-certified safety apparel. Germany, France, and the U.K. lead adoption due to large infrastructure and industrial projects. Southern and Eastern Europe see growth with rising construction activity supported by EU-funded development. It benefits from strong awareness campaigns that highlight workplace safety. Manufacturers also leverage regional distribution networks to expand reach across diverse markets.
Asia-Pacific:
Asia-Pacific secured 24% market share in 2024, backed by rapid industrialization and infrastructure investments. The high visibility clothing market in this region expands swiftly with strong demand from China, India, and Southeast Asia. It is supported by government-driven safety programs and increasing adoption across mining, construction, and logistics. Growing employment in high-risk sectors drives procurement of certified apparel. Japan and South Korea contribute with advanced fabric technologies integrated into safety gear. Australia strengthens regional demand with mining and energy industries adopting compliance-driven apparel. Expanding e-commerce platforms improve accessibility for small contractors and enterprises across developing markets.
Key Player Analysis:
- 3M
- Bulwark Protection (Workwear Outfitters, LLC)
- Carhartt, Inc.
- Cintas Corporation
- Radians, Inc.
- Honeywell International Inc.
- Jiangsu Tianshi New Material Co., Ltd.
- Lakeland Industries, Inc.
- Portwest Ltd.
- Pyramex
Competitive Analysis:
The high visibility clothing market is highly competitive, shaped by global leaders and regional specialists. Key players include 3M, Bulwark Protection (Workwear Outfitters, LLC), Carhartt, Inc., Cintas Corporation, Radians, Inc., Honeywell International Inc., Jiangsu Tianshi New Material Co., Ltd., Lakeland Industries, Inc., Portwest Ltd., and Pyramex. It is defined by strong competition based on innovation, compliance with safety standards, and global distribution networks. Companies invest in advanced fabrics, such as flame-resistant and breathable materials, to strengthen product portfolios. Strategic partnerships with industries and government safety initiatives further support long-term contracts. E-commerce expansion and customization options also provide a competitive edge, helping companies reach smaller contractors and new regions. Leading firms focus on sustainability and smart textiles to differentiate offerings while maintaining strict adherence to ANSI and EN ISO standards. This competition drives continuous product upgrades and reinforces the industry’s emphasis on safety, comfort, and durability.
Recent Developments:
- In September 2025, 3M presented new automotive solutions at IAA Mobility, emphasizing continued innovation in mobility solutions.
- In August 2025, Thompson Safety acquired Bulwark Fire Protection, expanding Thompson Safety’s fire protection capabilities and team in Austin, Texas, though this fire protection company is distinct from the Bulwark PPE apparel line.
Report Coverage:
The research report offers an in-depth analysis based on Distribution Channel, Product, End Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The high visibility clothing market will expand with stricter enforcement of global workplace safety regulations.
- It will see rising adoption across construction, mining, oil and gas, and transportation industries.
- Sustainable and eco-friendly fabrics will gain importance as companies align with green initiatives.
- Smart textiles with sensor integration will emerge, offering monitoring of worker health and safety.
- Customization and branded safety apparel will increase demand among corporate buyers.
- E-commerce platforms will strengthen distribution by improving accessibility across remote and developing markets.
- Manufacturers will focus on multi-functional apparel combining weather resistance, durability, and ergonomic comfort.
- Regional growth will be led by Asia-Pacific, driven by rapid industrialization and infrastructure investments.
- Collaborations between manufacturers and governments will expand safety training and certified apparel adoption.
- It will remain highly competitive, with companies differentiating through innovation, sustainability, and strong distribution networks.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Workplace Safety Regulations
Global enforcement of safety standards such as OSHA in the U.S. and EN ISO in Europe mandates the use of high visibility clothing in high-risk sectors, compelling employers to invest in certified protective apparel and ensuring steady market adoption.
Expanding Infrastructure and Industrial Projects
Large-scale construction, mining, and transportation projects, especially in emerging economies, are increasing the number of workers exposed to hazardous environments, thereby driving demand for high visibility clothing to meet legal and operational safety requirements.
Technological Advancements in Materials
Innovations in fabric technology, including breathable, flame-resistant, and lightweight materials, are making high visibility clothing more comfortable and durable, encouraging broader adoption across industries with demanding work conditions.
Rising Worker Safety Awareness
Employers and governments are increasingly prioritizing workplace safety, with training programs and safety campaigns highlighting the importance of high visibility apparel, which supports long-term investment and consistent demand.
Growth of E-Commerce and Customization
The expansion of online sales channels and the availability of customizable, branded safety apparel are making high visibility clothing more accessible to small contractors and remote buyers, further expanding the market’s reach.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the High Visibility Clothing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the High Visibility Clothing Market projected to grow between 2024 and 2032?
Which High Visibility Clothing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the High Visibility Clothing Market?
Who are the leading companies in the High Visibility Clothing Market?
Which region commanded the largest share of the High Visibility Clothing Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Construction
- 1.2.2 Mining
- 1.2.3 Oil and Gas
- 1.2.4 Transportation and Logistics
- 1.2.5 Utilities
- 1.2.6 Industrial Manufacturing
- 1.2.7 Others
- 1.3 By Product
- 1.3.1 Vests
- 1.3.2 Jackets
- 1.3.3 Pants
- 1.3.4 Coveralls
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.89 billion → 2032: USD 3.58 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global High Visibility Clothing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global High Visibility Clothing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global High Visibility Clothing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global High Visibility Clothing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global High Visibility Clothing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global High Visibility Clothing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global High Visibility Clothing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global High Visibility Clothing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.89 billion → 2032: USD 3.58 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global High Visibility Clothing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Construction
- 12.3.7.2 Mining
- 12.3.7.3 Oil and Gas
- 12.3.7.4 Transportation and Logistics
- 12.3.7.5 Utilities
- 12.3.7.6 Industrial Manufacturing
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Vests
- 12.4.7.2 Jackets
- 12.4.7.3 Pants
- 12.4.7.4 Coveralls
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global High Visibility Clothing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global High Visibility Clothing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global High Visibility Clothing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global High Visibility Clothing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bulwark Protection (Workwear Outfitters, LLC)
- 18.4 Carhartt, Inc.
- 18.5 Cintas Corporation
- 18.6 Radians, Inc.
- 18.7 Honeywell International Inc.
- 18.8 Jiangsu Tianshi New Material Co., Ltd.
- 18.9 Lakeland Industries, Inc.
- 18.10 Portwest Ltd.
- 18.11 Pyramex
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

