
Market Overview
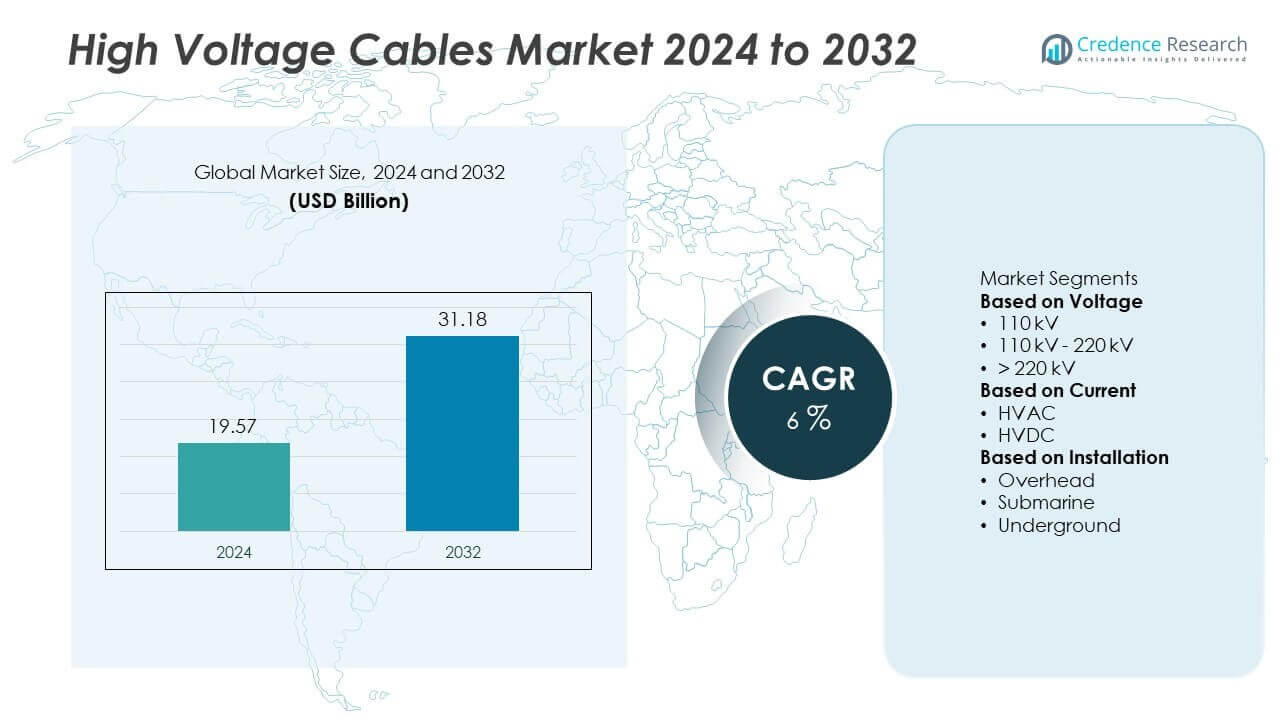
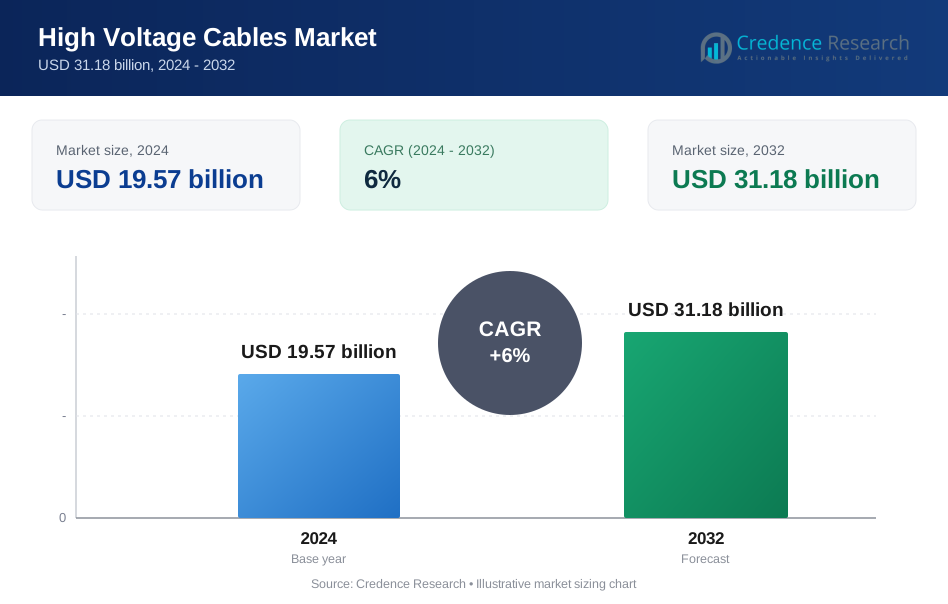
The High Voltage Cables Market was valued at USD 19.57 billion in 2024 and is projected to reach USD 31.18 billion by 2032, expanding at a CAGR of 6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| High Voltage Cables Market Size 2024 | USD 19.57 Billion |
| High Voltage Cables Market, CAGR | 6% |
| High Voltage Cables Market Size 2032 | USD 31.18 Billion |
The High Voltage Cables Market grows with rising electricity demand, renewable energy integration, and large-scale infrastructure expansion. Governments invest in advanced transmission networks to ensure reliable power delivery and reduce grid losses.
The High Voltage Cables Market demonstrates strong geographical diversity, shaped by infrastructure maturity, energy transition policies, and regional demand for reliable power transmission. North America advances with large-scale grid modernization and offshore wind projects in the United States and Canada, while Europe leads in submarine installations and cross-border interconnections to support its renewable energy transition. Asia-Pacific shows rapid growth driven by China’s ultra-high-voltage projects, India’s rural electrification, and Japan’s offshore wind expansion. Latin America steadily adopts high-voltage cables through hydropower and industrial development in Brazil, Mexico, and Chile. The Middle East and Africa emphasize new installations for smart city projects, energy parks, and rural electrification, supported by international collaborations. Key players such as Nexans, Furukawa Electric, LS Cable & System, and Mitsubishi Electric strengthen their presence with advanced cable technologies, global supply networks, and partnerships that address regional power needs while aligning with long-term sustainability goals.
Market Insights
- The High Voltage Cables Market was valued at USD 19.57 billion in 2024 and is projected to reach USD 31.18 billion by 2032, expanding at a CAGR of 6%.
- Rising electricity demand from industrialization, urbanization, and data center expansion drives the adoption of advanced high-voltage transmission systems.
- Increasing deployment of submarine and underground cables for offshore wind, smart cities, and interconnections reflects a clear trend toward modern and efficient solutions.
- Competitive landscape is shaped by key players such as Nexans, LS Cable & System, Mitsubishi Electric, and Furukawa Electric, focusing on advanced insulation technologies, global expansion, and renewable energy projects.
- High installation costs, raw material price fluctuations, and complex regulatory processes act as restraints that limit rapid adoption in some developing regions.
- North America shows strong growth through grid modernization and renewable integration, Europe emphasizes offshore wind and cross-border links, while Asia-Pacific emerges as the fastest-growing region with ultra-high-voltage projects in China and large-scale electrification in India.
- Latin America expands steadily with hydropower and industrial development, while the Middle East and Africa advance through new installations in smart city projects, renewable parks, and rural electrification programs.
Market Drivers
Rising Electricity Demand and Expanding Transmission Networks
The High Voltage Cables Market is driven by global growth in electricity consumption across industrial, commercial, and residential sectors. Expanding urbanization and industrialization require stronger transmission networks to ensure reliable power delivery. It supports large-scale integration of renewable energy sources into national grids. Governments invest in high-capacity transmission lines to reduce outages and enhance efficiency. Data centers, electric mobility, and urban infrastructure projects further increase demand for high-voltage connections. Growing reliance on uninterrupted energy supply reinforces the need for advanced cable systems worldwide.
- For instance, in July 2025, LS Cable & System completed its fifth submarine cable plant in Donghae City, South Korea, quadrupling its high-voltage direct current (HVDC) cable production capacity to supply projects, including those requiring 525 kV transmission capability.
Government Support for Renewable Energy Integration
The High Voltage Cables Market benefits from policy-driven initiatives that promote renewable energy deployment. Offshore wind, solar farms, and hydropower projects require efficient high-voltage connections to transport electricity to consumption centers. It ensures stable integration of intermittent energy sources with existing grids. Governments in Europe, Asia, and North America provide funding and regulations that accelerate deployment of high-voltage cables in renewable projects. Large interconnection projects across regions also depend on reliable cable systems. This policy support strengthens long-term growth opportunities for the market.
- For instance, Nexans secured a framework agreement with RTE to supply 450 km of HVDC subsea cables and 280 km of HVDC onshore cables to connect the Centre Manche 1, Centre Manche 2, and Oléron offshore wind farms to the French national grid, integrating a combined capacity of several gigawatts.
Technological Advancements Enhancing Performance and Safety
The High Voltage Cables Market experiences strong momentum from innovations in insulation, materials, and monitoring systems. Advanced cross-linked polyethylene (XLPE) cables improve performance, reduce losses, and extend service life. It enables safer and more efficient power transmission across long distances. Real-time monitoring technologies enhance grid resilience by identifying faults before failures occur. Submarine high-voltage cables expand applications in offshore wind and inter-island connections. These advancements position high-voltage cables as critical infrastructure in modern power systems.
Urbanization, Infrastructure Development, and Cross-Border Interconnections
The High Voltage Cables Market grows with large infrastructure projects, industrial expansion, and cross-border energy trade. Expanding metro systems, airports, and industrial hubs require dependable cable networks. It ensures reliable energy supply for construction, operations, and smart city development. Cross-border interconnection projects in Europe, Asia, and Africa further increase the demand for advanced cable systems. Investments in rural electrification also create opportunities in developing regions. These factors highlight the critical role of high-voltage cables in supporting economic growth and energy security.
Market Trends
Growing Deployment of Submarine and Underground Cable Systems
The High Voltage Cables Market is shaped by rising demand for submarine and underground cable installations. Offshore wind projects, inter-island connections, and undersea interconnectors require high-capacity cables to transmit electricity efficiently. It supports cross-border energy trade and renewable energy integration. Underground systems gain traction in urban areas due to space limitations and the need for safer, aesthetically integrated networks. These trends highlight a shift away from overhead lines toward advanced cable technologies. Investments in offshore and underground projects will continue to strengthen market growth.
- For instance, Nexans was awarded a contract to supply 57 km of extra-high voltage underground cables to replace overhead lines crossing Switzerland's Saint-Gotthard Pass. The cables will be installed in the new second tube of the Saint-Gotthard Road Tunnel, with work starting in 2028 and finishing by 2030, enabling secure power transmission across the Alps.
Adoption of Advanced Insulation Materials and Smart Monitoring Systems
The High Voltage Cables Market benefits from growing use of advanced insulation materials such as cross-linked polyethylene (XLPE). These cables reduce transmission losses, extend lifespan, and improve reliability under high stress. It also sees rising integration of smart monitoring systems that track performance, detect faults, and ensure preventive maintenance. Digital solutions provide real-time data for utilities to optimize energy transmission. The combination of advanced insulation and intelligent monitoring improves both safety and efficiency. This trend ensures steady adoption of modern cable technologies across regions.
- For instance, LS Cable & System commercialized a 525 kV HVDC XLPE-insulated cable with an operating conductor temperature raised to 90 °C, supporting stable long-distance transmission in Korea’s East Coast–Metropolitan Area network.
Rising Demand from Renewable Energy Projects
The High Voltage Cables Market reflects strong demand from expanding renewable energy capacity worldwide. Wind farms, solar parks, and hydropower projects require high-voltage cables to transmit electricity to urban and industrial load centers. It supports stable grid integration of variable renewable sources. Offshore wind expansion in Europe and Asia particularly drives demand for submarine cable networks. Large-scale renewable targets set by governments ensure long-term opportunities. This alignment with global energy transition strengthens cable market expansion.
Expansion of Cross-Border Interconnection Projects
The High Voltage Cables Market is influenced by increasing investments in cross-border transmission infrastructure. Interconnection projects across Europe, the Middle East, and Asia improve grid stability and enable efficient energy trade. It enhances supply security by connecting regions with surplus power to areas with higher demand. Governments and utilities prioritize long-distance transmission lines to strengthen regional cooperation. Large-scale interconnectors require advanced cable technologies that ensure minimal losses over vast distances. This trend underlines the market’s strategic role in global energy integration.
Market Challenges Analysis
High Installation Costs and Complex Project Execution
The High Voltage Cables Market faces challenges from significant upfront costs and complex deployment processes. Submarine and underground installations require specialized equipment, skilled labor, and lengthy approval procedures. It increases project timelines and creates financial barriers for utilities and governments in cost-sensitive regions. Harsh environmental conditions, including deep-sea and mountainous terrains, add to technical difficulties. Maintenance of such systems also demands advanced monitoring tools and expertise, further elevating operational costs. These financial and logistical challenges limit rapid adoption in some developing markets.
Supply Chain Constraints and Raw Material Price Volatility
The High Voltage Cables Market is also challenged by supply chain disruptions and fluctuating raw material prices. Copper, aluminum, and insulation materials are critical inputs that face global shortages and price instability. It impacts production schedules and reduces profit margins for manufacturers. Limited availability of specialized components, such as XLPE insulation and submarine cable sheathing, creates additional hurdles. Political uncertainties and trade restrictions also affect timely procurement of materials. These risks strain project execution and delay large-scale cable installations worldwide.
Market Opportunities
Rising Investments in Renewable Energy and Offshore Wind Projects
The High Voltage Cables Market presents strong opportunities through expanding renewable energy installations, particularly offshore wind and large-scale solar projects. Governments worldwide set ambitious clean energy targets that require extensive transmission infrastructure. It enables stable grid integration of variable renewable sources by carrying high-capacity electricity over long distances. Offshore wind development in Europe, China, and the United States fuels significant demand for submarine cables. Solar power expansion in Asia and the Middle East also contributes to steady growth. These investments create long-term opportunities for cable manufacturers and utility providers.
Expansion of Smart Infrastructure and Cross-Border Interconnections
The High Voltage Cables Market benefits from rapid infrastructure modernization and cross-border energy trade. Smart cities, industrial zones, and transport corridors demand reliable high-voltage transmission systems. It supports digital infrastructure growth, electrification of transport, and modernization of aging grids. Cross-border projects in Europe, Asia, and Africa drive demand for advanced cable networks that ensure stable interconnection between nations. Rising collaboration between governments and private players accelerates project execution. These developments highlight the strategic role of high-voltage cables in strengthening energy security and enabling global power exchange.
Market Segmentation Analysis:
By Voltage
The High Voltage Cables Market, by voltage, is divided into 72.5 kV–220 kV, 220 kV–440 kV, and above 440 kV. The 72.5 kV–220 kV segment dominates due to its wide use in urban distribution and regional power transmission. It ensures efficient supply for industrial clusters, residential zones, and infrastructure projects. The 220 kV–440 kV category gains strong demand from long-distance interconnections and renewable energy integration. Above 440 kV cables, though less common, are critical for ultra-high-voltage projects and international interconnectors. Expansion of large-scale power corridors continues to boost demand across all voltage ranges.
- For instance, Furukawa Electric supplied the 275 kV underground XLPE cable system for the Chiba-Katsunan Line in Japan, extending over 30.4 km to reinforce power transmission reliability for the metropolitan Tokyo area. The installation was completed in December 2013, with the system beginning operation in March 2014.
By Current
The High Voltage Cables Market, by current, includes alternating current (AC) and direct current (DC) systems. AC high-voltage cables hold a major share due to their wide deployment in traditional grid networks. It supports cost-effective power transmission across short and medium distances. DC high-voltage cables gain traction for long-distance and submarine applications where efficiency and lower losses are crucial. The shift toward renewable integration and intercontinental connections drives higher demand for HVDC technology. Utilities increasingly invest in hybrid systems to balance reliability and efficiency.
- For instance, Mitsubishi Electric signed an MoU with GE Vernova to supply insulated-gate bipolar transistors (IGBTs) for its voltage source converter (VSC) HVDC systems, supporting the expansion of renewable energy transmission and enhancing overall grid efficiency.
By Installation
The High Voltage Cables Market, by installation, covers overhead, underground, and submarine systems. Overhead cables remain dominant due to their cost-effectiveness and ease of deployment across large distances. It continues to be the preferred option for rural electrification and grid expansion in developing regions. Underground installations are expanding in urban areas where land scarcity and safety concerns require compact solutions. Submarine installations record strong growth from offshore wind projects and cross-border interconnection projects. Rising investments in smart infrastructure and renewable energy strengthen opportunities across all installation categories.
Segments:
Based on Voltage
- 110 kV
- 110 kV - 220 kV
- > 220 kV
Based on Current
- HVAC
- HVDC
Based on Installation
- Overhead
- Submarine
- Underground
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the High Voltage Cables Market, accounting for nearly 32% in 2024. The region benefits from robust investments in renewable energy integration, modernization of existing grid infrastructure, and cross-border interconnection projects. The United States leads demand with offshore wind development, urban grid upgrades, and large-scale transmission projects linking renewable plants to major consumption centers. Canada contributes steadily with rural electrification initiatives, hydroelectric projects, and submarine cable installations for regional connectivity. Mexico supports growth with rising investments in industrial zones and renewable integration under government-backed reforms. It reflects a mature ecosystem with strong regulatory frameworks, advanced technologies, and consistent funding for power infrastructure expansion.
Europe
Europe represents about 29% of the High Voltage Cables Market in 2024, supported by its strong renewable energy transition and interconnection policies. Germany, France, and the United Kingdom drive regional growth with large offshore wind farms requiring advanced submarine cables. The European Union prioritizes cross-border projects that ensure energy security, reduce carbon emissions, and balance regional electricity supply. It also promotes underground installations in urban areas where land scarcity and environmental concerns are high. Scandinavian countries lead in deploying HVDC cables for long-distance renewable integration, while Southern and Eastern Europe expand gradually with modernization of aging grids. Policy support, green funding, and regional cooperation ensure sustained demand for high-voltage cable systems.
Asia-Pacific
Asia-Pacific accounts for nearly 26% of the High Voltage Cables Market in 2024, making it the fastest-growing region. China dominates with massive investments in ultra-high-voltage projects that connect remote renewable generation centers with urban demand hubs. Japan and South Korea deploy submarine cables for offshore wind farms and urban underground systems for safety and reliability. India accelerates demand through rural electrification, smart grid initiatives, and rapid industrialization. Southeast Asian nations including Vietnam, Indonesia, and Thailand expand infrastructure with renewable integration and urban development projects. It reflects a dynamic market driven by rapid economic growth, rising electricity demand, and government-backed digital infrastructure investments.
Latin America
Latin America holds around 8% of the High Voltage Cables Market in 2024, supported by gradual but steady expansion. Brazil leads regional demand with hydropower connections, urban grid modernization, and offshore renewable projects. Mexico shows strong adoption with infrastructure reforms and industrial development requiring efficient transmission systems. Chile, Argentina, and Colombia also contribute with renewable integration and urban power upgrades. It faces challenges of cost constraints and slower regulatory processes, but rising public-private partnerships improve growth prospects. Expanding energy access and renewable initiatives create promising opportunities for high-voltage cable adoption across the region.
Middle East and Africa
The Middle East and Africa together account for about 5% of the High Voltage Cables Market in 2024, reflecting steady yet emerging growth. The Middle East, led by Saudi Arabia, the United Arab Emirates, and Qatar, invests in smart city projects, large-scale industrial zones, and renewable energy parks requiring high-voltage connections. Submarine and underground cables gain traction in urban and coastal developments. Africa demonstrates growing opportunities with South Africa, Nigeria, and Egypt focusing on electrification projects and grid reliability improvements. It benefits from international funding and collaborations to expand transmission networks. Rising adoption of HVDC and modular systems highlights the region’s growing role in global energy connectivity.
Key Player Analysis
- Gupta Power
- Nexans
- Iljin Electric
- Jeddah Cables
- Furukawa Electric
- Brugg Kabel
- Mitsubishi Electric
- LS Cable & System
- Elsewedy Electric
- Ducab
Competitive Analysis
The competitive landscape of the High Voltage Cables Market is defined by leading players including Nexans, LS Cable & System, Mitsubishi Electric, Furukawa Electric, Ducab, Elsewedy Electric, Brugg Kabel, Iljin Electric, Jeddah Cables, and Gupta Power. These companies compete through strong portfolios of overhead, underground, and submarine cable solutions designed for high efficiency, safety, and long-distance transmission. They focus heavily on innovation in insulation materials such as XLPE, advanced sheathing, and smart monitoring systems to reduce losses and improve reliability. Strategic investments in offshore wind projects, renewable energy integration, and cross-border interconnection initiatives strengthen their market positions globally. Many of these players leverage joint ventures, government partnerships, and regional expansion strategies to capture opportunities in both developed and emerging economies. Cost optimization, quality assurance, and sustainability goals drive continuous product development, ensuring alignment with global energy transition targets. Intense competition among these manufacturers promotes technological advancement, large-scale deployment, and steady growth of the market.
Recent Developments
- In September 2025, LS Cable & System secured a contract from Taiwan worth 160 billion won to supply submarine cable systems.
- In July 2025, LS Cable & System completed its fifth submarine cable plant in Donghae City, Korea. This new facility quadrupled its production capacity for HVDC submarine cables.
- In April 2025, Nexans Won a contract with Interconnect Malta (ICM) to deliver a 220 kV HVAC subsea cable (225 MW) for the second Malta-Sicily interconnector.
- In March 2025, Nexans Secured a frame agreement with RTE to supply 450 km of HVDC subsea cables and 280 km of HVDC onshore cables for three offshore wind farms: Centre Manche 1 & 2 and Oléron.
Report Coverage
The research report offers an in-depth analysis based on Voltage, Current, Installation and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for submarine cables will grow with offshore wind and interconnection projects.
- Advanced insulation technologies will improve efficiency and extend cable lifespan.
- Grid modernization will create strong opportunities for underground high-voltage systems.
- Cross-border interconnections will expand to strengthen regional energy trade.
- Renewable energy targets will drive continuous investment in high-voltage cable networks.
- Digital monitoring and IoT-enabled systems will enhance fault detection and maintenance.
- Urbanization will increase demand for compact underground installations.
- HVDC projects will gain prominence for long-distance and intercontinental transmission.
- Emerging economies will adopt new cable networks to support electrification and industrialization.
- Sustainability initiatives will encourage eco-friendly materials and energy-efficient designs in cable production.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Grid Modernization and Expansion
Ongoing upgrades to aging grid infrastructure and the expansion of transmission networks to meet growing urbanization and industrialization are driving demand for high voltage cables, especially in developed regions and rapidly growing economies.
Renewable Energy Integration
The global shift toward renewable energy sources such as offshore wind, solar, and hydropower requires advanced high voltage cables for efficient transmission from generation sites to consumption centers, supported by strong government policies and funding.
Growth in Submarine and Underground Installations
Rising deployment of submarine and underground cables for offshore wind farms, inter-island connections, and urban grid projects is fueling market growth, as these solutions offer reliability, safety, and support for cross-border energy trade.
Technological Advancements in Cable Materials and Monitoring
Innovations in insulation materials like XLPE and the adoption of smart monitoring systems are enhancing cable performance, reducing losses, and extending service life, making high voltage cables more attractive for modern power systems.
Cross-Border Interconnection Projects
Increasing investments in cross-border transmission infrastructure, particularly in Europe, Asia, and Africa, are boosting demand for high voltage cables to enable efficient regional energy trade and improve grid stability.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for High Voltage Cables, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the High Voltage Cables market projected to grow between 2025 and 2032?
Which High Voltage Cables market segment held the largest share in 2024?
What are the primary factors fueling the growth of the High Voltage Cables market?
Who are the leading companies in the High Voltage Cables market?
Which region commanded the largest share of the High Voltage Cables market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Current
- 1.2.1 HVAC
- 1.2.2 HVDC
- 1.3 By Voltage
- 1.3.1 110 kV
- 1.3.2 110 kV - 220 kV
- 1.3.3 > 220 kV
- 1.4 By Installation
- 1.4.1 Overhead
- 1.4.2 Submarine
- 1.4.3 Underground
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 19.57 billion → 2032: USD 31.18 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global High Voltage Cables Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global High Voltage Cables Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global High Voltage Cables Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global High Voltage Cables Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global High Voltage Cables Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global High Voltage Cables Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global High Voltage Cables Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global High Voltage Cables Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 19.57 billion → 2032: USD 31.18 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global High Voltage Cables Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Current - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 HVAC
- 12.3.7.2 HVDC
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Voltage - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 110 kV
- 12.4.7.2 110 kV - 220 kV
- 12.4.7.3 > 220 kV
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Installation - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Overhead
- 12.5.7.2 Submarine
- 12.5.7.3 Underground
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global High Voltage Cables Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global High Voltage Cables Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global High Voltage Cables Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Nexans
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 LS Cable & System
- 17.4 Mitsubishi Electric
- 17.5 Furukawa Electric
- 17.6 Ducab
- 17.7 Elsewedy Electric
- 17.8 Brugg Kabel
- 17.9 Iljin Electric
- 17.10 Jeddah Cables
- 17.11 Gupta Power
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

