
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Higher Education Market Size 2024 | USD 748,290 million |
| Higher Education Market, CAGR | 12.57% |
| Higher Education Market Size 2032 | USD 1,929,529 million |
Market Overview:
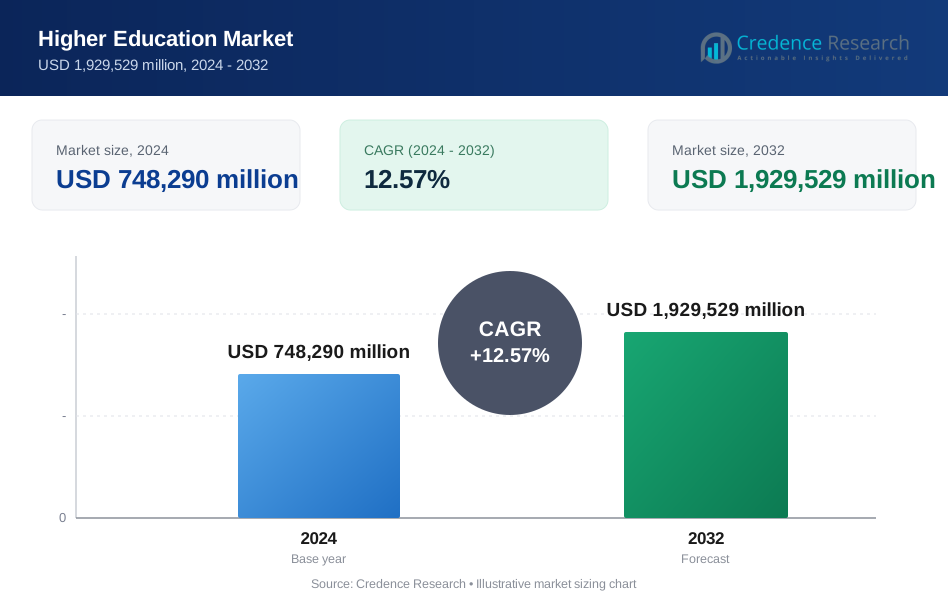
The Global Higher Education Market is projected to grow from USD 748,290 million in 2024 to USD 1,929,529 million by 2032, with a compound annual growth rate (CAGR) of 12.57%.
The higher education market is driven by several key factors, including the increasing demand for skilled professionals in a rapidly evolving global economy and the growing adoption of digital learning technologies. The rise of online and distance learning platforms, accelerated by the COVID-19 pandemic, has significantly expanded access to education, particularly in developing regions. Additionally, government initiatives supporting higher education reforms, coupled with rising investments from private institutions, contribute to market growth. Trends such as personalized learning, competency-based education, and the integration of artificial intelligence (AI) and data analytics into curriculum design are reshaping the education landscape. The growing emphasis on interdisciplinary studies and industry-academia collaborations to enhance employability further fuels market expansion. As institutions strive to meet the evolving needs of students and the labor market, the higher education sector is poised for significant growth in the coming years.
The higher education market is experiencing significant growth across various regions, with North America holding the largest share, driven by institutions such as Stanford University, MIT, and Harvard College. Europe, particularly countries like the UK and Germany, also plays a key role, with top players like Imperial College London and the University of Oxford leading the way. In the Asia-Pacific region, Tsinghua University and Peking University are prominent, reflecting the rising demand for quality education in countries like China and India. The Latin American market is growing, with institutions like the University of Cape Town in South Africa emerging as key players. In the Middle East and Africa, governments are investing in educational reform, with universities such as the University of Cape Town contributing to the region’s expanding higher education market.
Market Insights:
- The global higher education market is projected to grow from USD 748,290 million in 2024 to USD 1,929,529 million by 2032, with a CAGR of 12.57%.
- Increasing demand for skilled professionals across industries is a primary market driver, fueling higher enrollment in educational programs.
- Technological advancements, including online learning platforms and AI integration, are reshaping how education is delivered and accessed worldwide.
- Government initiatives and funding are vital in supporting higher education reforms and infrastructure improvements, contributing to market expansion.
- Industry-academia collaborations are becoming more popular, ensuring students acquire relevant skills aligned with current job market demands.
- North America holds the largest market share (40% in 2024), with leading institutions like MIT, Stanford, and Harvard driving growth.
- The Asia-Pacific region is experiencing rapid market expansion, accounting for 20% of the market share in 2024, fueled by rising demand in countries like China and India.
Market Drivers:
Increasing Demand for Skilled Professionals:
One of the primary drivers of the higher education market is the growing demand for skilled professionals in various industries. STEM (science, technology, engineering, and mathematics) programs in universities such as MIT and Stanford have seen a surge in enrollment as industries seek graduates with advanced technical and analytical skills. As economies become more knowledge-based, the need for a highly educated workforce is essential to remain competitive in global markets. Employers are seeking individuals with advanced technical, analytical, and leadership skills, leading to increased enrollment in higher education institutions. As a result, universities and colleges are expanding their program offerings to meet the diverse needs of students and the evolving labor market.
Technological Advancements in Education:
The integration of technology into education has significantly transformed the higher education market. For instance, platforms like Coursera and edX enable universities to offer online degrees and certifications, making education accessible to students around the globe. The rise of online learning platforms, digital classrooms, and e-learning tools has made education more accessible and flexible, allowing students to pursue degrees from anywhere in the world. These advancements have not only widened access to education but also improved student engagement and learning outcomes. Institutions are increasingly adopting innovative technologies such as artificial intelligence, virtual reality, and data analytics to enhance the quality of education and tailor learning experiences to individual needs.
Government Initiatives and Funding:
Government initiatives and increased funding for higher education are also key market drivers. For instance, Germany’s “Excellence Initiative” provides substantial funding to support cutting-edge research and improve the quality of higher education institutions nationwide. Many governments worldwide recognize the importance of higher education for economic growth and social development. As a result, they are implementing policies to improve access to education, enhance the quality of programs, and encourage research and innovation. Scholarships, student loans, and funding for research and development are some of the measures taken to support higher education institutions, further boosting market growth.
Growing Popularity of Industry-Academia Collaborations:
Industry-academia collaborations have gained traction as companies partner with educational institutions to develop programs that align with industry needs. IBM collaborates with universities through its Skills Academy to provide specialized courses and hands-on training in emerging technologies like artificial intelligence and blockchain. These collaborations help bridge the skills gap, ensuring that graduates are well-prepared for the workforce. By working closely with industries, higher education institutions can offer specialized courses, internships, and research opportunities, enhancing students' employability and driving market growth.
Market Trends:
Rise of Online and Blended Learning:
A significant trend in the higher education market is the rise of online and blended learning models. For example, Southern New Hampshire University offers hybrid programs that combine on-campus classes with flexible online learning options, catering to working professionals and remote students. The global shift to remote education during the COVID-19 pandemic accelerated the adoption of online platforms, which continue to thrive due to their flexibility and accessibility. Institutions are increasingly offering hybrid programs that combine traditional in-person instruction with online learning, catering to the needs of students seeking flexible education solutions. This trend has broadened access to higher education, particularly for working professionals and students in remote locations.
Integration of Artificial Intelligence and Data Analytics:
The integration of artificial intelligence (AI) and data analytics into higher education is transforming the way institutions design and deliver educational content. For instance, platforms like Carnegie Learning use AI algorithms to adapt lessons based on individual student performance, offering a personalized learning experience. AI-powered tools are being used to personalize learning experiences, assess student performance, and provide real-time feedback. Data analytics allows institutions to analyze student behaviors and learning patterns, enabling them to improve retention rates and optimize curriculum development. These technologies also support administrative functions, enhancing the overall efficiency of educational institutions.
Focus on Interdisciplinary Studies:
Interdisciplinary studies are gaining popularity as higher education institutions recognize the value of offering programs that combine different fields of study. Arizona State University’s interdisciplinary studies program allows students to integrate subjects such as business, social sciences, and technology to develop diverse skill sets. Students are increasingly seeking programs that provide a broader skill set, allowing them to tackle complex, real-world problems. Institutions are responding by creating flexible curricula that integrate multiple disciplines such as technology, business, and social sciences, enabling students to develop a more holistic understanding of their chosen fields.
Emphasis on Lifelong Learning:
The concept of lifelong learning is becoming more prominent in the higher education landscape. Harvard Extension School offers professional development programs and certifications tailored for individuals aiming to upskill and stay competitive in their careers. As industries evolve rapidly, professionals are seeking continuous education to upskill and remain competitive in their careers. Universities and colleges are expanding their offerings to include short-term certifications, professional development programs, and executive education, supporting individuals in achieving ongoing career advancement.
Market Challenges Analysis:
Rising Costs of Higher Education:
One of the foremost challenges in the higher education market is the rising cost of education, which continues to outpace inflation in many parts of the world. The costs associated with tuition, accommodation, textbooks, and other educational materials have escalated, making it increasingly difficult for students and their families to afford quality education. In many developed countries, student loan debt has reached critical levels, burdening graduates with financial obligations that persist long after they have completed their studies. This financial pressure has led to increased scrutiny of the return on investment in higher education, with students and parents questioning whether the high costs of attending universities and colleges are justified by future earning potential. Additionally, government funding for public institutions has decreased in certain regions, forcing universities to raise tuition fees or cut services to maintain operations. Addressing the rising costs of education is essential to ensure that higher education remains accessible and that students are not deterred by financial barriers.
Disparities in Access and Technological Inequities:
Despite advancements in technology that have made online education more prevalent, significant disparities in access persist, particularly in developing countries and underserved communities. Many students still lack reliable internet access, digital devices, and adequate infrastructure to fully engage in online or blended learning environments. The digital divide is stark, with students from lower socioeconomic backgrounds disproportionately affected, limiting their opportunities for academic success. For example, immersive learning technologies like virtual reality (VR) and augmented reality (AR), which allow students to engage with interactive environments such as exploring anatomical structures or historical sites, require significant investment in hardware and training. Even in regions with better technological access, educational institutions often face challenges in integrating advanced technologies into their teaching and administrative processes due to resource constraints. Additionally, the rapid pace of technological change may overwhelm institutions unprepared for continual upgrades and staff training. These disparities not only hinder equal access to education but also widen the gap in educational outcomes. Addressing technological inequities requires coordinated efforts from governments, institutions, and private sector partners to ensure that all students, regardless of their background, have the tools and resources necessary to thrive in modern learning environments.
Market Opportunities:
The higher education market presents substantial opportunities for growth, particularly through the continued expansion of online and hybrid learning models. The increasing demand for flexible and accessible education options, driven by working professionals and non-traditional students, creates significant potential for institutions to reach new audiences. By offering a combination of online courses, micro-credentials, and specialized certification programs, universities and colleges can attract learners seeking to upskill or reskill in response to the rapidly changing job market. Additionally, the rise of digital education platforms enables institutions to collaborate globally, providing cross-border educational opportunities and enhancing their global footprint. This growing demand for lifelong learning and professional development presents an avenue for sustained market growth.
Furthermore, emerging markets in developing regions offer significant opportunities for expansion. As governments in these areas prioritize higher education reform and invest in educational infrastructure, institutions have the chance to tap into new student populations. Developing economies, particularly in Asia and Africa, are seeing increasing numbers of students pursuing higher education, creating a burgeoning demand for quality institutions and programs. By partnering with local governments and private sector entities, higher education institutions can establish campuses, provide online courses, or offer dual-degree programs in these regions. These efforts not only help close the education gap but also contribute to global economic development, positioning higher education as a catalyst for social and economic progress.
Market Segmentation Analysis:
By Course
The higher education market is segmented by course into undergraduate, postgraduate, and doctoral programs. Undergraduate courses account for the largest share due to the broad demand for foundational education across various fields. Postgraduate and doctoral programs are growing in popularity, driven by the increasing need for specialized expertise in competitive job markets.
By Institution Type
The market is also segmented by institution type into public and private institutions. Public institutions dominate the market due to government funding and their accessibility to a broader range of students. However, private institutions are witnessing growth, particularly in developed regions, as they offer specialized programs, smaller class sizes, and industry-aligned curricula.
By Learning Mode
The learning mode segment includes traditional in-person learning, online learning, and blended learning models. While in-person learning remains the most common mode, online and blended learning are gaining momentum due to their flexibility, accessibility, and growing adoption of digital education platforms, making them attractive options for working professionals and distance learners.
Segments:
Based on Course:
- Undergraduate
- Master’s
- PhD
Based on Institution Type:
- Public Universities
- Private Universities
- Community Colleges
Based on Revenue Source:
- Tuition Fees
- Grants, Contracts, and Gifts
- Investment Returns
Based on Learning Mode:
- Online
- Offline
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the global higher education sector, accounting for 40% in 2024. The United States and Canada are the dominant players in this region, with renowned universities such as Harvard, MIT, and Stanford attracting students from all over the world. The region benefits from substantial government funding, advanced research capabilities, and a robust private education sector. Additionally, the growing adoption of online and hybrid learning models has further propelled market growth. The increasing demand for specialized programs and professional development courses also contributes to the region’s market leadership. Despite the strong competition in the market, North America's higher education institutions continue to lead in terms of innovation and academic excellence.
Europe
Europe follows closely behind North America, with a market share of 30% in 2024. The region is home to several prestigious universities, including the University of Oxford, the University of Cambridge, and ETH Zurich. The growing number of international students seeking higher education opportunities in Europe is a significant driver of the market. Moreover, many European countries, such as Germany and France, offer low-cost or even free education at public universities, making them attractive to students from across the globe. Additionally, the integration of digital learning solutions is increasing, with many institutions offering online programs to cater to non-traditional students. The European Union’s funding initiatives further promote the development of higher education institutions across the continent, fostering innovation and accessibility.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth in the higher education market, accounting for 20% of the market share in 2024. Countries such as China, India, Japan, and South Korea are leading the way in educational expansion. The growing middle class and the increasing emphasis on higher education in countries like China and India contribute to this growth. In addition, the rise of online education and foreign collaborations is helping educational institutions expand their reach. The demand for quality higher education continues to increase, driven by a large young population seeking opportunities for advanced learning. Furthermore, countries in the region are investing heavily in education infrastructure, which is expected to continue fueling growth in the sector.
Latin America
Latin America holds a smaller portion of the global higher education market, contributing 5% in 2024. However, the region is seeing a growing demand for quality higher education, particularly in countries like Brazil and Mexico. Rising middle-class income, government funding initiatives, and increased access to digital learning solutions are helping boost enrollment numbers. The expansion of online learning platforms and partnerships with international universities are contributing to the region’s growth. Although Latin America still faces challenges such as economic instability and limited access to education in some areas, the region’s higher education market is poised for gradual growth in the coming years.
Middle East & Africa
The Middle East and Africa account for 5% of the global higher education market in 2024. The region has been witnessing a gradual increase in demand for higher education, driven by economic development, population growth, and a push toward educational reform. Countries like the United Arab Emirates, Saudi Arabia, and South Africa are making significant investments in education, with initiatives aimed at attracting international students and improving domestic education standards. The adoption of online learning is also growing, though it remains limited in comparison to other regions. The market is expected to experience steady growth as governments continue to prioritize education and invest in modernizing their education systems.
Key Player Analysis:
- Stanford University
- Tsinghua University
- Columbia University
- University College London, UCL
- The University of Tokyo
- Massachusetts Institute of Technology
- The President and Fellows of Harvard College
- University of Cape Town
- The Trustees of Princeton University
- California Institute of Technology
- Imperial College London
- Peking University
Competitive Analysis:
The higher education market is highly competitive, with leading players such as Stanford University, Massachusetts Institute of Technology, Columbia University, California Institute of Technology, Imperial College London, and The University of Tokyo dominating the sector. These institutions are known for their academic excellence, research capabilities, and strong global reputations. They invest heavily in infrastructure, technology, and faculty development to maintain their competitive edge. Moreover, these universities are expanding their reach through digital platforms and online programs, allowing them to cater to a global audience. MIT's OpenCourseWare platform offers free access to lecture materials and courses, making quality education accessible to learners worldwide. While prestigious universities such as Harvard College, Peking University, and Princeton University continue to lead in attracting international students, the growing demand for specialized and flexible learning models has opened opportunities for new players to enter the market. As competition intensifies, these institutions are increasingly focusing on partnerships, industry collaborations, and innovation in education delivery methods to stay ahead in a rapidly evolving higher education landscape.
Recent Developments:
- In October 2023, Columbia University’s Institute of Global Politics (IGP) will commence. This initiative offers policymakers and political leaders the opportunity to develop new political solutions while training future generations of leaders.
- In Jane 2024, OpenAI will unveil ChatGPT Edu, an innovative AI tool designed to enhance institutions' capabilities in areas such as document summarization, data analysis, and code assistance. This tool aims to provide students with a dynamic and superior learning experience
Market Concetration & Characteristics:
The higher education market is characterized by moderate concentration, with a few prestigious institutions dominating the global landscape. Renowned universities such as Stanford University, MIT, Harvard, and Oxford continue to lead in terms of academic reputation, research output, and enrollment numbers. However, the market also includes a vast number of regional and smaller institutions that cater to specific student populations, offering a diverse range of programs and courses. This diversity is further amplified by the increasing presence of online education platforms, which have enabled both traditional and non-traditional institutions to reach a global audience. Market characteristics also include growing competition among institutions to attract international students and offer industry-aligned curricula. Additionally, there is a rising trend of partnerships and collaborations between educational institutions and private sectors to enhance employability outcomes and bridge skills gaps. The market continues to evolve with technological advancements and global demands for skilled professionals.
Report Coverage:
The research report offers an in-depth analysis based on Course, Institution Type, Revenue Source, Learning Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The global higher education market is expected to continue growing, driven by the increasing demand for skilled professionals in various industries.
- Online and hybrid learning models will remain a significant trend, expanding access to education for non-traditional students.
- The integration of artificial intelligence and data analytics into curricula will personalize learning experiences and improve educational outcomes.
- The rising importance of industry-academia collaborations will ensure that graduates possess relevant skills for the job market.
- Government funding and initiatives to improve education quality and accessibility will contribute to market expansion, especially in developing regions.
- Regional markets in Asia-Pacific, particularly China and India, will see significant growth due to increasing student populations and expanding middle classes.
- Technological advancements such as virtual reality and AI will further transform education delivery and student engagement.
- Institutions will increasingly adopt competency-based education models to address the evolving needs of students and employers.
- There will be a stronger emphasis on lifelong learning as individuals seek continuous upskilling opportunities throughout their careers.
- The rising costs of education will continue to drive demand for affordable, flexible learning options, including online degrees and certifications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Education
The integration of digital learning platforms, artificial intelligence, and data analytics is transforming how higher education is delivered, making it more accessible and personalized. These technologies enable institutions to reach a global audience and improve student engagement and outcomes.
Government Initiatives and Funding
Increased government support for higher education reforms, scholarships, and research funding is expanding access and improving the quality of institutions, particularly in developing regions. Such initiatives help drive enrollment and support infrastructure development.
Industry-Academia Collaborations
Partnerships between universities and industry players are aligning curricula with labor market needs, ensuring graduates possess relevant, in-demand skills. These collaborations enhance employability and attract students seeking practical, career-oriented education.
Rising Demand for Lifelong and Flexible Learning
The need for continuous upskilling and reskilling in a rapidly changing job market is fueling demand for flexible learning options, such as online degrees, micro-credentials, and professional development programs. This trend is expanding the market beyond traditional student populations.
Globalization and International Student Mobility
The increasing movement of students across borders, driven by the pursuit of quality education and global career opportunities, is boosting enrollment in leading institutions worldwide. This trend is particularly strong in regions offering prestigious programs and international partnerships.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Higher Education Market?
What factors are driving the growth of the Higher Education Market?
What are some challenges faced by the Higher Education Market?
Who are the major players in the Higher Education Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Course
- 1.2.1 Undergraduate
- 1.2.2 Master’s
- 1.2.3 PhD
- 1.3 By Learning Mode
- 1.3.1 Online
- 1.3.2 Offline
- 1.3.3 Blended
- 1.4 By Revenue Source
- 1.4.1 Tuition Fees
- 1.4.2 Grants, Contracts, and Gifts
- 1.4.3 Investment Returns
- 1.5 By Institution Type
- 1.5.1 Public Universities
- 1.5.2 Private Universities
- 1.5.3 Community Colleges
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 748,290 million → 2032: USD 1,929,529 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Higher Education Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Higher Education Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Higher Education Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Higher Education Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Higher Education Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Higher Education Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Higher Education Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Higher Education Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 748,290 million → 2032: USD 1,929,529 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Higher Education Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Course - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Undergraduate
- 12.3.7.2 Master’s
- 12.3.7.3 PhD
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Learning Mode - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Online
- 12.4.7.2 Offline
- 12.4.7.3 Blended
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Revenue Source - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Tuition Fees
- 12.5.7.2 Grants, Contracts, and Gifts
- 12.5.7.3 Investment Returns
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Institution Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Public Universities
- 12.6.7.2 Private Universities
- 12.6.7.3 Community Colleges
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Higher Education Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Higher Education Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Higher Education Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Stanford University
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Massachusetts Institute of Technology (MIT)
- 17.4 Harvard College
- 17.5 Tsinghua University
- 17.6 Imperial College London
- 17.7 University of Oxford
- 17.8 Peking University
- 17.9 University of Cape Town
- 17.10 Columbia University
- 17.11 California Institute of Technology
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

