
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hot Dip Galvanized Steel Pipe MarketSize 2024 | USD 12,523 Million |
| Hot Dip Galvanized Steel Pipe Market, CAGR | 5.8% |
| Hot Dip Galvanized Steel Pipe Market Size 2032 | USD 19,660.46 Million |
Market Overview
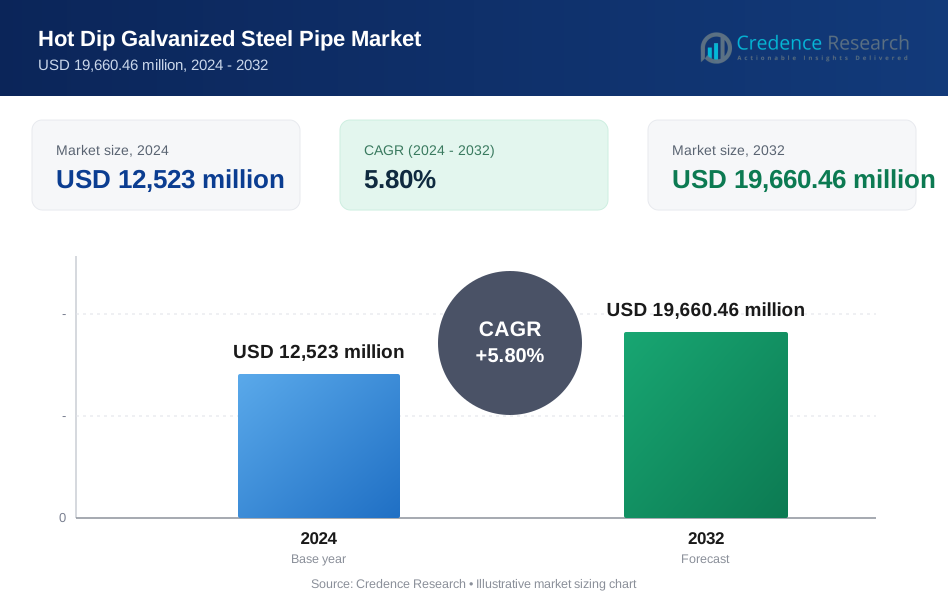
The Hot Dip Galvanized Steel Pipe Market is projected to grow from USD 12,523 million in 2024 to USD 19,660.46 million by 2032, registering a compound annual growth rate (CAGR) of 5.8% during the forecast period.
The Hot Dip Galvanized Steel Pipe Market is driven primarily by the increasing demand for durable and corrosion-resistant piping solutions across various industries such as construction, oil and gas, and water treatment. Growing infrastructure development, especially in emerging economies, fuels the need for reliable steel pipes that withstand harsh environmental conditions. Additionally, stringent government regulations on pipeline safety and environmental standards further propel market growth by encouraging the adoption of galvanized steel pipes. Technological advancements in galvanization processes have enhanced product quality and reduced production costs, making these pipes more accessible. Market trends indicate a rising preference for eco-friendly and sustainable materials, pushing manufacturers to innovate greener galvanizing techniques. The growing integration of automated production systems is improving efficiency and consistency in pipe manufacturing. Furthermore, the expansion of the oil and gas sector and increasing urbanization globally continue to stimulate demand, solidifying the market’s steady upward trajectory over the forecast period.
The Hot Dip Galvanized Steel Pipe Market spans key regions including North America, Asia-Pacific, and Europe, each contributing significantly to its global growth. Asia-Pacific leads with a 42% market share due to rapid industrialization and infrastructure development, followed by North America at 28%, driven by advanced manufacturing and strict regulations. Europe holds 20%, supported by sustainable construction and refurbishment projects. Leading players in the market include Zhejiang Kingland & Pipeline Technologies Co., Ltd., AK Steel, Hunan Prime Steel Pipe, SHINESTAR STEEL GROUP CO. LTD, Youfa Steel Pipe Group, Hebei Tianchuang Pipe Co. Ltd., and Octal. These companies focus on innovation, capacity expansion, and regional presence to capture market opportunities and address diverse industry demands across these prominent regions. Their strategic investments and technological advancements position them as key contributors to the market’s competitive landscape.
Market Insights
- The Hot Dip Galvanized Steel Pipe Market is expected to grow from USD 12,523 million in 2024 to USD 19,660.46 million by 2032, with a CAGR of 5.8%.
- Increasing demand for corrosion-resistant and durable pipes across construction, oil and gas, and water treatment sectors drives market growth.
- Rapid infrastructure development, particularly in emerging economies, boosts the need for reliable steel piping solutions that endure harsh conditions.
- Stringent government regulations on pipeline safety and environmental protection encourage the adoption of galvanized steel pipes.
- Technological advancements improve coating quality, reduce production costs, and support wider industry adoption.
- The oil and gas sector’s expansion and growing urbanization globally continue to stimulate demand, strengthening market momentum.
- Asia-Pacific leads with a 42% market share due to rapid industrialization, followed by North America at 28% and Europe at 20%, supported by mature infrastructure and regulatory frameworks.
Market Drivers
Rising Infrastructure Development Boosts Demand
Rapid urbanization and expanding infrastructure projects worldwide drive significant demand for hot dip galvanized steel pipes. These pipes offer superior corrosion resistance and durability, making them ideal for construction and water supply applications. The increasing investment in residential, commercial, and industrial developments fuels the need for reliable piping solutions. Governments and private sectors prioritize long-lasting materials to reduce maintenance costs, directly benefiting the Hot Dip Galvanized Steel Pipe Market. It supports the development of robust pipelines for safe water transportation and efficient gas distribution.
For instance, Tata Steel supplied over 100,000 metric tons of hot dip galvanized pipes for India’s Smart Cities Mission, ensuring long-term durability in urban water supply networks (Tata Steel, 2023).
Stringent Safety and Environmental Regulations Encourage Adoption
Government regulations focusing on pipeline safety and environmental protection stimulate the adoption of galvanized steel pipes. Strict standards require materials that prevent corrosion and leakage, ensuring longer service life and minimal environmental impact. Companies comply by choosing hot dip galvanized steel pipes to meet these legal requirements. The Hot Dip Galvanized Steel Pipe Market benefits from regulations mandating the use of quality materials, pushing manufacturers to innovate and improve product performance to satisfy industry standards and certifications.
For instance, in India, the Bureau of Indian Standards (BIS) mandates that hot-dip galvanized steel sheets and strips must meet IS 18385 requirements, including parameters like coating weight and tensile strength, before receiving certification for use in construction and infrastructure projects.
Technological Advancements Enhance Product Quality
Innovations in galvanization processes improve coating uniformity and corrosion resistance, boosting the overall quality of hot dip galvanized steel pipes. Enhanced manufacturing techniques reduce production costs and increase efficiency, allowing manufacturers to offer competitive pricing. It enables wider adoption across sectors such as oil and gas, construction, and water management. The Hot Dip Galvanized Steel Pipe Market leverages these advancements to provide high-performance pipes that meet the evolving needs of customers, strengthening its position in global markets.
Growing Oil and Gas Sector Supports Market Expansion
Expansion in the oil and gas industry significantly propels demand for hot dip galvanized steel pipes, which are crucial for transporting crude oil, natural gas, and other fluids safely. The material’s resistance to harsh environmental conditions and chemical exposure ensures pipeline integrity. Exploration and production activities in emerging markets create new opportunities for it. The Hot Dip Galvanized Steel Pipe Market experiences growth from increasing pipeline infrastructure development and refurbishment projects across various regions.
Market Trends
Increasing Adoption of Eco-Friendly Galvanization Techniques
The Hot Dip Galvanized Steel Pipe Market is witnessing a shift toward environmentally sustainable galvanization processes. Manufacturers focus on reducing hazardous waste and minimizing energy consumption during production. This trend aligns with growing regulatory pressure and consumer demand for green manufacturing practices. It encourages the development of innovative coatings that maintain durability while lowering environmental impact. The move toward eco-friendly solutions strengthens the market’s long-term viability and aligns with global sustainability goals.
For instance, Henkel has introduced Bonderite Eco-Coat, a chromium-free metal surface treatment process that prevents corrosion while being more environmentally friendly than traditional methods..
Integration of Automation in Manufacturing Processes Automation technologies continue to transform the production of hot dip galvanized steel pipes by enhancing precision, efficiency, and consistency. It reduces human error and accelerates output, enabling manufacturers to meet increasing market demand. Automated inspection and quality control systems ensure higher product reliability and compliance with industry standards. The Hot Dip Galvanized Steel Pipe Market benefits from these advancements, which lower operational costs and improve overall supply chain responsiveness.
For instance, Tuspipe implemented automated production technology in its galvanized steel pipe manufacturing, increasing production efficiency by 30% to 50% and significantly reducing manual errors.
Rising Demand for Customized and Specialty Pipes
The market increasingly emphasizes customized pipe solutions tailored to specific industry requirements, including size, coating thickness, and corrosion resistance. This trend reflects growing customer preferences for pipes that address unique environmental and operational challenges. It drives manufacturers to innovate and offer flexible production capabilities. The Hot Dip Galvanized Steel Pipe Market responds by expanding its portfolio to include specialty pipes suitable for diverse applications such as marine, chemical, and industrial sectors.
Expansion into Emerging Regional Markets
Emerging economies in Asia-Pacific, Latin America, and Africa present significant growth opportunities for the Hot Dip Galvanized Steel Pipe Market. Increasing industrialization, infrastructure development, and urbanization in these regions fuel demand for durable steel piping. It supports critical sectors such as water management, construction, and energy. Market players invest in regional manufacturing facilities and distribution networks to capture this growth potential. The expansion into emerging markets sustains global market growth and diversification.
Market Challenges Analysis
Volatility in Raw Material Prices Impacts Profit Margins
The Hot Dip Galvanized Steel Pipe Market faces challenges from fluctuating prices of raw materials such as zinc and steel. Price volatility increases production costs, which manufacturers often find difficult to pass on to end-users due to competitive pricing pressures. It creates uncertainty in budgeting and financial planning, affecting profit margins and investment decisions. Manufacturers must adopt cost-control strategies and explore alternative sourcing to maintain profitability. This challenge requires continuous monitoring of global supply chains and market dynamics to mitigate risks effectively.
For instance, ArcelorMittal, one of the world’s largest steel producers, has adopted dynamic sourcing strategies and supply chain monitoring to manage the impact of steel price volatility on its galvanized product lines.
Corrosion and Quality Concerns in Harsh Environments
Despite its corrosion-resistant properties, hot dip galvanized steel pipes can experience degradation under extreme environmental conditions, including exposure to acidic or highly saline media. This limitation restricts its application in certain industrial sectors requiring specialized coatings or materials. It forces manufacturers to invest in research for improved protective layers and alternative materials. The Hot Dip Galvanized Steel Pipe Market must address these quality concerns to retain customer confidence and expand usage in demanding environments. Meeting stringent industry standards remains a critical challenge for market players.
Market Opportunities
Expansion of Infrastructure Projects in Emerging Economies
The Hot Dip Galvanized Steel Pipe Market holds significant growth potential driven by expanding infrastructure developments in emerging economies. Rapid urbanization and government investments in water supply, transportation, and energy projects increase demand for durable piping solutions. It creates opportunities for manufacturers to establish local production facilities and distribution networks to serve regional markets effectively. Growing industrialization in Asia-Pacific, Latin America, and Africa further supports market expansion. Companies that capitalize on these developments can strengthen their global presence and capture new revenue streams.
Technological Innovation and Product Diversification
Advancements in galvanization technology present promising opportunities for the Hot Dip Galvanized Steel Pipe Market. Enhancing coating performance and developing specialty pipes tailored to industry-specific needs allow manufacturers to differentiate their offerings. It opens new applications in sectors such as marine, chemical processing, and renewable energy, where corrosion resistance is critical. Investing in research and development to create high-quality, cost-effective solutions can drive customer adoption and market growth. Innovation also enables companies to comply with evolving environmental regulations, enhancing their competitive edge.
Market Segmentation Analysis:
By Application
The Hot Dip Galvanized Steel Pipe Market serves multiple applications, including construction, automotive, oil and gas, agriculture, telecommunications, and industrial infrastructure. Construction remains the largest segment due to the need for corrosion-resistant pipes in water supply and structural frameworks. The oil and gas sector demands pipes that withstand harsh environments and chemical exposure. Automotive and telecommunications industries require durable piping for manufacturing and signal transmission. Industrial infrastructure projects increase demand for reliable and long-lasting piping solutions. It supports growth across these sectors by providing tailored products suited to varying operational requirements.
For instance, in construction, companies like Tata Steel and Jindal Steel supply hot-dip galvanized pipes for structural frameworks and water supply networks in major infrastructure projects such as metro rail systems and high-rise buildings, where corrosion resistance is critical for long-term safety and durability.
By Pipe Type
The market segments pipe types into seamless and welded pipes, catering to different technical needs and budget considerations. Seamless pipes provide superior strength and resistance, favored in high-pressure applications like oil and gas transport. Welded pipes offer cost-effective solutions with ease of customization and large-scale production advantages. It enables manufacturers to serve diverse customer preferences and application demands. Both pipe types contribute significantly to market expansion, driven by industry-specific requirements and evolving infrastructure projects.
For instance, Tata Steel manufactures large-diameter welded pipes for municipal water supply projects, leveraging the ease of customization and rapid production to meet infrastructure demands efficiently.
By Coating Thickness
Coating thickness segments include standard, heavy, and ultra-heavy coatings, offering varying degrees of corrosion protection based on environmental conditions. Standard coating suits general-purpose applications with moderate exposure, while heavy and ultra-heavy coatings cater to highly corrosive or industrial environments requiring enhanced durability. It allows customers to select appropriate protection levels for specific operational challenges. This segmentation enhances product versatility, meeting stringent regulatory standards and extending pipe service life across multiple industries.
Segments:
Based on Application
- Construction
- Automotive
- Oil and Gas
- Agriculture
- Telecommunications
- Industrial Infrastructure
Based on Pipe Type
- Seamless Pipes
- Welded Pipes
Based on Coating Thickness
- Standard Coating
- Heavy Coating
- Ultra-Heavy Coating
Based on Pipe Size
- Small Diameter Pipes
- Medium Diameter Pipes
- Large Diameter Pipes
Based on End-User Industry
- Construction Industry
- Automotive Industry
- Oil and Gas Industry
- Energy Sector
- Water Treatment Plants
Based on Product Form
- Pipe Fittings
- Structural Pipes
- Round Pipes
- Square Pipes
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of 28% in the Hot Dip Galvanized Steel Pipe Market due to its well-established infrastructure and stringent regulatory environment. The region experiences steady demand from construction, oil and gas, and industrial sectors that require durable and corrosion-resistant piping. It benefits from advanced manufacturing capabilities and continuous technological innovation, which improve product quality and cost efficiency. The US and Canada invest heavily in pipeline maintenance and replacement, further supporting market growth. It remains a key market for both seamless and welded pipes with various coating thickness options.
Asia-Pacific
Asia-Pacific commands the largest market share at 42% owing to rapid industrialization, urbanization, and infrastructure development in countries such as China, India, and Southeast Asian nations. The expanding oil and gas industry and growing construction activities drive demand for hot dip galvanized steel pipes in the region. It offers manufacturers vast growth opportunities through rising investments in water supply systems, agriculture, and telecommunications infrastructure. Lower production costs and increasing adoption of advanced galvanization technologies contribute to the region’s market dominance. This growth supports ongoing regional economic development and infrastructure modernization.
Europe
Europe accounts for 20% of the Hot Dip Galvanized Steel Pipe Market, driven by mature industrial sectors and increasing focus on sustainable construction and infrastructure projects. Strict environmental and safety regulations push the adoption of high-quality galvanized pipes with heavy and ultra-heavy coatings to withstand harsh conditions. It supports the oil and gas, automotive, and industrial infrastructure sectors with reliable pipe solutions. Countries like Germany, France, and the UK lead market demand through ongoing refurbishment and new infrastructure projects. The region’s emphasis on technological advancement and quality control sustains its competitive position in the global market.
Key Player Analysis
- AK Steel
- Youfa Steel Pipe Group
- Hebei Tianchuang Pipe Co. Ltd.
- Zhejiang Kingland & Pipeline Technologies Co., Ltd.
- Octal
- SHINESTAR STEEL GROUP CO. LTD
- Hunan Prime Steel Pipe
Competitive Analysis
The Hot Dip Galvanized Steel Pipe Market features intense competition among key players focused on product innovation, capacity expansion, and strategic partnerships. Leading companies such as Zhejiang Kingland & Pipeline Technologies Co., Ltd., AK Steel, Hunan Prime Steel Pipe, and SHINESTAR STEEL GROUP CO. LTD leverage advanced manufacturing technologies to enhance coating quality and pipe durability. It drives differentiation through seamless and welded pipe offerings tailored to diverse industry needs. Companies invest in regional expansions to capture emerging market opportunities and strengthen distribution networks. Competitive pricing and adherence to stringent quality standards remain critical for maintaining market share. The market’s dynamic landscape requires continuous improvements in production efficiency and customer service to sustain growth and respond to evolving industry demands. Collaboration with raw material suppliers and adoption of sustainable galvanization processes further support competitive advantage. Continuous innovation and market responsiveness remain essential to meet shifting regulatory and customer requirements globally.
Recent Developments
- In March 2023, US steel manufacturer V\&S Galvanizing acquired Korns Galvanizing Company Inc., enhancing its regional presence, broadening service offerings, and strengthening its position in the Eastern US hot-dip galvanizing market.
- In August 2024, ArcelorMittal Nippon Steel India launched Optigal, a premium color-coated steel brand with an innovative Zinc-Aluminium-Magnesium (ZAM) metallic coating, designed to enhance corrosion resistance and durability for construction and architectural applications.
- In March 2023, V&S Galvanizing acquired Korns Galvanizing Company, Inc., strengthening its regional presence and expanding service capabilities in the Eastern U.S. hot-dip galvanizing market.
Market Concentration & Characteristics
The Hot Dip Galvanized Steel Pipe Market exhibits a moderately concentrated competitive landscape dominated by key regional and global players who focus on technological innovation, capacity expansion, and strategic partnerships. Leading companies invest heavily in research and development to improve product quality, corrosion resistance, and coating technologies, enabling it to meet diverse industry requirements. It benefits from a balance between established manufacturers and emerging players striving to capture market share through cost-effective solutions and regional expansions. The market characteristics include a wide range of product offerings such as seamless and welded pipes with varying coating thicknesses tailored to applications across construction, oil and gas, and industrial infrastructure. It faces challenges from raw material price volatility but leverages advancements in automated manufacturing and sustainable galvanization processes to enhance efficiency. Similar to the Railway Service System Market, it demands adherence to stringent quality standards and regulatory compliance, which shapes competitive dynamics and drives continuous innovation.
Report Coverage
The research report offers an in-depth analysis based on Application, Pipe Type, Coating Thickness, Pipe Size, Product Form, End-User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for corrosion-resistant steel pipes will increase across construction and infrastructure sectors.
- Manufacturers will focus on developing eco-friendly galvanization processes.
- Expansion of pipeline infrastructure in emerging economies will create new growth opportunities.
- Technological advancements will enhance coating durability and reduce production costs.
- The oil and gas industry will continue to drive demand for high-performance galvanized pipes.
- Automation will improve manufacturing efficiency and product consistency.
- Customized pipe solutions will gain traction to meet specific industry requirements.
- Strict environmental and safety regulations will push adoption of advanced coating technologies.
- Regional market expansion will remain a priority for major players.
- Investment in research and development will accelerate innovation and market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Hot Dip Galvanized Steel Pipe Market?
What factors are driving the growth of the Hot Dip Galvanized Steel Pipe Market?
What are the key segments within the Hot Dip Galvanized Steel Pipe Market?
What are some challenges faced by the Hot Dip Galvanized Steel Pipe Market?
Who are the major players in the Hot Dip Galvanized Steel Pipe Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hot Dip Galvanized Steel Pipe Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hot Dip Galvanized Steel Pipe Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12,523 million → 2032: USD 19,660.46 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hot Dip Galvanized Steel Pipe Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hot Dip Galvanized Steel Pipe Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hot Dip Galvanized Steel Pipe Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hot Dip Galvanized Steel Pipe Market Drivers
- 3.3 Hot Dip Galvanized Steel Pipe Market Restraints & Challenges
- 3.4 Hot Dip Galvanized Steel Pipe Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hot Dip Galvanized Steel Pipe Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hot Dip Galvanized Steel Pipe Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hot Dip Galvanized Steel Pipe category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hot Dip Galvanized Steel Pipe Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Hot Dip Galvanized Steel Pipe Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Hot Dip Galvanized Steel Pipe. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hot Dip Galvanized Steel Pipe Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hot Dip Galvanized Steel Pipe Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Hot Dip Galvanized Steel Pipe Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hot Dip Galvanized Steel Pipe (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Hot Dip Galvanized Steel Pipe
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hot Dip Galvanized Steel Pipe Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Hot Dip Galvanized Steel Pipe Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hot Dip Galvanized Steel Pipe Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hot Dip Galvanized Steel Pipe Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hot Dip Galvanized Steel Pipe Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hot Dip Galvanized Steel Pipe Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hot Dip Galvanized Steel Pipe Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hot Dip Galvanized Steel Pipe Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
