
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hurricane Protection Products Sales Market Size 2024 | USD 1200 Million |
| Hurricane Protection Products Sales Market, CAGR | 8.7% |
| Hurricane Protection Products Sales Market Size 2032 | USD 2338.93 Million |
Market Overview:
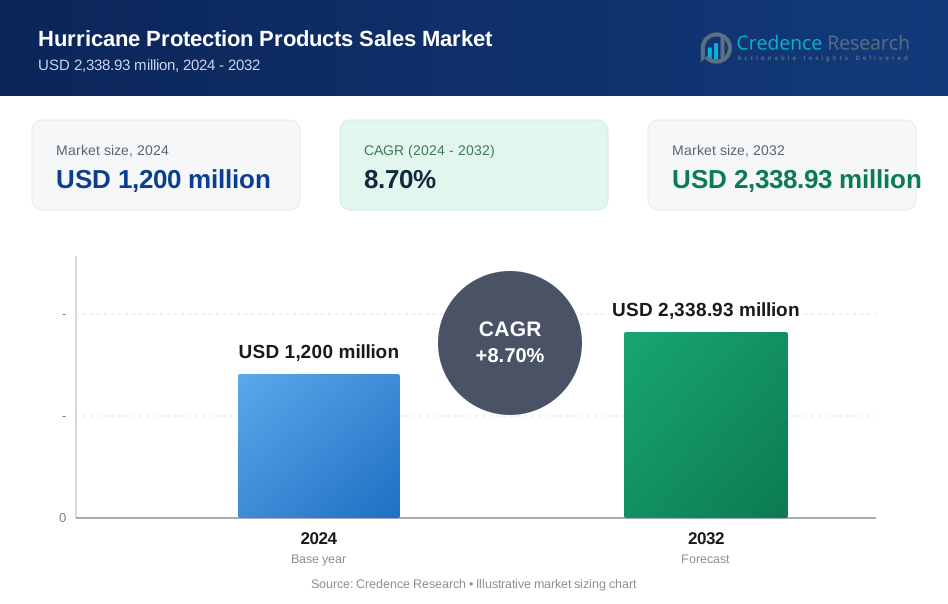
Hurricane Protection Products Sales Market size was valued at USD 1200 million in 2024 and is anticipated to reach USD 2338.93 million by 2032, at a CAGR of 8.7% during the forecast period (2024-2032).
Several key factors are driving the growth of the hurricane protection products market. The growing frequency and intensity of hurricanes, driven by climate change, have heightened the demand for robust and reliable protective solutions. Governments, especially in the United States, are enforcing stricter building codes and disaster preparedness regulations, which require or incentivize the use of hurricane-resistant construction materials. Furthermore, technological advancements in product materials-such as polycarbonate and impact-resistant glass-are improving durability and appeal, encouraging both new installations and retrofitting in existing structures. Rising property insurance premiums in hurricane-prone areas are also motivating property owners to invest in preventive solutions that lower long-term costs and risks. Additionally, the increasing awareness among consumers regarding structural safety and asset protection is enhancing product uptake. Manufacturers are also expanding their product lines to offer customizable and aesthetically pleasing options, further boosting market penetration.
Regionally, North America dominates the market due to high hurricane activity along the Gulf Coast and the Southeastern United States, including Florida, Louisiana, and Texas. These regions have well-established regulatory frameworks that mandate or support the adoption of hurricane protection products. Moreover, significant investments in residential and commercial infrastructure are reinforcing demand in the region. The Asia-Pacific region is expected to witness the fastest growth, driven by increasing urbanization and frequent tropical storms in countries like the Philippines, Japan, and parts of Southeast Asia. Governments in this region are improving early warning systems and promoting structural resilience, which supports product adoption. Meanwhile, the Caribbean and parts of Central America are emerging markets due to their high vulnerability and increasing government focus on disaster resilience. Partnerships between local governments and international aid organizations are also facilitating the adoption of affordable hurricane protection solutions in these regions.
Market Insights:
- The market is expected to grow significantly, from USD 1,200 million in 2024 to USD 2,338.93 million by 2032, driven by an 7% CAGR.
- Increasing hurricane frequency and intensity due to climate change is fueling demand for durable protective systems across coastal regions.
- Stricter building codes and disaster preparedness regulations, especially in the U.S., are mandating the use of certified hurricane protection products.
- Advanced materials like polycarbonate and impact-resistant glass, along with smart technologies, are enhancing product effectiveness and consumer appeal.
- High initial costs remain a barrier, particularly in emerging markets, but grant programs and insurance incentives are helping reduce affordability issues.
- North America leads the market with 43% share, supported by strict regulations, high awareness, and well-established distribution networks.
- Asia-Pacific and Latin America are emerging as high-growth regions due to increasing storm activity, government initiatives, and expanding urban infrastructure.
Market Drivers:
Increasing Frequency and Intensity of Hurricanes:
The growing frequency and severity of hurricanes due to climate change is one of the primary factors fueling demand in the hurricane protection products market. Warmer ocean temperatures are generating stronger and more unpredictable storms, increasing the risk to homes, commercial buildings, and industrial infrastructure in coastal regions. As a result, there is a rising demand for protective systems such as impact-resistant windows, storm panels, and reinforced doors that help reduce structural damage. Property owners are increasingly investing in these solutions as preventive measures to safeguard assets and ensure personal safety.
Stricter Government Regulations and Building Codes:
Governments in hurricane-prone regions are implementing stricter building regulations to enhance disaster preparedness and resilience. In the United States, for instance, states like Florida and Louisiana have mandated the use of hurricane-resistant materials in new construction and major renovations. These regulations are not only enhancing public safety but also boosting demand for certified hurricane protection products. Compliance with such codes often leads to insurance benefits and increased property value, encouraging more property owners to adopt these solutions. The alignment of construction standards with climate adaptation strategies further supports sustained market growth.
Technological Advancements in Materials and Designs:
Advancements in material science and product engineering are significantly contributing to market expansion. Modern hurricane protection products now incorporate high-performance materials such as polycarbonate, laminated safety glass, and tensile fabric that offer improved strength, durability, and visual appeal. For instance, polycarbonate hurricane panels, including brands like LEXAN™, are recognized by Florida building codes for their exceptional impact resistance and are preferred over traditional wood panels for storm preparation. Additionally, smart technologies such as automated shutters and remote-control systems are gaining popularity, especially among tech-savvy consumers. These innovations are not only increasing the functional value of protection systems but also enabling broader adoption across both residential and commercial sectors.
Rising Awareness and Economic Incentives:
Increasing awareness of the economic and safety advantages of hurricane protection solutions is driving consumer adoption. Many insurance providers offer reduced premiums for properties equipped with certified protection products, making them a cost-effective investment. Furthermore, governments and non-profit organizations are conducting public awareness campaigns to highlight the benefits of storm preparedness. As property owners become more proactive about disaster mitigation, the demand for durable and efficient protection products is expected to grow consistently across various global markets.
Market Trends:
Shift Toward Sustainable Materials:
The hurricane protection products market is increasingly embracing sustainability. Manufacturers are developing protective systems using recyclable, non-toxic, and low-impact materials to meet growing environmental standards. This aligns with the global shift toward eco-friendly construction practices. Consumers are also showing a strong preference for products that support green building initiatives, encouraging brands to invest in sustainability certifications and environmentally responsible manufacturing.
Integration of Smart Technologies:
Smart technology is becoming a key differentiator in the market. Hurricane protection systems are now being equipped with automation features, enabling remote operation through mobile applications and smart home platforms. For instance, Storm Smart Technologies has advanced integrated storm protection systems that allow users to control shutters and barriers remotely, enhancing both safety and convenience for residential and commercial clients. Users can activate shutters or protective barriers in real-time, offering greater control and responsiveness during emergencies. This trend is particularly gaining traction in residential and commercial segments seeking enhanced safety, convenience, and energy efficiency.
Focus on Aesthetic Appeal:
Design is playing an increasingly important role in the selection of hurricane protection products. Consumers are looking for solutions that not only provide safety but also complement the architectural design of their properties. For instance, Defender Screens International (Progressive Screens) is recognized for its advanced storm screening technologies that combine robust protection with aesthetic appeal, offering customizable options that blend seamlessly with modern buildings. Manufacturers are responding with customizable, sleek designs that blend seamlessly with modern buildings. The demand for aesthetically pleasing yet functional systems is rising, especially in premium housing and commercial spaces.
Rise in Retrofitting and Renovation Activities There is growing demand for retrofitting hurricane protection products in existing structures. Older homes and commercial buildings, which were not originally constructed with storm resilience in mind, are being upgraded with modern protective solutions. Government subsidies, regulatory support, and insurance discounts are driving this trend. Retrofitting enhances both safety and property value, making it a practical choice for homeowners and real estate developers in high-risk regions.
Market Challenges Analysis:
High Initial Costs and Affordability Constraints:
One of the major challenges facing the hurricane protection products market is the high upfront cost of installation. Advanced protective systems such as impact-resistant windows, storm shutters, and automated barriers require significant investment, which can be a deterrent for middle- and low-income property owners. For instance, the My Safe Florida Homes Wind Mitigation Grant program, administered by the Florida Department of Financial Services, provides matching grants up to $10,000 to help homeowners install hurricane protection systems like accordion shutters and impact windows, effectively reducing the financial burden for qualifying residents. While these systems offer long-term savings through reduced repair costs and lower insurance premiums, the initial expense often outweighs immediate budgets, especially in regions with limited financial support or subsidies. This cost barrier is particularly pronounced in emerging economies, where awareness may be rising but purchasing power remains limited. Moreover, limited access to financing options or government-backed loan programs further restricts adoption. Small businesses and residential property owners often prioritize other structural needs over hurricane protection, delaying critical safety upgrades.
Lack of Awareness and Standardization Issues:
Another challenge affecting market growth is the lack of awareness and education about the benefits of hurricane protection solutions. Many homeowners, particularly in newly developing coastal regions, remain unaware of the structural and financial advantages of proactive protection. This knowledge gap results in a reactive approach to hurricane preparedness, delaying the adoption of safety systems until after disaster strikes. Additionally, the market suffers from inconsistent product standards and regulatory enforcement across regions. The absence of unified certification systems creates confusion among consumers and raises concerns about product quality and reliability. Inadequate promotion by local authorities and minimal industry collaboration further exacerbate this issue. As a result, market players face difficulties in building trust and achieving large-scale consumer engagement in underserved regions.
Market Opportunities:
The Hurricane Protection Products Sales Market presents significant growth opportunities driven by increasing global awareness of climate-related risks and the rising emphasis on resilient infrastructure. As hurricanes become more frequent and intense due to climate change, there is a growing demand for advanced protective systems across residential, commercial, and industrial sectors. This creates substantial opportunities for manufacturers to expand their product portfolios with innovative, durable, and cost-effective solutions. The rising adoption of green building certifications and sustainable construction practices also opens doors for eco-friendly protection products that align with environmental standards. Furthermore, as insurance companies continue to offer premium reductions for properties equipped with certified protection systems, more consumers are likely to invest in these solutions, strengthening market prospects.
Emerging economies in Asia-Pacific, Latin America, and the Caribbean offer untapped potential as governments begin prioritizing disaster preparedness and infrastructure resilience. Investment in coastal infrastructure, coupled with urbanization and increasing property values, supports demand for retrofit-friendly and affordable protection systems in these regions. Technological advancements such as smart protection systems integrated with IoT capabilities also provide a unique market edge, appealing to tech-savvy consumers and commercial property managers. Additionally, public-private partnerships, government incentives, and educational campaigns focused on disaster resilience are expected to play a vital role in expanding market reach. Companies that can offer scalable, customized, and easy-to-install solutions will be well-positioned to capitalize on this growing demand, especially in regions with evolving construction regulations and growing environmental vulnerabilities.
Market Segmentation Analysis:
By Product Type
The market is segmented into storm panels, accordion shutters, roll-down shutters, impact-resistant windows and doors, hurricane fabrics, and others. Impact-resistant windows and roll-down shutters are gaining significant traction due to their dual functionality in providing protection and enhancing aesthetics. Storm panels and accordion shutters remain popular in cost-sensitive markets due to their affordability and effectiveness in emergency preparedness.
By Material Type
Key materials used include aluminum, steel, polycarbonate, and fabric-based composites. Aluminum dominates the market due to its strength, corrosion resistance, and lightweight properties. However, polycarbonate and advanced fabric materials are experiencing rapid adoption for their transparency, flexibility, and ease of handling. These modern materials are particularly favored in residential installations where visibility and design are important.
By Distribution Channel
The distribution channels include direct sales, retail stores, and online platforms. Direct sales remain the dominant channel, especially for commercial projects and customized installations that require professional consultation. Meanwhile, the growing preference for DIY solutions has fueled the expansion of online sales, offering consumers greater accessibility and product variety. Retail outlets continue to serve as key points of purchase in regional and coastal markets.
Segmentations:
By Product Type
- Storm Panels
- Accordion Shutters
- Roll-Down Shutters
- Bahama Shutters
- Colonial Shutters
- Impact-Resistant Windows and Doors
- Hurricane Fabric
- Others
By Material Type
- Aluminum
- Steel
- Polycarbonate
- Fabric
- Others
By Distribution Channel
- Direct Sales
- Retail Stores
- Online Platforms
- Distributors/Dealers
By Application
- Residential
- Commercial
- Industrial
- Institutional
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
North America holds the largest share in the global hurricane protection products market, accounting for 43% of the total market. This dominance is driven by frequent hurricane activity, particularly in southeastern states such as Florida, Louisiana, and Texas. Strict building codes and disaster preparedness regulations mandate the use of certified storm-resistant systems, which significantly boost product demand. Public awareness, insurance incentives, and government support further strengthen adoption rates. Additionally, the presence of established manufacturers and continuous innovation in materials and designs reinforce the region’s dominant position. The market also benefits from strong distribution networks and a high rate of retrofitting projects in older residential properties.
Asia-Pacific
Asia-Pacific holds a 26% share of the global hurricane protection products market and is the fastest-growing regional segment. This growth is supported by rapid urbanization and infrastructure development in coastal cities. Countries like Japan, the Philippines, India, and Vietnam frequently experience typhoons and tropical storms, prompting increased investments in disaster preparedness. Governments are tightening building standards to enhance resilience, while the rising need for retrofit-friendly and affordable solutions is creating new opportunities. The demand for hurricane protection systems is expanding across both residential and commercial sectors in this region. Local players are also entering the market with cost-effective innovations tailored to regional building structures and climate risks.
Latin America
Latin America accounts for 15% of the global hurricane protection products market and is emerging as a key growth area. Countries such as Mexico and those across the Caribbean are increasingly vulnerable to seasonal cyclones and hurricanes, heightening the urgency for resilient infrastructure. Both public and private sectors are investing in storm preparedness solutions. Growing consumer awareness and insurance-driven benefits are supporting product adoption. Local manufacturers are increasingly offering cost-effective and easy-to-install systems tailored for coastal residential applications. Regional collaborations and government subsidies are also helping accelerate adoption, especially in low-income and high-risk zones.
Key Player Analysis:
- PGT Innovations
- Clopay Corporation
- Assa Abloy Group
- Wayne Dalton
- Plylox Hurricane Clips
- Custom Hurricane Products Inc.
- Babcock-Davis
- Eastern Metal Supply Inc.
- Storm Smart Industries
- Ply Gem Holdings Inc.
- Andersen Corporation
- Overhead Door Corporation
Competitive Analysis:
The Hurricane Protection Products Sales Market is characterized by moderate to high competition, with several key players striving to enhance market presence through product innovation, strategic partnerships, and geographic expansion. Leading companies such as Storm Smart Technologies, Armor Screen, and Defender Screens International focus on delivering advanced, durable, and customizable solutions to meet varying consumer needs. Competitive differentiation is largely driven by product performance, design aesthetics, installation flexibility, and compliance with regional building codes. Many firms are also investing in eco-friendly materials and smart technologies to appeal to environmentally conscious and tech-savvy customers. In addition, local and regional manufacturers maintain a strong foothold in specific markets by offering cost-effective and easily deployable solutions tailored to regional weather patterns. As the demand for hurricane protection continues to rise, companies that can balance quality, affordability, and regulatory compliance are likely to maintain a competitive edge and expand their market share in both developed and emerging regions.
Recent Developments:
In January 2025, Storm Smart continued to offer a comprehensive range of hurricane protection products, including Storm Catcher screens, impact-resistant windows and doors, aluminum shutters, and storm panels, with ongoing expansion in Florida and other hurricane-prone regions.Market Concentration & Characteristics:
The Hurricane Protection Products Sales Market exhibits a moderately fragmented structure, with a mix of well-established players and regional manufacturers contributing to its overall dynamics. Market concentration is relatively low at the global level, as several companies operate within localized markets, particularly in coastal regions prone to hurricanes. The market is characterized by high customization, as product requirements often vary based on building codes, regional weather conditions, and customer preferences. Demand is primarily driven by residential and commercial sectors, with growing traction in retrofitting applications for older properties. Product innovation, material strength, ease of installation, and regulatory compliance are key characteristics influencing buyer decisions. Additionally, the market shows strong seasonal behavior, with sales peaking during pre-hurricane seasons. As climate change continues to elevate storm risks, the market is evolving with increased emphasis on smart technologies and sustainable materials, reshaping product offerings and supplier strategies to meet future resilience standards.
Report Coverage:
The research report offers an in-depth analysis based on Product type, Material Type, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for hurricane protection products is expected to rise as climate change continues to increase the frequency and severity of storms globally.
- Governments are likely to implement stricter building codes and safety regulations, further boosting product adoption in both residential and commercial sectors.
- Advancements in materials, such as high-impact polycarbonate and reinforced fabrics, will lead to the development of more durable and lightweight protective systems.
- The integration of smart technologies into shutters and protection systems will enhance real-time responsiveness and remote operation, appealing to tech-savvy consumers.
- Increased investment in coastal infrastructure and real estate development will create new opportunities for product installations in high-risk regions.
- Retrofitting of older buildings with modern hurricane protection solutions will become more common, supported by public safety campaigns and insurance incentives.
- The market will see greater emphasis on aesthetically designed products that align with modern architectural styles, especially in upscale residential projects.
- Emerging economies in Asia-Pacific, Latin America, and the Caribbean will witness growing adoption as urbanization and disaster preparedness initiatives expand.
- Online and direct-to-consumer distribution channels are expected to grow, making products more accessible to individual homeowners and small businesses.
- Industry players will focus on strategic partnerships, product customization, and regional expansion to strengthen their presence in evolving markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the hurricane protection products market?
What is driving the growth of this market?
Why is North America leading the market?
Which region is expected to grow the fastest?
What types of products are becoming more popular?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hurricane Protection Products Sales Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hurricane Protection Products Sales Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,200 million → 2032: USD 2,338.93 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hurricane Protection Products Sales Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hurricane Protection Products Sales Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hurricane Protection Products Sales Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hurricane Protection Products Sales Market Drivers
- 3.3 Hurricane Protection Products Sales Market Restraints & Challenges
- 3.4 Hurricane Protection Products Sales Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hurricane Protection Products Sales Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hurricane Protection Products Sales Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hurricane Protection Products Sales category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hurricane Protection Products Sales Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Hurricane Protection Products Sales Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Hurricane Protection Products Sales. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hurricane Protection Products Sales Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hurricane Protection Products Sales Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Hurricane Protection Products Sales Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hurricane Protection Products Sales (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Hurricane Protection Products Sales
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hurricane Protection Products Sales Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Hurricane Protection Products Sales Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hurricane Protection Products Sales Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hurricane Protection Products Sales Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hurricane Protection Products Sales Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hurricane Protection Products Sales Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hurricane Protection Products Sales Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hurricane Protection Products Sales Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
