
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| India Frozen Bakery Products Market Size 2023 | USD 1,212.39 million |
| India Frozen Bakery Products Market, CAGR | 7.53% |
| India Frozen Bakery Products Market Size 2032 | USD 2,342.37 million |
Market Overview
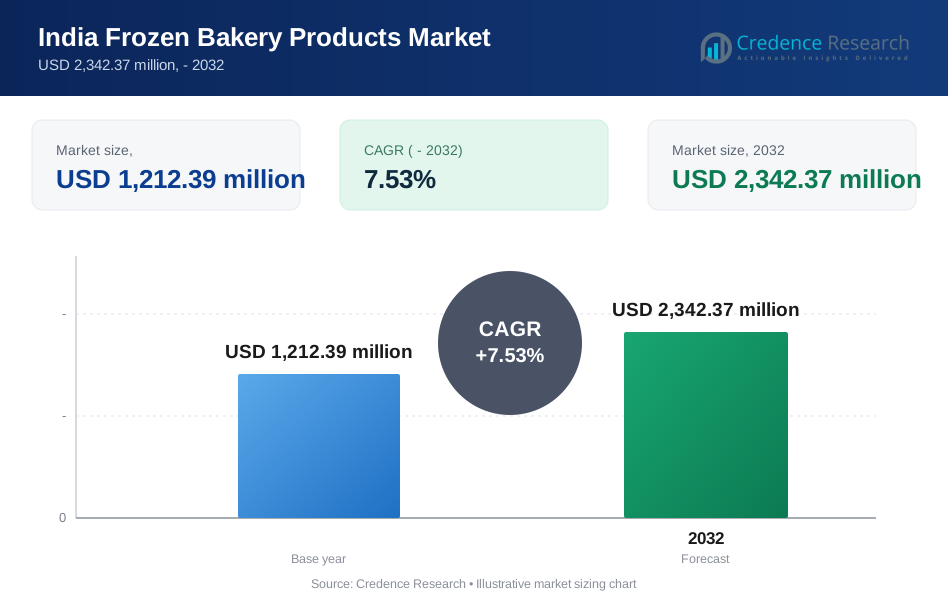
The India Frozen Bakery Products Market is projected to grow from USD 1,212.39 million in 2023 to an estimated USD 2,342.37 million by 2032, with a compound annual growth rate (CAGR) of 7.53% from 2024 to 2032. This robust growth is attributed to the increasing urbanization, rising disposable incomes, and the growing preference for convenience foods among the Indian population.
Key market drivers include the growing consumer demand for ready-to-eat bakery products, the expansion of retail chains, and the increasing influence of western food culture. Additionally, advancements in freezing technology have enhanced the shelf life and quality of frozen bakery products, further boosting their acceptance among consumers. The trend toward healthier and premium bakery products is also gaining traction, contributing to market growth.
Geographically, the market is witnessing significant growth in metropolitan areas such as Delhi, Mumbai, and Bangalore, driven by the increasing presence of retail outlets and bakeries offering frozen products. The southern region of India is also emerging as a key market due to the rising demand for frozen bakery products among the urban middle class. Key players in the market include Aryzta AG, Lantmannen, General Mills Inc., McCain Foods Limited, and Nestlé SA, who are focusing on expanding their product portfolios and strengthening their distribution networks across the country.
Market Drivers
Rising Urbanization and Changing Lifestyles
The increasing urbanization and shift in consumer lifestyles are major drivers of the India Frozen Bakery Products Market. As more people move to urban areas, there is growing demand for convenient food options that fit busy schedules. Urban consumers, especially millennials and working professionals, are gravitating towards ready-to-eat and easy-to-prepare foods like frozen bakery items. For instance, a survey by the National Restaurant Association of India found that 65% of urban millennials prefer convenience foods due to time constraints. The convenience of frozen bakery products - longer shelf life, minimal preparation time, and year-round availability - has made them popular among urban populations. Additionally, western food influences have increased the appeal of products like frozen bread, pastries and pizzas. A study by Nielsen India reported that frozen bakery sales in metro cities grew by 24% in 2022, driven by changing food habits. The Food Safety and Standards Authority of India has also noted a 35% year-on-year increase in frozen food product approvals, indicating rising consumer acceptance. As manufacturers expand offerings to meet evolving urban consumer needs, the frozen bakery market continues to grow rapidly across India's major cities.
Expansion of Retail Chains and E-commerce
The growth of organized retail and e-commerce has significantly boosted India's frozen bakery products market. Rapid expansion of supermarkets, hypermarkets and convenience stores has improved product visibility and accessibility. For instance, a report by the Retailers Association of India found that the number of modern retail outlets stocking frozen foods increased by 18% in 2022. These retail chains offer a wide assortment of frozen bakery items, driving consumer purchases. Additionally, the rise of e-commerce has revolutionized food shopping habits. Online grocery platforms now offer extensive frozen bakery selections with home delivery options. According to a survey by RedSeer Consulting, online grocery sales in India grew by 65% in 2022, with frozen foods being one of the fastest-growing categories. The COVID-19 pandemic further accelerated the shift to online shopping. Government data shows that e-commerce food and grocery sales doubled during 2020-2022. Major e-commerce players like BigBasket and Grofers reported over 40% growth in their frozen foods segment. The dual forces of retail expansion and e-commerce boom have significantly widened the reach and availability of frozen bakery products across urban and semi-urban India, fueling market growth.
Advancements in Freezing Technology
Technological innovations in freezing processes have been crucial for the growth of India's frozen bakery products market. Improved freezing techniques have significantly enhanced the quality, taste and texture of frozen bakery items. For instance, a study by the Central Food Technological Research Institute found that quick-freezing methods like blast freezing can retain up to 95% of the original nutritional content in baked goods. This has increased consumer confidence in frozen products. Packaging innovations have also extended shelf life and prevented quality deterioration. The Indian Institute of Packaging reported that new modified atmosphere packaging can extend frozen bakery shelf life by up to 12 months. These advancements have enabled manufacturers to offer diverse product ranges. According to the All India Bread Manufacturers' Association, the number of frozen bakery SKUs in India increased by 40% between 2020-2022. Government bodies like the Ministry of Food Processing Industries have supported R&D in freezing technologies through various schemes. Industry data shows that investment in freezing equipment by bakery companies grew by 28% in 2022. As freezing technology continues to improve product quality and variety, consumers are more willing to incorporate frozen bakery items into their diets, driving market expansion.
Growing Health Awareness and Demand for Premium Products
As health awareness among Indian consumers continues to rise, there has been a noticeable shift in preference towards healthier and premium frozen bakery products. Consumers are becoming more conscious of the ingredients in their food, leading to increased demand for products that are perceived as healthier, such as those made with whole grains, natural sweeteners, and without artificial additives or preservatives. The frozen bakery segment has responded to this trend by introducing a variety of health-oriented products, including gluten-free, low-sugar, and high-fiber options. This focus on health is not limited to individual consumers; even institutional buyers, such as hotels and cafes, are increasingly seeking out premium frozen bakery items that cater to the health-conscious segment of their clientele. Additionally, there is a growing trend towards artisanal and gourmet frozen bakery products, which offer unique flavors and high-quality ingredients. These premium products often command higher prices but are gaining traction among affluent consumers who are willing to pay more for superior quality and taste. The convergence of health consciousness and the desire for premium, indulgent experiences is driving the diversification of product offerings in the frozen bakery market, further propelling its growth.
Market Trends
Increased Demand for Health-Conscious and Functional Bakery Products
One of the most prominent trends in the India Frozen Bakery Products Market is the rising demand for health-conscious and functional bakery items. As consumers become more aware of their dietary habits, there is a growing preference for products that offer nutritional benefits alongside convenience. This trend has led to an increase in frozen bakery products fortified with vitamins, minerals, and other functional ingredients. For instance, whole grain breads, gluten-free pastries, and low-calorie snacks are gaining popularity among health-conscious consumers. There is also a noticeable shift towards products with clean labels—those free from artificial preservatives, additives, and GMOs. Manufacturers are responding by developing frozen bakery products that cater to specific dietary needs, such as diabetic-friendly or heart-healthy options. The emphasis on health and wellness is not only influencing product formulations but also driving innovation in the frozen bakery segment, as companies strive to meet evolving consumer expectations.
Growth of Premium and Artisanal Frozen Bakery Products
Another significant trend in the India Frozen Bakery Products Market is the increasing demand for premium and artisanal frozen bakery items. As disposable incomes rise and consumer preferences become more sophisticated, there is a growing market for high-quality, indulgent bakery products. Consumers are seeking out frozen bakery items that offer unique flavors, superior ingredients, and an artisanal touch. This trend is particularly evident in urban areas, where consumers are willing to pay a premium for products that provide a gourmet experience. Artisanal frozen breads, pastries, and desserts—often made with organic or locally sourced ingredients—are becoming increasingly popular. Moreover, the influence of global culinary trends is driving demand for international bakery products such as croissants, baguettes, and gourmet pizzas, which are now available in frozen formats. The home bakers' segment is thriving on innovative recipes, contributing to this trend. The growth of premium and artisanal frozen bakery products reflects a broader trend towards experiential consumption, where consumers are seeking both convenience and quality in their food choices.
Market Restraints and Challenges
Limited Cold Chain Infrastructure and High Logistics Costs
The India Frozen Bakery Products Market faces significant challenges due to limited cold chain infrastructure and high logistics costs. Many parts of India, especially rural and semi-urban areas, lack adequate cold chain facilities, hindering the distribution of frozen bakery products. This infrastructure gap makes it difficult for manufacturers and retailers to expand their reach and serve a wider customer base. The costs associated with maintaining cold storage and refrigerated transportation are substantial, impacting the profitability of companies in the frozen bakery segment. These expenses are often transferred to consumers, making frozen bakery products relatively expensive compared to fresh alternatives. For instance, a survey conducted by the National Centre for Cold-chain Development (NCCD) revealed that a significant portion of perishable food products, including frozen bakery items, are lost due to inadequate cold chain facilities. The study also highlighted that the cost of refrigerated transportation in India is considerably higher than in developed countries, further straining the industry.
Consumer Perception and Preference for Fresh Bakery Products
A major challenge for the India Frozen Bakery Products Market is the strong consumer preference for fresh bakery items over frozen alternatives. Fresh bakery products are widely available in India and are often perceived as superior in taste and quality. This cultural preference presents a substantial barrier to the adoption of frozen bakery products. Despite advancements in freezing technology, many consumers still harbor misconceptions about the quality of frozen foods. For instance, a significant percentage of Indian consumers associate frozen foods with being less healthy and flavorful compared to fresh alternatives. The study also revealed a lack of awareness about the convenience and benefits of frozen bakery items among consumers. To address this challenge, manufacturers need to invest in consumer education and marketing strategies. The Indian Bakers Federation, in collaboration with frozen food companies, has initiated awareness campaigns to highlight the advantages of frozen bakery products, such as longer shelf life and consistent quality.
Market Segmentation Analysis
By Product Type
Bread remains the largest segment in the India Frozen Bakery Products Market, driven by its status as a staple food and the growing popularity of frozen varieties. For instance, surveys by leading bakery companies indicate strong consumer preference for white, whole wheat, and multigrain frozen breads, especially in urban areas. Cakes and pastries are rapidly gaining traction as consumer preferences shift towards indulgent, premium options. Government data shows increasing consumption of these products for celebrations and gifting. Morning goods like muffins, croissants, and rolls are increasingly in demand among working professionals and students. Industry reports highlight the influence of Western eating habits on this trend. The frozen pizza crust segment is expanding as more consumers embrace at-home pizza preparation. Growing interest in customizable, ready-to-use crusts. Other product types, such as doughnuts, pies, and cookies, are gradually expanding. Manufacturer surveys indicate introduction of innovative products to meet niche market demands and consumer desires for variety.
By Distribution Channel
Hypermarkets and supermarkets dominate the distribution of frozen bakery products in India, according to retail industry data. These outlets offer a wide variety under one roof, making them the preferred choice for consumers seeking both variety and promotional deals. Specialty stores, including gourmet and bakery shops, cater to a more discerning urban clientele. Market research shows a growing segment of consumers willing to pay a premium for high-quality, artisanal offerings. Online retailing is the fastest-growing channel, as indicated by e-commerce platform statistics. The convenience of online shopping and home delivery particularly appeals to urban consumers. Government surveys highlight the crucial role of other distribution channels, such as smaller retail outlets, convenience stores, and direct sales, in reaching consumers in semi-urban and rural areas where larger retail chains may be absent.
Segments
Based on Product Type
- Bread
- Cakes and Pastries
- Morning Goods
- Pizza Crust
- Other Product Types
Based on Distribution Channel
- Hypermarkets/Supermarkets
- Specialty Stores
- Online Retailing
- Other Distribution Channels
Based on Region
- Northern Region
- Western Region
- Southern Region
- Eastern Region
Regional Analysis
Northern Region
The Northern region holds the largest market share, accounting for approximately 35% of the India Frozen Bakery Products Market. This is primarily due to high urbanization rates and the strong presence of organized retail chains in major cities like Delhi, Chandigarh, and Jaipur. For instance, a survey conducted by the National Restaurant Association of India found that 72% of consumers in Northern cities prefer frozen bakery products for their convenience. The region's consumers are increasingly adopting Western food habits, leading to rising demand for frozen bread, pastries, and pizza crusts. The growth of the hospitality and tourism industry has further bolstered the market, with hotels and restaurants incorporating more frozen bakery items into their menus. A robust cold chain infrastructure supports distribution and storage, ensuring widespread availability.
Western Region
The Western region, including states like Maharashtra and Gujarat, holds a significant market share of approximately 30%. This region is characterized by high disposable income levels and a rapidly growing urban population, particularly in cities like Mumbai and Ahmedabad. For instance, a study by the Federation of Indian Chambers of Commerce and Industry (FICCI) revealed that 65% of urban households in Western India regularly purchase frozen bakery products. The region is a hub for the food and beverage industry, with strong consumer demand for convenience foods. The influence of international culinary trends is evident, with a growing preference for artisanal and premium bakery items. A survey by the Indian Bakers Federation found that 80% of bakeries in Mumbai now offer frozen products. The expansion of modern retail outlets and e-commerce platforms has further facilitated accessibility, driving market growth.
Key players
- Aryzta AG
- Lantmannen
- General Mills Inc.
- McCain Foods Limited
- Ajinomoto Co. Inc.
- Conagra Brands Inc.
- Flower Foods Inc.
- Nestlé SA
- Pasco Shikishima Corporation
- Grupo Bimbo
Competitive Analysis
The India Frozen Bakery Products Market is highly competitive, with several global and regional players vying for market share. Aryzta AG, Lantmannen, and General Mills Inc. are among the leading companies, leveraging their extensive product portfolios and strong distribution networks to maintain a competitive edge. McCain Foods Limited and Conagra Brands Inc. are notable for their innovative product offerings and focus on expanding their presence in the Indian market. Nestlé SA and Ajinomoto Co. Inc. are capitalizing on their established brand recognition and expertise in food processing to introduce new frozen bakery products tailored to local tastes. Pasco Shikishima Corporation and Grupo Bimbo are also key players, steadily increasing their market footprint through strategic partnerships and product diversification. The market is characterized by continuous innovation, with companies investing in new product development, marketing strategies, and expansion of their retail networks to capture a larger share of the growing consumer demand.
Recent Developments
- In June 2024, McCain Foods expanded its network of Innovation Hub farms across North America, adding four new farms in Alberta, Wisconsin, Maine, and Idaho. While not directly related to tablet counting machines, this expansion supports McCain's commitment to implement regenerative agriculture practices.
- In June 2024, Conagra Brands enhanced its artificial intelligence capabilities with a human-centered approach. While not specifically about tablet counting machines, this development could potentially impact various aspects of their operations, including manufacturing processes.
- In April 2024, Flowers Foods introduced 11 new bread and snacking products across its various brands, including Nature's Own, Dave's Killer Bread, Wonder, Canyon Bakehouse, Tastykake, and Mrs. Freshley's. While not related to tablet counting machines, this demonstrates the company's focus on product innovation.
Market Concentration and Characteristics
The India Frozen Bakery Products Market is moderately fragmented, with a mix of global giants and regional players competing for market share. Market concentration is increasing as leading companies such as Aryzta AG, General Mills Inc., and Nestlé SA strengthen their positions through strategic acquisitions, partnerships, and product innovations. Despite the presence of a few dominant players, the market remains competitive, with new entrants regularly emerging, driven by the growing consumer demand for convenient and premium bakery products. Characteristics of the market include a strong focus on product quality, innovation, and expanding distribution networks, particularly in urban areas where consumer preferences are rapidly evolving towards Western-style frozen bakery items.
Report Coverage
The research report offers an in-depth analysis based on Products Type, Distribution channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As urbanization in India accelerates, the demand for convenient and ready-to-eat frozen bakery products is expected to rise, driving market growth across metropolitan areas.
- The ongoing expansion of organized retail and e-commerce platforms will enhance consumer access to frozen bakery products, contributing to increased market penetration, particularly in tier 2 and tier 3 cities.
- Growing health awareness among consumers will lead to a surge in demand for healthier frozen bakery options, including whole grain, gluten-free, and low-calorie products, fostering innovation in the market.
- Innovations in freezing technology and packaging will continue to improve product quality and shelf life, making frozen bakery products more appealing and expanding their reach across the country.
- The influence of Western food culture will strengthen, particularly among younger consumers, driving increased consumption of products like frozen pizzas, croissants, and pastries.
- There will be a significant growth in the premium segment as consumers seek out artisanal and gourmet frozen bakery products, offering unique flavors and superior quality.
- Investments in cold chain infrastructure will expand the distribution capabilities of frozen bakery products, enabling companies to reach more remote and underserved regions.
- The market will witness heightened competition as both global giants and local players introduce new products and expand their distribution networks to capture a larger share of the growing consumer base.
- Sustainability will become a key focus, with companies adopting eco-friendly packaging and sourcing practices to appeal to environmentally conscious consumers.
- The Southern and Eastern regions of India are expected to show strong growth in demand for frozen bakery products, driven by increasing urbanization, rising incomes, and greater consumer awareness of frozen foods.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the India Frozen Bakery Products Market in 2023, and whatis it projected to reach by 2032?
What factors are driving the growth of the India Frozen Bakery Products Market?
How is the expansion of retail chains influencing the frozen bakery market in India?
What role does freezing technology play in the India Frozen Bakery Products Market?
Which regions in India are showing significant growth in the frozen bakery productsmarket?
What trends are shaping the future of the India Frozen Bakery Products Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Frozen Bakery Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Frozen Bakery Products Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 1,212.39 million → 2032: USD 2,342.37 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Frozen Bakery Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Frozen Bakery Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Frozen Bakery Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Frozen Bakery Products Market Drivers
- 3.3 India Frozen Bakery Products Market Restraints & Challenges
- 3.4 India Frozen Bakery Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Frozen Bakery Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Frozen Bakery Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Frozen Bakery Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Frozen Bakery Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Frozen Bakery Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Frozen Bakery Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Frozen Bakery Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Frozen Bakery Products Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Frozen Bakery Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Frozen Bakery Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Frozen Bakery Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Frozen Bakery Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Frozen Bakery Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Frozen Bakery Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Frozen Bakery Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Frozen Bakery Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Frozen Bakery Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Frozen Bakery Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Frozen Bakery Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
