
Market Overview:
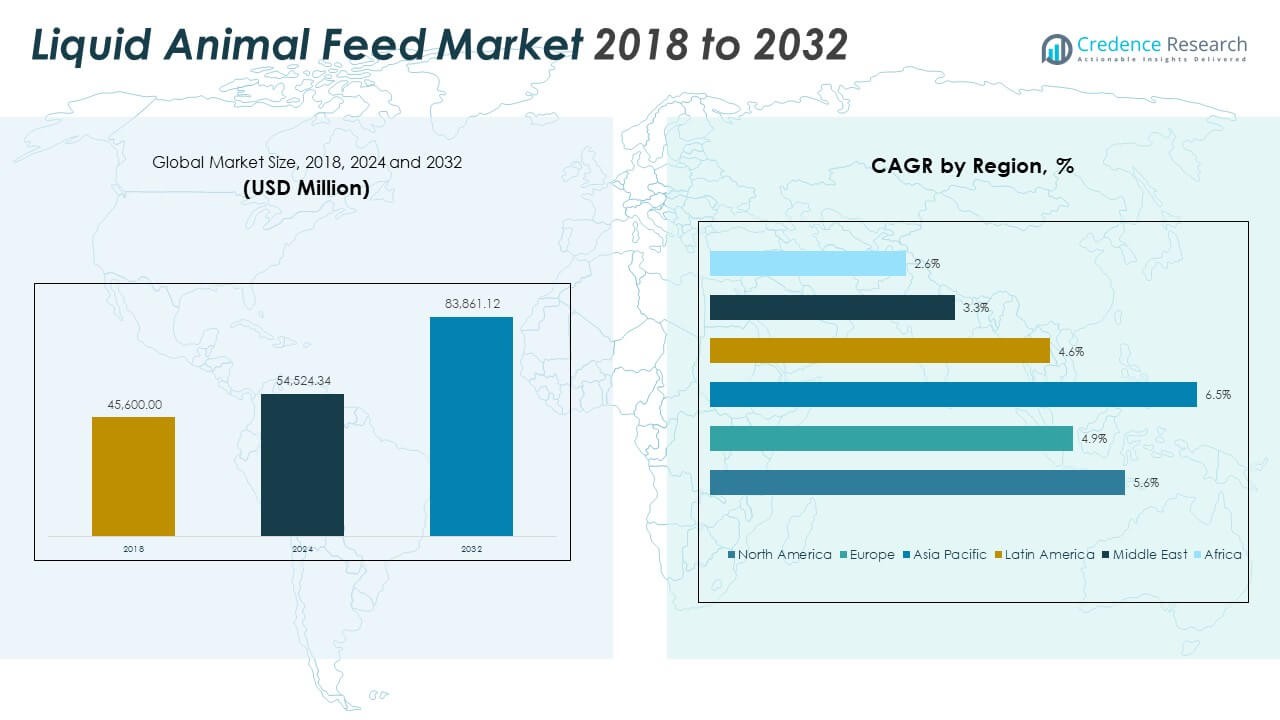
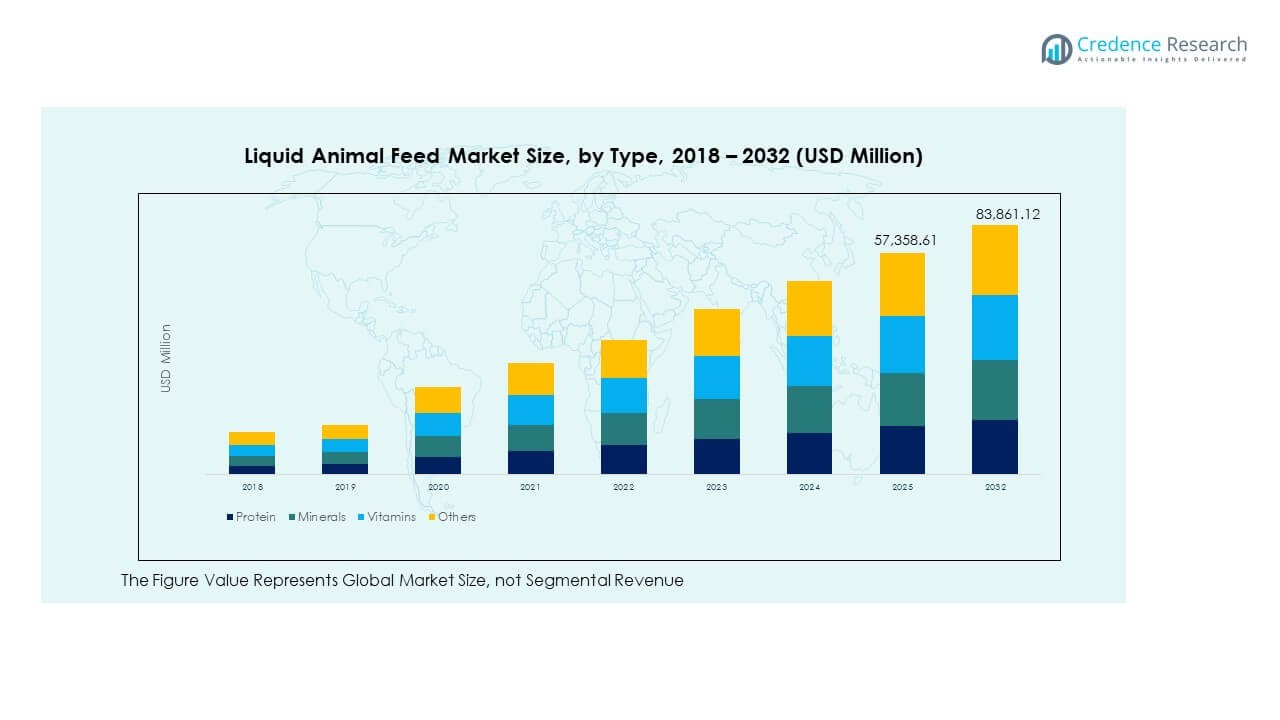
The Liquid Animal Feed Market size was valued at USD 45,600.00 million in 2018 to USD 54,524.34 million in 2024 and is anticipated to reach USD 83,861.12 million by 2032, at a CAGR of 5.58% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Liquid Animal Feed Market Size 2024 | USD 54,524.34 Million |
| Liquid Animal Feed Market, CAGR | 5.58% |
| Liquid Animal Feed Market Size 2032 | USD 83,861.12 Million |
Rising livestock populations and the increasing focus on nutrient-dense feed formulations are key drivers for market growth. Liquid feeds improve digestibility, enhance nutrient absorption, and reduce wastage compared to traditional dry feed. Farmers are adopting molasses-based and protein-enriched formulations to support higher milk yields, weight gain, and overall animal health. Growing awareness of feed efficiency, coupled with the need for sustainable livestock nutrition, is pushing feed producers to innovate and expand product portfolios targeting dairy, poultry, and swine production systems.
Asia Pacific dominates the global market, led by expanding dairy and poultry industries in China, India, and Southeast Asia. North America follows due to strong industrial livestock production and advanced feed technologies. Europe maintains steady growth driven by sustainability initiatives and regulated feed quality standards. Latin America is emerging as a promising region supported by growing meat exports, while the Middle East and Africa show gradual adoption supported by government-led livestock productivity programs and increasing focus on food security.
Market Insights:
- The Liquid Animal Feed Market was valued at USD 45,600.00 million in 2018, reached USD 54,524.34 million in 2024, and is projected to hit USD 83,861.12 million by 2032, growing at a CAGR of 5.58%.
- Asia Pacific leads with a 35.3% share, driven by strong dairy, poultry, and aquaculture sectors in China and India. North America follows with 27.4%, supported by advanced feed technologies, while Europe holds 24.5% due to sustainable livestock practices.
- Asia Pacific remains the fastest-growing region with a 35.3% share, fueled by rapid urbanization, expanding livestock production, and government initiatives promoting efficient feed usage.
- Protein dominates segmental distribution with an estimated 40% share, reflecting its vital role in animal growth and feed efficiency.
- Minerals and vitamins collectively contribute nearly 45%, showing rising demand for balanced nutrition and fortified liquid feed formulations across livestock sectors.
Market Drivers
Rising Livestock Population and Demand for Nutrient-Enriched Feed
Liquid Animal Feed Market benefits from increasing livestock numbers across dairy, poultry, and swine sectors. Farmers are prioritizing nutrient-rich feed to enhance growth performance and production output. The ease of absorption in liquid feeds improves animal health and feed conversion rates. Molasses-based supplements remain popular due to their palatability and energy density. The growing demand for sustainable animal protein sources supports the feed industry’s evolution. Governments are promoting efficient feed practices to boost productivity. Livestock owners seek cost-effective and nutrient-balanced products. It continues to gain traction among intensive livestock farms globally.
- For example, Cargill Incorporated developed the SilvAir™ nutritional solution that reduces enteric methane production by up to 10 % while maintaining performance in cattle. It also launched the Reach4Reduction™ initiative offering farmers a framework to integrate emissions-reduction strategies linked to feed and nutrition.
Growing Awareness of Feed Efficiency and Animal Health Management
Feed efficiency plays a vital role in achieving profitability and sustainability in livestock farming. The Liquid Animal Feed Market is expanding as producers focus on performance optimization and disease prevention. Nutrient-enriched formulations reduce feed waste while maintaining balanced animal diets. Liquid supplements allow precise nutrient delivery and faster digestion. Rising awareness of gut health and immunity in animals increases the adoption of fortified feed solutions. Manufacturers invest in R&D to create protein and amino acid blends that enhance growth. Improved livestock performance helps reduce antibiotic dependency. It promotes animal welfare and long-term productivity improvements.
- For instance, feed additives containing Lactiplantibacillus plantarum strains DSM 18112, DSM 18113, and DSM 18114 were officially evaluated by the European Food Safety Authority (EFSA) in 2025. The EFSA assessment, published on PubMed Central, confirmed their safety and functional use as silage additives for all animal species, supporting improved fermentation quality and feed preservation.
Technological Advancements in Feed Processing and Formulation
Modern feed processing technologies are reshaping the production of liquid animal feed. The Liquid Animal Feed Market benefits from automation, precision mixing, and real-time nutrient tracking. These innovations ensure consistent quality and optimized nutrient profiles. Companies are integrating digital monitoring systems for improved traceability and performance analysis. Advanced emulsifiers and stabilizers enhance feed shelf life and nutritional retention. Feed manufacturers are leveraging biotechnology to enhance protein synthesis and digestibility. Continuous improvements in formulation methods reduce material loss and energy consumption. It supports scalable, high-efficiency feed production across commercial farms.
Shift Toward Sustainable and Cost-Effective Livestock Nutrition
Sustainability in feed production is becoming a strategic priority for producers and regulators. The Liquid Animal Feed Market supports this shift by promoting low-waste, energy-efficient feeding systems. The use of co-products such as molasses and condensed distillers solubles enhances circular economy practices. Manufacturers adopt eco-friendly ingredients that reduce environmental footprints. Cost efficiency is achieved through flexible formulation and easy on-site blending. Farmers increasingly prefer liquid feeds that simplify handling and storage. This trend reduces packaging waste and transportation emissions. It strengthens the position of liquid feed as a sustainable alternative to dry feed products.
Market Trends
Integration of Smart Farming and Digital Feed Monitoring Systems
Smart farming adoption drives innovation in livestock nutrition and feeding practices. The Liquid Animal Feed Market benefits from IoT-enabled sensors that track consumption patterns and nutrient intake. Real-time monitoring helps farmers maintain feed consistency and efficiency. Predictive analytics tools identify nutrient deficiencies early, optimizing feed ratios. Automation in mixing and dispensing systems minimizes manual errors. Data-driven insights improve herd health and production outcomes. Integration with farm management software enhances operational control. It enables precision feeding strategies for improved yield and profitability.
- For instance, BinSentry, in collaboration with Soracom, deployed IoT-enabled sensors across over 40,000 feed bins in 2025, capturing more than 500,000 real-time consumption data points daily. The deployment, reported by IoT World Today and Soracom’s official releases, helps livestock producers in North America and Europe optimize feed delivery and minimize manual tracking errors.
Increasing Use of By-Products and Natural Ingredients in Feed Formulation
Feed manufacturers are turning to agricultural and food industry by-products to enhance sustainability. The Liquid Animal Feed Market embraces molasses, corn steep liquor, and glycerin as valuable feed inputs. These materials improve palatability and energy content while reducing waste. Natural additives such as herbal extracts and enzymes support digestion and immunity. Farmers prefer eco-friendly and non-GMO formulations that align with consumer expectations. Innovation in fermentation technologies enhances ingredient bioavailability. The trend also supports compliance with green certification standards. It encourages resource-efficient feed production across regions.
Expansion of Livestock Integration and Contract Farming Models
Integrated livestock production models are influencing global feed demand patterns. The Liquid Animal Feed Market grows as vertically integrated farms standardize feeding protocols. Large producers secure consistent supply through contract manufacturing partnerships. This integration ensures quality control and cost efficiency. Collaboration between feed producers and livestock farmers improves nutrient management. Enhanced supply chain coordination reduces inventory losses. Contract farming promotes consistent feed quality and traceability. It establishes reliable distribution networks for large-scale liquid feed adoption.
- For instance, Smithfield Foods operates one of the largest integrated pork production systems globally, with most hogs raised under long-term grower contracts. This integrated model allows consistent feed quality control and efficient resource management across its production network, as documented in Smithfield’s sustainability disclosures and USDA livestock contracting reports.
Growing Preference for Customized and Species-Specific Feed Solutions
Demand for tailored nutritional programs is reshaping product development strategies. The Liquid Animal Feed Market supports precision nutrition targeting cattle, poultry, and swine needs. Custom formulations help meet productivity goals across varied farm environments. Companies develop feed blends with optimal amino acid, vitamin, and mineral ratios. Personalized feeding solutions improve conversion efficiency and reduce waste. This customization trend attracts both small and large-scale farmers. Data analytics and laboratory testing enhance formulation accuracy. It ensures species-specific performance improvement across different production stages.
Market Challenges Analysis
Fluctuating Raw Material Prices and Supply Chain Constraints
Volatile raw material prices affect production costs for feed manufacturers. The Liquid Animal Feed Market faces margin pressure due to dependence on molasses, corn, and oilseed by-products. Disruptions in global trade and transportation raise procurement risks. Seasonal variations in crop yields limit ingredient availability. Feed producers struggle to maintain consistent quality under fluctuating input costs. Small-scale farmers face affordability issues during high-cost cycles. Supply chain interruptions can delay distribution and impact product freshness. It challenges manufacturers to stabilize pricing and ensure uninterrupted supply.
Regulatory Compliance and Product Standardization Issues
Strict regulations on feed additives and safety limit product formulation flexibility. The Liquid Animal Feed Market must comply with labeling, quality testing, and residue control standards. Differences in regional policies increase complexity for exporters. Compliance costs rise with frequent updates in feed ingredient guidelines. Maintaining uniformity across international markets becomes difficult for global producers. Lack of awareness among small manufacturers results in inconsistent quality output. Certification procedures delay market entry for new formulations. It increases operational burden and slows product innovation cycles.
Market Opportunities
Rising Demand for Protein-Rich Diets and Efficient Feed Systems
Global demand for high-quality animal protein continues to expand. The Liquid Animal Feed Market can capitalize on this through advanced protein-based feed formulations. Efficient feeding systems improve digestibility and reduce waste. Growth in meat, dairy, and aquaculture sectors creates consistent opportunities. Nutrient-rich liquid feed supports faster animal weight gain and reproductive health. Adoption among developing economies accelerates due to rising income levels. Feed companies investing in amino acid research gain a competitive edge. It paves the way for long-term expansion in the livestock nutrition sector.
Expansion in Emerging Markets and Product Diversification
Emerging economies present new opportunities for liquid feed adoption. The Liquid Animal Feed Market benefits from industrial livestock farming expansion in Asia Pacific, Africa, and Latin America. Farmers seek innovative and cost-efficient feeding methods. Growing awareness of feed efficiency drives adoption of fortified solutions. Manufacturers diversify offerings through probiotic, mineral, and enzyme-based variants. Strategic alliances with local distributors help expand regional presence. Evolving dietary preferences boost livestock sector investments. It strengthens market prospects and supports global product penetration.
Market Segmentation Analysis:
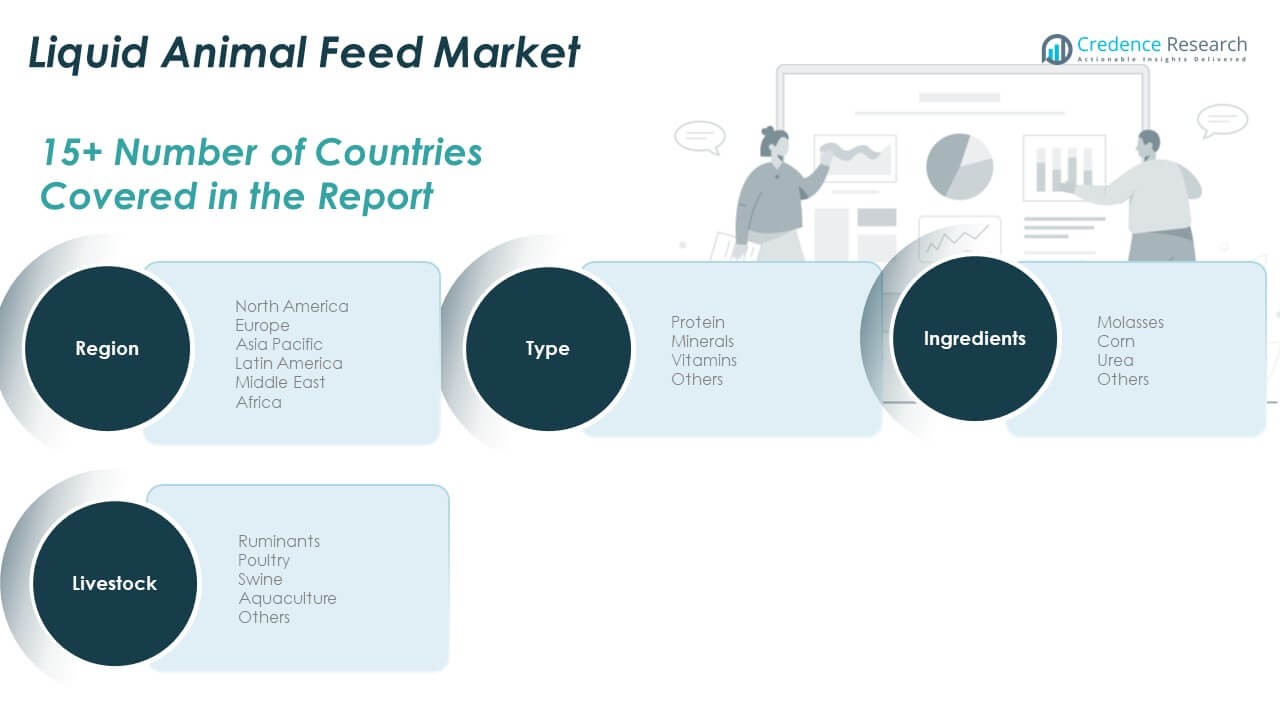
The Liquid Animal Feed Market is segmented by type, ingredients, and livestock, reflecting its diverse application across global animal nutrition systems.
By type, protein-based feed dominates due to its critical role in muscle growth and milk production. High-protein formulations support better feed conversion ratios and overall animal performance. Mineral and vitamin segments also hold strong positions, meeting essential dietary requirements that improve metabolism and immunity. The others segment includes additives that enhance feed palatability and nutrient absorption, supporting farm productivity.
By ingredients, molasses leads the segment due to its affordability, energy content, and blending compatibility. It serves as a base for most liquid feed formulations. Corn follows closely, valued for its carbohydrate richness that promotes growth and energy supply. Urea contributes as a non-protein nitrogen source, improving protein synthesis in ruminants. The others segment includes glycerin and by-products, offering flexibility and cost efficiency.
- For instance, Westway Feed Products documented in field trials that its RumaWAY® LAUNCH molasses-based liquid feed supplement increased dry matter intake (DMI) by 2–4 lbs in pre-fresh cows due to enhanced palatability. The supplement supports more consistent feed intake and improved transition health before calving, as reported in Westway’s official product data.
By livestock, ruminants represent the largest share, driven by strong demand from dairy and beef producers. Poultry shows rapid adoption supported by modern feed management practices and nutrient-focused formulations. Swine and aquaculture segments are expanding due to higher protein needs and efficient feed conversion. The others category covers goats, sheep, and niche livestock where liquid feed adoption is rising. It continues to gain momentum across all livestock categories, driven by the need for cost-efficient, high-performance feeding solutions that enhance productivity and sustainability.
- For instance, De Heus Animal Nutrition reported measurable improvements in milk yield and feed efficiency in dairy cows through its optimized feeding programs. According to the company’s documented trials, higher concentrate rations and balanced nutrient formulations have enhanced milk protein content and overall production performance in commercial dairy operations.
Segmentation:
By Type
- Protein
- Minerals
- Vitamins
- Others
By Ingredients
- Molasses
- Corn
- Urea
- Others
By Livestock
- Ruminants
- Poultry
- Swine
- Aquaculture
- Others
By Region
- North America (U.S., Canada, Mexico)
- Europe (UK, France, Germany, Italy, Spain, Russia, Rest of Europe)
- Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia, Rest of Asia Pacific)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East (GCC Countries, Israel, Turkey, Rest of Middle East)
- Africa (South Africa, Egypt, Rest of Africa)
Regional Analysis:
North America
The North America Liquid Animal Feed Market size was valued at USD 13,087.20 million in 2018 to USD 15,408.25 million in 2024 and is anticipated to reach USD 23,657.37 million by 2032, at a CAGR of 5.6% during the forecast period. North America holds a 27.4% share of the global market, supported by strong livestock farming and advanced feed technologies. The U.S. leads due to high dairy and beef production coupled with large-scale adoption of precision feeding. Canada and Mexico show steady growth driven by rising poultry and swine industries. Technological adoption in feed formulation and farm automation strengthens market presence. Sustainable and nutrient-efficient feed production remains a regional focus. It benefits from strong regulatory frameworks and high investments in animal nutrition research. The region’s established agribusiness infrastructure ensures consistent liquid feed supply and distribution.
Europe
The Europe Liquid Animal Feed Market size was valued at USD 12,608.40 million in 2018 to USD 14,518.34 million in 2024 and is anticipated to reach USD 21,154.19 million by 2032, at a CAGR of 4.9% during the forecast period. Europe accounts for a 24.5% share, supported by well-developed dairy and swine industries. Germany, France, and the Netherlands lead adoption due to advanced livestock management systems. Strict EU feed regulations encourage innovation in safe and traceable formulations. Growth is driven by a preference for high-quality animal nutrition and sustainable practices. The market benefits from strong demand for molasses-based and vitamin-enriched feeds. R&D initiatives in alternative proteins and bio-based ingredients create new opportunities. It continues to expand through modernization and integration of automated feed blending technologies.
Asia Pacific
The Asia Pacific Liquid Animal Feed Market size was valued at USD 15,276.00 million in 2018 to USD 18,857.01 million in 2024 and is anticipated to reach USD 31,221.56 million by 2032, at a CAGR of 6.5% during the forecast period. Asia Pacific leads with a 35.3% share, driven by rapid expansion in dairy, poultry, and aquaculture sectors. China and India are key contributors due to population growth and protein consumption rise. Feed manufacturers focus on cost-effective and high-yield formulations to support large-scale farming. Strong government initiatives promoting livestock productivity drive market growth. Japan, South Korea, and Southeast Asia witness adoption of advanced feed technologies. Urbanization and demand for processed animal products sustain long-term growth. It continues to gain momentum through regional feed integration and expanding agribusiness investments.
Latin America
The Latin America Liquid Animal Feed Market size was valued at USD 2,781.60 million in 2018 to USD 3,292.72 million in 2024 and is anticipated to reach USD 4,685.32 million by 2032, at a CAGR of 4.6% during the forecast period. Latin America holds a 7.1% share, supported by growth in cattle and poultry sectors. Brazil leads the market with its large-scale livestock exports and feed production capabilities. Argentina and Mexico also contribute through expanding dairy and meat industries. Increasing adoption of nutrient-rich feed and modernization of farming practices enhance efficiency. Feed producers emphasize cost-effective and energy-dense formulations suitable for tropical conditions. Government focus on agricultural exports supports feed manufacturing investments. It remains a key growth region due to improving farm mechanization and feed quality standards.
Middle East
The Middle East Liquid Animal Feed Market size was valued at USD 1,094.40 million in 2018 to USD 1,177.37 million in 2024 and is anticipated to reach USD 1,518.35 million by 2032, at a CAGR of 3.3% during the forecast period. The region represents a 3.0% share, driven by growing poultry and dairy production in GCC countries. Feed imports dominate due to limited domestic grain supply. The market benefits from rising investments in modern livestock infrastructure and food security programs. Saudi Arabia and the UAE lead adoption through government-backed initiatives promoting self-sufficiency. Demand for molasses-based and fortified feeds supports nutritional efficiency. Regional players focus on partnerships with global feed producers to reduce dependency. It continues to evolve through sustainable feed innovations and localized formulation efforts.
Africa
The Africa Liquid Animal Feed Market size was valued at USD 752.40 million in 2018 to USD 1,270.64 million in 2024 and is anticipated to reach USD 1,624.33 million by 2032, at a CAGR of 2.6% during the forecast period. Africa holds a 2.7% share, with South Africa leading in dairy and poultry feed production. Feed adoption remains low in rural regions due to limited infrastructure and awareness. Growth is emerging in Nigeria, Kenya, and Egypt, supported by government livestock initiatives. Local feed manufacturers are exploring cost-effective raw materials to improve affordability. Urban population growth and demand for animal protein drive gradual market expansion. Global feed companies are entering through joint ventures and training programs. It is steadily developing with focus on improving feed quality and nutrient balance across the continent.
Key Player Analysis:
- Cargill Incorporated
- Archer Daniels Midland Company (ADM)
- Land O’Lakes, Inc.
- Double S Liquid Feed Services, Inc.
- Foster Farms
- Midwest Liquid Feeds
- Alliance Liquid Feeds Inc.
- Performance Seeds LLC
- Quality Liquid Feeds Inc.
- Westway Feed Products LLC
- BASF SE
- DLG Group
- GrainCorp Limited
- Ridley Corporation
- Masterfeeds LP
- Alltech Inc.
- Sugar Corporation of Malawi Limited
- Industrias Bachoco S.A.B. de C.V.
Competitive Analysis:
The Liquid Animal Feed Market is characterized by strong competition among global and regional producers focusing on product innovation, nutrient efficiency, and sustainability. Leading companies such as Cargill Incorporated, Archer Daniels Midland Company (ADM), Land O’Lakes, Inc., and BASF SE invest heavily in R&D to enhance feed formulations and production efficiency. Mid-sized firms like Quality Liquid Feeds Inc. and Westway Feed Products LLC strengthen their presence through partnerships and distribution expansion. Companies are adopting advanced blending technologies and digital monitoring to ensure consistent quality. Strategic mergers, acquisitions, and ingredient diversification support market consolidation. It emphasizes tailored solutions for livestock nutrition, with manufacturers prioritizing customized protein, mineral, and vitamin blends. Growing focus on cost optimization and sustainable sourcing practices enhances competitiveness among key market participants.
Recent Developments:
- In October 2025, Cargill launched a new line of plant-based feed additives for poultry and swine which feature natural compounds designed to improve gut health and feed conversion rates. This product launch comes at a time when the liquid animal feed market is increasingly focused on sustainability and animal welfare, aligning Cargill's portfolio with industry trends favoring environmentally-friendly feed solutions as well as efficient nutrition delivery systems for livestock producers.
- In September 2025, Archer Daniels Midland Company (ADM) and Alltech Inc. announced a significant joint venture focused on the North American animal feed market. This partnership aims to combine ADM's animal feed business with Alltech's Hubbard Feeds and Masterfeeds, operating a total of 44 feed mills across the U.S. and Canada.
- In February 2025, Zoetis finalized a deal to sell its medicated-feed-additive portfolio to Phibro Animal Health for $350 million. With this transaction, Zoetis aims to concentrate its resources on vaccines and biologics, while Phibro expands its presence in the feed additive and liquid animal feed space, enhancing its product offerings and reach in livestock nutrition.
Report Coverage:
The research report offers an in-depth analysis based on Type, Ingredients and Livestock. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for nutrient-rich feed solutions will strengthen due to rising livestock productivity goals worldwide.
- Adoption of digital feed monitoring and precision nutrition systems will enhance formulation accuracy.
- Expansion in aquaculture and poultry sectors will drive continuous demand for liquid feed products.
- Sustainable feed practices using co-products and natural ingredients will shape future product strategies.
- Collaborations between feed producers and livestock farms will improve supply chain integration.
- Technological advancements in enzyme and amino acid blends will improve feed conversion efficiency.
- Emerging economies will witness rising feed adoption supported by modernization of animal farming.
- Manufacturers will invest in automated blending and storage systems to maintain consistent quality.
- Regulatory focus on traceable, eco-friendly feed formulations will accelerate innovation in product development.
- It will continue to evolve through strong R&D investments and partnerships targeting performance-driven livestock nutrition.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Livestock Population and Demand for Nutrient-Enriched Feed
Increasing numbers of dairy, poultry, and swine livestock are driving the need for nutrient-rich liquid feeds that enhance growth, productivity, and animal health. Liquid formulations offer improved digestibility and feed conversion, making them attractive for intensive farming operations.
Growing Awareness of Feed Efficiency and Animal Health Management
Producers are prioritizing feed efficiency and animal health, adopting liquid feeds that enable precise nutrient delivery, reduce waste, and support gut health. This trend is reinforced by the need to optimize production costs and reduce antibiotic use through better nutrition.
Technological Advancements in Feed Processing and Formulation
Automation, precision mixing, and digital monitoring systems are enabling consistent quality and optimized nutrient profiles in liquid animal feed. These innovations support scalable production, traceability, and improved performance analysis for commercial farms.
Shift Toward Sustainable and Cost-Effective Livestock Nutrition
The use of co-products like molasses and condensed distillers solubles in liquid feeds supports circular economy practices and reduces environmental impact. Farmers are increasingly adopting liquid feeds for their cost efficiency, ease of handling, and contribution to sustainable livestock production.
Expansion in Emerging Markets and Product Diversification
Rapid growth in industrial livestock farming in Asia Pacific, Africa, and Latin America is creating new opportunities for liquid feed adoption. Manufacturers are diversifying their product portfolios with protein, mineral, and enzyme-based variants to meet evolving nutritional needs and regional preferences.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Liquid Animal Feed Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Liquid Animal Feed Market projected to grow between 2024 and 2032?
Which Liquid Animal Feed Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Liquid Animal Feed Market?
Who are the leading companies in the Liquid Animal Feed Market?
Which region commanded the largest share of the Liquid Animal Feed Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Protein
- 1.2.2 Minerals
- 1.2.3 Vitamins
- 1.2.4 Others
- 1.3 By Livestock
- 1.3.1 Ruminants
- 1.3.2 Poultry
- 1.3.3 Swine
- 1.3.4 Aquaculture
- 1.3.5 Others
- 1.4 By Ingredients
- 1.4.1 Molasses
- 1.4.2 Corn
- 1.4.3 Urea
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 54,524.34 million → 2032: USD 83,861.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Liquid Animal Feed Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Liquid Animal Feed Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Liquid Animal Feed Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Liquid Animal Feed Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Liquid Animal Feed Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Liquid Animal Feed Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Liquid Animal Feed Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Liquid Animal Feed Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 54,524.34 million → 2032: USD 83,861.12 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Liquid Animal Feed Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Protein
- 12.3.7.2 Minerals
- 12.3.7.3 Vitamins
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Livestock - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ruminants
- 12.4.7.2 Poultry
- 12.4.7.3 Swine
- 12.4.7.4 Aquaculture
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Ingredients - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Molasses
- 12.5.7.2 Corn
- 12.5.7.3 Urea
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Liquid Animal Feed Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Liquid Animal Feed Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Liquid Animal Feed Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Cargill Incorporated
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Archer Daniels Midland Company (ADM)
- 17.4 Land O’Lakes, Inc.
- 17.5 BASF SE
- 17.6 Westway Feed Products LLC
- 17.7 Quality Liquid Feeds Inc.
- 17.8 Alltech Inc.
- 17.9 Ridley Corporation
- 17.10 GrainCorp Limited
- 17.11 DLG Group
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

