
Market Overview
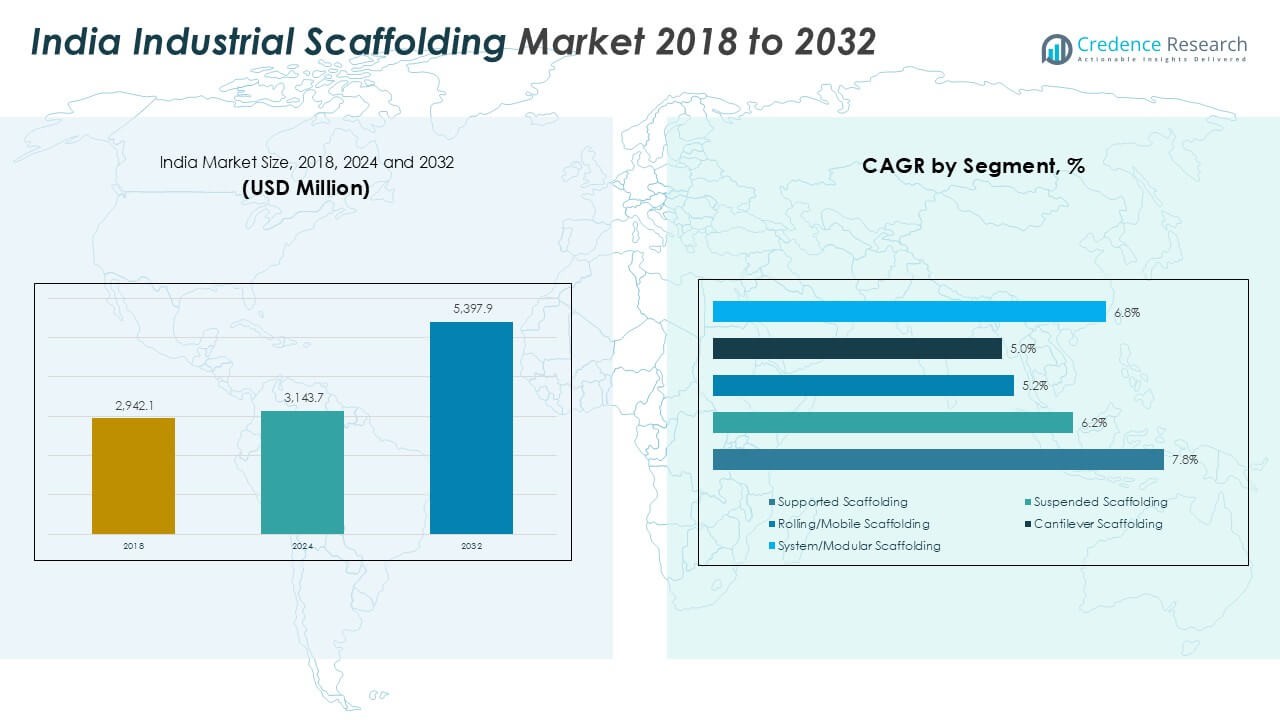
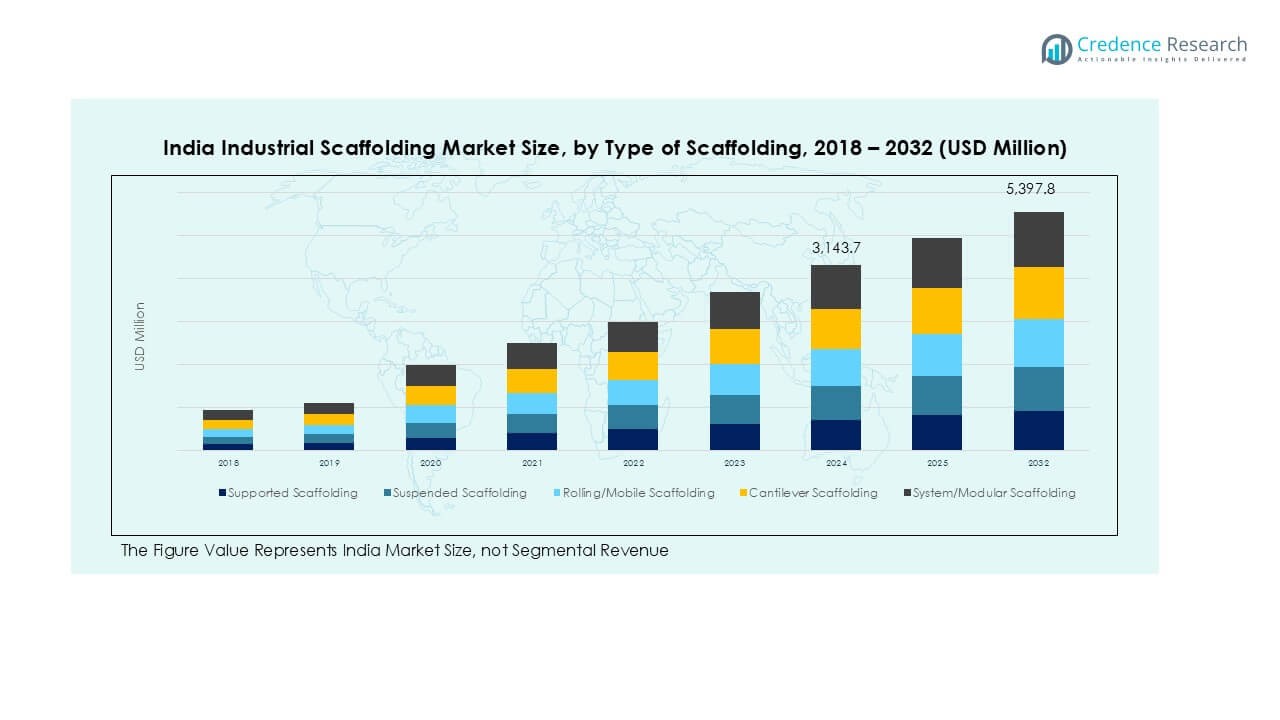
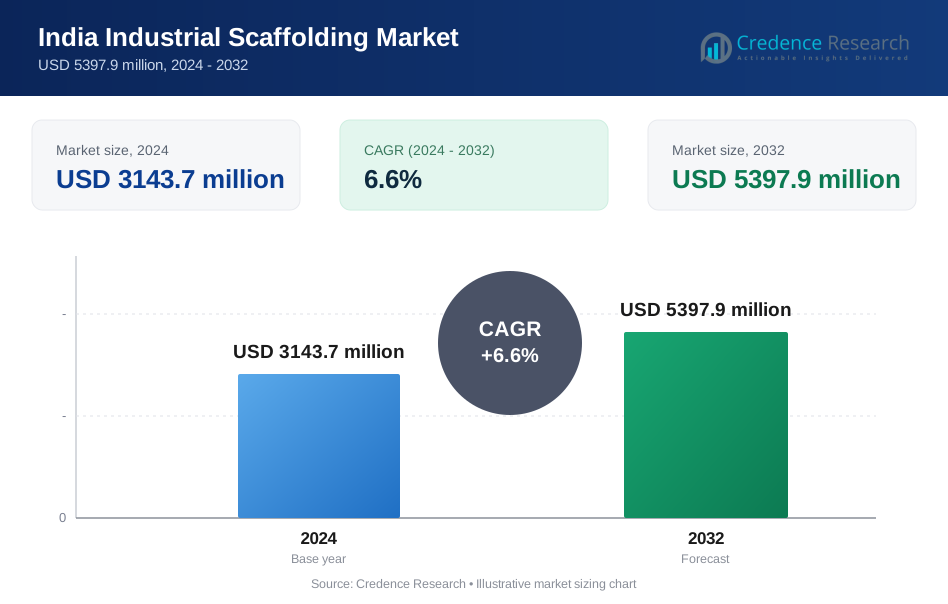
India Industrial Scaffolding market size was valued at USD 2942.1 million in 2018 to USD 3143.7 million in 2024 and is anticipated to reach USD 5397.9 million by 2032, at a CAGR of 6.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Industrial Scaffolding Market Size 2024 | USD 3143.7 Million |
| India Industrial Scaffolding Market, CAGR | 6.6% |
| India Industrial Scaffolding Market Size 2032 | USD 5397.9 Million |
The India industrial scaffolding market is shaped by key players such as Aarvi Scaffolding, Shiv Shakti Scaffolding, BSL Scaffolding Ltd, Utkarsh Scaffolding, Layher India, PERI India, ULMA Construction, and Shreeji Scaffolding. These companies compete through product innovation, strong rental networks, and adherence to global safety standards. Layher India and PERI India lead in modular and system scaffolding solutions, catering to large-scale industrial and infrastructure projects. Regionally, North India dominates the market with a 35% share, driven by metro rail, refinery, and power plant projects, followed by West India at 28% and South India at 22%, reflecting strong industrial growth.
Market Insights
- India Industrial Scaffolding market was valued at USD 3143.7 million in 2024 and is projected to reach USD 5397.9 million by 2032, growing at a CAGR of 6.6%.
- Market growth is driven by rising infrastructure projects, industrial expansion, and stricter workplace safety regulations increasing demand for reliable scaffolding systems.
- Trends include adoption of modular and lightweight scaffolding solutions, faster assembly systems, and use of digital monitoring for safety and efficiency during plant maintenance.
- The market is moderately fragmented with key players like Aarvi Scaffolding, Layher India, PERI India, and ULMA Construction focusing on rental services, safety compliance, and turnkey project solutions.
- North India holds 35% share, followed by West India at 28%, South India at 22%, and East India at 15%; supported scaffolding dominates with over 40% share, driven by stability and heavy-load applications across oil & gas, power generation, and large-scale infrastructure projects.
Market Segmentation Analysis:
By Type of Scaffolding
Supported scaffolding holds the dominant share in the India industrial scaffolding market, accounting for over 40% of total demand in 2024. Its popularity stems from its high load-bearing capacity, stability, and suitability for heavy-duty industrial projects. This type is extensively used in large-scale infrastructure and plant maintenance activities. System/modular scaffolding is gaining traction due to faster assembly and enhanced safety features, especially in time-critical shutdown projects. Growing investments in infrastructure upgrades and strict safety regulations drive adoption of reliable and easy-to-install scaffolding solutions across industrial facilities.
- For instance, Layher India supplies its Allround modular system, which is generally known to be faster to erect than conventional tube-and-coupler systems. While Layher has completed projects in industrial settings in India and its systems are used in refineries.
By Application
The oil & gas industry leads the application segment, capturing nearly 35% market share in 2024. Frequent maintenance, inspection, and shutdown activities in refineries and offshore facilities drive strong demand for scaffolding solutions. Power generation, including thermal and hydro plants, represents the second-largest share, supported by ongoing plant expansions and modernization projects. Mining and metallurgy operations also contribute significantly due to the need for access solutions in material handling and smelting units. The demand is driven by India’s industrial growth, increasing capital expenditure, and focus on worker safety standards.
- For instance, Cuplok Scaffolding India supported Vedanta’s Lanjigarh alumina refinery expansion with over 60,000 scaffold fittings, facilitating work on high-elevation material conveyors.
By Material
Steel dominates the material segment with over 60% share in 2024, owing to its strength, durability, and ability to handle heavy industrial loads. Steel scaffolding remains the preferred choice for complex, high-rise, and long-term projects across oil & gas, power, and chemical sectors. Aluminum is witnessing rising adoption due to its lightweight properties, making it ideal for quick assembly and disassembly during short maintenance cycles. Fiberglass/composite scaffolding is used in chemical plants where corrosion resistance is critical. Increasing emphasis on safety, reusability, and cost efficiency supports strong growth for steel-based systems.
Key Growth Drivers
Expanding Infrastructure and Industrial Projects
India’s rapid infrastructure development is a major growth driver for the industrial scaffolding market. Expansion of oil refineries, metro projects, power plants, and manufacturing facilities creates strong demand for access solutions. Scaffolding is essential for construction, maintenance, and periodic shutdowns across these sectors. Government initiatives like “Make in India” and large-scale infrastructure spending further boost project pipelines. Industrial growth and modernization programs in sectors such as steel, cement, and petrochemicals increase the frequency of scaffolding use, driving consistent demand throughout the forecast period.
- For instance, a scaffolding provider, potentially including a past entity known as Harsco Infrastructure, would have supplied a large quantity of scaffolding, potentially over 100,000 m², for a refinery shutdown at the Bharat Petroleum Kochi refinery.
Rising Focus on Worker Safety and Compliance
Stringent workplace safety regulations are pushing industries to adopt reliable scaffolding systems. Compliance with occupational safety standards requires certified, stable, and high-quality access equipment. Companies are increasingly replacing makeshift and unsafe scaffolds with modular, engineered systems that meet global safety norms. Regular audits and penalties for non-compliance encourage investment in durable solutions. This focus improves operational efficiency and reduces accident risks, leading to higher adoption of advanced scaffolding products across oil & gas, power, and chemical industries in India.
- For instance, Aluma Systems India introduced lightweight aluminum scaffold systems at Indian Oil's Panipat refinery, reportedly reducing manual handling strain by 30% for over 500 workers.
Growth in Maintenance and Shutdown Activities
Periodic maintenance and plant shutdowns represent a key demand source for scaffolding solutions. Industries such as oil & gas, power generation, and mining rely on scaffolding for inspection, repair, and retrofitting activities. The rising number of brownfield projects and plant overhauls boosts demand for temporary access structures. Quick-assembly system scaffolding is increasingly preferred due to its ability to reduce downtime and labor costs. The growing emphasis on maintaining operational efficiency in aging industrial facilities continues to sustain the market for industrial scaffolding services.
Key Trend
Adoption of Modular and Lightweight Scaffolding
The market is witnessing a shift toward modular and lightweight scaffolding systems. These solutions offer faster installation, enhanced safety, and reduced labor requirements. Aluminum and composite scaffolding are gaining popularity for projects with frequent assembly-disassembly needs. Modular systems also enable flexible configurations to suit complex plant layouts, improving efficiency during shutdown projects. This trend aligns with industry demands for time savings, cost optimization, and compliance with safety standards, driving adoption across diverse sectors including power, petrochemicals, and infrastructure development.
- For instance, Layher introduced its Allround Lightweight system, whose components weigh significantly less and allow for faster assembly compared to older systems. The company reports an overall assembly speed increase of up to 10%.
Digitalization and Smart Monitoring Solutions
Digital transformation is creating opportunities in the industrial scaffolding market through smart monitoring systems. Integration of IoT-enabled sensors and software platforms allows real-time tracking of scaffold usage, load conditions, and worker movement. This improves safety compliance and reduces risks of collapse or misuse. Digital project management tools also streamline planning, inventory control, and workforce coordination, cutting operational costs. Companies investing in technology-driven scaffolding solutions can differentiate themselves and cater to large-scale industrial clients seeking efficiency and predictive maintenance capabilities.
- For instance, Datadog supports companies monitoring their IoT fleets with dashboards covering tens of thousands of devices, aggregating metrics across device hardware, logs, and network performance.
Key Challenge
High Initial Investment and Rental Costs
The high upfront cost of advanced scaffolding systems is a major barrier for small and medium contractors. Modular and system scaffolding require significant capital investment compared to conventional methods. Rental prices can also be high, particularly for long-term projects or specialized configurations. Budget constraints in smaller projects may limit adoption, leading contractors to use unsafe or improvised solutions. Price sensitivity in the Indian market continues to challenge suppliers, necessitating flexible pricing models and rental options to support wider adoption.
Skilled Labor Shortages and Training Needs
Shortage of skilled scaffolders and inadequate training programs hinder efficient deployment of advanced scaffolding systems. Proper erection, inspection, and dismantling require trained personnel to ensure safety and compliance with regulations. Lack of skilled labor increases the risk of workplace accidents and project delays. Training costs and time requirements add to operational challenges for contractors and plant operators. The industry needs structured certification programs and partnerships to build a competent workforce capable of handling complex scaffolding solutions effectively.
Regional Analysis
North India
North India holds the largest share of the India industrial scaffolding market, accounting for around 35% in 2024. The dominance is driven by extensive infrastructure projects, including metro rail expansions, highways, and industrial corridors such as the Delhi-Mumbai Industrial Corridor (DMIC). The region hosts several large-scale power plants, oil refineries, and manufacturing hubs, which generate consistent demand for scaffolding during construction and maintenance. The presence of major public sector enterprises and government-led development programs further supports market growth. Frequent plant shutdowns and maintenance activities in Uttar Pradesh, Haryana, and Rajasthan also contribute significantly to scaffolding demand.
West India
West India captures approximately 28% of the market share, driven by its concentration of petrochemical complexes, ports, and power plants. States like Maharashtra and Gujarat are major industrial hubs with significant refinery, chemical, and manufacturing operations requiring extensive scaffolding services. Ongoing investments in renewable energy projects and smart city developments are fueling growth in the region. High industrial activity in areas like Jamnagar and Hazira, coupled with frequent turnaround maintenance schedules, creates robust demand. The region benefits from the presence of leading scaffolding suppliers and a strong rental network that supports timely project execution and shutdown activities.
South India
South India accounts for nearly 22% of the industrial scaffolding market share in 2024. The region’s demand is fueled by strong growth in the construction, power, and manufacturing sectors across Tamil Nadu, Karnataka, and Andhra Pradesh. Large-scale thermal and hydroelectric power plants, along with port development projects, create continuous scaffolding requirements. The presence of automotive and electronics manufacturing clusters increases usage for plant expansions and maintenance. Government-backed infrastructure initiatives, such as Chennai Metro Phase 2 and Vizag Industrial Corridor, contribute to demand. Growing investments in renewable energy and industrial automation are expected to further strengthen market growth.
East India
East India represents around 15% of the market share, with demand largely concentrated in steel, mining, and heavy engineering sectors. States like Odisha, Jharkhand, and West Bengal host major steel plants and mining operations, which rely heavily on scaffolding for construction and equipment maintenance. The region is witnessing infrastructure development, including new road and railway projects, boosting demand for temporary access solutions. However, compared to other regions, adoption of modular scaffolding remains limited, leaving room for modernization. Increased government focus on industrial corridor development and port connectivity projects is expected to gradually drive market penetration in coming years.
Market Segmentations:
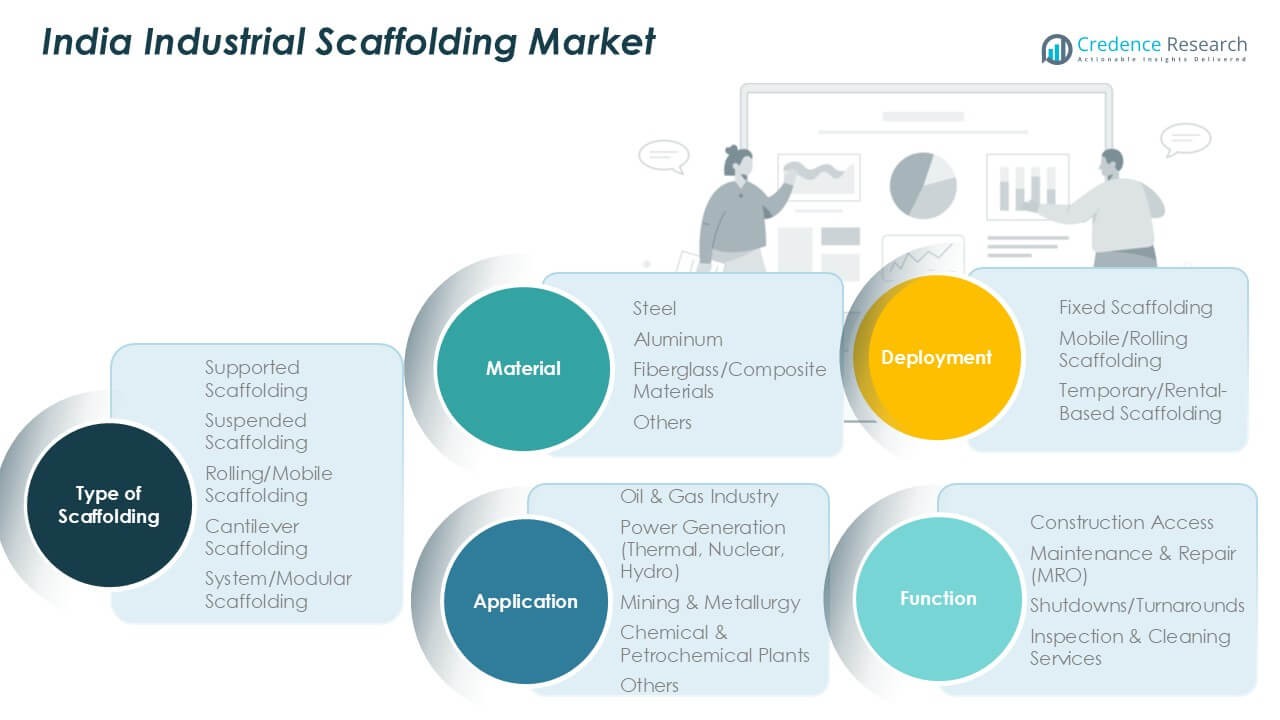
By Type of Scaffolding
- Supported Scaffolding
- Suspended Scaffolding
- Rolling/Mobile Scaffolding
- Cantilever Scaffolding
- System/Modular Scaffolding
By Application
- Oil & Gas Industry
- Power Generation (Thermal, Nuclear, Hydro)
- Mining & Metallurgy
- Chemical & Petrochemical Plants
- Others
By Material
- Steel
- Aluminum
- Fiberglass/Composite Materials
- Others
By Deployment
- Fixed Scaffolding
- Mobile/Rolling Scaffolding
- Temporary/Rental-Based Scaffolding
By Function
- Construction Access
- Maintenance & Repair (MRO)
- Shutdowns/Turnarounds
- Inspection & Cleaning Services
By Geography
- North India
- West India
- South India
- East India
Competitive Landscape
The India industrial scaffolding market is moderately fragmented, with a mix of domestic manufacturers, rental service providers, and global players competing for market share. Key companies include Aarvi Scaffolding, Shiv Shakti Scaffolding, BSL Scaffolding Ltd, Utkarsh Scaffolding, Layher India, PERI India, and ULMA Construction. Domestic players focus on cost-effective solutions and wide rental networks to cater to local demand, while international companies emphasize modular and engineered systems with advanced safety features. Competition is driven by pricing, product durability, compliance with safety standards, and timely project delivery. Partnerships with EPC contractors and plant operators are common strategies to secure long-term contracts. Growing demand for system scaffolding and turnkey solutions encourages players to invest in product innovation and workforce training. The market is expected to see increased consolidation, with mergers and collaborations likely as companies seek to expand their geographic reach and service capabilities across India’s industrial hubs.
Key Player Analysis
- Aarvi Scaffolding
- Shiv Shakti Scaffolding
- BSL Scaffolding Ltd
- Siddhivinayak Scaffolding
- Tirupati Scaffolding
- Utkarsh Scaffolding
- Layher India
- PERI India
- ULMA Construction
- Shreeji Scaffolding
Recent Developments
- In July 2022, A major developer and provider of formwork and scaffolding systems, PERI Formwork Systems, Inc., has developed what would become a new industry standard for bridge construction. VPS ensures a safety and efficiency gap through a highly versatile system that is adjustable, rentable, and productive in forming bridge columns and caps.
- In July 2022, Doka, a key player in formwork solutions and services to the construction industry has taken its collaboration with the well-known American scaffolding company AT-PAC to the next level by making a significant investment in the US-based firm. The two companies first teamed up in 2020 to offer comprehensive solutions for building sites, and their partnership has only grown stronger since then.
- In July 2022, A Glasgow subsidiary named StepUp Scaffold UK from StepUp Scaffold Group in Memphis has completed the purchase of MP House ApS located near Copenhagen during July 2022. The company MP House stands as the dominant supplier of tools and equipment along with accessories to scaffolding operators based in Denmark.
- In April 2022, Layher Holding GmbH Co KG has introduced the Allround Scaffold, a name that reflects the company and perhaps represents the pinnacle of modular scaffolding solutions. The Modular Scaffolding System is essentially the Layher Allround Scaffolding. This system is comparable to Allround Performance, as it serves multiple purposes within a single framework. No matter how complex the designs, architectural styles, or strict safety standards may be, Allround Scaffolding consistently proves to be the quicker, safer, and more economical choice.
Report Coverage
The research report offers an in-depth analysis based on Type of Scaffolding, Application, Material, Deployment, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will grow with expansion of oil & gas, power, and infrastructure projects.
- Adoption of modular and system scaffolding will rise for faster installation and safety.
- Rental services will see strong growth due to cost efficiency and flexibility.
- Digital monitoring and IoT-enabled scaffolding management will gain traction.
- Worker safety regulations will drive investment in certified, engineered scaffolding systems.
- Steel scaffolding will maintain dominance, but aluminum and composite use will increase.
- Maintenance and plant shutdown projects will remain key revenue sources.
- Market consolidation is expected as players form partnerships and acquisitions.
- Skilled workforce training programs will become a priority for safe operations.
- Regional demand will remain highest in North and West India, supporting long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Infrastructure and Industrial Projects
India's rapid infrastructure development, including metro rail, refinery, and power plant projects, is driving strong demand for industrial scaffolding. Government initiatives and large-scale investments in construction and manufacturing sectors require extensive scaffolding for both new builds and ongoing maintenance.
Rising Focus on Worker Safety and Compliance
Stricter workplace safety regulations and enforcement of global safety standards are pushing industries to adopt certified, engineered scaffolding systems. This shift from makeshift to modular, compliant solutions is increasing market demand, especially in hazardous sectors like oil & gas and chemicals.
Growth in Maintenance and Shutdown Activities
Frequent maintenance, inspection, and plant shutdowns in industries such as oil & gas, power generation, and mining require reliable scaffolding for safe access. The need for quick-assembly and efficient scaffolding solutions is rising as industrial facilities age and undergo regular overhauls.
Adoption of Modular and Lightweight Scaffolding
The trend toward modular and lightweight scaffolding systems, which offer faster assembly and enhanced safety, is accelerating market growth. These systems are increasingly preferred for time-sensitive projects and are being adopted across sectors seeking efficiency and compliance.
Digitalization and Smart Monitoring Solutions
Integration of IoT-enabled monitoring and digital project management tools is improving safety, operational efficiency, and predictive maintenance in scaffolding operations. This technological advancement is attracting large industrial clients and differentiating suppliers in a competitive market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Industrial Scaffolding market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Industrial Scaffolding market projected to grow between 2025 and 2032?
Which India Industrial Scaffolding market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Industrial Scaffolding market?
Who are the leading companies in the India Industrial Scaffolding market?
Which region commanded the largest share of the India Industrial Scaffolding market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Steel
- 1.2.2 Aluminum
- 1.2.3 Fiberglass/Composite Materials
- 1.2.4 Others
- 1.3 By Application
- 1.3.1 Oil & Gas Industry
- 1.3.2 Power Generation (Thermal, Nuclear, Hydro)
- 1.3.3 Mining & Metallurgy
- 1.3.4 Chemical & Petrochemical Plants
- 1.3.5 Others
- 1.4 By Type of Scaffolding
- 1.4.1 Supported Scaffolding
- 1.4.2 Suspended Scaffolding
- 1.4.3 Rolling/Mobile Scaffolding
- 1.4.4 Cantilever Scaffolding
- 1.4.5 System/Modular Scaffolding
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3143.7 million → 2032: USD 5397.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Industrial Scaffolding Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Industrial Scaffolding Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Industrial Scaffolding Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Industrial Scaffolding Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Industrial Scaffolding Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Industrial Scaffolding Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Industrial Scaffolding Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Industrial Scaffolding Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3143.7 million → 2032: USD 5397.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Industrial Scaffolding Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Steel
- 12.3.7.2 Aluminum
- 12.3.7.3 Fiberglass/Composite Materials
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oil & Gas Industry
- 12.4.7.2 Power Generation (Thermal, Nuclear, Hydro)
- 12.4.7.3 Mining & Metallurgy
- 12.4.7.4 Chemical & Petrochemical Plants
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Scaffolding - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Supported Scaffolding
- 12.5.7.2 Suspended Scaffolding
- 12.5.7.3 Rolling/Mobile Scaffolding
- 12.5.7.4 Cantilever Scaffolding
- 12.5.7.5 System/Modular Scaffolding
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 India Industrial Scaffolding End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Industrial Scaffolding Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Industrial Scaffolding Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Industrial Scaffolding Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Aarvi Scaffolding
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Shiv Shakti Scaffolding
- 18.4 BSL Scaffolding Ltd
- 18.5 Utkarsh Scaffolding
- 18.6 Layher India
- 18.7 PERI India
- 18.8 ULMA Construction
- 18.9 Shreeji Scaffolding
- 18.10 Siddhivinayak Scaffolding
- 18.11 Tirupati Scaffolding
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

