
Market Overview:
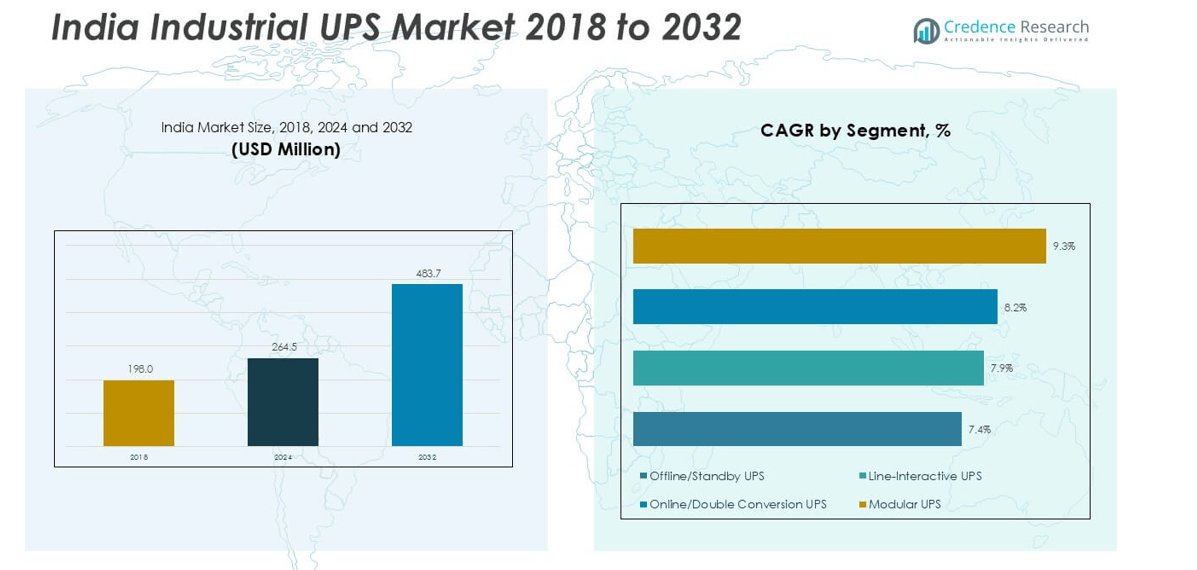
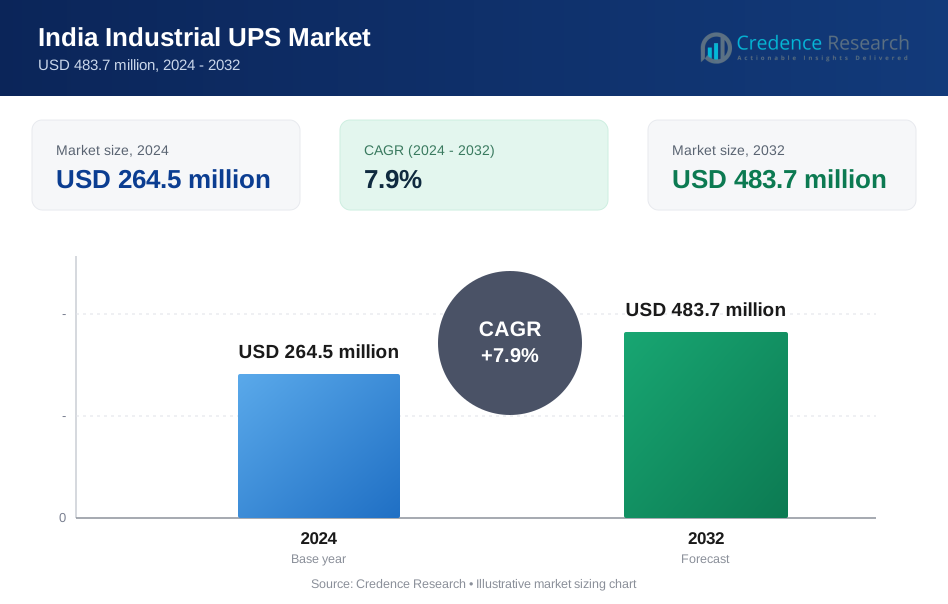
India Industrial UPS market size was valued at USD 198.0 million in 2018, growing to USD 264.5 million in 2024, and is anticipated to reach USD 483.7 million by 2032, registering a CAGR of 7.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Industrial UPS Market Size 2024 | USD 264.5 million |
| India Industrial UPS Market, CAGR | 7.9% |
| India Industrial UPS Market Size 2032 | USD 483.7 million |
Schneider Electric, Eaton, and Vertiv lead the India industrial UPS market with strong portfolios of online and modular UPS systems, catering to large enterprises and mission-critical facilities. Luminous Power Technologies and Microtek maintain a robust presence in the SME and cost-sensitive segments, while Delta Power Solutions and Hitachi Hi-Rel focus on high-efficiency solutions for process industries and data centers. South India dominated the market in 2024 with around 30% share, supported by its IT hubs, electronics clusters, and pharmaceutical industries. North India followed with 28% share, driven by industrial corridors and infrastructure projects.
Market Insights
- India Industrial UPS market was valued at USD 264.5 million in 2024 and is projected to reach USD 483.7 million by 2032, growing at a CAGR of 7.9% during 2025–2032.
- Growth is driven by rising industrialization, automation, and infrastructure development across oil & gas, pharmaceuticals, telecom, and construction sectors. Online/Double Conversion UPS dominated with over 40% share, followed by modular UPS gaining traction for scalability.
- Key trends include adoption of modular and lithium-ion battery-based UPS systems, integration with renewable energy, and deployment of remote monitoring for predictive maintenance.
- The market is moderately consolidated with players like Schneider Electric, Eaton, Vertiv, Luminous, and Microtek competing on technology, service coverage, and efficiency. Price-sensitive SMEs drive demand for cost-effective standby UPS solutions.
- South India led with 30% share, followed by North India with 28% and West India at 26%, supported by industrial corridors, manufacturing hubs, and data center growth.
Market Segmentation Analysis:
By Type
Online/Double Conversion UPS dominated the India industrial UPS market with over 40% share in 2024. This segment leads due to its ability to deliver continuous, high-quality power to critical equipment in industrial and process sectors. Industries with sensitive electronics, such as manufacturing and data centers, favor this type for its superior voltage regulation and zero transfer time during outages. Growing automation in production lines and stricter requirements for uninterrupted operations are further driving demand for online UPS systems. Modular UPS is also gaining traction as enterprises seek scalability and ease of maintenance.
- For instance, Schneider Electric is an established provider of industrial uninterruptible power supply (UPS) systems, such as the Galaxy VX, which is designed for mission-critical applications like large data centers and industrial facilities. The company has a significant presence in India and actively serves the automotive and eMobility sectors with industrial automation and energy management solutions.
By Application
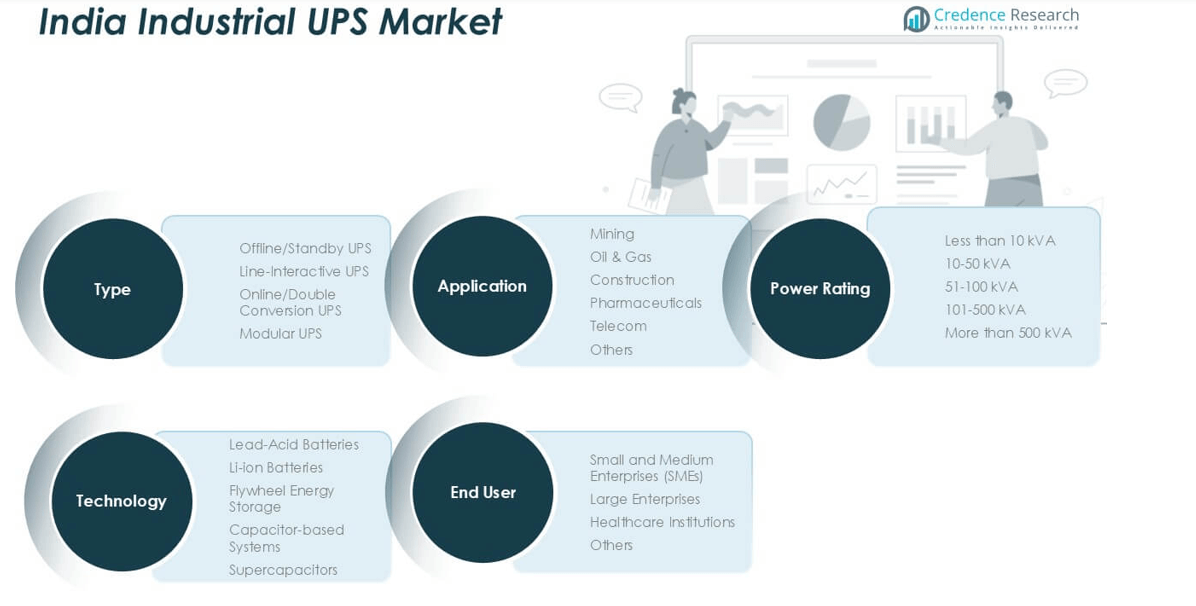
Oil & gas held the largest share of over 35% in 2024, making it the dominant application segment. This demand is fueled by the need for reliable power backup to maintain process control systems, drilling operations, and safety mechanisms in remote and hazardous sites. Mining and telecom sectors follow, driven by investments in digital monitoring systems and uninterrupted communications infrastructure. Construction sites are increasingly adopting UPS solutions to safeguard equipment and ensure smooth project timelines. Rising pharmaceutical manufacturing activities also boost demand for clean, uninterrupted power supply.
- For instance, Eaton delivered 800 kVA of UPS capacity for Coal India's digital mine monitoring centers in Jharkhand and Odisha in 2024.
By Power Rating
The 101–500 kVA power rating segment accounted for the largest share at nearly 38% in 2024. This range is preferred for medium to large industrial facilities requiring high power reliability, such as refineries, petrochemical plants, and manufacturing clusters. Its dominance is supported by rapid industrialization and expansion of process industries in India’s key states. The 10–50 kVA segment is also witnessing healthy growth, driven by SMEs investing in backup power to avoid production losses. Higher adoption of automation and digital control systems is pushing demand across multiple power rating categories.
Market Overview
Growing Industrialization and Infrastructure Development
India’s rapid industrialization is a major driver for the industrial UPS market. Expansion in sectors such as oil & gas, pharmaceuticals, mining, and manufacturing increases the need for reliable backup power systems. Modern production lines, SCADA systems, and process automation require uninterrupted power to prevent equipment downtime and data loss. The government’s push for “Make in India” and significant infrastructure investments, including smart cities, industrial corridors, and metro projects, are strengthening demand for high-capacity UPS systems. New manufacturing units are adopting online and modular UPS systems to ensure process continuity. In addition, the rise of large warehousing and logistics facilities drives adoption of UPS solutions to support automated material handling systems.
- For instance, ABB has a long-standing history of collaboration with ONGC, with past projects including the provision of automation systems for ONGC's drilling and production facilities. ABB routinely provides its industrial UPS technology to the oil and gas sector to support the continuous operation of critical infrastructure.
Digitalization and Adoption of Industry 4.0
The adoption of Industry 4.0 technologies is significantly accelerating UPS demand. Automation, robotics, and IoT-enabled equipment rely on constant power availability to function without interruptions. Indian industries are increasingly integrating digital twins, predictive analytics, and AI-based monitoring systems to improve efficiency, which increases reliance on a stable power infrastructure. UPS systems play a critical role in preventing data corruption, unplanned shutdowns, and production delays. Sectors such as automotive, electronics, and pharmaceuticals are leading this digital transformation, further driving UPS adoption. Additionally, the expansion of data centers and cloud infrastructure in India supports the need for high-efficiency online and modular UPS systems.
- For instance, Vertiv supplied a significant number of Liebert EXL S1 online UPS systems to various industries in India in 2024. These UPS systems likely contributed to protecting critical infrastructure, including SCADA systems and robotics, from power outages.
Rising Power Outages and Grid Instability
India continues to face challenges with power quality and grid reliability, particularly in remote and semi-urban areas where many industrial projects are located. Frequent voltage fluctuations, short circuits, and unplanned outages can damage sensitive equipment, resulting in costly downtime. Industrial UPS systems provide a crucial buffer by offering stable voltage and frequency, allowing operations to continue during interruptions. Growing dependence on automated process control systems in oil & gas, chemical, and mining sectors further fuels demand for robust UPS systems. Seasonal weather disruptions, such as monsoons causing power failures, also increase reliance on backup power. With rising investments in renewable energy projects and hybrid microgrids, UPS systems are becoming essential to balance intermittent supply. Industries view UPS adoption as a preventive measure to avoid losses, safeguard equipment, and maintain productivity, making grid instability a strong demand driver across various sectors in the country.
Key Trends & Opportunities
Shift Toward Modular and Scalable UPS Systems
A major trend in the India industrial UPS market is the adoption of modular UPS solutions. These systems allow scalability as industries expand operations, reducing upfront capital expenditure and simplifying maintenance. Modular designs also minimize downtime since faulty modules can be replaced without disrupting operations. Growing demand from data centers, telecom networks, and manufacturing units is pushing suppliers to develop compact, energy-efficient modular UPS systems. Indian enterprises prefer solutions with high flexibility and quick deployment capabilities to adapt to fast-changing load requirements. This trend supports cost efficiency and meets sustainability targets, as modular UPS systems typically have higher energy efficiency ratings. The increasing focus on operational agility and lifecycle cost reduction ensures that modular UPS adoption will continue to expand, particularly among SMEs and large enterprises undergoing digital transformation and capacity expansion in high-growth industrial clusters across India.
- For instance, Delta Electronics manufactures modular UPS units with N+X redundancy and hot-swappable modules that enable zero-downtime maintenance, and these systems are used in industries like pharmaceuticals where uninterrupted power is critical.
Energy Efficiency and Green Power Integration
Energy efficiency is becoming a critical factor in UPS selection as industries look to reduce operating costs and meet sustainability goals. High-efficiency UPS systems with lower power losses and advanced battery management are gaining popularity. Government initiatives promoting renewable energy integration and reduced carbon emissions are encouraging industries to adopt UPS systems compatible with solar and hybrid power solutions. Lithium-ion battery-based UPS systems are witnessing increased demand due to their longer lifecycle, compact size, and faster recharge capabilities. The market is also seeing a shift toward UPS systems that offer intelligent energy management and remote monitoring to optimize performance and minimize wastage. This trend aligns with India’s ESG commitments and helps companies achieve compliance with green building certifications. The push for sustainable energy management creates opportunities for manufacturers to innovate and provide eco-friendly UPS solutions that combine reliability, efficiency, and digital control features.
Key Challenges
High Capital and Maintenance Costs
One of the major challenges for the India industrial UPS market is the high capital investment required for advanced UPS systems. Large online and modular UPS units with higher power ratings can be expensive, creating budget constraints for SMEs and mid-scale industries. In addition, the cost of batteries, particularly lithium-ion variants, remains high, affecting affordability. Maintenance expenses add further burden, as regular servicing and periodic battery replacement are required to ensure reliability. Companies with limited budgets may delay upgrades, which impacts overall market penetration. Vendors are working to address this challenge by offering leasing models, financing options, and service contracts. However, price sensitivity in the Indian market continues to slow adoption, especially in cost-driven sectors such as small manufacturing and construction, limiting potential growth despite rising awareness about the importance of power continuity and equipment protection.
Limited Awareness and Skilled Workforce Shortage
A lack of awareness about advanced UPS technologies is another barrier to growth. Many small and medium enterprises still rely on basic standby systems and are unaware of the benefits of online or modular UPS solutions. Limited knowledge about lifecycle costs, efficiency benefits, and reduced downtime hinders investment in high-performance systems. Additionally, there is a shortage of skilled technicians capable of installing and maintaining complex UPS systems, especially in remote regions. This leads to improper deployment, suboptimal performance, and higher failure rates. The gap in technical expertise also increases dependence on external service providers, which can be costly and time-consuming. To overcome this challenge, manufacturers and industry associations are conducting training programs and awareness campaigns, but widespread adoption of advanced UPS technologies will depend on sustained education and capacity-building efforts in the Indian industrial sector.
Regional Analysis
North India
North India accounted for around 28% of the market share in 2024, driven by strong demand from manufacturing, automotive, and power generation sectors in states such as Haryana, Uttar Pradesh, and Delhi NCR. The presence of large industrial clusters, IT hubs, and data centers is boosting adoption of online and modular UPS systems. Rapid infrastructure development, including metro projects and smart city initiatives, further fuels growth. Government support for industrial corridors such as DMIC is creating demand for reliable backup power solutions to ensure operational continuity across factories, logistics hubs, and process industries.
West India
West India held nearly 26% market share in 2024, supported by strong demand from oil & gas refineries, petrochemical complexes, and pharmaceuticals concentrated in Gujarat and Maharashtra. The region’s large automotive and engineering manufacturing base requires stable power supply to protect automation systems and maintain production quality. Growing investments in logistics parks and warehousing also drive UPS adoption. Industrial UPS demand in this region is supported by ports, SEZs, and rapid growth of renewable energy projects, which need power stability for grid synchronization. Increasing deployment of digital infrastructure further strengthens the region’s market growth prospects.
South India
South India led the market with the largest share of about 30% in 2024, driven by robust presence of IT hubs, electronics manufacturing clusters, and data centers in Karnataka, Tamil Nadu, and Telangana. The region’s thriving pharmaceutical sector and large-scale industrial parks require uninterrupted power for critical processes. Adoption of modular UPS systems is rising due to scalability and low maintenance needs. Supportive state policies for electronics manufacturing and EV production are boosting demand for higher power rating UPS systems. The region’s focus on Industry 4.0 adoption and automation further accelerates UPS penetration in manufacturing facilities.
East India
East India contributed approximately 10% of the market share in 2024, with demand led by mining, steel, and power generation sectors in Odisha, Jharkhand, and West Bengal. Industrial UPS systems are crucial for ensuring smooth operations in remote mining sites and large steel plants that experience frequent grid fluctuations. The expansion of coal-fired and renewable power plants in this region further drives UPS demand for process control systems. Growing infrastructure projects such as metro expansions in Kolkata and new industrial parks are expected to create additional opportunities, gradually boosting the region’s share in the coming years.
Central India
Central India held nearly 6% market share in 2024, with demand concentrated in Madhya Pradesh and Chhattisgarh. The region’s cement, mining, and power generation industries rely heavily on UPS systems to maintain uninterrupted operations. Investments in smart grid projects and state-led industrial growth initiatives are helping drive adoption of modern online and modular UPS solutions. While the region is smaller compared to other zones, rising industrialization and capacity expansions in thermal power and manufacturing facilities are expected to improve its market share steadily through 2032, creating new opportunities for UPS vendors and service providers.
Market Segmentations:
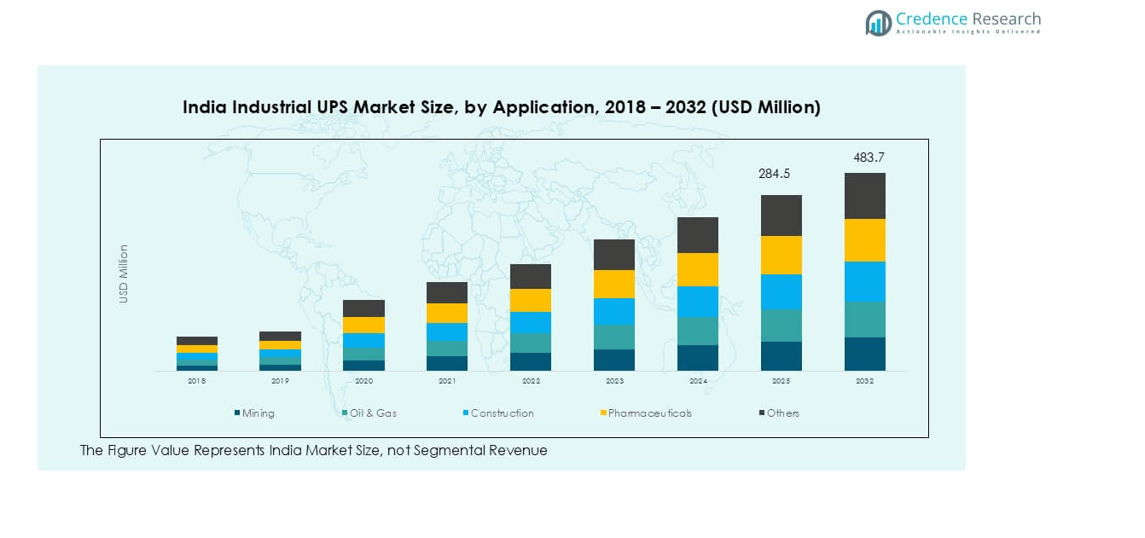
By Type
- Offline/Standby UPS
- Line-Interactive UPS
- Online/Double Conversion UPS
- Modular UPS
By Application
- Mining
- Oil & Gas
- Construction
- Pharmaceuticals
- Telecom
- Others
By Power Rating
- Less than 10 kVA
- 10–50 kVA
- 51–100 kVA
- 101–500 kVA
- More than 500 kVA
By Technology
- Lead-Acid Batteries
- Li-ion Batteries
- Flywheel Energy Storage
- Capacitor-based Systems
- Supercapacitors
By End User
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- Healthcare Institutions
- Others
By Geography
- North India
- West India
- South India
- East India
- Central India
Competitive Landscape
The India industrial UPS market is moderately consolidated, with global and domestic players competing on technology, reliability, and service offerings. Schneider Electric, Eaton, and Vertiv dominate the premium online and modular UPS segments, focusing on high-efficiency solutions for large enterprises and critical facilities. Luminous Power Technologies and Microtek hold strong positions in the mid-range and SME segments, supported by wide distribution networks and cost-competitive products. Delta Power Solutions and Hitachi Hi-Rel are expanding their presence with scalable and energy-efficient UPS systems designed for process industries and data centers. Local players such as Zebronics and Genus Power cater to niche and price-sensitive markets, providing basic standby systems. Companies are investing in lithium-ion battery technology, remote monitoring capabilities, and service contracts to differentiate their offerings. Strategic collaborations, capacity expansions, and product launches are key growth strategies aimed at capturing demand from rapidly growing industrial clusters and infrastructure projects.
Key Player Analysis
- Schneider Electric
- Luminous Power Technologies
- Microtek
- Eaton
- Vertiv
- Hitachi Hi-Rel
- STMicroelectronics
- Delta Power Solutions
- Zebronics
- Genus Power
Recent Developments
- In 2025, Riello UPS will showcase its energy-efficient solutions at DCN Riyadh 2025, where Dr. Antonio Coccia will present strategies for optimizing UPS systems for performance and sustainability. The event will host over 750 decision-makers, focusing on the future of data center infrastructure. This participation strengthens Riello UPS’s brand visibility among industry stakeholders and consumers.
- In January 2024, EPI launched the "Modular Data Center Standard" (MDCS) to standardize and enhance sustainability in modular data center construction. Huawei Digital Power Technologies Co., Ltd is actively contributing to this initiative, driving innovation and growth in the sector.
- In 2023, Kehua Tech successfully supported the 31st FISU World University Games in Chengdu, China, providing over 700 units of MR and KR Series UPS to ensure reliable power for key venues, including the opening and closing ceremonies, media centers, and hotels. This exposure helped strengthen its market presence and build trust with potential clients in diverse sectors.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Power Rating, Technology, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily with rising industrial automation and digital infrastructure projects.
- Adoption of modular UPS systems will increase due to scalability and low maintenance benefits.
- Lithium-ion battery UPS systems will gain higher penetration for efficiency and longer lifecycle.
- Data center expansion across tier-2 and tier-3 cities will boost demand for high-capacity UPS units.
- SMEs will increasingly adopt mid-range UPS systems to avoid production downtime.
- Integration with renewable and hybrid energy systems will become a key selection criterion.
- Government initiatives like Make in India and industrial corridors will create new opportunities.
- Vendors will focus on remote monitoring, IoT, and predictive maintenance features.
- Competition will intensify with global players and domestic brands enhancing service networks.
- Market share of southern and western regions will continue to grow with new industrial hubs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Industrialization and Infrastructure Development
India's ongoing industrial expansion, particularly in sectors like oil & gas, pharmaceuticals, and manufacturing, is driving demand for reliable backup power solutions to ensure uninterrupted operations and protect sensitive equipment.
Digitalization and Industry 4.0 Adoption
The integration of automation, robotics, and IoT-enabled systems in Indian industries increases the need for high-quality, continuous power, making advanced UPS systems essential for preventing downtime and data loss.
Grid Instability and Power Outages
Frequent voltage fluctuations and unplanned outages in many industrial regions of India make industrial UPS systems critical for maintaining operational continuity and safeguarding process control systems.
Shift Toward Modular and Energy-Efficient UPS
Growing preference for modular, scalable, and energy-efficient UPS solutions is fueled by the need for flexible capacity expansion, reduced maintenance, and alignment with sustainability goals, especially in data centers and large industrial facilities.
Expansion of Data Centers and Digital Infrastructure
The rapid growth of data centers, especially in tier-2 and tier-3 cities, is boosting demand for high-capacity, reliable UPS systems to support mission-critical applications and digital transformation initiatives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Industrial UPS market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Industrial UPS market projected to grow between 2025 and 2032?
Which India Industrial UPS market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Industrial UPS market?
Who are the leading companies in the India Industrial UPS market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Offline/Standby UPS
- 1.2.2 Line-Interactive UPS
- 1.2.3 Online/Double Conversion UPS
- 1.2.4 Modular UPS
- 1.3 By Technology
- 1.3.1 Lead-Acid Batteries
- 1.3.2 Li-ion Batteries
- 1.3.3 Flywheel Energy Storage
- 1.3.4 Capacitor-based Systems
- 1.3.5 Supercapacitors
- 1.4 By Application
- 1.4.1 Mining
- 1.4.2 Oil & Gas
- 1.4.3 Construction
- 1.4.4 Pharmaceuticals
- 1.4.5 Telecom
- 1.4.6 Others
- 1.5 By Power Rating
- 1.5.1 Less than 10 kVA
- 1.5.2 10–50 kVA
- 1.5.3 51–100 kVA
- 1.5.4 101–500 kVA
- 1.5.5 More than 500 kVA
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 264.5 million → 2032: USD 483.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Industrial UPS Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Industrial UPS Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Industrial UPS Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Industrial UPS Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Industrial UPS Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Industrial UPS Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Industrial UPS Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Industrial UPS Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 264.5 million → 2032: USD 483.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Industrial UPS Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Offline/Standby UPS
- 12.3.7.2 Line-Interactive UPS
- 12.3.7.3 Online/Double Conversion UPS
- 12.3.7.4 Modular UPS
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lead-Acid Batteries
- 12.4.7.2 Li-ion Batteries
- 12.4.7.3 Flywheel Energy Storage
- 12.4.7.4 Capacitor-based Systems
- 12.4.7.5 Supercapacitors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Mining
- 12.5.7.2 Oil & Gas
- 12.5.7.3 Construction
- 12.5.7.4 Pharmaceuticals
- 12.5.7.5 Telecom
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Power Rating - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Less than 10 kVA
- 12.6.7.2 10–50 kVA
- 12.6.7.3 51–100 kVA
- 12.6.7.4 101–500 kVA
- 12.6.7.5 More than 500 kVA
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 India Industrial UPS End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Industrial UPS Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Industrial UPS Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Industrial UPS Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Schneider Electric
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eaton
- 18.4 Vertiv
- 18.5 Luminous Power Technologies
- 18.6 Microtek
- 18.7 Delta Power Solutions
- 18.8 Hitachi Hi-Rel
- 18.9 Zebronics
- 18.10 Genus Power
- 18.11 STMicroelectronics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

