
Market Overview
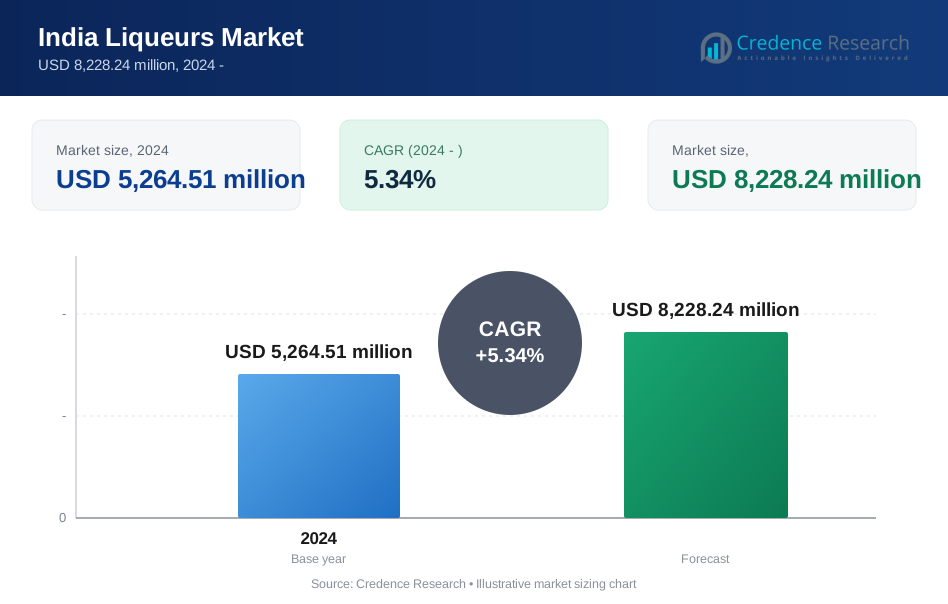
The India Liqueurs Market size was valued at USD 3,724.44 million in 2018 to USD 5,264.51 million in 2024 and is anticipated to reach USD 8,228.24 million by 2032, at a CAGR of 5.34% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| India Liqueurs Market Size 2024 | USD 5,264.51 million |
| India Liqueurs Market, CAGR | 5.34% |
| India Liqueurs Market Size 2032 | USD 8,228.24 million |
Market Insights
- The India Liqueurs Market was valued at USD 3,724.44 million in 2018 and is expected to reach USD 8,228.24 million by 2032, growing at a CAGR of 5.34%.
- Rising disposable incomes and a growing middle class are driving demand for premium, artisanal, and flavored liqueurs across urban and semi-urban areas.
- Urbanization and expanding hospitality and tourism sectors support on-premises consumption, particularly in bars, hotels, and high-end restaurants.
- Digital marketing, e-commerce platforms, and influencer campaigns boost brand visibility, product accessibility, and consumer engagement.
- Regulatory complexity and state-level taxation differences challenge distribution efficiency and create entry barriers for emerging brands.
- North India leads with 28% market share, followed by South India (24%), West India (22%), East India (15%), and Northeast India (11%).
- Key players include Diageo’s United Spirits, Radico Khaitan Ltd., Allied Blenders & Distillers, John Distilleries, DesmondJi, Mohan Meakin, and Tilaknagar Industries.
Market Drivers
Rising Urbanization and Shifting Consumer Preferences The India Liqueurs Market is driven by rapid urbanization, which has transformed social dynamics and lifestyle patterns across metropolitan areas. Young consumers increasingly favor premium and flavored alcoholic beverages during leisure and social gatherings. Rising exposure to global cocktail culture through travel and media has influenced taste preferences, pushing demand for liqueurs. It benefits from evolving consumer behavior that supports experimentation, indulgence, and luxury in beverage consumption. Tier-1 and Tier-2 cities continue expanding consumption volumes. For instance, Perrnod Ricard’s Absolut vodka, popular in metropolitan bars, offers a diverse range of high-quality flavored variants that resonate with urban young adults seeking sophisticated drinking experiences. Growing Disposable Income and Middle-Class Expansion The India Liqueurs Market gains momentum from increasing disposable income and the expanding middle-class population. Higher earnings enable consumers to explore diverse alcoholic beverage options, including premium and imported liqueurs. This trend fuels demand for value-added products across retail, on-trade, and home consumption channels. It supports market expansion into aspirational segments where consumers seek indulgent and status-driven experiences. The market benefits from aspirational purchases and greater willingness to spend on premium liquor. For instance, United Breweries’ premium whisky brand, Kingfisher Blue, has seen a volume growth of over 10% in urban markets due to increased consumer spending on quality products. Rising Influence of E-Commerce and Digital Campaigns The India Liqueurs Market is also propelled by digitalization, which enables direct engagement with consumers via social media, influencer marketing, and e-commerce platforms. Online liquor sales and home delivery services have increased product accessibility, especially in urban regions. It creates new avenues for brand discovery and promotion among tech-savvy consumers. Promotional campaigns highlight unique flavor profiles, cocktail recipes, and lifestyle branding. Convenience and targeted outreach significantly improve product penetration and consumer loyalty. Expansion of Hospitality and Tourism Sectors The India Liqueurs Market benefits from the growth of hospitality, tourism, and luxury dining establishments that incorporate liqueurs into cocktail menus and dessert offerings. Hotel chains, bars, and event venues demand a broad liqueur portfolio to cater to domestic and international visitors. It drives consistent volume movement across premium and flavored liqueur categories. Seasonal events, destination weddings, and corporate gatherings contribute to rising on-trade consumption. This channel remains critical for sustained market expansion.Market Trends
Premiumization and Craft Innovation The [India Liqueurs Market] tracks strong premiumization driven by consumers seeking elevated taste experiences. Brands introduce craft variants that combine artisanal ingredients and traditional distillation methods. It delivers limited-edition products that appeal to niche connoisseurs through storytelling and brand heritage. Producers invest in compelling packaging and labeling to reinforce premium positioning. Distribution through boutique liquor stores, upscale bars, and curated online platforms heightens visibility. Elevated pricing strategies reflect quality perception and exclusivity within emerging consumer segments. For instance, Pernod Ricard invested €200 million to establish India’s largest malt distillery, emphasizing craft whisky production with traditional distillation techniques to cater to premium consumers Flavor Diversification and Fusion Profiles The [India Liqueurs Market] evolves through flavor diversification that matches local palates and global preferences. It targets consumers with innovative fusions such as Indian spices, tropical fruits, and dessert-inspired blends. Producers collaborate with culinary experts to design unique recipes that elevate cocktail culture. It encourages experimentation among mixologists and home bartenders. Retailers highlight flavor stories through sampling events and digital campaigns. Flavor expansion fosters repeat purchases and strengthens emotional brand connections over time. For instance, Globus Spirits develops masala-flavored drinks integrating Indian spices to cater to local preferences, enhancing the traditional profiles of Indian Made Indian Liquor (IMIL). Health-Conscious Offerings and Low-Alcohol Alternatives The [India Liqueurs Market] shifts toward health-conscious consumption with low-alcohol and functional ingredient variants. It appeals to mindful consumers who prefer moderation alongside flavor. Brands introduce botanical-infused liqueurs with minimal sugar and natural extracts. It aligns with global wellness trends that influence beverage selection. Retail channels promote lighter alternatives through curated displays and digital content. Market responds with sugar-free and gluten-friendly options, broadening appeal to consumers focused on healthier lifestyles. Digital Engagement and E-Commerce Penetration The [India Liqueurs Market] embraces digital engagement that amplifies brand awareness and facilitates online sales. It leverages social media influencers who showcase cocktail recipes and flavor pairings. Interactive virtual tasting sessions connect brands with consumers remotely. It integrates secure home delivery platforms that improve purchase convenience and compliance. Retailers provide subscription-based offerings and discovery packs to enhance trial rates. Digital-first strategies drive higher conversion, repeat purchases, and stronger brand recall among urban audiences.Market Challenges Analysis
Regulatory Complexity and Taxation Barriers The India Liqueurs Market faces persistent challenges from regulatory fragmentation and high taxation. Excise duties vary significantly across states, creating logistical complications and pricing inconsistencies. It limits national distribution efficiency and restricts new entrants. Frequent policy shifts and license hurdles slow product launches and expansion. Smaller players struggle to compete with well-established brands that can absorb regulatory costs. Complex compliance processes increase operational burden and discourage innovation in premium and craft segments. Cultural Sensitivities and Limited Awareness The India Liqueurs Market also contends with cultural barriers and limited consumer education. In several regions, alcohol consumption remains a sensitive topic, reducing demand visibility and market penetration. It constrains brand marketing efforts and promotional reach, especially in traditional demographics. Many consumers are unaware of liqueurs’ distinct flavor profiles and mixology potential, which narrows adoption. Retailers often deprioritize liqueur inventory due to slow turnover and low product understanding. Bridging awareness gaps requires sustained engagement and education.Market Opportunities
Rising Demand for Premium and Experimental Flavors The India Liqueurs Market holds strong opportunity in the rising preference for premium, artisanal, and fusion-flavored offerings. Young urban consumers actively seek unique taste experiences that blend local ingredients with international trends. It creates space for new entrants and existing brands to innovate with Indian spices, tropical fruits, and dessert profiles. Brands can differentiate through exclusive editions, storytelling, and packaging aesthetics. The growing cocktail culture in metro cities supports demand across on-trade and home mixology segments. Expansion through Digital and Direct-to-Consumer Channels The India Liqueurs Market can leverage digital platforms and D2C models to enhance accessibility and engagement. E-commerce growth enables brands to bypass distribution barriers and reach consumers across diverse regions. It supports curated product discovery, virtual tastings, and influencer-driven promotions. Subscription boxes, limited-release drops, and personalized experiences build long-term loyalty. Tech-enabled convenience and evolving consumer openness toward online alcohol purchases offer significant scale potential for agile, digitally-native liqueur brands.Market Segmentation Analysis:
By Type The India Liqueurs Market segments by type into Neutrals/Bitters, Creams, Fruit Flavored, and Others. Neutrals/Bitters hold a strong share due to their use in classic cocktails and increasing bar consumption. Cream-based liqueurs gain popularity among younger consumers for dessert pairings and smooth textures. Fruit-flavored variants appeal to experimental drinkers, supporting product expansion in tropical and seasonal lines. The Others category includes niche blends that tap into artisanal and fusion demand, contributing to premium segment growth. For instance, Diageo’s portfolio features neutral and bitter liqueurs used extensively in classic cocktails and bar culture, exemplified by their investment in premium spirits like Copper Dog, a blended malt Scotch awarded Double Gold at the San Francisco World Spirits Competition 2020, reflecting focus on quality and mixability. By Packaging The India Liqueurs Market divides packaging into Glass, PET Bottle, Metal Can, and Others. Glass bottles dominate sales due to their association with premium quality, brand perception, and gifting suitability. PET bottles are gaining traction in lower-cost, high-volume segments due to durability and affordability. Metal cans offer convenience for travel and single-serve consumption, although adoption remains limited. It sees innovation in sustainable and resealable packaging formats, catering to evolving preferences across urban demographics. For instance, Maaricha, which manufactures custom glass bottles with cork closures ideal for whiskey, vodka, and craft liquors, supporting global export markets including the US and Europe with food and pharma-grade quality assurance and eco-friendly sealing. By Distribution Channel The India Liqueurs Market categorizes distribution through Convenience Stores, On-Premises, Retailers, and Others. On-premises channels such as bars, clubs, and hotels lead consumption volumes driven by nightlife and tourism. Retailers, including liquor shops and large-format stores, contribute significantly to off-trade demand. Convenience stores expand presence in Tier-2 cities where accessibility drives sales. It also experiences growth in hybrid formats like experience-led liquor boutiques and online platforms integrated into the Others category.Segments:
Based on Type:- Neutrals/Bitters
- Creams
- Fruit Flavored
- Others
- Glass
- PET Bottle
- Metal Can
- Others
- Convenience Stores
- On-Premises
- Retailers
- Others
- North India
- South India
- East India
- West India
- Central India
- Northeast India
Regional Analysis
North India North India holds the largest share in the India Liqueurs Market, accounting for 28% of total market volume. The region benefits from strong urban centers such as Delhi, Chandigarh, and Jaipur, where premium alcohol consumption continues to rise. Hospitality and tourism in these areas fuel consistent on-premises demand. It shows steady growth in retail sales supported by organized liquor outlets and evolving nightlife. Premium liqueur brands perform well due to rising disposable incomes. Festive seasons and weddings further elevate demand across product categories. South India South India captures 24% of the India Liqueurs Market, driven by cities like Bengaluru, Hyderabad, and Chennai. Consumers in this region show growing interest in flavored and cream-based liqueurs, supporting diversity in product offerings. It benefits from a strong tech-driven millennial base that favors mixology and global drinking trends. The market sees higher adoption of craft and regional blends through specialty outlets and boutique liquor stores. On-premises consumption thrives due to vibrant food and beverage culture. E-commerce expansion also improves accessibility in Tier-1 and Tier-2 cities. West, East, and Northeast India West India holds 22% of the market, supported by high consumption in Mumbai, Pune, and Goa, where tourism and premium hospitality drive sales. East India accounts for 15% share, with moderate growth led by Kolkata and Bhubaneswar. It remains price-sensitive but shows increasing interest in fruit-flavored variants. Northeast India holds an 11% share, where cultural acceptance and local events support growth. Cross-border demand and government-backed liquor retail systems support distribution. Regional festivals and tourism continue to drive seasonal spikes in demand.Key Player Analysis
- Diageo’s United Spirits
- Radico Khaitan Ltd.
- Allied Blenders & Distillers (ABD)
- John Distilleries Pvt. Ltd.
- DesmondJi
- Mohan Meakin
- Tilaknagar Industries
Competitive Analysis
The India Liqueurs Market features a competitive landscape led by both multinational corporations and domestic distillers. Key players such as Diageo’s United Spirits, Radico Khaitan Ltd., and Allied Blenders & Distillers dominate premium and mass-market segments. It sees strong competition in flavored and cream-based offerings, with John Distilleries and DesmondJi introducing innovative, locally inspired variants. Established brands leverage wide distribution networks and consistent branding, while new entrants focus on craft positioning and digital engagement. Regional players compete through price advantages and cultural familiarity. The market continues to evolve through product diversification, packaging innovation, and targeted promotional strategies that enhance brand loyalty and shelf visibility. Emerging digital storefronts, subscription models, and influencer partnerships help brands connect with younger, urban consumers. Strategic alliances and limited-edition releases further deepen market presence and differentiate offerings in a crowded landscape.Recent Developments
- In June 2025, Diageo India (United Spirits) acquired a majority stake in Nao Spirits, known for Greater Than and Hapusa gins, for INR 130 crore.
- In March 2025, Radico Khaitan launched Ankahi Zaffran Spiced Liqueur, its first entry in the Ankahi liqueur range, during ProWein 2025 in Düsseldorf.
- In March 2025, Tilaknagar Industries and Spaceman Spirits Lab jointly launched AMARA Pink Vodka, expanding into the super-premium spirits category.
- On June 27, 2025, Diageo India launched Godawan Artisanal Indian Single Malt – Triple Cask Expression, marking a milestone expansion of its artisanal spirits portfolio and emphasizing regional sourcing and premium maturation.
Market Concentration & Characteristics
The India Liqueurs Market displays moderate market concentration, with a mix of multinational corporations and regional distillers shaping competitive dynamics. Leading players such as Diageo’s United Spirits, Radico Khaitan Ltd., and Allied Blenders & Distillers control a significant portion of the premium and mass-market segments. It also includes emerging craft producers like DesmondJi and John Distilleries, which focus on localized innovation and flavor experimentation. The market features a wide variety of products spanning cream-based, fruit-flavored, and neutral variants, tailored to diverse regional preferences. Organized retail, on-premises consumption, and digital distribution channels contribute to its fragmented structure. Product differentiation, pricing strategy, packaging design, and distribution capabilities define competitive advantage. It continues to evolve through innovation, brand positioning, and targeted marketing to address varied consumer demographics. Despite entry barriers due to taxation and regulatory controls, the growing acceptance of liqueurs and increasing consumer sophistication present ample space for brand development and market expansion.Report Coverage
The research report offers an in-depth analysis based on Type, Packaging, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- Demand for premium and craft liqueurs will continue to rise in urban and semi-urban markets.
- Fruit-flavored and cream-based variants will attract younger consumers and home mixologists.
- E-commerce platforms will drive growth through improved accessibility and digital engagement.
- On-premises consumption will increase with the expansion of hotels, bars, and restaurants.
- Regional brands will gain traction by offering localized flavors and competitive pricing.
- Investments in sustainable packaging and branding will influence consumer purchasing decisions.
- Digital campaigns and influencer partnerships will strengthen brand awareness and loyalty.
- Entry of new domestic and international players will intensify product innovation and competition.
- Retail expansion in Tier-2 and Tier-3 cities will unlock new consumption opportunities.
- Government policy reforms and licensing improvements may ease market entry and distribution.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India Liqueurs Market?
What factors are driving the growth of the India Liqueurs Market?
What are the key segments within the India Liqueurs Market?
What are some challenges faced by the India Liqueurs Market?
Who are the major players in the India Liqueurs Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Liqueurs Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Liqueurs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 5,264.51 million → forecast year: USD 8,228.24 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Liqueurs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Liqueurs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Liqueurs Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Liqueurs Market Drivers
- 3.3 India Liqueurs Market Restraints & Challenges
- 3.4 India Liqueurs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Liqueurs Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Liqueurs Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Liqueurs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Liqueurs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Liqueurs Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Liqueurs market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Liqueurs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Liqueurs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Liqueurs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Liqueurs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Liqueurs Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Liqueurs Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Liqueurs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Liqueurs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Liqueurs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Liqueurs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Liqueurs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Liqueurs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Liqueurs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
