
Market Overview:
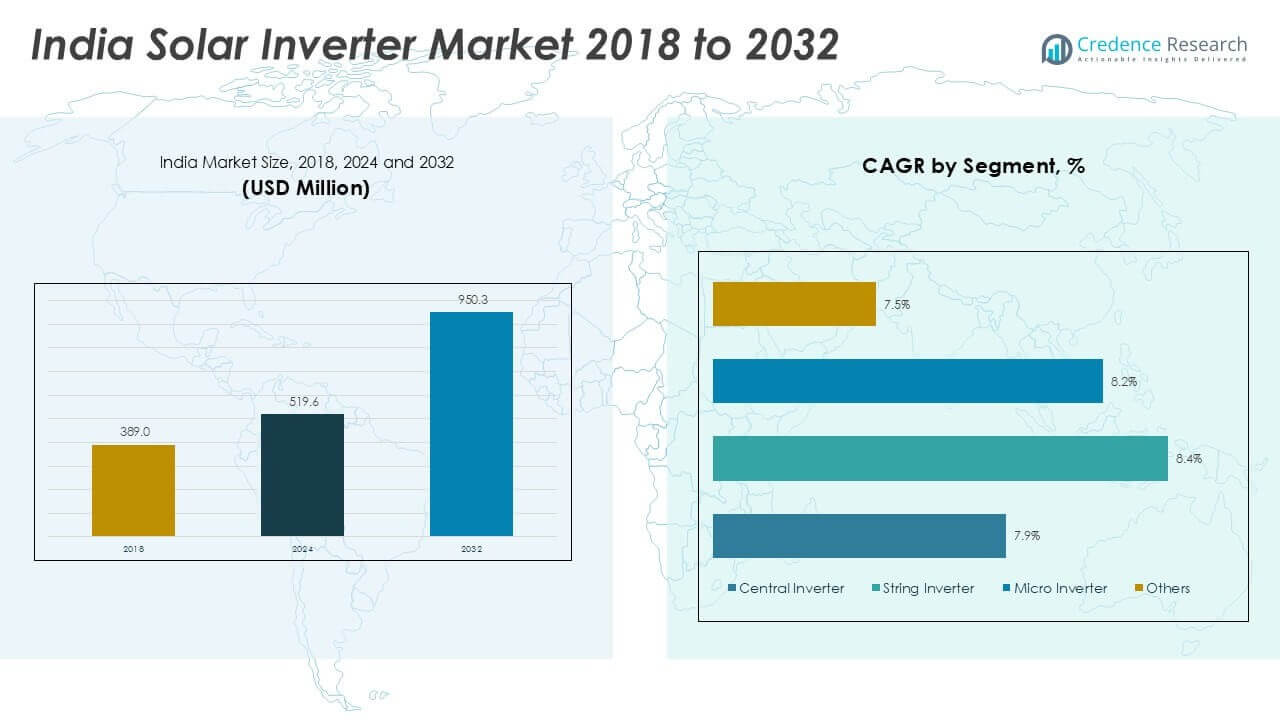
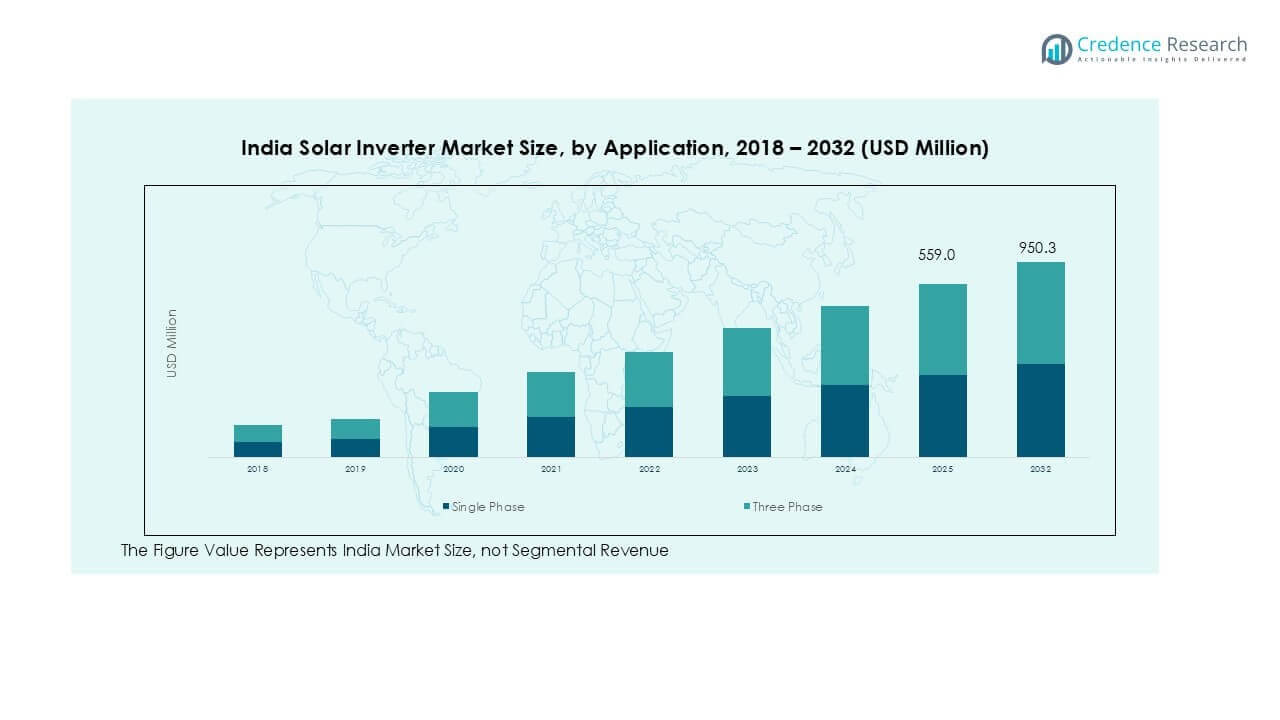
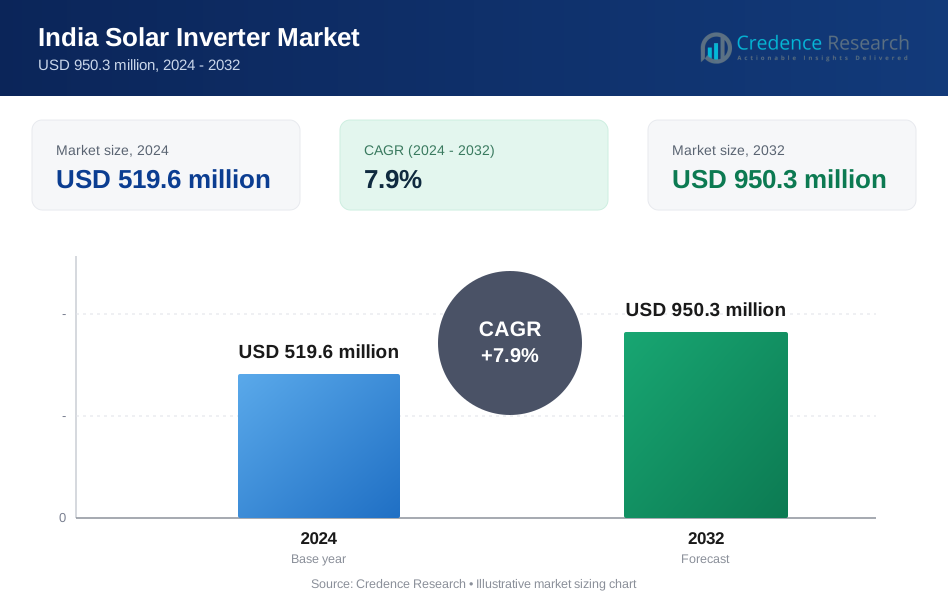
India Solar Inverter market size was valued at USD 389.0 million in 2018, growing to USD 519.6 million in 2024. The market is projected to reach USD 950.3 million by 2032, registering a CAGR of 7.9% during the forecast period (2025–2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Solar Inverter Market Size 2024 | USD 519.6 million |
| India Solar Inverter Market, CAGR | 7.9% |
| India Solar Inverter Market Size 2032 | USD 950.3 million |
The India solar inverter market is led by major players such as Schneider Electric, Siemens AG, Mitsubishi Electric Corporation, ABB Ltd, SMA, Delta Electronics, Fronius International GmbH, Sungrow, TMEIC, and GoodWe. These companies dominate through strong portfolios of central, string, and hybrid inverters catering to residential, commercial, and utility-scale projects. North India holds the largest market share at 35%, driven by large-scale solar parks and favorable state policies, followed by West India with 28% share, supported by Gujarat and Maharashtra’s strong rooftop solar programs. South India contributes 22%, led by Karnataka and Tamil Nadu’s industrial solar adoption.
Market Insights
- India solar inverter market size reached USD 519.6 million in 2024 and is projected to hit USD 950.3 million by 2032, growing at a CAGR of 7.9% during 2025–2032.
- Strong government initiatives, including the National Solar Mission and rooftop solar subsidies, drive adoption across residential, commercial, and utility-scale sectors, boosting demand for central and string inverters.
- Key trends include rising adoption of smart IoT-enabled inverters, hybrid systems with energy storage, and growing demand for distributed rooftop solar solutions in urban areas.
- Leading players such as Schneider Electric, Siemens AG, ABB Ltd, Delta Electronics, and Sungrow compete through technology innovation, grid-compliant designs, and strong EPC partnerships to capture market share.
- North India leads with 35% share, followed by West India at 28% and South India at 22%, with central inverters dominating utility projects and string inverters gaining traction in residential and commercial applications.
Market Segmentation Analysis:
By Type
Central inverters held the dominant share in the India solar inverter market in 2024, accounting for over 40% of total revenue. Their widespread use in utility-scale projects and large commercial installations drives demand. Central inverters offer high efficiency, lower installation costs per watt, and simplified maintenance, making them preferred for large-scale solar farms. String inverters are gaining traction due to their scalability and suitability for residential and small commercial setups. The growth of microinverters remains moderate but rising with rooftop solar adoption in urban areas.
- For instance, Sungrow supplied over 4 GW of central inverters for utility-scale solar farms commissioned across Rajasthan and Gujarat in 2024.
By System Type
On-grid solar inverters dominate the India market with more than 70% market share in 2024. Government initiatives promoting grid-connected solar systems, net metering policies, and rising utility-scale projects support this segment’s growth. On-grid inverters help optimize power export to the grid and provide real-time monitoring, aligning with India’s push toward renewable energy integration. Off-grid systems maintain a smaller share, primarily serving remote and rural regions where grid connectivity is limited, driven by initiatives like rural electrification and microgrid projects.
- For instance, in India, efforts to enhance rural electrification through microgrids continue under new programs, as the previous Saubhagya scheme was officially closed in 2022. While Victron Energy is a known supplier of components for off-grid systems in the Indian market, companies like them participate in various private and government-supported initiatives, rather than a single large-scale project as initially claimed. In 2024, the Indian government continued its support for off-grid electrification for thousands of homes, though this effort is part of newer schemes like the Revamped Distribution Sector Scheme (RDSS) and PM-JANMAN.
By Phase
Three-phase solar inverters lead the market, capturing over 60% revenue share in 2024, owing to their use in large-scale commercial, industrial, and utility projects. These inverters handle higher power capacity and offer superior grid stability, making them ideal for megawatt-scale installations. Single-phase inverters remain significant for residential rooftop solar systems, driven by rapid adoption of distributed solar in urban households. Government subsidies for residential solar rooftop programs are expected to further support single-phase inverter demand, although three-phase continues to dominate due to industrial and utility deployment.
Market Overview
Government Policies and Solar Initiatives
Government programs such as the National Solar Mission and state-specific solar policies are major growth drivers for the India solar inverter market. Net metering regulations, rooftop solar subsidies, and accelerated depreciation benefits encourage both residential and commercial adoption. Incentives for utility-scale solar parks and public-private partnerships have increased grid-connected installations nationwide. The push toward achieving 500 GW of renewable capacity by 2030 has created a strong demand pipeline for solar inverters. In addition, initiatives like PM-KUSUM promote decentralized solar power generation for rural areas, further boosting off-grid and small-capacity inverter sales.
- For instance, Tata Power Solar led India's rooftop solar market in 2024 with a 19.4% market share. The company's total installed rooftop capacity as of June 2024 was 343 MW, far short of 1 GW.
Declining Solar Component Costs
Falling prices of solar PV modules, coupled with improved efficiency, significantly lower the overall system cost. This cost reduction makes solar projects more financially attractive for industries, utilities, and households. Affordable financing schemes from banks and NBFCs complement cost reductions and accelerate adoption. Inverter technology advancements, including higher conversion efficiencies and longer product lifespans, improve project ROI and reduce levelized cost of energy (LCOE). As costs decline further, adoption is expected to penetrate deeper into residential and SME sectors, fueling consistent demand for both string and microinverters.
- For instance, IREDA sanctioned ₹37,354 crore and disbursed ₹25,089 crore in loans for renewable energy projects, achieving a record Profit After Tax of ₹1,252 crore.
Rising Electricity Demand and Energy Security Goals
India’s rising power consumption and need for energy diversification drive demand for solar inverters. Industrial growth, urbanization, and rural electrification programs require sustainable and cost-effective energy solutions. Solar power, supported by efficient inverters, addresses peak demand challenges and reduces dependency on fossil fuels. The government’s focus on energy self-sufficiency and reducing carbon emissions under COP commitments creates a favorable investment climate. Corporate ESG initiatives and green building certifications further stimulate solar adoption across commercial and industrial sectors, supporting robust market growth.
Key Trends & Opportunities
Shift Toward Smart and Hybrid Inverters
Smart solar inverters with IoT-enabled remote monitoring and advanced analytics are emerging as a key trend. These systems enable predictive maintenance, real-time performance tracking, and seamless grid integration. Hybrid inverters, which support energy storage, are gaining popularity as businesses and households adopt battery-backed systems to ensure power reliability. This trend aligns with India’s push for energy resilience and self-consumption optimization. Manufacturers offering hybrid-ready and smart-enabled solutions are positioned to capture significant market share as digitalization becomes a core requirement.
- For instance, Sungrow is a major supplier of solar inverters in India and uses its iSolarCloud platform for monitoring installations. The company has deployed SG350HX and other advanced inverters for large-scale projects in the region.
Utility-Scale and Rooftop Solar Expansion
Massive capacity additions in utility-scale solar parks present a strong opportunity for central inverter manufacturers. At the same time, rooftop solar installations in residential and commercial spaces are accelerating, driving demand for string and microinverters. Policies enabling net metering and capital subsidies for rooftop solar adoption create a dual growth engine for both centralized and distributed generation segments. The combination of large projects and small-scale distributed generation ensures a balanced and diverse demand outlook for solar inverter manufacturers.
- For instance, Adani Green Energy commissioned substantial new solar capacity in 2024, prominently at its large-scale project in Khavda, Gujarat.
Key Challenges
Grid Stability and Technical Constraints
Frequent grid fluctuations and voltage variations in many regions challenge inverter performance and system reliability. Inverters must comply with grid codes and provide features such as reactive power control and low-voltage ride-through capabilities. Poor grid infrastructure in rural areas increases maintenance requirements and limits the efficiency of on-grid systems. Manufacturers face the challenge of designing robust inverters that can handle India’s diverse grid conditions without compromising efficiency or lifespan.
High Initial Investment and Financing Barriers
Despite declining component costs, upfront capital expenditure for solar projects remains a challenge, particularly for small businesses and households. Limited access to affordable financing slows adoption in rural and semi-urban markets. Long payback periods deter some consumers, especially where electricity tariffs are already low. Inverter replacement and maintenance costs also add to lifecycle expenses, impacting project economics. Addressing these barriers through innovative financing models, leasing programs, and government-backed credit support is critical for accelerating market penetration.
Regional Analysis
North India
North India accounted for around 35% market share of the India solar inverter market in 2024, leading the overall demand. States such as Rajasthan, Haryana, Uttar Pradesh, and Punjab host large utility-scale solar parks and benefit from high solar irradiance. Government-backed projects like Rajasthan Solar Energy Policy and extensive grid infrastructure development fuel adoption of central inverters. Rooftop solar programs in Delhi NCR and commercial installations in industrial clusters further drive demand for string inverters. Favorable state policies and continued capacity additions will sustain North India’s dominant position during the forecast period.
West India
West India held nearly 28% of the market share in 2024, driven by Maharashtra and Gujarat’s strong renewable energy policies. Gujarat’s rooftop solar incentives and large solar park projects encourage demand for central and string inverters. Maharashtra’s focus on net metering and industrial adoption boosts installations across commercial spaces. The region benefits from robust grid connectivity and higher adoption of smart inverter technology. Strong state-level initiatives like the Solar Power Policy 2021 and ease of project execution position West India as a key growth hub for both on-grid and hybrid inverter systems in coming years.
South India
South India captured about 22% market share in 2024, led by Karnataka, Tamil Nadu, and Telangana. The region has seen significant solar capacity deployment, with Karnataka being a pioneer in large-scale solar parks. Industrial zones and tech parks in Tamil Nadu and Telangana are major users of rooftop solar systems, fueling string inverter demand. Government programs encouraging distributed generation and hybrid solar installations further support growth. Strong solar irradiance and active state-level renewable energy missions ensure South India continues to be a key contributor to the national solar inverter market.
East India
East India represented close to 8% of market share in 2024, reflecting steady but slower adoption compared to other regions. States like Odisha, West Bengal, and Bihar are gradually expanding solar capacity through state-led electrification programs and decentralized energy initiatives. The demand is mainly driven by off-grid systems and small-scale residential rooftop installations. Lack of robust grid infrastructure and lower industrialization levels slightly limit large-scale deployments. However, rural electrification projects and growing government focus on renewable energy penetration present opportunities for inverter manufacturers to expand their footprint in the region.
Central India
Central India accounted for roughly 7% of the market share in 2024, with Madhya Pradesh emerging as the key state in the region. Large-scale solar parks like the Rewa Ultra Mega Solar Park drive central inverter demand. Rooftop solar installations across institutional and commercial sectors are slowly increasing adoption of string inverters. Supportive state policies and competitive solar auction prices make the region attractive for future projects. Grid improvement initiatives and upcoming solar capacity additions are expected to strengthen Central India’s contribution to the overall solar inverter market during the forecast period.
Market Segmentations:
By Type
- Central Inverter
- String Inverter
- Micro Inverter
- Others
By System Type
- On-Grid
- Off-Grid
By Phase
- Single Phase
- Three Phase
By Output Power Rating
- Below 1 kW
- 1–3 kW
- 3–15 kW
- 15–50 kW
- 50–100 kW
- Above 100 kW
By End User
- Residential
- Commercial & Industrial
- Utilities
- Others
By Geography
- North India
- West India
- South India
- East India
- Central India
Competitive Landscape
The India solar inverter market is highly competitive, with global and domestic players focusing on technology upgrades, partnerships, and capacity expansion. Leading companies include Schneider Electric, Siemens AG, Mitsubishi Electric Corporation, ABB Ltd, SMA, Delta Electronics, Fronius International GmbH, Sungrow, TMEIC, and GoodWe. These players compete by offering advanced central, string, and hybrid inverters with improved efficiency, remote monitoring, and grid compliance features. Strategic initiatives such as collaborations with EPC contractors, participation in government solar tenders, and localization of manufacturing are common to strengthen market presence. Many companies are expanding their service networks and digital monitoring platforms to enhance customer experience. The competitive environment is also influenced by price sensitivity, encouraging firms to innovate cost-efficient solutions while maintaining performance standards. Continuous R&D investment and focus on energy storage-ready solutions will remain key differentiators for maintaining market share in the rapidly growing Indian solar sector.
Key Player Analysis
- Schneider Electric
- Siemens AG
- Mitsubishi Electric Corporation
- ABB Ltd
- SMA
- Delta Electronics, Inc
- Fronius International GmbH
- SUNGROW
- TMEIC
- GOODWE
Recent Developments
- In May 2024, Omron Electronic Components Europe announced a diverse range of innovations at the Smarter E Europe Exhibition 2024 to support efficiency and reduce energy losses for electric vehicle charging, electricity storage systems (ESS), and solar applications.
- In February 2024, Siemens AG announced new products and partnerships to achieve transformation and sustainable infrastructure. Siemens customers get access to flagship technologies in the space, including Xcelerator, an open and innovative digital business platform offering integration with more than 400 sellers in the Siemens global ecosystem.
- In October 2023, Fuji Electric India, a leader in the automation industry and cutting-edge energy-efficient solutions for industry operations showed the Central solar inverter PV 1500 series at the Renewable Energy India Expo held from October 4th to 6th at Greater Noida.
- In September 2023,WattPower, one of the major renewable energy firms globally, unveiled a modernized solar inverter production plant located in Tamil Nadu’s district of Chennai as a significant move forward in India’s solar energy sector. With its new string PV inverters, it desires to make an impact on the Indian solar PV industry.
- In July 2023, LG Energy Solution Ltd., a South Korea-based battery manufacturer, introduced new hybrid inverters suitable for private electric power plants. These inverters are designed to work on both low-voltage and high-voltage setups and come with an integrated backup feature that will easily blend with their own line of batteries.
- In April 2023, SolaX Power, which is famous for manufacturing solar inverters, publicized X1-Hybrid LV, another single-phase low-voltage hybrid inverter meant for residential applications. This new technology has been devised for the efficient operation of low-voltage solar photovoltaic (PV) systems.
Report Coverage
The research report offers an in-depth analysis based on Type, System Type, Phase, Output Power Rating, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness strong growth driven by rising solar capacity additions across utility and rooftop segments.
- Central inverters will continue dominating utility-scale projects due to their cost efficiency and reliability.
- String and microinverters will see faster growth with increasing residential and commercial rooftop solar installations.
- Hybrid inverters with storage compatibility will gain traction as energy independence becomes a priority.
- Smart inverters with IoT-enabled remote monitoring will become standard in new installations.
- Government policies and net metering regulations will continue to boost adoption in urban and rural areas.
- Domestic manufacturing initiatives under “Make in India” will improve supply chain resilience and reduce costs.
- Falling inverter prices and improved efficiency will enhance project ROI and drive wider penetration.
- Industrial and commercial sectors will adopt solar inverters to meet sustainability and ESG goals.
- Continued grid modernization will support integration of high-capacity solar power systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Policies and Solar Initiatives
Strong government support through the National Solar Mission, net metering regulations, and rooftop solar subsidies is accelerating adoption of solar inverters across residential, commercial, and utility-scale sectors in India.
Declining Solar Component Costs
Falling prices of solar PV modules and inverters, combined with improved efficiency and affordable financing, are making solar projects more financially attractive, driving deeper penetration into residential and SME segments.
Rising Electricity Demand and Energy Security Goals
India’s growing power consumption, industrialization, and rural electrification programs are increasing the need for sustainable energy solutions, with solar inverters playing a critical role in integrating renewable energy and reducing dependence on fossil fuels.
Shift Toward Smart and Hybrid Inverters
The adoption of IoT-enabled smart inverters and hybrid systems with energy storage is rising, as businesses and households seek greater energy reliability, remote monitoring, and self-consumption optimization.
Expansion of Utility-Scale and Rooftop Solar
Large-scale solar parks and accelerating rooftop solar installations in both residential and commercial sectors are creating robust demand for central, string, and microinverters, supported by favorable policies and incentives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Solar Inverter market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Solar Inverter market projected to grow between 2025 and 2032?
Which India Solar Inverter market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Solar Inverter market?
Who are the leading companies in the India Solar Inverter market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Central Inverter
- 1.2.2 String Inverter
- 1.2.3 Micro Inverter
- 1.2.4 Others
- 1.3 By Phase
- 1.3.1 Single Phase
- 1.3.2 Three Phase
- 1.4 By End User
- 1.4.1 Residential
- 1.4.2 Commercial & Industrial
- 1.4.3 Utilities
- 1.4.4 Others
- 1.5 By System Type
- 1.5.1 On-Grid
- 1.5.2 Off-Grid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 519.6 million → 2032: USD 950.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Solar Inverter Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Solar Inverter Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Solar Inverter Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Solar Inverter Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Solar Inverter Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Solar Inverter Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Solar Inverter Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Solar Inverter Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 519.6 million → 2032: USD 950.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Solar Inverter Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Central Inverter
- 12.3.7.2 String Inverter
- 12.3.7.3 Micro Inverter
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Phase - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Single Phase
- 12.4.7.2 Three Phase
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential
- 12.5.7.2 Commercial & Industrial
- 12.5.7.3 Utilities
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By System Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 On-Grid
- 12.6.7.2 Off-Grid
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 India Solar Inverter End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Solar Inverter Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Solar Inverter Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Solar Inverter Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Schneider Electric
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens AG
- 18.4 Mitsubishi Electric Corporation
- 18.5 ABB Ltd
- 18.6 SMA
- 18.7 Delta Electronics, Inc
- 18.8 Fronius International GmbH
- 18.9 Sungrow
- 18.10 TMEIC
- 18.11 GoodWe
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

