
Market Overview:
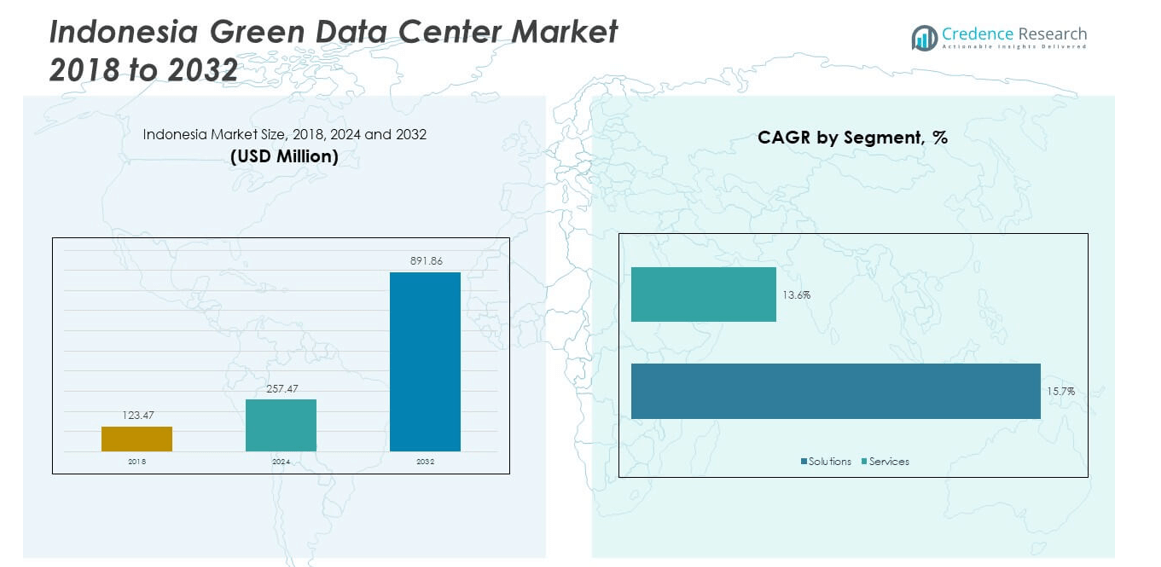
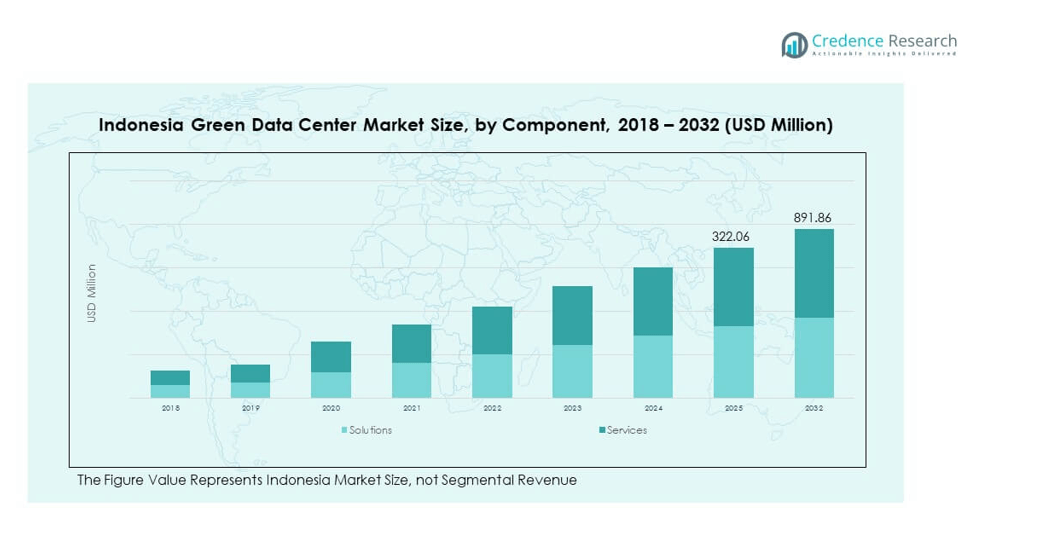
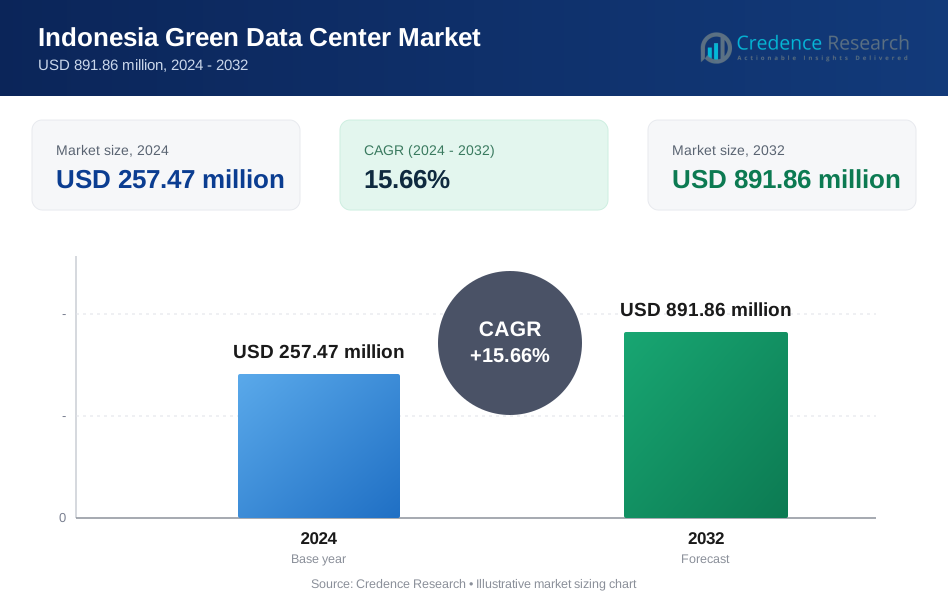
The Indonesia Green Data Center Market size was valued at USD 123.47 million in 2018 to USD 257.47 million in 2024 and is anticipated to reach USD 891.86 million by 2032, at a CAGR of 15.66% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Indonesia Green Data Center Market Size 2024 | USD 257.47 million |
| Indonesia Green Data Center Market, CAGR | 15.66% |
| Indonesia Green Data Center Market Size 2032 | USD 891.86 million |
The market growth is driven by the rising demand for energy-efficient infrastructure and sustainable operations in the IT and telecom sector. Cloud adoption, increased digital services, and the expansion of hyperscale data centers are pushing companies to adopt green technologies to reduce operating costs and comply with environmental targets. Strong government initiatives promoting renewable energy integration, alongside growing investor interest in sustainable infrastructure, further accelerate adoption. Rising enterprise awareness about reducing carbon footprints also plays a critical role in fueling market demand.
Regionally, Jakarta remains the hub for green data centers due to its role as Indonesia’s financial and digital capital, hosting large enterprises and hyperscale operators. Other regions are emerging, with West Java and Batam gaining traction due to favorable infrastructure, proximity to Singapore, and supportive investment policies. Eastern Indonesia is still at a nascent stage but offers potential as connectivity improves and local demand rises. This geographic shift shows a balanced trend between established hubs and upcoming growth regions across the country.
Market Insights:
- The Indonesia Green Data Center Market was valued at USD 123.47 million in 2018, reached USD 257.47 million in 2024, and is projected to hit USD 891.86 million by 2032, growing at a CAGR of 15.66%.
- Jakarta led with 55% share in 2024, supported by its position as the financial and digital hub with strong infrastructure.
- Batam followed with 25% share, benefiting from proximity to Singapore and cross-border connectivity, while Surabaya held 12% share, driven by economic growth in Eastern Java.
- Secondary and remote regions accounted for 8% share, but they represent the fastest-growing areas due to SME adoption and government-backed infrastructure expansion.
- By component, solutions such as cooling and power systems dominated with over 65% share in 2024, while services including deployment, consulting, and support contributed around 35%, reflecting balanced growth across infrastructure and service models.
Market Drivers:
Rising Demand for Sustainable Digital Infrastructure Across Enterprises:
The Indonesia Green Data Center Market is fueled by rapid digital transformation across industries. Enterprises are expanding their IT capacity, which increases energy demand. Green data centers help lower operating costs through energy-efficient cooling and power management systems. Companies see them as strategic investments for long-term savings and compliance with environmental regulations. Government support for sustainable infrastructure adds further momentum to adoption. It positions Indonesia as a regional leader in eco-friendly digital development. Strong demand from telecom, banking, and e-commerce players strengthens this transition.
- For instance, IDC Indonesia operates multiple Tier III and Tier IV data centers across Jakarta, Batam, and Makassar, utilizing advanced cooling solutions and redundant power systems with N+1 and 2N configurations, which have resulted in a measured reduction in energy consumption per rack by up to 20%. Government support for sustainable infrastructure adds further momentum to adoption.
Government Policies Encouraging Renewable Energy Integration:
Public policy plays a critical role in accelerating the green data center shift. Indonesia has committed to reduce carbon emissions while supporting digitalization. Incentives for renewable energy usage in IT infrastructure align with these goals. This has created an environment where operators focus on solar, wind, and hybrid energy solutions. The Indonesia Green Data Center Market benefits directly from these policy measures. Companies adopting clean energy reduce dependency on traditional power sources. It enhances their market reputation while meeting global sustainability standards. Regulatory clarity attracts both domestic and foreign investors.
- For example, Datagarda is enabling Indonesian data centers to integrate on-site solar and hybrid energy systems coupled with battery storage, contributing to a broader industry shift away from coal dependency towards cleaner energy sources. The Indonesian Green Data Center Market benefits from national policies that encourage renewable energy adoption. By adopting clean energy, companies enhance their market reputation, meet global sustainability standards, and contribute to Indonesia's green energy transition.
Growing Cloud Adoption and Hyperscale Expansion Across Indonesia:
The country’s increasing reliance on cloud services is a major driver. Hyperscale data centers require high efficiency and minimal environmental impact. Green solutions reduce electricity consumption while supporting high computing loads. Global players are entering Indonesia with large-scale investments. It has led to new projects in Jakarta and surrounding regions. Enterprises migrating workloads to the cloud also prefer eco-friendly solutions. The Indonesia Green Data Center Market gains momentum from this large-scale transition. Strong cloud growth is expected to sustain demand over the coming years.
Corporate Sustainability Goals and Carbon Neutrality Targets:
Enterprises are aligning operations with international sustainability benchmarks. Large corporations focus on achieving carbon neutrality across their supply chains. Green data centers provide measurable benefits by lowering greenhouse gas emissions. This makes them an attractive option for companies reporting ESG performance. Consumer awareness of sustainable practices further strengthens demand. The Indonesia Green Data Center Market reflects this corporate shift toward green IT. It allows enterprises to balance growth with environmental accountability. This driver ensures steady adoption across multiple industry verticals.
Market Trends:
Shift Toward Modular and Scalable Green Data Center Designs:
Enterprises demand flexible infrastructure that supports rapid digital expansion. Modular data center designs enable faster deployment with lower capital cost. Scalable green technologies allow operators to adapt to changing workloads. This trend reduces downtime while enhancing efficiency. The Indonesia Green Data Center Market is moving toward modular construction. It helps optimize space utilization and energy performance. The preference for modular systems aligns with the growing need for cost-effective and eco-friendly digital infrastructure.
- For example, Schneider Electric provides pre-engineered, modular data center elements that streamline commissioning times by 30%, which is being adopted by Indonesian data center operators to optimize space and energy performance. The preference for modular systems aligns with the growing need for cost-effective and eco-friendly digital infrastructure.
Integration of Advanced Cooling Systems for Energy Optimization:
Cooling consumes a significant portion of data center energy. Operators are shifting toward liquid cooling, free-air cooling, and AI-driven optimization. These systems reduce energy waste and extend equipment lifespan. The Indonesia Green Data Center Market shows growing adoption of innovative cooling strategies. It reflects a focus on operational excellence and sustainability. Companies deploying advanced cooling cut electricity bills and carbon output. This trend highlights technology-driven efficiency as a key differentiator. Operators adopting such solutions gain long-term competitive advantages.
- For instance, industry distributor Climanusa highlights its liquid cooling deployments in Indonesia, which offer significant energy efficiency improvements over traditional air cooling systems. While the company's own marketing materials claim savings of up to 30%, numerous independent studies confirm that liquid cooling substantially cuts electricity consumption and carbon output for data centers.
Adoption of Smart Monitoring and Automation for Efficiency Gains:
Smart monitoring solutions are transforming operational management. Real-time analytics enhance energy utilization and detect inefficiencies early. Automation reduces manual oversight while improving reliability. The Indonesia Green Data Center Market increasingly incorporates AI and IoT systems. It ensures higher efficiency and predictive maintenance capabilities. Enterprises gain better visibility into resource consumption patterns. This trend also improves service uptime and client trust. Technology-driven automation is becoming a standard in Indonesia’s evolving green data ecosystem.
Collaborations Between Local and Global Players for Green Innovation:
Strategic alliances shape the growth of Indonesia’s green digital infrastructure. Local firms partner with global technology leaders to introduce advanced solutions. Such collaborations bring in capital, expertise, and renewable integration strategies. The Indonesia Green Data Center Market benefits from shared innovations in design and operations. It accelerates knowledge transfer and boosts infrastructure development. Multinational players establish regional facilities while local companies provide execution support. These partnerships create competitive advantages and scale up adoption. The trend highlights cooperation as a core enabler of green transition.
Market Challenges Analysis:
High Initial Investment and Operational Cost Pressures:
Building green data centers requires significant upfront capital. Energy-efficient equipment, advanced cooling, and renewable integration drive costs higher. Many enterprises hesitate to make large investments without guaranteed returns. The Indonesia Green Data Center Market faces delays due to financial concerns. It must balance sustainable goals with affordability for operators. Rising land and construction expenses add further strain. Operators face pressure to control costs while meeting sustainability targets. It creates barriers for smaller firms aiming to enter the market.
Infrastructure Gaps and Power Reliability Concerns in Emerging Regions:
Indonesia still faces uneven infrastructure development across its regions. Outside Jakarta, reliable power supply and connectivity remain inconsistent. Green data centers require stable grids and advanced utility support. The Indonesia Green Data Center Market struggles in areas with poor infrastructure readiness. It impacts expansion into secondary and remote markets. Power disruptions increase operational risks and reduce efficiency benefits. Enterprises prefer established hubs, slowing nationwide growth. Closing these gaps is critical for achieving balanced market expansion.
Market Opportunities:
Rising Investor Interest in Sustainable Infrastructure Development:
Sustainability is now a global investment priority. Indonesia attracts strong investor attention for renewable energy and green IT. The Indonesia Green Data Center Market stands to benefit from this momentum. It provides opportunities for partnerships, financing, and innovation. Foreign investors see it as a gateway to Southeast Asia’s digital economy. Domestic enterprises leverage these funds to scale operations. Investor appetite ensures long-term market stability and growth potential.
Emergence of Secondary Hubs to Support Digital Expansion Nationwide:
Beyond Jakarta, cities like Batam and Surabaya are evolving as new data center hubs. They offer strategic advantages such as connectivity, land availability, and proximity to Singapore. The Indonesia Green Data Center Market can diversify by expanding into these hubs. It opens new opportunities for enterprises targeting regional growth. It also helps balance demand across Indonesia’s digital economy. These emerging hubs enhance resilience and strengthen national competitiveness. Market opportunities are growing steadily across multiple geographies.
Market Segmentation Analysis:
By Component
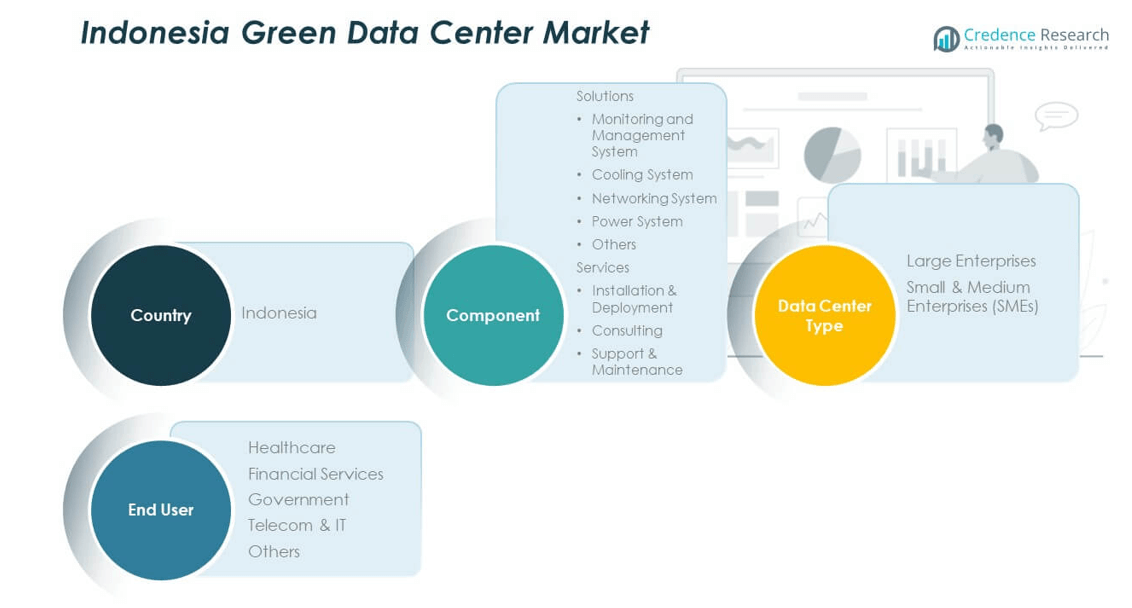
The Indonesia Green Data Center Market is divided into solutions and services. Solutions include monitoring and management systems, cooling systems, networking systems, power systems, and others. Cooling and power systems hold significant demand due to high energy consumption in data operations. Monitoring and networking solutions are gaining traction with the rise of automation. Service offerings such as installation & deployment, consulting, and support & maintenance provide strong recurring revenue opportunities. It demonstrates balanced growth between infrastructure and service-driven adoption.
- For instance, Cisco Systems and Huawei Technologies provide networking solutions that support automated monitoring and management, helping data centers reduce operational inefficiencies by analyzing real-time power usage data to optimize loads. Meanwhile, service offerings such as installation & deployment, consulting, and support & maintenance provide strong recurring revenue opportunities.
By Data Center Type
Large enterprises lead the market due to their capacity for capital investment and advanced infrastructure needs. They focus on energy-efficient technologies to align with sustainability targets. Small and medium enterprises are emerging adopters, supported by cloud migration and managed service models. It highlights the increasing democratization of green data solutions across business sizes.
- For example, NTT DATA's Jakarta 2 Annex Data Center supports up to 12MW critical IT load with racks capable of handling densities up to 40kW, employing advanced cooling and power management to optimize energy use. Small and medium enterprises are emerging adopters, supported by cloud migration and managed service models.
By End User
Telecom and IT remain the dominant end-user segment, driven by digital transformation and rising connectivity needs. Financial services adopt green infrastructure to meet regulatory standards and secure high-performance operations. Government agencies emphasize sustainability mandates, while healthcare accelerates adoption for secure and efficient digital storage. Other industries show steady progress through pilot-scale deployments.
Segmentation:
By Component
- Solutions
- Monitoring and Management System
- Cooling System
- Networking System
- Power System
- Others
- Services
- Installation & Deployment
- Consulting
- Support & Maintenance
By Data Center Type
- Large Enterprises
- Small & Medium Enterprises (SMEs)
By End User
- Healthcare
- Financial Services
- Government
- Telecom & IT
- Others
By Country (within Indonesia scope)
- Country-level Revenue Analysis
- By Component
- By Data Center Type
- By End User
Regional Analysis:
Jakarta as the Core Market Hub
Jakarta dominates the Indonesia Green Data Center Market with a share of around 55% in 2024. The city’s position as the financial and digital capital makes it the prime destination for hyperscale operators and multinational enterprises. Strong connectivity, access to reliable power, and concentration of IT infrastructure support its dominance. Enterprises in banking, telecom, and cloud services establish their largest operations in Jakarta. It continues to attract foreign investors seeking scalable and energy-efficient facilities. The concentration of corporate headquarters further enhances Jakarta’s leadership role.
Emerging Growth in Batam and Surabaya
Batam holds nearly 25% of the market, driven by its strategic location near Singapore and supportive investment climate. The city benefits from competitive land costs and growing cross-border digital traffic. Surabaya contributes about 12% share, supported by its role as an economic hub in Eastern Java. Enterprises recognize its potential for regional expansion due to improving connectivity and infrastructure readiness. The Indonesia Green Data Center Market leverages these emerging hubs to balance national digital demand. It reflects a trend toward diversifying operations beyond Jakarta’s saturated ecosystem.
Potential of Secondary and Remote Regions
Other regions, including West Java and Central Java, collectively account for about 8% market share. These areas remain at a nascent stage but show potential with rising demand from SMEs and government initiatives to expand digital access. Infrastructure gaps such as inconsistent power reliability and limited fiber coverage still limit large-scale adoption. It is expected that investment in grid modernization and renewable integration will unlock these regions in the future. The Indonesia Green Data Center Market demonstrates a gradual expansion from established hubs to underserved geographies. This shift will help create a more balanced and resilient digital ecosystem across the country.
Key Player Analysis:
- Telkom Indonesia
- SpaceDC
- DCI Indonesia
- Aesler
- Telkomsigma
- Indosat Ooredoo Hutchison
- NTT Communications
Competitive Analysis:
The Indonesia Green Data Center Market is competitive, with local and global players expanding capacity and strengthening service portfolios. Telkom Indonesia, DCI Indonesia, SpaceDC, and NTT Communications lead through large-scale investments and advanced sustainable infrastructure. Indosat Ooredoo Hutchison and Telkomsigma strengthen their presence with cloud-driven solutions. Smaller players such as Aesler focus on innovation in energy-efficient design. It demonstrates intense rivalry, with firms investing in renewable integration, modular designs, and automation to differentiate. Strategic alliances, mergers, and regional expansions shape the competitive landscape.
Recent Developments:
- In August 2025, Telkom Indonesia announced a strategic partnership with OpenAI during Solution Day 2025. This partnership aims to bring advanced AI applications to businesses and communities across Indonesia, including deploying ChatGPT Enterprise and leveraging Telkom's network to make AI accessible nationwide.
- In August 2025, Telkom Indonesia launched its AI Center of Excellence (AI CoE) to foster AI development and collaboration across sectors. The AI CoE aims to accelerate digital transformation by partnering with universities, industries, and government agencies to present AI solutions tailored for Indonesia's needs.
- In June 2025, DCI Indonesia inaugurated its eighth data center, JK6, at the H1 Campus in Cibitung. This facility adds 36 megawatts of capacity, bringing the total installed capacity to 119 megawatts, making it the largest data center operator in Indonesia. The data center is AI-ready and supports global cloud providers, marking a significant milestone in Indonesia's digital infrastructure development.
- In June 2025, Indosat Ooredoo Hutchison formed a strategic partnership with Transsion Holdings to boost digital inclusion in Indonesia. This partnership combines Indosat's connectivity with Transsion's affordable smart devices to improve digital access, especially in rural and underserved communities.
- In October 2023, Telkomsigma, a subsidiary of Telkom Indonesia, focused on expanding its cloud business portfolio, reaching an estimated market size of IDR 39.3 trillion. Telkomsigma is developing hybrid multicloud capabilities, supported by a team of certified cloud practitioners and 24/7 IT support, aiming to accelerate Indonesia's digital economy through efficient cloud solutions.
Report Coverage:
The research report offers an in-depth analysis based on component, data center type, end user, and country-level segmentation. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising digital adoption will sustain demand for energy-efficient data infrastructure.
- Jakarta will remain the dominant hub, while Batam and Surabaya expand rapidly.
- Investments in renewable energy integration will strengthen competitive positioning.
- Modular and scalable designs will gain traction to optimize deployment speed.
- AI-driven monitoring and automation will enhance operational efficiency.
- Hyperscale data centers will lead capacity expansion across core regions.
- Telecom and IT will continue as the largest end-user segment.
- SMEs will increase adoption through managed and cloud-based solutions.
- Government policies will encourage carbon neutrality and green infrastructure.
- Competition will intensify with global entrants targeting Indonesia’s growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Policies Encouraging Renewable Energy Integration
Indonesia's government has implemented incentives and regulatory support for renewable energy adoption in IT infrastructure, directly accelerating the shift toward green data centers. These policies encourage operators to invest in solar, wind, and hybrid energy solutions, reducing reliance on traditional power sources and enhancing sustainability.
Expansion of Hyperscale and Cloud Data Centers
The rapid growth of cloud adoption and hyperscale data centers in Indonesia is driving demand for energy-efficient, scalable, and environmentally friendly infrastructure. Global and local players are investing in large-scale, green-certified facilities to support high computing loads while minimizing environmental impact.
Corporate Sustainability and Carbon Neutrality Goals
Enterprises across sectors are prioritizing carbon neutrality and ESG compliance, making green data centers a strategic choice for reducing greenhouse gas emissions and meeting international sustainability benchmarks. This trend is especially strong among telecom, financial services, and IT companies.
Rising Investor Interest in Sustainable Infrastructure
Strong investor appetite for sustainable and green infrastructure projects is fueling capital inflows into Indonesia's green data center market. Both domestic and foreign investors are attracted by the long-term growth prospects and alignment with global sustainability priorities.
Emergence of Secondary Hubs and Infrastructure Modernization
Cities beyond Jakarta, such as Batam and Surabaya, are becoming new data center hubs due to improved connectivity, strategic location, and supportive investment policies. This geographic diversification is expanding market opportunities and driving balanced digital growth across Indonesia.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Indonesia Green Data Center Market in 2023 and 2032?
At what Compound Annual Growth Rate is the Indonesia Green Data Center Market projected to grow between 2024 and 2032?
What are the key drivers of growth in the Indonesia Green Data Center Market?
Which regions in Indonesia are experiencing growth in the Green Data Center Market?
How are renewable energy sources influencing the growth of the Indonesia Green Data Center Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Telecom & IT
- 1.2.2 Financial Services
- 1.2.3 Government
- 1.2.4 Healthcare
- 1.2.5 Others
- 1.3 By Component
- 1.3.1 Solutions
- 1.3.2 Monitoring and Management System
- 1.3.3 Cooling System
- 1.3.4 Networking System
- 1.3.5 Power System
- 1.3.6 Others
- 1.3.7 Services
- 1.3.8 Installation & Deployment
- 1.3.9 Consulting
- 1.3.10 Support & Maintenance
- 1.4 By Data Center Type
- 1.4.1 Large Enterprises
- 1.4.2 Small & Medium Enterprises (SMEs)
- 1.5 By Region (within Indonesia)
- 1.5.1 Jakarta
- 1.5.2 Batam
- 1.5.3 Surabaya
- 1.5.4 Other Regions (West Java, Central Java, etc.)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 257.47 million → 2032: USD 891.86 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Indonesia Green Data Center Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Indonesia Green Data Center Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Indonesia Green Data Center Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Indonesia Green Data Center Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Indonesia Green Data Center Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Indonesia Green Data Center Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Indonesia Green Data Center Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Indonesia Green Data Center Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 257.47 million → 2032: USD 891.86 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Indonesia Green Data Center Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Telecom & IT
- 12.3.7.2 Financial Services
- 12.3.7.3 Government
- 12.3.7.4 Healthcare
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solutions
- 12.4.7.2 Monitoring and Management System
- 12.4.7.3 Cooling System
- 12.4.7.4 Networking System
- 12.4.7.5 Power System
- 12.4.7.6 Others
- 12.4.7.7 Services
- 12.4.7.8 Installation & Deployment
- 12.4.7.9 Consulting
- 12.4.7.10 Support & Maintenance
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Data Center Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Large Enterprises
- 12.5.7.2 Small & Medium Enterprises (SMEs)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Region (within Indonesia) - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Jakarta
- 12.6.7.2 Batam
- 12.6.7.3 Surabaya
- 12.6.7.4 Other Regions (West Java, Central Java, etc.)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Indonesia Green Data Center End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Indonesia Green Data Center Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Indonesia Green Data Center Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Indonesia Green Data Center Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Telkom Indonesia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SpaceDC
- 18.4 DCI Indonesia
- 18.5 Aesler
- 18.6 Telkomsigma
- 18.7 Indosat Ooredoo Hutchison
- 18.8 NTT Communications
- 18.9 Huawei Technologies
- 18.10 Cisco Systems
- 18.11 Schneider Electric
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

