
Market Overview:
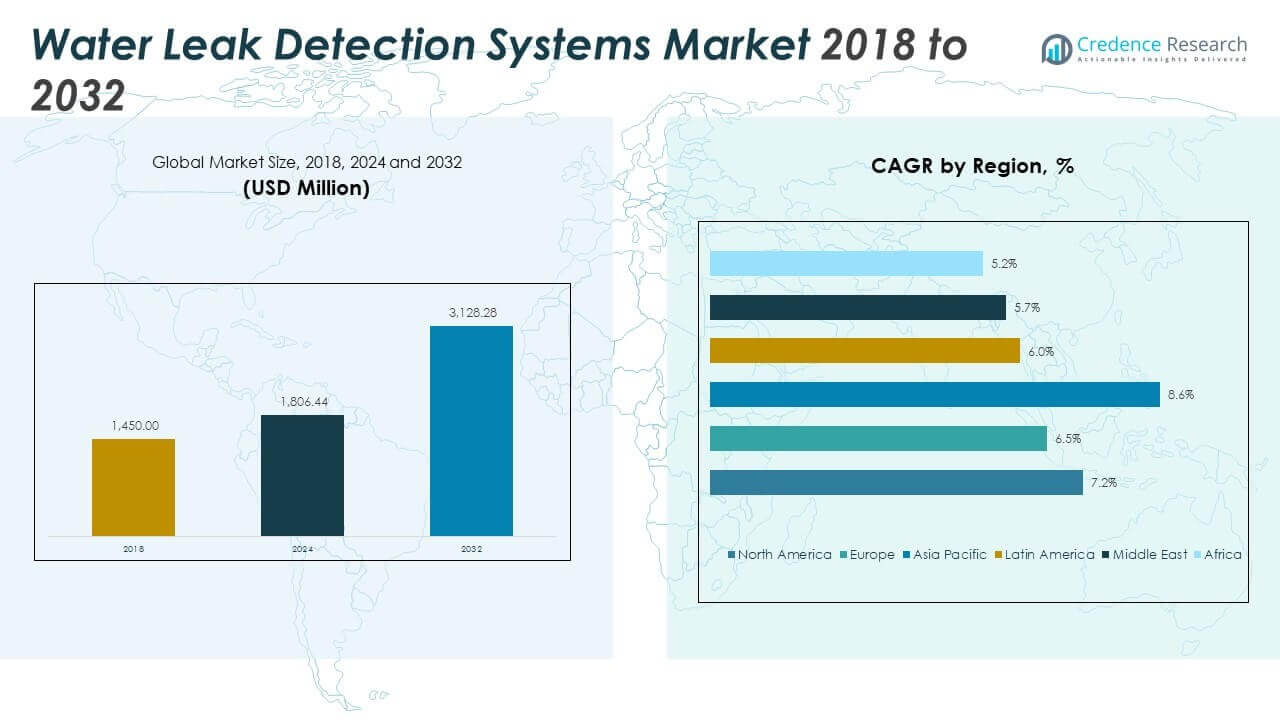
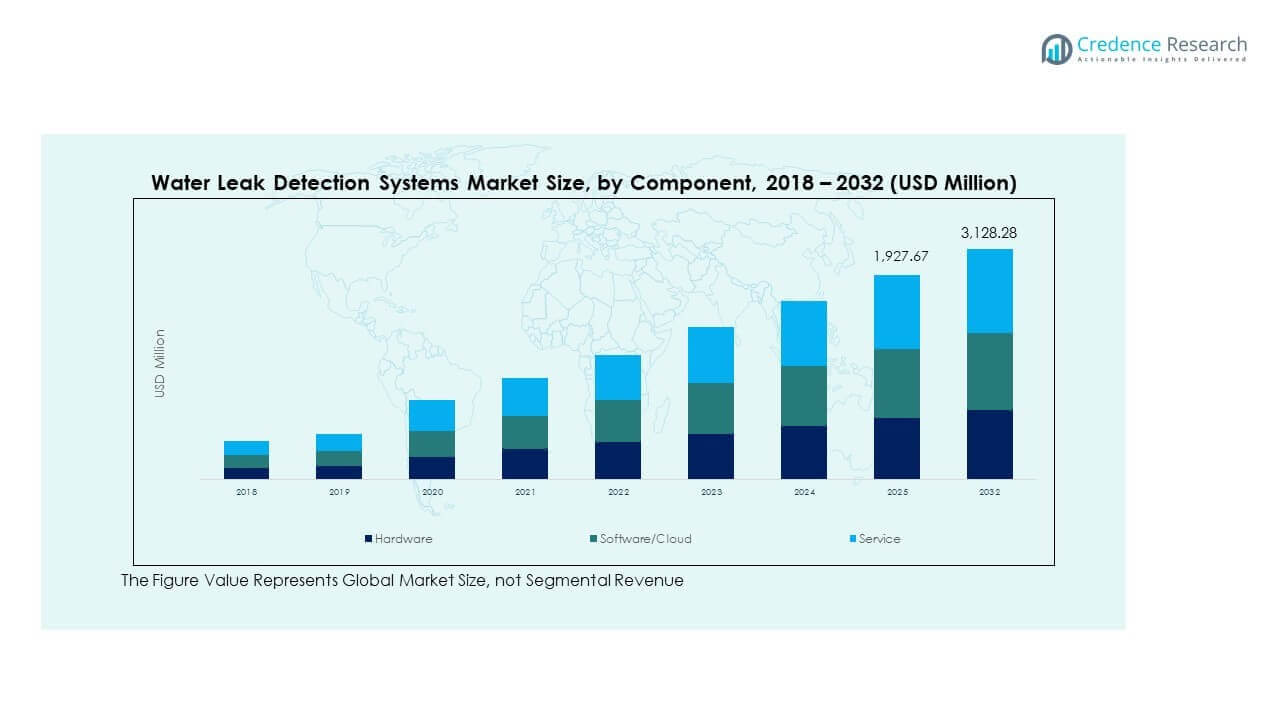
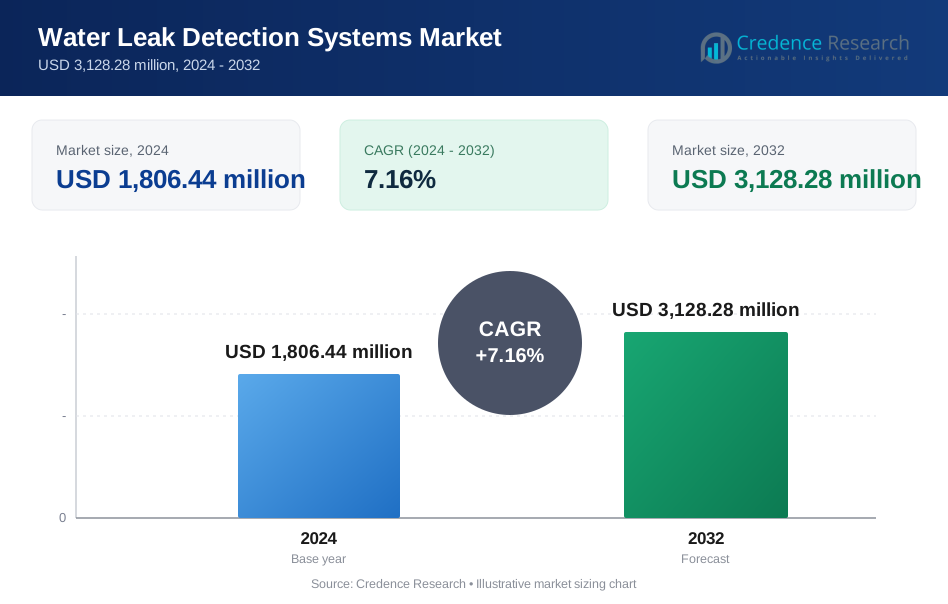
The Water Leak Detection Systems Market size was valued at USD 1,450.00 million in 2018, grew to USD 1,806.44 million in 2024, and is anticipated to reach USD 3,128.28 million by 2032, at a CAGR of 7.16% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Water Leak Detection Systems Market Size 2024 | USD 1,806.44 Million |
| Water Leak Detection Systems Market, CAGR | 7.16% |
| Water Leak Detection Systems Market Size 2032 | USD 3,128.28 Million |
The market is driven by rising awareness about water damage costs, asset safety, and infrastructure longevity. Building owners and facility managers increasingly deploy leak detection systems to minimize downtime, prevent structural harm, and comply with safety codes. The rise of smart buildings and integration of IoT platforms has improved the accuracy, responsiveness, and convenience of monitoring. Insurance firms encourage system use to reduce claims. Growing construction activity, especially in commercial and residential sectors, continues to expand the application base of these solutions.
Regionally, North America dominates due to high early adoption, strong regulatory enforcement, and demand from data centers and public infrastructure. Europe follows with investments in aging infrastructure and energy-efficient buildings. Asia Pacific leads in growth due to urban expansion, smart city projects, and increasing real estate developments in China, India, and Southeast Asia. Latin America, the Middle East, and Africa show gradual progress, supported by utility modernization programs and emerging construction projects in key cities.
Market Insights:
- The Water Leak Detection Systems Market was valued at USD 1,450.00 million in 2018, reached USD 1,806.44 million in 2024, and is projected to hit USD 3,128.28 million by 2032, expanding at a CAGR of 7.16%, reflecting strong long-term demand for proactive water monitoring solutions.
- North America led the market in 2024 with a share of about 38.02%, driven by early technology adoption, strong insurance influence, and high deployment across commercial buildings, data centers, and municipal infrastructure.
- Europe followed with roughly 27.46% share, supported by strict water conservation regulations, aging pipeline infrastructure, and sustained investment in smart buildings, while Asia Pacific held around 22.59% due to rapid urbanization and smart city programs.
- Asia Pacific emerged as the fastest-growing region, holding nearly 22.59% share in 2024, driven by large-scale construction activity, municipal water upgrades, and rising adoption of IoT-based leak detection in China, India, and Southeast Asia.
- By component, hardware accounted for about 45% of the market due to widespread sensor deployment, while software/cloud and services together represented roughly 55%, reflecting growing demand for real-time monitoring platforms and managed detection services.
Market Drivers:
Growing Financial Impact Of Undetected Water Leaks Across Properties
Water leaks cause high repair and replacement costs for buildings. Property owners seek early detection to limit damage. Facility managers focus on loss prevention strategies. The Water Leak Detection Systems Market gains traction from this need. Systems reduce downtime in offices and retail spaces. Early alerts help protect electrical and structural assets. Residential users also fear mold and health risks. Insurance teams promote preventive installation. Cost avoidance supports steady demand. Downtime from leaks also disrupts business continuity and service delivery. Asset depreciation accelerates when leaks remain undetected for long periods.
Rapid Expansion Of Commercial Buildings And Data-Intensive Facilities
Commercial construction continues across urban centers. Offices require reliable water control systems. Hospitals depend on clean and uninterrupted water supply. Data centers protect cooling and server rooms. Leak detection ensures operational continuity. Facility teams prioritize system reliability. Large campuses need centralized monitoring tools. Asset protection drives procurement decisions. Infrastructure growth sustains adoption levels. Hotels and airports also invest in proactive leak systems to avoid service shutdowns. Growth in co-working spaces increases system demand in new urban zones.
- For instance, Flo by Moen Smart Water Monitor continuously tracks pressure and flow to detect issues anywhere in facilities, alerting users or auto-shutting off to prevent damage.
Government Focus On Water Efficiency And Resource Management Policies
Authorities enforce water conservation rules. Municipal bodies aim to cut distribution losses. Building codes include water safety standards. Compliance drives system installation. Public projects specify leak monitoring tools. Policy pressure raises awareness among developers. Utilities adopt monitoring to improve accountability. Regulations influence long-term demand. Policy support strengthens market stability. Funding programs promote adoption in schools, hospitals, and community buildings. National water loss targets drive municipal investment in scalable detection systems.
Rising Role Of Insurance Providers In Risk Reduction Measures
Water damage claims affect insurers heavily. Risk assessment teams encourage detection systems. Commercial policies favor protected properties. Premium benefits influence buying behavior. Insurers prefer continuous monitoring solutions. Loss prevention guidelines guide installations. Residential insurance also reflects risk awareness. Prevention reduces claim frequency. Insurance alignment supports adoption growth. Major insurers now offer rebates or premium reductions for certified leak systems. Underwriters consider detection systems a key part of property risk scoring.
- For instance, LexisNexis Risk Solutions reported that homes equipped with Flo by Moen experienced a significant reduction in water damage claims, with observed trends supporting a lower claims frequency among users of smart water shutoff devices. This trend aligns with insurer interest in continuous water monitoring for proactive loss prevention.
Market Trends:
Increasing Adoption Of Software-Driven Monitoring Platforms
Vendors expand software capabilities across systems. Dashboards offer centralized system visibility. Users track alerts through digital interfaces. Software improves system control accuracy. Reporting tools support compliance needs. Facility teams value data access. Platform upgrades enhance user experience. Software becomes a key differentiator. Digital tools reshape buying preferences. Interoperability with other building systems enhances overall control. Frequent software updates improve scalability and security.
Rising Demand For Compact And Discreet Detection Devices
Users prefer low-visibility hardware designs. Compact sensors suit modern interiors. Aesthetic concerns affect residential demand. Discreet devices blend with building layouts. Small form factors ease installation. Designers integrate sensors during construction. Manufacturers focus on miniaturization. Space-saving designs gain acceptance. Visual simplicity becomes a trend. New designs include adhesive-mounted sensors for fast deployment. Demand rises for plug-and-play formats requiring no structural change.
- For instance, Honeywell ESSER’s IQ8Quad detectors support up to 48 units per loop with integrated alarm devices, enabling discreet installation suited to modern interior designs and compliance with stringent safety requirements.
Growth In Multi-Zone And Scalable Detection Architectures
Large buildings require zone-level monitoring. Scalable systems support expansion needs. Facility managers seek flexible layouts. Multi-zone control improves fault isolation. Expansion does not require full replacement. Modular design attracts enterprise buyers. Campuses benefit from scalable coverage. System flexibility gains importance. Architecture design influences selection. Hotels, hospitals, and airports lead adoption of scalable setups. Enterprise-grade systems now support up to hundreds of zones.
Preference For Vendor-Managed Monitoring And Service Models
End users seek reduced operational burden. Vendors offer managed monitoring services. Outsourced oversight improves response speed. Service models reduce internal staffing needs. Long-term contracts ensure system upkeep. Commercial users value predictable costs. Vendors strengthen customer relationships. Service-led sales increase retention. Business models continue to evolve. Managed models allow real-time analytics without client-side processing. Providers offer 24/7 support and proactive maintenance alerts.
- For instance, Honeywell ESSER systems integrate with WINMAG supervisor software to store up to 10,000 events, enabling remote monitoring and historical event review without relying on local client processing.
Market Challenges Analysis:
High System Complexity And Requirement For Skilled Technical Support
Advanced systems require proper calibration. Installation demands trained professionals. Configuration errors reduce system accuracy. False alerts affect user trust. Maintenance needs technical expertise. Smaller users lack skilled staff. Training adds operational cost. Technical barriers slow adoption. Complexity remains a key challenge.
Limited Awareness And Cost Sensitivity In Residential Segments
Many homeowners underestimate leak risks. Budget limits affect purchase decisions. Low-cost alternatives attract attention. Awareness programs remain limited. Installation cost discourages uptake. Benefits take time to realize. Price sensitivity slows penetration. Education gaps persist. Residential demand grows gradually.
Market Opportunities:
Integration With Smart Buildings And Automated Facility Management Systems
Smart buildings adopt connected monitoring tools. Leak detection integrates with building controls. Central systems improve operational efficiency. Automation supports faster response actions. Developers include systems at design stage. Facility platforms enable unified management. Digital buildings drive new demand. Integration creates long-term opportunities. Smart infrastructure supports growth.
Strong Construction And Infrastructure Development In Emerging Economies
Urban growth accelerates construction activity. New buildings adopt preventive technologies. Developers focus on asset protection. The Water Leak Detection Systems Market benefits from this shift. Emerging regions upgrade water networks. Commercial hubs expand rapidly. Awareness improves through infrastructure programs. Local vendors enter partnerships. Emerging markets offer strong expansion potential.
Market Segmentation Analysis:
The Water Leak Detection Systems Market spans several well-defined segments based on component, end user, technology, and application.
By component, hardware dominates due to widespread sensor deployment, especially in large-scale infrastructure. Software/Cloud is gaining momentum with real-time data dashboards, analytics, and integration capabilities. Services, including installation and maintenance, support long-term system performance and are critical for commercial and municipal buyers.
- For instance, Mueller Systems’ Solid State Meter (SSM) provides eight digits of granular data in sizes from 5/8″ through 2″ for ultrasonic metering, while Software/Cloud solutions are gaining momentum with real‑time data dashboards, analytics, and integration capabilities that enhance monitoring and decision‑making.
By end user, oil & gas leads due to high-risk, high-value assets requiring continuous monitoring. Water utilities follow closely, driven by non-revenue water reduction goals. Manufacturing facilities adopt detection systems to avoid production downtimes, while construction players integrate leak systems into smart building projects.
- For instance, Pepperl+Fuchs ultrasonic sensors offer detection ranges up to 10,000 mm for industrial applications, supporting reliable and long‑distance object detection in harsh environments.
By technology, acoustic methods remain preferred for buried pipeline inspection. Smart meters and flow/pressure-based detection serve utility-scale applications. IoT-enabled systems grow rapidly for smart buildings and remote monitoring. Infrared technology supports specialized use cases, including HVAC and confined space inspections.
By application, commercial buildings see strong adoption due to the need for early detection and cost avoidance. Residential usage grows with smart home integration. Industrial facilities demand high-performance systems with multi-zone support. Municipal applications continue rising with public infrastructure upgrades and regulatory initiatives.
Segmentation:
By Component
- Hardware
- Software/Cloud
- Service
By End User
- Oil & Gas
- Water Utilities
- Manufacturing
- Construction
By Technology
- Acoustic
- Smart Meters
- Flow/Pressure
- IoT
- Infrared
By Application
- Commercial
- Residential
- Industrial
- Municipal
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Water Leak Detection Systems Market size was valued at USD 557.82 million in 2018 to USD 686.98 million in 2024 and is anticipated to reach USD 1,188.13 million by 2032, at a CAGR of 7.2% during the forecast period. North America accounted for approximately 38.02% of the global market share in 2024. It benefits from early technology adoption and strict building codes. The U.S. drives demand through data center expansion and smart infrastructure. Commercial and municipal sectors invest in cloud-based detection and automatic shut-off systems. Insurance companies influence adoption in residential markets. Water utilities in California and Texas deploy smart meters. Canada also adopts acoustic and pressure-based systems for urban water networks. Demand rises steadily due to risk prevention policies.
Europe
The Europe Water Leak Detection Systems Market size was valued at USD 412.96 million in 2018 to USD 496.00 million in 2024 and is anticipated to reach USD 815.08 million by 2032, at a CAGR of 6.5% during the forecast period. Europe represented 27.46% of the market in 2024. It shows strong momentum driven by sustainability goals. Aging infrastructure in Germany, France, and the UK supports high system demand. Regulatory bodies enforce leakage targets across utilities. EU-funded smart city projects integrate leak detection. Manufacturing hubs in Central Europe adopt industrial systems. Commercial buildings follow strict asset protection standards. Cloud platforms gain traction across office spaces. Integration with energy and building systems boosts sales. Europe remains a stable and mature market.
Asia Pacific
The Asia Pacific Water Leak Detection Systems Market size was valued at USD 311.75 million in 2018 to USD 407.98 million in 2024 and is anticipated to reach USD 789.27 million by 2032, at a CAGR of 8.6% during the forecast period. Asia Pacific contributed 22.59% to the global share in 2024. It leads in growth due to rapid urbanization and smart infrastructure expansion. China and India invest heavily in municipal water upgrades. Smart meters and IoT-based systems find widespread deployment in new buildings. Japan shows strong demand in industrial automation zones. Southeast Asia adopts wireless solutions in residential projects. Rising real estate activity creates recurring demand. Government-backed smart city initiatives drive procurement. Regional vendors launch affordable solutions. Asia Pacific continues to lead in future potential.
Latin America
The Latin America Water Leak Detection Systems Market size was valued at USD 75.40 million in 2018 to USD 92.83 million in 2024 and is anticipated to reach USD 146.62 million by 2032, at a CAGR of 6.0% during the forecast period. Latin America held 5.14% of the 2024 market. Brazil and Mexico drive most installations. Industrial zones adopt leak systems for cost control. Water utilities face aging infrastructure challenges. Pressure monitoring systems support leakage reduction programs. Smart city pilots in Colombia and Chile fuel awareness. Public sector investments remain moderate. Infrastructure upgrades increase system integration opportunities. Local firms form partnerships for low-cost deployments. Steady improvement is visible in mid-tier cities.
Middle East
The Middle East Water Leak Detection Systems Market size was valued at USD 50.75 million in 2018 to USD 58.88 million in 2024 and is anticipated to reach USD 91.05 million by 2032, at a CAGR of 5.7% during the forecast period. Its 2024 market share was 3.26%. The market grows with water conservation needs. Gulf countries face extreme water scarcity. Government mandates encourage early adoption. Smart infrastructure in UAE and Saudi Arabia boosts demand. Energy and construction sectors drive investment. Hotels and commercial spaces deploy smart meters. Oil & gas plants implement real-time detection systems. Partnerships with global vendors increase technology access. Public-private initiatives continue to scale.
Africa
The Africa Water Leak Detection Systems Market size was valued at USD 41.33 million in 2018 to USD 63.77 million in 2024 and is anticipated to reach USD 98.13 million by 2032, at a CAGR of 5.2% during the forecast period. Africa contributed 3.53% to the global total in 2024. The region is in an early adoption phase. Urban utilities in South Africa and Kenya lead deployments. Water loss from aging systems creates urgency. International aid supports pilot installations. Demand grows in smart housing projects. Awareness campaigns improve adoption. Limited budgets constrain private sector growth. Local vendors explore scalable solutions. Market potential improves with infrastructure development.
Key Player Analysis:
Competitive Analysis:
The Water Leak Detection Systems Market features a mix of global technology providers and specialized solution vendors. Leading players compete through product reliability, system accuracy, and portfolio breadth. Large firms leverage strong R&D capabilities to offer integrated hardware and software platforms. Many focus on smart sensors, cloud dashboards, and automated shut-off features. Strategic partnerships with utilities and construction firms strengthen market presence. Companies expand service offerings to support installation and long-term maintenance. Pricing strategy plays a key role in residential and small commercial segments. Regional players compete by offering cost-effective and scalable solutions. Brand reputation influences procurement decisions in industrial and municipal projects. Innovation cycles remain short due to fast technology change. Competitive pressure pushes vendors to improve ease of use and interoperability. The market shows moderate consolidation with frequent collaborations and targeted acquisitions.
Recent Developments:
- In May 2025, Honeywell International Inc. launched the Hydrogen Leak Detector (HLD), a sensor using Thermal Conductivity Detection to identify microscopic hydrogen leaks as small as 50 parts per million, applicable to water-related industrial systems. The solution integrates into equipment for real-time safety, supporting hydrogen-powered infrastructure.
- In May 2025, Leaktronics launched the LT-2000 leak detection equipment kit advancing water leak detection for plumbing, pools, and irrigation with proprietary technology for precise locating in residential and commercial settings. The kit includes tools for challenging environments, backed by training, a five-year warranty, and support.
- In February 2025, LAIIER partnered with Cox Engineering to integrate its wireless Severn WLD™ leak detection solution into the latter's portfolio, enhancing smart leak prevention for commercial real estate and facility management across Boston and the East Coast.
- In January 2024, ABB acquired Real Tech, a Canadian company specializing in optical sensor technology for real-time water monitoring, to bolster its smart water management portfolio in the water leak detection systems market. The deal, enhances ABB's capabilities in sustainable water solutions through advanced optical sensors. This positions ABB for growth amid global water management demands
Report Coverage:
The research report offers an in-depth analysis based on Component, End User, Technology and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing investment in smart infrastructure projects will increase demand for IoT-enabled leak detection systems.
- Integration of AI and predictive analytics is expected to reshape decision-making for large facility managers.
- Public utilities and municipalities will expand adoption to reduce non-revenue water losses across old pipelines.
- Hardware upgrades will focus on multi-zone sensors and battery-powered wireless models for easier deployment.
- Service-based models and managed monitoring contracts will become key for commercial and industrial clients.
- Government mandates and water conservation policies will accelerate installations in new construction projects.
- Cloud-based platforms will play a critical role in real-time alerts, system diagnostics, and compliance reporting.
- Asia Pacific will remain the fastest-growing region due to rising urbanization and rapid smart city development.
- Insurance-backed risk mitigation strategies will encourage residential adoption of leak detection products.
- Product innovation will center on compact design, multi-technology integration, and long battery life.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Financial Impact of Undetected Water Leaks
Water leaks result in significant repair costs, asset depreciation, and business downtime, prompting property owners and facility managers to invest in early detection systems to minimize losses and protect infrastructure.
Rapid Expansion of Commercial Buildings and Data-Intensive Facilities
The ongoing construction boom in commercial real estate, data centers, and healthcare facilities increases the need for reliable water leak detection to ensure operational continuity and asset protection.
Government Focus on Water Efficiency and Resource Management
Regulatory mandates and water conservation policies are driving the installation of leak detection systems in public infrastructure, utilities, and new construction projects to reduce water loss and comply with safety standards.
Rising Role of Insurance Providers in Risk Reduction
Insurance companies are incentivizing the adoption of water leak detection systems by offering premium reductions and rebates, as these systems help lower the frequency and severity of water damage claims.
Integration with Smart Buildings and IoT Platforms
The trend toward smart buildings and IoT-enabled infrastructure is boosting demand for advanced leak detection solutions that offer real-time monitoring, automated alerts, and seamless integration with facility management systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Water Leak Detection Systems Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Water Leak Detection Systems Market projected to grow between 2024 and 2032?
Which Water Leak Detection Systems Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Water Leak Detection Systems Market?
Who are the leading companies in the Water Leak Detection Systems Market?
Which region commanded the largest share of the Water Leak Detection Systems Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Oil & Gas
- 1.2.2 Water Utilities
- 1.2.3 Manufacturing
- 1.2.4 Construction
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software/Cloud
- 1.3.3 Service
- 1.4 By Technology
- 1.4.1 Acoustic
- 1.4.2 Smart Meters
- 1.4.3 Flow/Pressure
- 1.4.4 IoT
- 1.4.5 Infrared
- 1.5 By Application
- 1.5.1 Commercial
- 1.5.2 Residential
- 1.5.3 Industrial
- 1.5.4 Municipal
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,806.44 million → 2032: USD 3,128.28 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Water Leak Detection Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Water Leak Detection Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Water Leak Detection Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Water Leak Detection Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Water Leak Detection Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Water Leak Detection Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Water Leak Detection Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Water Leak Detection Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,806.44 million → 2032: USD 3,128.28 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Water Leak Detection Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Oil & Gas
- 12.3.7.2 Water Utilities
- 12.3.7.3 Manufacturing
- 12.3.7.4 Construction
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software/Cloud
- 12.4.7.3 Service
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Acoustic
- 12.5.7.2 Smart Meters
- 12.5.7.3 Flow/Pressure
- 12.5.7.4 IoT
- 12.5.7.5 Infrared
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Commercial
- 12.6.7.2 Residential
- 12.6.7.3 Industrial
- 12.6.7.4 Municipal
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Water Leak Detection Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Water Leak Detection Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Water Leak Detection Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Water Leak Detection Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell International Inc.
- 18.4 Siemens
- 18.5 Leaktronics
- 18.6 Aqualeak Detection
- 18.7 Mueller Systems
- 18.8 Pepperl+Fuchs
- 18.9 LAIIER
- 18.10 Sensus (Xylem Inc.)
- 18.11 Schneider Electric
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

