
Market Overview
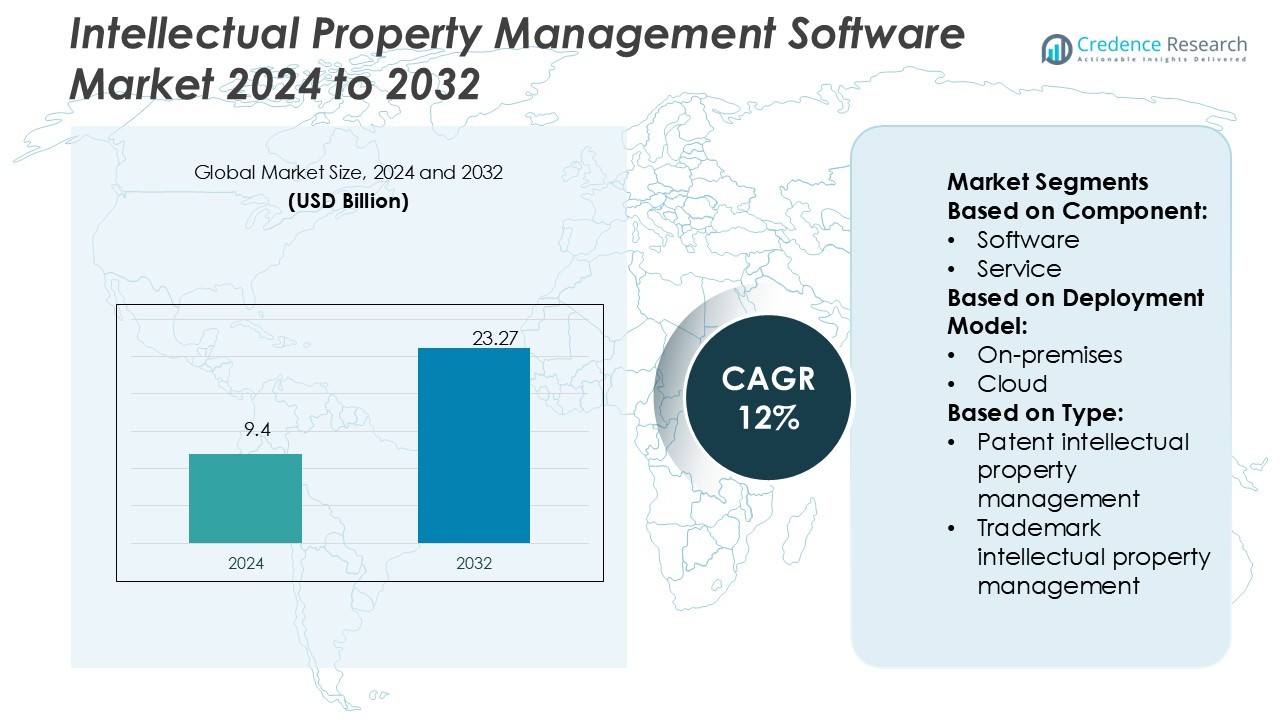
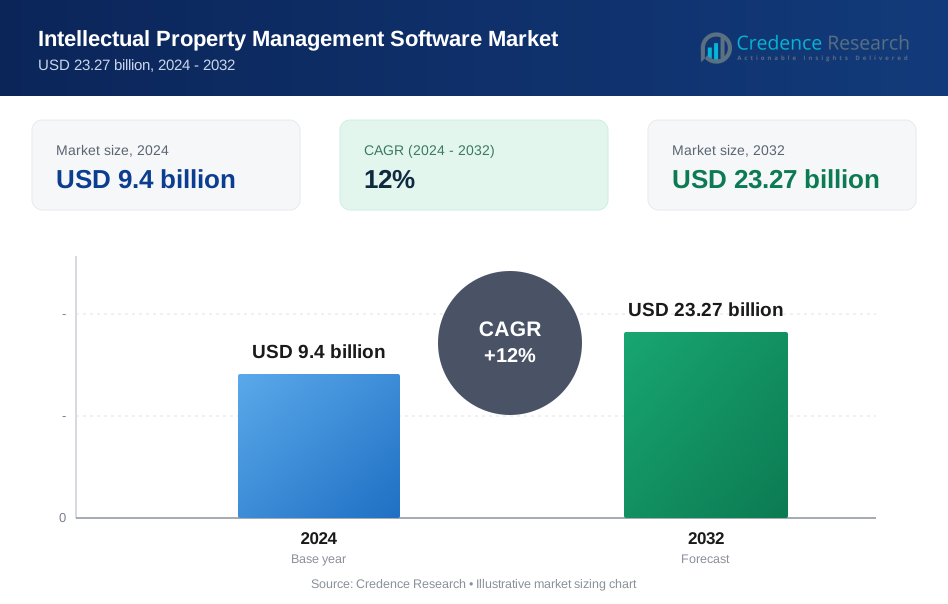
Intellectual Property Management Software Market size was valued USD 9.4 billion in 2024 and is anticipated to reach USD 23.27 billion by 2032, at a CAGR of 12% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Intellectual Property Management Software Market Size 2024 | USD 9.4 Billion |
| Intellectual Property Management Software Market, CAGR | 12% |
| Intellectual Property Management Software Market Size 2032 | USD 23.27 Billion |
The Intellectual Property Management Software Market features strong competition from leading players such as Clarivate PLC, LexisNexis, Anaqua Inc., Questel, Dennemeyer, Patsnap Pte Ltd, PatSeer Technologies Pvt. Ltd, Cardinal IP, WebTMS Limited, and Wellspring Worldwide. These companies compete by offering advanced IP lifecycle management platforms, AI-driven analytics, and cloud-based deployment models to meet rising global demand. North America dominates the market with a 37% share, supported by high patent activity, strong regulatory frameworks, and early adoption of digital IP solutions. The region’s innovation-driven industries and investments in advanced compliance systems solidify its leadership in the global market.
Market Insights
- The Intellectual Property Management Software Market size was USD 9.4 billion in 2024 and will reach USD 23.27 billion by 2032, at a CAGR of 12%.
- Key drivers include rising global patent filings, digital transformation of IP workflows, and growing demand for brand protection in e-commerce and technology sectors.
- Market trends highlight the shift toward cloud-based platforms, AI-powered analytics, and integration with enterprise systems, enabling real-time compliance and predictive portfolio management.
- Competition is strong among leading players offering end-to-end IP solutions, though high implementation costs and data security concerns act as restraints to wider adoption.
- North America leads with 37% share, driven by innovation-intensive industries and advanced regulatory frameworks, while the software segment dominates with nearly 65% share, supported by automation and centralized IP lifecycle management solutions.
Market Segmentation Analysis:
By Component
The Intellectual Property Management Software Market by component is divided into software and service. The software segment dominates with a market share of nearly 65%, supported by rising demand for integrated IP management platforms. Organizations prefer centralized solutions that streamline patent, trademark, and copyright tracking while offering analytics for decision-making. Key drivers include automation of IP workflows, cost reduction through digital platforms, and compliance with global IP regulations. The service segment continues to grow, led by consulting and managed services that enhance adoption and integration.
- For instance, WebTMS Limited provides a comprehensive IP management platform with automated docketing capabilities. Its Data Sync tool can access trademark data from over 180 jurisdictions, and the system includes features such as workflow management and automated updates from official registries.
By Deployment Model
In deployment, cloud-based solutions lead with 58% market share, outpacing on-premises adoption. Cloud deployment is driven by scalability, lower upfront costs, and the ability to support global collaboration. Enterprises benefit from faster updates, real-time data access, and integration with AI-enabled tools for IP portfolio analysis. On-premises models remain relevant for industries with strict data security needs, particularly in pharmaceuticals and defense. However, the shift to cloud is accelerating as organizations focus on operational efficiency and cross-border IP rights management.
- For instance, Dennemeyer selected Managed SD-WAN with NTT to interconnect 20 international offices, creating secure and optimized cloud connectivity across its network.
By Type
Among types, patent intellectual property management is the dominant sub-segment with 42% market share. This growth is driven by the rising number of patent filings across technology, healthcare, and manufacturing sectors. Patent software enables companies to manage applications, monitor lifecycles, and avoid costly lapses in renewals. Trademark and copyright management solutions also show strong growth, propelled by digital branding and content protection needs. Design IP management and other categories are gaining momentum with increasing innovation in consumer goods and creative industries, expanding the market scope.
Key Growth Drivers
Rising Global Patent Filings
The increasing volume of global patent filings is a major growth driver for the Intellectual Property Management Software Market. Companies across technology, pharmaceuticals, and manufacturing sectors seek efficient tools to track, process, and manage intellectual property assets. The complexity of global IP regulations necessitates software solutions that automate filing processes and ensure compliance. As businesses compete to secure innovation leadership, the demand for platforms that manage large patent portfolios, streamline renewals, and protect against infringement risks continues to grow steadily.
- For instance, Questel Orbit Intelligence platform the database included over 100,000 patent families declared essential to 2G, 3G, 4G, and 5G standards. It also included thousands of families with manual essentiality reviews. The database is continually updated.
Shift Toward Digitalization and Automation
Organizations are rapidly digitalizing IP workflows to replace manual processes and outdated systems. Intellectual property management software enables automation in areas such as docketing, renewal tracking, and portfolio analytics. This shift enhances accuracy, reduces administrative costs, and improves decision-making through real-time data insights. The integration of AI and machine learning further strengthens predictive analysis, enabling companies to assess IP valuation and identify infringement risks. Businesses adopting automation gain a competitive edge by increasing efficiency and strengthening IP lifecycle management strategies.
- For instance, Patsnap fully opened 140 data product types across Patent, Bio-Chemical, and Innovation data, supporting 178 million patent entries from 170 patent offices.
Growing Importance of Brand Protection
The rise of e-commerce, digital media, and cross-border trade has intensified the need for brand protection. Trademark and copyright infringements are more frequent, driving demand for advanced IP management solutions. Companies rely on software tools to monitor brand usage, detect violations, and enforce rights across multiple jurisdictions. As digital businesses expand, safeguarding brand assets becomes crucial to maintaining market reputation and revenue streams. The growing awareness of IP as a strategic asset positions brand protection as a critical driver of software adoption.
Key Trends & Opportunities
Adoption of Cloud-Based Platforms
Cloud-based IP management platforms are emerging as a leading trend due to their scalability and cost-effectiveness. Enterprises benefit from centralized data access, real-time collaboration, and seamless integration with AI-driven tools. The cloud also enables cross-border portfolio management, which is increasingly important as companies expand globally. Vendors are enhancing cloud solutions with advanced security features, making them suitable for industries handling sensitive IP. This trend presents opportunities for providers to capture enterprises transitioning from on-premises models to flexible cloud-based systems.
- For instance, IP Pragmatics Wellspring expanded its services to over 900 clients, including universities, research institutions, and government bodies, on a global scale.
Integration of AI and Predictive Analytics
Artificial intelligence and predictive analytics are transforming intellectual property management by providing deeper insights into portfolio performance. These technologies enable predictive renewal forecasting, infringement detection, and valuation analysis. Companies leverage AI tools to identify trends in patent filings, competitive activity, and potential litigation risks. This enhances strategic planning and resource allocation, reducing exposure to costly disputes. The opportunity lies in the increasing adoption of AI-driven platforms that support proactive IP decision-making and help organizations optimize their innovation strategies.
- For instance, LexisNexis launched the Protégé™ AI Assistant in PatentSight+, which draws on a harmonized global database of over 90 million patent family records and more than 100 baked-in patent metrics to answer natural language queries with visual insights.
Key Challenges
High Implementation Costs
The adoption of intellectual property management software often involves significant upfront investments in licensing, customization, and training. Small and medium-sized enterprises may find these costs prohibitive, limiting adoption across diverse sectors. While cloud-based solutions reduce infrastructure expenses, the total cost of ownership remains high due to ongoing subscription fees and integration with existing enterprise systems. This financial barrier slows market penetration in cost-sensitive regions, creating a key challenge for vendors aiming to expand their customer base.
Data Security and Compliance Risks
Managing sensitive intellectual property data across global jurisdictions presents serious security and compliance challenges. Cloud deployment, while efficient, raises concerns over data breaches, unauthorized access, and regulatory non-compliance. Industries such as pharmaceuticals and defense face heightened risks due to the strategic value of their IP assets. Vendors must ensure robust encryption, compliance with regional data laws, and reliable backup systems. Failure to address these risks can lead to loss of client trust and limit the adoption of digital IP management platforms.
Regional Analysis
North America
North America leads the Intellectual Property Management Software Market with 37% share in 2024, supported by strong patent activity in technology and pharmaceuticals. The United States drives adoption due to its large IP-intensive industries, stringent regulatory frameworks, and rising need for patent and trademark portfolio management. Software providers in the region focus on integrating AI and cloud solutions to enhance automation and compliance. Canada contributes steadily, with growing investments in innovation and R&D. The region’s emphasis on safeguarding intellectual property positions it as the dominant market, attracting both established vendors and emerging solution providers.
Europe
Europe accounts for 29% of the Intellectual Property Management Software Market, fueled by robust IP frameworks and cross-border trade within the European Union. Countries such as Germany, the United Kingdom, and France demonstrate strong adoption due to advanced manufacturing, automotive, and pharmaceutical industries. The European Patent Office’s initiatives to streamline filings further support the adoption of digital IP solutions. The region’s emphasis on compliance with GDPR and other regulations encourages vendors to offer secure and integrated platforms. Growing awareness of brand protection and digital innovation sustains demand for advanced IP management tools across Europe.
Asia-Pacific
Asia-Pacific holds 22% market share and is the fastest-growing region in the Intellectual Property Management Software Market. Rapid innovation in China, Japan, South Korea, and India drives strong patent and trademark filings. Expanding technology, electronics, and pharmaceutical industries fuel demand for software that ensures IP protection and lifecycle management. Cloud-based adoption is rising as enterprises seek cost-efficient, scalable solutions for managing large IP portfolios. Governments across the region are strengthening intellectual property laws, encouraging businesses to invest in digital management tools. Asia-Pacific’s growth trajectory highlights its emergence as a major hub for IP-driven industries.
Latin America
Latin America represents 7% of the Intellectual Property Management Software Market, with adoption led by Brazil and Mexico. Rising awareness of IP rights in industries such as consumer goods, agriculture, and healthcare is creating opportunities for software providers. While the region faces challenges like limited IP enforcement and high implementation costs, growing participation in international trade is increasing demand for reliable IP management solutions. Cloud deployment is gaining traction, particularly among SMEs seeking affordable platforms. Vendors targeting localized solutions and compliance support will find strong opportunities in strengthening Latin America’s IP protection ecosystem.
Middle East & Africa
The Middle East & Africa region accounts for 5% market share in the Intellectual Property Management Software Market. Adoption is concentrated in countries such as the United Arab Emirates, Saudi Arabia, and South Africa, where governments are investing in innovation ecosystems and IP frameworks. Industries like oil & gas, healthcare, and technology are driving gradual uptake of IP solutions. Challenges include low awareness and limited digital infrastructure in certain parts of the region. However, rising startup activity, coupled with government-backed IP initiatives, is expected to expand adoption and enhance regional growth prospects over the forecast period.
Market Segmentations:
By Component:
- Software
- Service
By Deployment Model:
- On-premises
- Cloud
By Type:
- Patent intellectual property management
- Trademark intellectual property management
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Intellectual Property Management Software Market is highly competitive, with key players including WebTMS Limited, Anaqua Inc., Dennemeyer, Questel, Clarivate PLC, Patsnap Pte Ltd, Cardinal IP, Wellspring Worldwide, LexisNexis, and PatSeer Technologies Pvt. Ltd. The Intellectual Property Management Software Market is characterized by intense competition, driven by rising innovation, digital adoption, and globalization of intellectual property rights. Vendors differentiate themselves through AI-driven analytics, cloud-based platforms, and end-to-end lifecycle management solutions that enhance efficiency and compliance. The market is witnessing a strong shift toward automation, enabling organizations to streamline complex processes such as patent filing, trademark monitoring, and renewal management. Companies also focus on delivering scalable platforms that cater to both large enterprises and SMEs. Strategic collaborations, product enhancements, and integration with predictive analytics remain critical factors shaping the competitive landscape.
Key Player Analysis
- WebTMS Limited
- Anaqua Inc.
- Dennemeyer
- Questel
- Clarivate PLC
- Patsnap Pte Ltd
- Cardinal IP
- Wellspring Worldwide
- LexisNexis
- PatSeer Technologies Pvt. Ltd
Recent Developments
- In February 2025, Eventdex.com, a provider of event management software, launched an integrated event suite to enhance event experience, operational efficiency, and event planning. The suite combines three tools: Gala Event Seating Software, Custom Event Badge Printing Software, and Event Floor Plan Software.
- In September 2024, Stova, an event management technology provider, launched an exhibitor management solution named Exhibitor Resource Center (ERC) for event professionals, sponsors, and exhibitors. ERC features include task management, sponsorship management, actionable insights, and seamless integration with other systems and tools.
- In May 2023, Accenture and Blue Yonder, Inc. announced the expansion of their strategic partnership to enhance organizations' supply chains by leveraging Accenture's technology and industry expertise. Accenture's cloud-native platform engineers and industry experts will collaborate with Blue Yonder to develop new solutions on the Blue Yonder Luminate Platform, offering end-to-end supply chain synchronization.
- In April 2023, Oracle introduced advanced artificial intelligence (AI) and automation capabilities designed to assist customers in optimizing their supply chain management processes. These new features leveraged AI and automation technologies to enhance efficiency, streamline operations, and enable better decision-making within supply chain management for its customers.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Model, Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising patent and trademark filings across industries.
- Cloud-based IP management platforms will continue to gain wider adoption.
- AI and machine learning will play a central role in predictive portfolio analysis.
- Enterprises will demand stronger compliance solutions to meet global IP regulations.
- Brand protection tools will see higher adoption due to digital content growth.
- SMEs will increasingly invest in cost-effective and scalable IP management solutions.
- Integration of IP tools with enterprise systems will strengthen decision-making processes.
- Data security will remain a priority, driving innovation in encrypted platforms.
- Cross-border IP management will grow as businesses expand internationally.
- Vendors will focus on partnerships and acquisitions to expand service offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Intellectual Property Management Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Intellectual Property Management Software Market projected to grow between 2025 and 2032?
Which Intellectual Property Management Software Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Intellectual Property Management Software Market?
Who are the leading companies in the Intellectual Property Management Software Market?
Which region commanded the largest share of the Intellectual Property Management Software Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Intellectual Property Management Software Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Intellectual Property Management Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9.4 billion → 2032: USD 23.27 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Intellectual Property Management Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Intellectual Property Management Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Intellectual Property Management Software Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Intellectual Property Management Software Market Drivers
- 3.3 Intellectual Property Management Software Market Restraints & Challenges
- 3.4 Intellectual Property Management Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Intellectual Property Management Software Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Intellectual Property Management Software Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Intellectual Property Management Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Intellectual Property Management Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Intellectual Property Management Software Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Intellectual Property Management Software. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Intellectual Property Management Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Intellectual Property Management Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Intellectual Property Management Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Intellectual Property Management Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Intellectual Property Management Software
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Intellectual Property Management Software Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Intellectual Property Management Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Intellectual Property Management Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Intellectual Property Management Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Intellectual Property Management Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Intellectual Property Management Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Intellectual Property Management Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Intellectual Property Management Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
