
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Interior Fit Out Market Size 2023 | USD 2,106.61 million |
| Interior Fit Out Market, CAGR | 7.28% |
| Interior Fit Out Market Size 2032 | USD 3,969.55 million |
Market Overview
The Interior Fit Out Market is projected to grow from USD 2,106.61 million in 2023 to an estimated USD 3,969.55 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 7.28% from 2024 to 2032. The steady growth trajectory is driven by increasing demand for customized interior spaces in both residential and commercial sectors, as well as a rising emphasis on aesthetics and functionality in interior design.
Several key factors are propelling the market's expansion. The booming real estate industry, coupled with a surge in renovation projects, is significantly boosting the demand for interior fit-out services. Additionally, the growing trend of open office layouts and flexible working environments is leading organizations to invest in fit-out solutions that enhance employee productivity and well-being.
Regionally, North America dominates the Interior Fit Out Market, primarily due to high construction activities and a well-established demand for interior design services. Europe closely follows, supported by increasing investments in commercial spaces and renovations. The Asia-Pacific region is anticipated to witness substantial growth during the forecast period, driven by rapid urbanization, rising disposable incomes, and a growing focus on modern living and working spaces. Emerging economies in this region, such as China and India, are expected to present significant opportunities for growth, fueled by their expanding construction sectors and evolving consumer preferences.
Market Insights
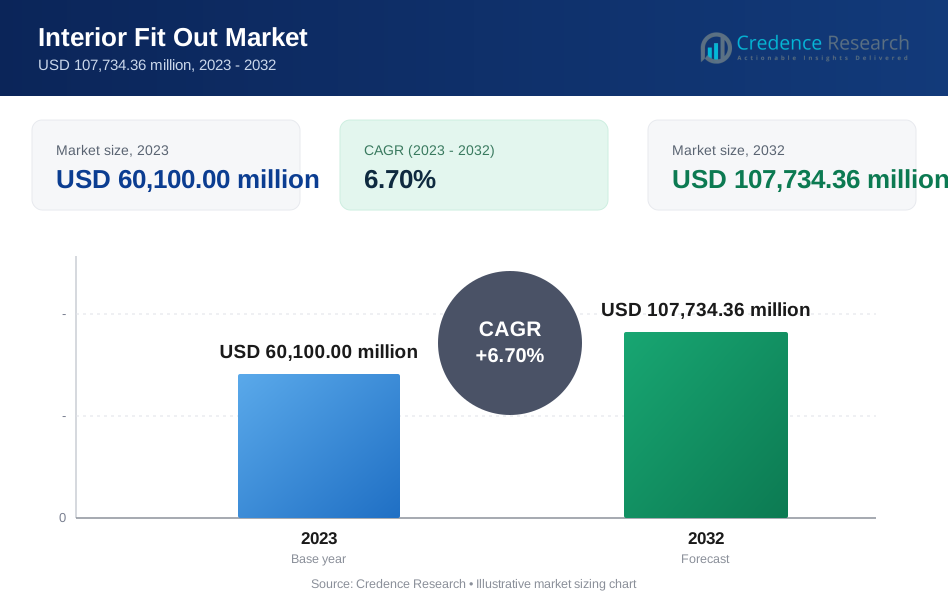
• The global interior fit-out market is projected to grow from USD 60,100.00 million in 2023 to USD 107,734.36 million by 2032, driven by a CAGR of 6.70% from 2024 to 2032. • Rising demand for aesthetically designed, functional spaces across commercial, residential, and industrial sectors is a major driver of market growth. • The integration of smart building technologies, IoT devices, and energy-efficient solutions is enhancing the functionality and appeal of interior fit-out services. • Growing emphasis on sustainable design practices and eco-friendly materials is fueling the adoption of green building standards in interior fit-out projects. • North America, Europe, and Asia Pacific are experiencing the highest growth, with robust urbanization, infrastructure development, and rising disposable incomes. • Rising raw material costs and supply chain disruptions pose significant challenges to market players, impacting project timelines and budgets. • A shortage of skilled labor in some regions is hindering project execution and delivery, affecting the overall market performance.Market Drivers:
Increasing Demand for Customized Spaces:
The growing trend toward personalization in both residential and commercial environments is a significant driver of the Interior Fit Out Market. As consumers seek unique designs that reflect their individual styles and brand identities, the demand for tailored interior fit-out solutions has surged. According to a report by the International Monetary Fund (IMF), there has been a marked increase in consumer spending on home renovations, with a reported growth of approximately 15% from 2020 to 2023. This trend highlights the shift towards customized spaces that cater to personal preferences and functional needs. For instance, a survey by the National Kitchen and Bath Association found that 60% of homeowners prefer custom designs for their kitchens and bathrooms, demonstrating the rising desire for tailored solutions.
Growth of the Real Estate Sector:
The rapid expansion of the real estate sector, particularly in emerging markets, has been a pivotal factor driving the Interior Fit Out Market. According to the World Bank, global urbanization rates are projected to reach 68% by 2050, significantly increasing the demand for residential and commercial properties. As new buildings are constructed and existing ones undergo renovations, the need for professional fit-out services is expected to grow correspondingly. For instance, data from the Asian Development Bank indicates that Southeast Asia's construction sector has seen an annual growth rate of 9% from 2019 to 2023, leading to a surge in opportunities for interior fit-out firms to enhance the functionality and aesthetic appeal of new and renovated spaces.
Emphasis on Workplace Wellness:
There is a growing recognition of the importance of workplace wellness, which has become a crucial factor in interior design and fit-out projects. Research by the World Health Organization (WHO) indicates that well-designed work environments can improve employee productivity by as much as 10%. This awareness has led businesses to invest in interior fit-outs that prioritize employee well-being, including features such as ergonomic furniture, natural lighting, and open spaces. For instance, a study by the Global Wellness Institute found that companies focusing on wellness-centric designs reported a 25% reduction in employee turnover, along with a 30% increase in employee satisfaction. As more organizations seek to create healthy work environments, the demand for innovative interior fit-out solutions that support these goals is expected to rise significantly.
Technological Advancements in Interior Design:
Technological advancements are revolutionizing the interior design and fit-out industry, offering new tools and techniques that enhance design efficiency and effectiveness. The integration of Building Information Modelling (BIM) and Virtual Reality (VR) technologies allows for more accurate planning and visualization of interior spaces, significantly reducing project timelines and costs. According to a report by the McKinsey Global Institute, companies that have adopted these technologies have seen productivity improvements of up to 30% in project execution. For instance, a survey conducted by the American Institute of Architects revealed that 40% of firms utilizing BIM reported a significant decrease in design conflicts and rework, leading to smoother project flows and faster delivery times. As these technologies become more accessible, the demand for technologically enhanced fit-out services is expected to increase, driving growth in the market.
Market Trends:
Sustainable Design Practices:
One of the most notable trends in the Interior Fit Out Market is the increasing emphasis on sustainable design practices. As awareness of environmental issues grows, both consumers and companies are prioritizing eco-friendly materials and energy-efficient designs. Government initiatives, such as those outlined by the United Nations Environment Programme (UNEP), encourage sustainable building practices and emphasize the importance of reducing carbon footprints in construction and interior design. For instance, a report from the World Green Building Council states that green buildings can reduce energy consumption by up to 30% compared to traditional designs. Additionally, a survey by the U.S. Green Building Council revealed that 79% of construction firms now prioritize sustainable design, indicating a significant shift towards eco-friendly practices that resonate with environmentally conscious consumers.
Integration of Smart Technologies:
The integration of smart technologies into interior design is another key trend reshaping the Interior Fit Out Market. As the Internet of Things (IoT) continues to evolve, more interior spaces are being equipped with smart devices that enhance convenience, security, and energy efficiency. According to a report by the International Energy Agency (IEA), smart technologies in buildings can lead to energy savings of 10-30%. Companies are increasingly adopting these innovations to improve user experience and operational efficiency. For instance, the U.S. Department of Energy has highlighted several projects where smart systems, such as automated lighting and climate control, have significantly improved the sustainability and functionality of interior spaces. Moreover, a study by the Consumer Technology Association found that 50% of consumers are willing to invest in smart home technologies, showcasing a growing demand for technologically advanced environments that drive transformation in the industry.
Market Challenges Analysis:
Rising Material Costs:
One of the significant challenges facing the Interior Fit Out Market is the rising cost of materials. Fluctuations in the prices of raw materials, such as wood, steel, and glass, have been exacerbated by global supply chain disruptions and geopolitical tensions. According to the World Bank, the price of construction materials has seen a notable increase of over 30% in the past few years, driven by factors such as tariffs, transportation costs, and increased demand in the wake of post-pandemic recovery. This surge in material costs places a strain on project budgets, compelling interior fit-out firms to reassess their pricing strategies and project scopes. Companies may find themselves needing to compromise on quality or reduce project sizes to stay within budget, which can lead to dissatisfaction among clients seeking high-quality, customized solutions. Furthermore, these rising costs can deter potential clients from initiating new projects or renovations, leading to a slowdown in market growth.
Skilled Labor Shortages:
Another pressing challenge in the Interior Fit Out Market is the ongoing shortage of skilled labor. As the demand for specialized interior design and fit-out services continues to grow, the industry faces a significant gap in the availability of qualified professionals. According to data from the U.S. Bureau of Labor Statistics, the construction sector is expected to see a demand for approximately 1.2 million new workers each year over the next decade, but the industry is struggling to attract and retain talent. This shortage of skilled labor not only hinders project timelines but also impacts the overall quality of work, as firms may need to hire less experienced workers or rely on subcontractors. Additionally, the increasing complexity of fit-out projects, which often require specialized knowledge of sustainable practices and smart technologies, further complicates the recruitment process. As companies grapple with these challenges, they may face higher labor costs and increased competition for skilled workers, ultimately affecting their ability to deliver projects on time and within budget.
Market Segmentation Analysis:
By Type
The Interior Fit Out Market can be segmented based on the type of fit-out services offered. The primary categories include hard fit-out and soft fit-out. Hard fit-out refers to the structural elements of an interior space, encompassing walls, flooring, and ceilings. This type of fit-out is critical for creating functional layouts and ensuring compliance with building codes. On the other hand, soft fit-out focuses on the furnishings and decorative aspects, including furniture, fixtures, and artwork. As trends shift towards personalization and comfort, the demand for soft fit-out services is increasing. Many companies are opting for a mix of both types to create holistic environments that meet both aesthetic and functional needs.
By Technology
Technological advancements are reshaping the Interior Fit Out Market, with significant segmentation based on the technologies employed. Key categories include traditional methods, Building Information Modeling (BIM), and smart technologies. Traditional methods rely on manual processes for design and execution, which may limit efficiency and flexibility. In contrast, BIM enables real-time collaboration among stakeholders, enhancing accuracy and reducing project timelines. Additionally, the integration of smart technologies, such as IoT devices and automated systems, is becoming increasingly prevalent. These technologies not only improve energy efficiency but also enhance user experience, making spaces more adaptable to occupant needs. The adoption of these advanced technologies is a key factor in driving innovation and efficiency within the market.
By End-User
The Interior Fit Out Market can also be segmented by end-user industries, which include residential, commercial, and institutional sectors. The residential segment encompasses private homes and apartments, where consumers seek personalized designs that reflect their individual tastes. The commercial segment includes offices, retail spaces, and hospitality establishments, where the focus is often on creating functional and inviting environments that enhance customer and employee experiences. The institutional segment covers educational facilities, healthcare environments, and government buildings, which require fit-out solutions that prioritize safety, accessibility, and compliance with regulations. As diverse needs arise across these sectors, the demand for tailored fit-out solutions continues to grow, driving market expansion.
Segmentations:
Based on Type:
- Hard Fit-Out
- Soft Fit-Out
Based on Technology:
- Traditional Methods
- Building Information Modeling (BIM)
- Smart Technologies
Based on End-User:
- Residential
- Commercial
- Institutional
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Interior Fit Out Market, accounting for approximately 35% of the total market share. The region's robust economy, coupled with a well-established construction industry, drives demand for both residential and commercial fit-out projects. The United States, in particular, is at the forefront, where rising consumer spending on home renovations and office space optimization is evident. A growing trend towards sustainable and smart interior solutions is also influencing market dynamics. Government initiatives and incentives aimed at promoting green building practices have further encouraged investments in eco-friendly fit-out solutions. Major cities like New York and San Francisco are seeing a surge in projects that prioritize innovative designs and sustainability, reflecting the region's commitment to creating high-quality interior environments.
Europe
Europe accounts for around 30% of the Interior Fit Out Market, driven by increasing urbanization and a strong focus on sustainable development. Countries such as Germany, the United Kingdom, and France are leading the charge, with significant investments in both residential and commercial sectors. The European Union's regulations promoting energy-efficient buildings are prompting businesses and homeowners alike to seek professional fit-out services that meet these standards. Additionally, the rise of remote work has led to a transformation in office layouts, driving demand for flexible and functional workspaces. Cities like London and Berlin are becoming hubs for innovative interior design solutions, showcasing a blend of modern aesthetics and sustainability. The emphasis on well-being in work environments has also led to increased interest in fit-out services that incorporate biophilic design principles.
Asia-Pacific
The Asia-Pacific region is rapidly emerging as a key player in the Interior Fit Out Market, capturing approximately 25% of the market share. With rapid urbanization and economic growth, countries like China, India, and Japan are witnessing a surge in demand for interior fit-out solutions. The expanding middle class in these nations is driving the demand for personalized residential spaces, while the commercial sector is booming due to increased foreign investment and infrastructure development. For instance, in China, government initiatives aimed at urban renewal and modernization are spurring significant construction activities, resulting in a higher demand for fit-out services. India is also experiencing robust growth, with rising investments in commercial real estate and a focus on modernizing office environments. Moreover, the integration of smart technologies and sustainable practices is gaining traction, with more companies looking to enhance their operational efficiency and minimize environmental impact. The Asia-Pacific region's diverse demographics and varying consumer preferences present both challenges and opportunities for fit-out service providers, making it a dynamic market to watch.
Key Players:
- Interiors by Design
- Turner Construction Company
- Haworth Inc.
- Gensler
- KPF (Kohn Pedersen Fox Associates)
- IKEA
- M Moser Associates
- Flad Architects
- JLL (Jones Lang LaSalle)
- Cushman & Wakefield
Competitive Analysis:
The Interior Fit Out Market is characterized by a competitive landscape featuring several key players that differentiate themselves through innovation, service quality, and specialization. Companies like Gensler and Turner Construction are at the forefront, leveraging their extensive experience and strong reputations in both commercial and residential sectors. Their ability to integrate sustainable practices into fit-out projects is a significant competitive advantage, especially as eco-conscious consumers demand greener solutions. Meanwhile, firms such as Haworth and IKEA focus on providing customizable and modular designs, catering to a wide range of consumer preferences and budget constraints. In contrast, niche players like M Moser Associates specialize in specific sectors, such as healthcare and technology, allowing them to command a strong position through tailored services. The rise of smart technologies has also introduced new competitors, as companies increasingly adopt IoT solutions to enhance user experiences in fit-out projects. Furthermore, the market is seeing increased collaboration among firms, with strategic partnerships enabling companies to expand their service offerings and geographical reach. As the demand for innovative, efficient, and sustainable interior spaces continues to grow, companies that can adapt quickly and respond to changing consumer preferences will have a significant competitive edge. Overall, the competitive dynamics in the Interior Fit Out Market are driven by a combination of established players and emerging firms, all striving to meet the evolving needs of clients.
Recent Developments:
- In September 2023, Herman Miller introduced the Fuld Nesting Chair, designed in collaboration with Stefan Diez. This sleek, minimalist chair enables flexible configurations for modern workspaces.
- In 2022, Steelcase launched the Flex furniture line, which creates adaptable work environments. This line features modular components that users can easily reconfigure to suit various needs.
- Also in 2022, Haworth unveiled the LiveWork furniture line, promoting collaboration and creativity in the workplace. This line includes open collaborative spaces and various amenities to enhance comfort and productivity.
- In 2022, HOK acquired AREEN Design Services, a prominent interior fit-out firm in the Middle East. This acquisition will enable HOK to strengthen its presence in the region.
Market Concentration & Characteristics:
The Interior Fit Out Market exhibits a moderate level of concentration, characterized by a mix of large, established firms and numerous smaller, specialized companies. Major players, such as Gensler and Turner Construction, dominate the market due to their extensive resources, brand recognition, and ability to handle large-scale projects across various sectors. These firms often leverage advanced technologies and sustainable practices, which are increasingly sought after by clients. However, the presence of numerous smaller firms allows for a diverse range of services and customization options, catering to niche markets and regional preferences. This fragmentation fosters healthy competition, driving innovation and responsiveness to emerging trends, such as the demand for smart technologies and sustainable design solutions. Additionally, client expectations are evolving, leading to a greater emphasis on collaboration and transparency in the fit-out process. Companies are increasingly adopting client-centric approaches, ensuring that projects align closely with specific needs and preferences. As a result, the market is characterized by a dynamic interplay between large firms seeking to expand their market share and smaller companies carving out their unique positions through specialization and tailored services. Overall, the Interior Fit Out Market reflects a balance of concentration and diversity, facilitating a competitive environment that encourages innovation and adaptability.
Report Coverage:
This report provides a comprehensive analysis of the Interior Fit Out Market, encompassing a wide range of key factors that influence its growth and dynamics. It covers various market segments, including by type, technology, end-user, and region, offering detailed insights into the trends and demands shaping the industry. The report examines the competitive landscape, highlighting the strategies employed by leading players and emerging firms alike, along with their market share and positioning. Additionally, it explores the impact of economic factors, regulatory frameworks, and technological advancements on market growth. Regional analyses focus on North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa, providing valuable context regarding local market conditions and opportunities. Furthermore, the report delves into market challenges, such as rising material costs and skilled labor shortages, while also discussing key drivers like increasing demand for sustainable and customized solutions. With in-depth insights and data-driven forecasts, this report serves as a vital resource for stakeholders looking to navigate the complexities of the Interior Fit Out Market, identify growth opportunities, and make informed strategic decisions. By synthesizing industry trends, consumer preferences, and competitive dynamics, the report aims to equip readers with the knowledge necessary to thrive in this evolving landscape.
Future Outlook:
- Companies will increasingly prioritize sustainable practices in fit-out projects to meet growing environmental concerns.
- The demand for smart technologies will rise, enhancing automation and user experience in interior spaces.
- Customization will remain a key focus as consumers seek personalized and functional design solutions.
- Collaboration between design firms and technology providers will expand, driving innovation and efficiency in project execution.
- The integration of biophilic design elements will gain traction, promoting well-being in residential and commercial environments.
- Companies will leverage data analytics to better understand consumer preferences and optimize design strategies.
- Remote work trends will continue to influence office layouts, emphasizing flexibility and adaptability in commercial spaces.
- Emerging markets in Asia-Pacific will present significant growth opportunities due to urbanization and rising disposable incomes.
- Investment in workforce training and development will become essential to address skilled labor shortages in the industry.
- Regulatory frameworks will evolve, pushing firms to adopt more rigorous standards for sustainability and safety in interior fit-out projects.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Customization and Personalization Demand
Consumers and businesses are increasingly seeking tailored interior spaces that reflect unique styles and functional needs, driving demand for bespoke fit-out solutions across residential and commercial sectors.
Growth in Real Estate and Renovation Activities
Rapid urbanization, rising investments in new construction, and a surge in renovation projects - especially in emerging markets - are significantly boosting the need for interior fit-out services.
Emphasis on Workplace Wellness
Organizations are investing in fit-out solutions that enhance employee well-being and productivity, such as ergonomic designs and biophilic elements, fueling market growth in the commercial segment.
Technological Advancements
The adoption of Building Information Modeling (BIM), Virtual Reality, and smart technologies is streamlining project execution, improving design accuracy, and enabling more innovative and efficient fit-out solutions.
Sustainable and Green Building Practices
Growing environmental awareness and regulatory pressures are pushing both clients and providers to prioritize eco-friendly materials and energy-efficient designs, increasing demand for sustainable fit-out services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current valuation of the Interior Fit Out Market?
What is the projected growth rate of the Interior Fit Out Market?
What factors are driving the growth of the Interior Fit Out Market?
Which regions are leading in the Interior Fit Out Market?
How does urbanization impact the Interior Fit Out Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Hard Fit-Out
- 1.2.2 Soft Fit-Out
- 1.3 By End-User
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Institutional
- 1.4 By Technology
- 1.4.1 Traditional Methods
- 1.4.2 Building Information Modeling (BIM)
- 1.4.3 Smart Technologies
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 60,100.00 million → 2032: USD 107,734.36 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Interior Fit Out Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Interior Fit Out Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Interior Fit Out Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Interior Fit Out Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Interior Fit Out Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Interior Fit Out Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Interior Fit Out Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Interior Fit Out Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 60,100.00 million → 2032: USD 107,734.36 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Interior Fit Out Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hard Fit-Out
- 12.3.7.2 Soft Fit-Out
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Institutional
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Traditional Methods
- 12.5.7.2 Building Information Modeling (BIM)
- 12.5.7.3 Smart Technologies
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Interior Fit Out End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Interior Fit Out Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Interior Fit Out Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Interior Fit Out Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Gensler
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Turner Construction Company
- 18.4 Haworth Inc.
- 18.5 IKEA
- 18.6 M Moser Associates
- 18.7 JLL (Jones Lang LaSalle)
- 18.8 Cushman & Wakefield
- 18.9 KPF (Kohn Pedersen Fox Associates)
- 18.10 Flad Architects
- 18.11 Interiors by Design
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

