
IV Infusion Pump Accessories Market Overview:
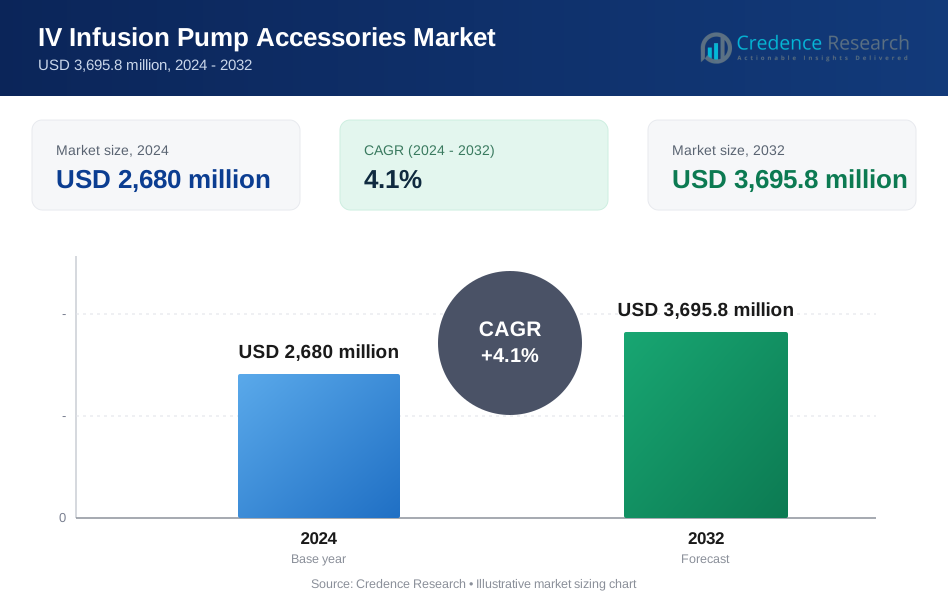
The IV Infusion Pump Accessories Market size was valued at USD 2,680 million in 2024 and is anticipated to reach USD 3,695.8 million by 2032, at a CAGR of 4.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| IV Infusion Pump Accessories Market Size 2024 | USD 2,680 million |
| IV Infusion Pump Accessories Market, CAGR | 4.1% |
| IV Infusion Pump Accessories Market Size 2032 | USD 3,695.8 million |
IV Infusion Pump Accessories Market Insights
- Market growth is driven by rising hospitalization rates, increasing surgical volumes, and expanding use of intravenous therapies for chronic disease management across hospitals and homecare settings.
- Key trends include growing adoption of smart infusion systems and needleless connectors, while IV infusion sets dominated by product type with a 34.6% share in 2024 due to routine and high-frequency usage.
- Leading players focus on broad accessory portfolios, safety compliance, infection prevention solutions, and long-term supply contracts, while pricing pressure and regulatory compliance remain key restraints.
- North America led with a 38.4% market share in 2024, followed by Europe at 27.1% and Asia Pacific at 22.6%, supported by advanced infrastructure, expanding healthcare access, and rising infusion therapy demand.

IV Infusion Pump Accessories Market Segmentation Analysis:
By Product Type:
The IV Infusion Pump Accessories Market by product type is led by IV infusion sets, which accounted for 34.6% market share in 2024, supported by their routine use across continuous, intermittent, and patient-controlled infusion therapies. Strong demand is driven by rising hospital admissions, increasing prevalence of chronic diseases requiring long-term intravenous therapy, and standardized replacement protocols to prevent infection risks. IV infusion lines and needleless connectors also contribute steadily due to safety mandates and compatibility with advanced infusion pumps. Growth across this segment is further reinforced by regulatory emphasis on infection control and expanding use of smart infusion systems in acute care settings.
- For instance, B. Braun's Intrafix SafeSet IV administration set includes an AirStop membrane that ensures the tubing remains filled with fluid during priming, acting as a particle filter with 15μm efficiency to reduce air infusion and infection risks.
By End User:
By end user, hospitals dominated the IV Infusion Pump Accessories Market with a 57.2% share in 2024, reflecting their high procedure volumes, intensive care utilization, and continuous need for infusion therapy in critical and post-surgical care. The dominance is driven by advanced infrastructure, higher adoption of infusion pumps, and strict compliance with safety and quality standards. Homecare settings are expanding due to rising outpatient care and chronic disease management, while ambulatory surgical centers gain traction from increasing minimally invasive procedures, collectively supporting sustained demand across diverse healthcare delivery environments.
- For instance, Baxter's Flo-Gard 6201 volumetric pump supports hospital-wide use with features like automatic occlusion restart and flow rates from 1-1999 mL/hr for fluids including blood emulsions.
Key Growth Drivers
Rising Hospitalization and Surgical Volumes
The IV Infusion Pump Accessories Market continues to expand due to increasing hospitalization rates and growing volumes of surgical procedures across healthcare systems. The rising burden of chronic diseases, including cancer, cardiovascular disorders, and renal conditions, has increased dependence on intravenous therapies for medication delivery, hydration, and nutrition. Higher admissions in intensive care units and postoperative recovery wards further elevate consumption of infusion sets, catheters, and cannulas. Additionally, expanding healthcare infrastructure in emerging economies and improved access to advanced medical treatments continue to reinforce sustained demand for IV infusion pump accessories.
- For instance ,ICU Medical's Plum Duo infusion pump, cleared by the FDA in 2023, features a dual-channel design enabling concurrent delivery of up to four compatible IV medications at independent rates, with LifeShield software for cloud-based drug library management.
Expansion of Homecare and Outpatient Infusion Therapy
The rapid shift toward homecare and outpatient treatment settings is a major growth driver for the IV Infusion Pump Accessories Market. Healthcare providers increasingly promote home-based infusion therapies to reduce treatment costs and hospital burden while enhancing patient comfort. Chronic disease management, chemotherapy, antibiotic therapy, and parenteral nutrition increasingly rely on portable infusion pumps and disposable accessories. This transition drives demand for easy-to-use, safe, and infection-resistant accessories suitable for non-hospital environments, supporting steady market growth across both developed and emerging regions.
- For instance, B. Braun's Infusomat Space pump, weighing 3 pounds with 8-hour battery life at 25 mL/hr, suits portable homecare via modular stacking and anti-free-flow protection paired with dedicated disposables like filtered sets.
Growing Focus on Infection Control and Patient Safety
Heightened emphasis on infection prevention and patient safety significantly supports growth in the IV Infusion Pump Accessories Market. Healthcare institutions are adopting advanced accessories designed to reduce catheter-related bloodstream infections and needlestick injuries. Needleless connectors, closed infusion systems, and antimicrobial-coated catheters are gaining widespread adoption due to stringent regulatory requirements and hospital accreditation standards. Frequent replacement of sterile accessories further fuels recurring demand. This strong focus on safety compliance enhances clinical outcomes while driving consistent procurement of high-quality infusion pump accessories.
Key Trends & Opportunities
Adoption of Smart Infusion Technologies and Compatible Accessories
The increasing deployment of smart infusion pumps represents a major trend and opportunity within the IV Infusion Pump Accessories Market. Healthcare providers are integrating dose-error reduction systems and automated drug libraries to improve medication accuracy. This has created rising demand for accessories that ensure seamless compatibility, precise flow control, and enhanced safety performance. Manufacturers are investing in innovation to develop accessories aligned with digital infusion platforms, offering opportunities for product differentiation, long-term supply contracts, and deeper integration within hospital infusion ecosystems.
- For instance, Baxter's SIGMA Spectrum Infusion Pump features a Master Drug Library with up to 5,000 drugs across 32 care areas, including upper/lower soft and hard limits plus starting rates for precise programming.
Growth Opportunities in Emerging Healthcare Markets
Emerging economies present strong growth opportunities for the IV Infusion Pump Accessories Market due to rapid healthcare infrastructure development and rising medical expenditure. Expansion of hospitals, diagnostic centers, and ambulatory care facilities increases demand for infusion-related accessories. Government investments in public healthcare systems, combined with growing awareness of infection prevention standards, are accelerating adoption of quality-certified accessories. Local manufacturing initiatives and cost-effective product offerings further enable market penetration, positioning emerging regions as key contributors to future market growth.
- For instance, B. Braun has strengthened its presence in India by supplying the Infusomat Space volumetric infusion pump alongside compatible accessories like Intrafix IV sets, supporting expanded ICU capacities where three to four pumps per bed are now standard.
Key Challenges
Pricing Pressure and Cost Sensitivity in Healthcare Procurement
The IV Infusion Pump Accessories Market faces significant challenges from pricing pressure and cost-sensitive procurement practices. Hospitals and healthcare providers increasingly negotiate bulk contracts and prioritize low-cost suppliers to manage operational expenses. This limits pricing flexibility for manufacturers and compresses profit margins, particularly for disposable accessories with high replacement frequency. Competitive bidding processes further intensify price competition, making it difficult for premium product offerings to achieve widespread adoption without clear cost-benefit justification.
Regulatory Compliance and Product Standardization Constraints
Stringent regulatory requirements and product standardization pose notable challenges in the IV Infusion Pump Accessories Market. Accessories must comply with varying international safety, sterility, and quality standards, increasing development time and compliance costs. Frequent updates to regulatory frameworks require continuous product validation and documentation, slowing market entry for new products. Additionally, compatibility requirements across different infusion pump brands limit design flexibility, creating technical and operational barriers for manufacturers seeking to expand their product portfolios globally.
Regional Analysis
North America
North America accounted for 38.4% market share in 2024 in the IV Infusion Pump Accessories Market, supported by advanced healthcare infrastructure and high adoption of infusion therapies across hospitals and homecare settings. Strong demand is driven by a high prevalence of chronic diseases, extensive use of infusion pumps in critical care, and strict infection control regulations. The region benefits from continuous technological innovation and rapid adoption of needleless connectors and antimicrobial accessories. Favorable reimbursement policies and strong presence of leading medical device manufacturers further reinforce sustained market growth across the United States and Canada.
Europe
Europe held 27.1% market share in 2024 in the IV Infusion Pump Accessories Market, driven by widespread access to universal healthcare systems and rising surgical volumes. Increasing focus on patient safety and infection prevention has accelerated adoption of advanced infusion accessories across hospitals and ambulatory care centers. Countries such as Germany, France, and the United Kingdom contribute significantly due to strong regulatory compliance and standardized treatment protocols. Growing demand from aging populations and expanded outpatient care services continues to support stable market expansion across both Western and Eastern European healthcare markets.
Asia Pacific
Asia Pacific captured 22.6% market share in 2024 in the IV Infusion Pump Accessories Market, reflecting rapid expansion of healthcare infrastructure and increasing patient volumes. Rising prevalence of chronic diseases, growing medical tourism, and government investments in hospital development drive accessory demand. Countries including China, India, and Japan are witnessing increased adoption of infusion therapies in both public and private healthcare facilities. Expanding access to affordable medical devices and improving awareness of infection control standards further support strong growth potential across the region.
Latin America
Latin America accounted for 7.1% market share in 2024 in the IV Infusion Pump Accessories Market, supported by gradual improvements in healthcare infrastructure and rising hospital admissions. Increasing incidence of chronic diseases and expanding surgical procedures drive demand for infusion accessories across hospitals and diagnostic centers. Brazil and Mexico lead regional adoption due to higher healthcare spending and expanding private healthcare sectors. Growing focus on patient safety and modernization of medical equipment continues to support steady market growth across the region.
Middle East & Africa
The Middle East & Africa region held 4.8% market share in 2024 in the IV Infusion Pump Accessories Market, driven by expanding hospital capacity and rising investment in healthcare modernization. Growth is supported by increasing demand for infusion therapy in acute and critical care settings, particularly in Gulf Cooperation Council countries. Government initiatives to improve healthcare access and infection control standards are boosting adoption of quality-certified infusion accessories. Although infrastructure disparities persist, gradual expansion of private healthcare facilities supports long-term regional market development.
IV Infusion Pump Accessories Market Segmentations:
By Product Type
- IV Infusion Set
- IV Infusion Lines
- IV Catheters
- IV Cannulas
- Needleless Connectors
By End User
- Hospitals
- Homecare Settings
- Ambulatory Surgical Centers
- Diagnosis Center
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the IV Infusion Pump Accessories Market includes key players such as B. Braun Melsungen AG, Baxter International Inc., Becton, Dickinson & Company, ICU Medical, Inc., Terumo Corporation, Fresenius Kabi, Smiths Medical, Teleflex, Inc., Nipro Corporation, and Moog Inc. The market is moderately consolidated, with leading companies competing through broad product portfolios covering infusion sets, lines, catheters, cannulas, and needleless connectors. Players focus on product reliability, safety compliance, and compatibility with advanced infusion pump systems to strengthen market presence. Strategic initiatives include expansion of manufacturing capacities, continuous product innovation to address infection prevention, and long-term supply contracts with hospitals and group purchasing organizations. Companies also emphasize geographic expansion in emerging healthcare markets and cost-optimized offerings to address pricing pressure, while maintaining strict adherence to regulatory and quality standards to sustain competitive positioning.
Key Player Analysis
- B. Braun Melsungen AG
- Smiths Medical (Smiths Group plc)
- Terumo Corporation
- Becton, Dickinson & Company (BD)
- ICU Medical, Inc.
- Teleflex, Inc.
- Nipro Corporation
- Fresenius Kabi
- Moog Inc.
- Baxter International Inc.
Recent Developments
- In November 2024, ICU Medical and Otsuka Pharmaceutical Factory announced a joint venture to enhance IV solutions manufacturing and innovation, combining ICU Medical's infusion pumps and consumables with Otsuka's global production scale for North American supply resiliency.
- In April 2024, Baxter received U.S. FDA clearance for its Novum IQ large volume infusion pump with Dose IQ Safety Software, expanding its integrated platform for safer infusion therapy across clinical settings.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand steadily, supported by rising demand for intravenous therapies across acute, chronic, and emergency care settings.
- Increasing adoption of infusion pumps in homecare and outpatient environments will strengthen long-term demand for compatible accessories.
- Hospitals will remain the primary end users, driven by high patient volumes and stringent infection control requirements.
- Growing emphasis on patient safety will accelerate adoption of needleless connectors and closed infusion systems.
- Technological integration with smart infusion pumps will drive innovation in accessory design and compatibility.
- Expanding geriatric populations will increase reliance on long-term infusion therapies.
- Emerging economies will witness faster adoption due to healthcare infrastructure development and improved access to medical devices.
- Manufacturers will focus on cost-efficient and disposable accessories to address pricing pressure and procurement challenges.
- Regulatory compliance and quality certification will remain critical for market participation and expansion.
- Strategic partnerships and supply agreements with healthcare providers will shape competitive positioning over the forecast period.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Hospitalization and Surgical Volumes
Increasing rates of hospital admissions and surgical procedures, especially for chronic disease management, are driving higher consumption of IV infusion pump accessories in both acute and post-surgical care settings.
Expansion of Homecare and Outpatient Infusion Therapy
The shift toward home-based and outpatient intravenous therapies for chronic conditions is boosting demand for portable, easy-to-use, and infection-resistant accessories compatible with infusion pumps outside traditional hospital environments.
Growing Focus on Infection Control and Patient Safety
Stringent infection prevention protocols and regulatory mandates are accelerating the adoption of advanced accessories such as needleless connectors and antimicrobial-coated components, supporting recurring demand for high-quality, sterile products.
Adoption of Smart Infusion Technologies
The integration of smart infusion pumps with dose-error reduction and automated drug libraries is increasing the need for compatible, technologically advanced accessories that ensure precise medication delivery and enhance patient safety.
Healthcare Infrastructure Development in Emerging Markets
Rapid expansion of hospitals and healthcare facilities in emerging economies, along with increased government investment and awareness of infection control, is fueling market growth for IV infusion pump accessories in these regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for IV Infusion Pump Accessories Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the IV Infusion Pump Accessories Market projected to grow between 2024 and 2032?
Which IV Infusion Pump Accessories Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the IV Infusion Pump Accessories Market?
Who are the leading companies in the IV Infusion Pump Accessories Market?
Which region commanded the largest share of the IV Infusion Pump Accessories Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Homecare Settings
- 1.2.3 Ambulatory Surgical Centers
- 1.2.4 Diagnosis Center
- 1.2.5 Others
- 1.3 By Product Type
- 1.3.1 IV Infusion Set
- 1.3.2 IV Infusion Lines
- 1.3.3 IV Catheters
- 1.3.4 IV Cannulas
- 1.3.5 Needleless Connectors
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,680 million → 2032: USD 3,695.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global IV Infusion Pump Accessories Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global IV Infusion Pump Accessories Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global IV Infusion Pump Accessories Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global IV Infusion Pump Accessories Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global IV Infusion Pump Accessories Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global IV Infusion Pump Accessories Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global IV Infusion Pump Accessories Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global IV Infusion Pump Accessories Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,680 million → 2032: USD 3,695.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global IV Infusion Pump Accessories Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Homecare Settings
- 12.3.7.3 Ambulatory Surgical Centers
- 12.3.7.4 Diagnosis Center
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 IV Infusion Set
- 12.4.7.2 IV Infusion Lines
- 12.4.7.3 IV Catheters
- 12.4.7.4 IV Cannulas
- 12.4.7.5 Needleless Connectors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global IV Infusion Pump Accessories End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global IV Infusion Pump Accessories Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global IV Infusion Pump Accessories Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global IV Infusion Pump Accessories Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 B. Braun Melsungen AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Baxter International Inc.
- 18.4 Becton, Dickinson & Company (BD)
- 18.5 ICU Medical, Inc.
- 18.6 Terumo Corporation
- 18.7 Fresenius Kabi
- 18.8 Smiths Medical (Smiths Group plc)
- 18.9 Teleflex, Inc.
- 18.10 Nipro Corporation
- 18.11 Moog Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

