
Market Overview:
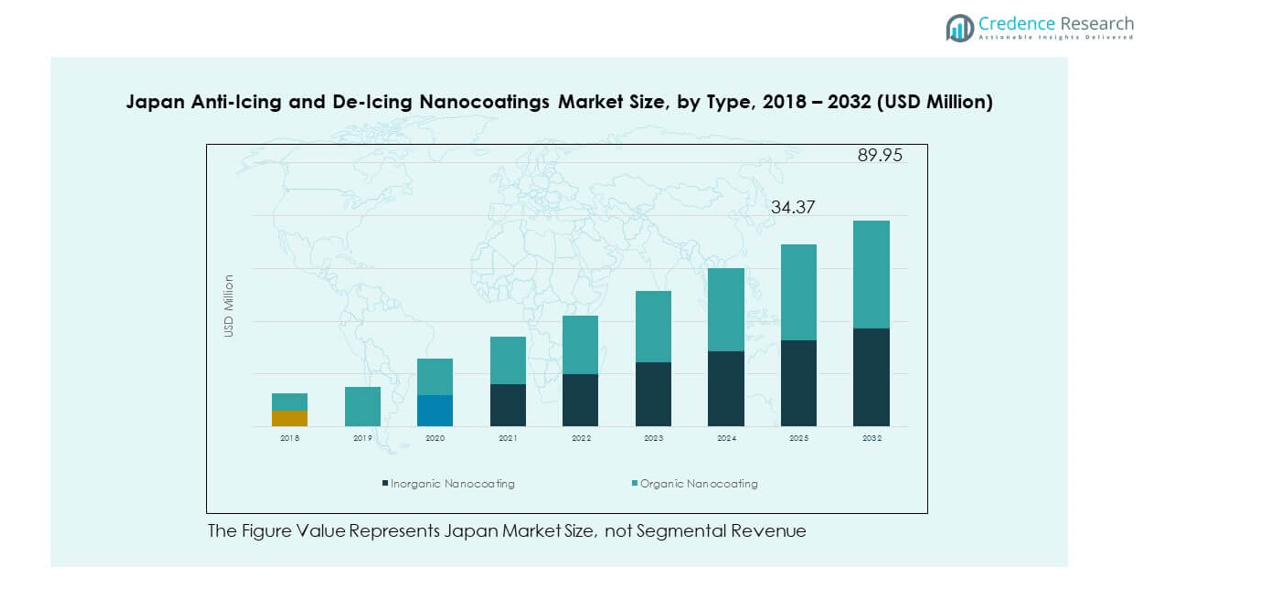
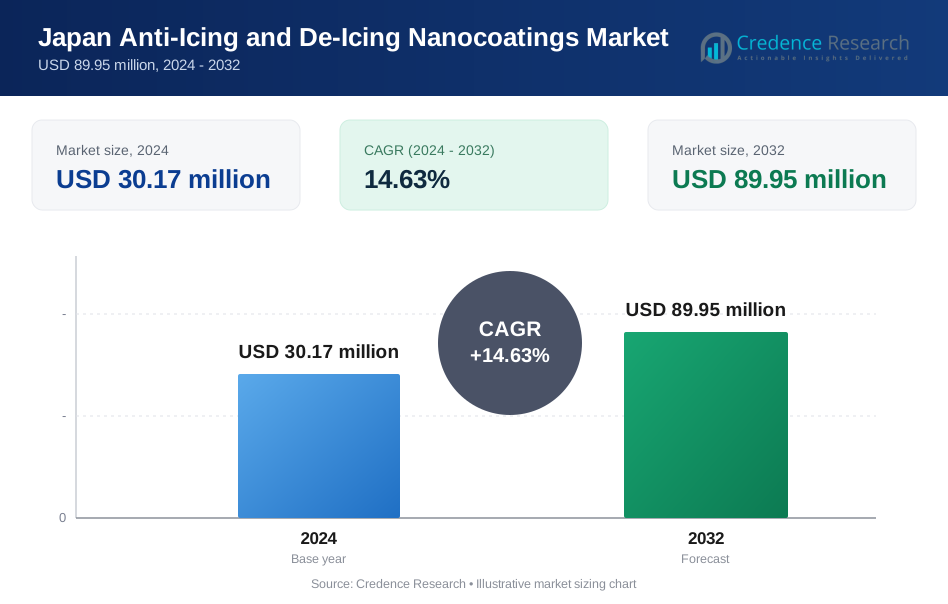
The Japan Anti-Icing and De-Icing Nanocoatings Market size was valued at USD 13.19 million in 2018 to USD 30.17 million in 2024 and is anticipated to reach USD 89.95 million by 2032, at a CAGR of 14.63% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Anti-Icing and De-Icing Nanocoatings Market Size 2024 | USD 30.17 million |
| Japan Anti-Icing and De-Icing Nanocoatings Market, CAGR | 14.63% |
| Japan Anti-Icing and De-Icing Nanocoatings Market Size 2032 | USD 89.95 million |
Growth in this market is strongly driven by the increasing demand for safer transportation and energy infrastructure. Aviation and automotive industries are focusing on advanced nanocoatings to reduce ice buildup and improve operational efficiency. Wind energy projects also rely on these coatings to ensure uninterrupted turbine function in cold climates. Government support for clean energy, coupled with the adoption of nanotechnology-based innovations, further accelerates the adoption of anti-icing and de-icing solutions across industries. This technological push is enhancing reliability and reducing downtime for critical assets.
Regionally, Japan leads the adoption of nanocoatings due to its advanced industrial base and strong focus on safety and energy efficiency. Other Asia-Pacific countries are emerging markets, particularly South Korea and China, which are rapidly expanding renewable energy projects and high-tech manufacturing. European nations remain key innovators, with a long history of applying nanotechnology in transportation and infrastructure. North America also shows steady adoption, supported by harsh weather conditions and regulatory emphasis on safety. Together, these regions are shaping the global competitive landscape, with Japan standing out for its early and focused integration of nanocoating technologies.
Market Insights:
- The Japan Anti-Icing and De-Icing Nanocoatings Market was valued at USD 13.19 million in 2018, reached USD 30.17 million in 2024, and is projected to attain USD 89.95 million by 2032, growing at a CAGR of 14.63%.
- Kanto held 42% share in 2024 due to its strong automotive and electronics base, Kansai secured 28% driven by renewable energy projects and manufacturing clusters, and Tohoku accounted for 19% supported by cold climate conditions and energy infrastructure.
- Tohoku is the fastest-growing region with 19% share, driven by high demand from wind farms, transportation, and infrastructure resilience against extreme winter conditions.
- Inorganic nanocoating represented the larger share in 2024, supported by adoption in aviation, automotive, and energy sectors requiring strong durability.
- Organic nanocoating accounted for a smaller but growing portion, supported by demand in textiles, packaging, and eco-friendly product development.
Market Drivers
Rising Demand for Safer and More Efficient Transportation and Infrastructure Systems
The Japan Anti-Icing and De-Icing Nanocoatings Market is expanding due to the strong demand for safety in transportation systems. Aviation companies are integrating these coatings to reduce ice-related disruptions and enhance flight safety. The automotive sector is also exploring nanocoatings for windshields and critical components to improve winter reliability. Wind energy operators seek advanced coatings to ensure uninterrupted turbine operations in harsh weather. Infrastructure projects rely on coatings to minimize maintenance and extend service life. Government incentives for technological upgrades further support adoption. It creates a pathway for industries to achieve operational efficiency. Strong collaboration between universities and industries fosters continuous innovation. Demand from diverse end-use sectors reinforces market growth.
- For instance, PPG has developed advanced anti-icing and hydrophobic coatings for aircraft windshields and transparencies, which are adopted by leading aerospace manufacturers to enhance safety and reduce maintenance requirements.
Increasing Investments in Renewable Energy and Clean Technology Expansion
Strong investments in renewable energy are fueling demand for advanced anti-icing solutions. Wind farms in northern Japan and coastal regions use nanocoatings to limit downtime. Energy security policies highlight the importance of uninterrupted generation from wind assets. The market gains momentum as operators adopt coatings to improve efficiency. It enables long-term performance while reducing maintenance costs. Renewable energy projects create new avenues for nanocoating suppliers. Partnerships with international technology providers bring advanced solutions into the local market. Strong public and private funding accelerates technology deployment. This alignment drives industry-wide transformation across the clean energy ecosystem.
- For instance, Mitsubishi Heavy Industries has developed and deployed wind turbines in Hokkaido designed to operate under cold climate conditions, where anti-icing technologies and materials are an essential focus for performance and reliability. Vestas has also conducted cold-climate wind turbine projects in Japan, where partnerships with local coating developers explore anti-icing and de-icing solutions to extend operational uptime during harsh winters.
Continuous Growth of Nanotechnology Research and Industry Collaboration
The research landscape in Japan continues to push the boundaries of nanotechnology innovation. Universities and corporate labs develop new formulations that increase coating durability and performance. The Japan Anti-Icing and De-Icing Nanocoatings Market benefits from this innovation ecosystem. It allows stakeholders to test and validate products across multiple industrial conditions. Collaborations reduce time-to-market and improve commercialization of solutions. Research institutions provide expertise, while manufacturers ensure scalable production. Strategic partnerships with aviation and energy firms ensure relevance of products. International collaboration strengthens competitive positioning in the global market. This driver sustains continuous progress in technology adoption.
Government Support and Regulatory Push for Safer and Sustainable Systems
Government initiatives encourage industries to adopt nanocoatings for public safety and environmental goals. Regulations highlight the need for efficient anti-icing solutions in transportation and energy. The Japan Anti-Icing and De-Icing Nanocoatings Market receives attention from policymakers aiming to reduce risks. It aligns with national safety standards and sustainability goals. Policies stimulate R&D funding and encourage commercialization of advanced coatings. Aviation, automotive, and energy sectors respond with active integration. Incentives for clean energy further amplify demand for protective coatings. Safety guidelines mandate high-performance solutions across industries. Government backing strengthens the foundation for long-term market expansion.
Market Trends
Emergence of Smart and Multi-Functional Nanocoatings with Integrated Capabilities
Smart coatings that combine anti-icing with other protective functions are gaining attention. Manufacturers develop solutions that offer hydrophobic, UV-resistant, and thermal properties. The Japan Anti-Icing and De-Icing Nanocoatings Market sees rising demand for multi-functional designs. It creates opportunities for integrated applications across transportation and infrastructure. Smart coatings reduce the need for multiple layers, improving cost-effectiveness. Companies focus on user-specific customization, enhancing adoption in different industries. Long-term durability and performance monitoring systems are included in new designs. Market leaders introduce coatings that address both safety and energy efficiency. This trend strengthens competitive advantage for innovators.
- For instance, AGC Inc. (Japan) has been developing advanced fluoropolymer-based coatings with hydrophobic and UV-resistant properties, aimed at enhancing durability and surface protection. These coatings are being researched for applications in transportation and energy sectors, where anti-icing performance and long-term reliability are critical under harsh weather conditions.
Growing Adoption of Eco-Friendly and Sustainable Nanocoating Formulations
Environmental concerns influence the shift toward sustainable coating solutions. Manufacturers are replacing harmful chemicals with eco-friendly alternatives. The Japan Anti-Icing and De-Icing Nanocoatings Market reflects this transformation through green formulations. It promotes alignment with global environmental goals and national sustainability initiatives. Biodegradable and non-toxic materials attract strong interest from regulators and industries. Market participants invest in R&D to develop coatings with low environmental impact. Consumer awareness of sustainability also drives demand for safer products. Renewable energy operators prioritize eco-friendly coatings for compliance and reputation. Sustainability-focused innovation is establishing long-term growth opportunities.
- For instance, Nippon Paint Holdings has advanced research in water-based nanocoatings that focus on reducing environmental impact by minimizing volatile organic compounds (VOCs) and eliminating harmful substances. These coatings are being developed for applications in renewable energy and infrastructure, where anti-icing performance and sustainability are increasingly critical in regions like northern Japan.
Increased Integration of Digital Monitoring and Performance Tracking Systems
The market is experiencing integration of digital monitoring tools with coating systems. Smart sensors track performance of coatings in real-time. The Japan Anti-Icing and De-Icing Nanocoatings Market benefits from enhanced predictive maintenance capabilities. It ensures consistent performance and timely intervention when degradation begins. Digital platforms collect data on environmental stress and material durability. Energy and transport operators adopt these systems to improve reliability. AI-driven analytics provide insights for improving product design. Real-time monitoring builds confidence among industrial users. Integration of digital tools represents a major shift in value delivery.
Expansion of Cross-Industry Applications Across Emerging Sectors
Nanocoatings are extending beyond aviation and energy into healthcare and construction. Advanced coatings find use in cold storage, biomedical devices, and specialized infrastructure. The Japan Anti-Icing and De-Icing Nanocoatings Market expands through diverse applications. It creates opportunities in non-traditional sectors looking for freeze protection. Construction firms adopt coatings to reduce ice hazards on exposed structures. Logistics and supply chain companies explore coatings for refrigerated assets. Biomedical research explores coatings for sensitive equipment exposed to frost. Industrial adoption across new sectors reflects market adaptability. This diversification trend opens pathways for long-term resilience.
Market Challenges Analysis
High Production Costs and Barriers to Large-Scale Commercial Adoption
High production costs remain a major challenge for widespread market adoption. Advanced nanocoating formulations involve expensive materials and complex processes. The Japan Anti-Icing and De-Icing Nanocoatings Market faces difficulties in achieving cost parity with traditional solutions. It limits accessibility for smaller operators in transportation and construction. High investment requirements also delay widespread infrastructure deployment. Pricing pressure forces companies to balance innovation with affordability. Manufacturers must address scale-up efficiency to meet broader demand. Limited standardization in production increases operational risk for suppliers. These cost-related barriers create resistance among budget-conscious industries.
Limited Awareness and Technical Integration Issues Across Industries
Another challenge is the limited awareness among potential end users. Many operators remain unfamiliar with advanced nanocoating benefits. The Japan Anti-Icing and De-Icing Nanocoatings Market encounters hesitation due to uncertain ROI. It creates slower adoption across small-scale energy and transport operators. Technical integration into existing systems often requires skilled expertise. Lack of standardized testing protocols complicates adoption for regulators and buyers. Industries demand proven case studies before committing to large-scale use. Training gaps also hinder adoption in new sectors. These issues must be addressed to unlock full market potential.
Market Opportunities
Rising Demand for Renewable Energy Resilience and Transportation Safety Enhancements
Opportunities are expanding due to the demand for resilient renewable energy systems. Wind farms adopt nanocoatings to improve efficiency and minimize downtime. The Japan Anti-Icing and De-Icing Nanocoatings Market benefits from growing investment in clean energy. It provides long-term opportunities for suppliers offering tailored solutions. Aviation safety upgrades also create consistent demand for advanced coatings. Strategic investments in transportation further increase adoption potential. Manufacturers that address cross-sector needs secure broader market penetration. Early adopters enjoy strong positioning in a fast-growing industry. Opportunities align with long-term sustainability and safety goals.
Expanding Scope of International Collaboration and Technology Transfer Initiatives
International collaboration offers a platform for knowledge and technology exchange. Partnerships with global firms enable faster development of high-performance coatings. The Japan Anti-Icing and De-Icing Nanocoatings Market benefits from these cooperative ventures. It improves access to cutting-edge research and advanced production methods. Technology transfer agreements open opportunities in aviation, energy, and construction. Cross-border projects encourage harmonized standards that promote adoption. Suppliers enhance their product portfolios through shared expertise. Collaborations also attract international funding and regulatory support. This opportunity strengthens competitiveness in the global market landscape.
Market Segmentation Analysis:
By type, the Japan Anti-Icing and De-Icing Nanocoatings Market is divided into inorganic nanocoating and organic nanocoating. Inorganic coatings dominate due to their durability, resistance to harsh weather, and strong adhesion on metals and composites. They are widely adopted in aviation, automotive, and wind energy applications where performance reliability is critical. Organic coatings are gaining ground for their flexibility, eco-friendly formulations, and potential in textiles and packaging. It demonstrates a balance between performance-driven inorganic solutions and sustainability-focused organic alternatives, supporting broad adoption across industries.
- For instance, Toppan Printing Co., Ltd. has been developing advanced functional coatings using inorganic materials such as titanium dioxide to enhance surface durability and performance in industrial applications, including potential use in aerospace and electronics.
By application, the market spans transportation, textiles, energy, electronics, food and packaging, and others. Transportation leads with demand from aviation and automotive sectors requiring consistent anti-icing solutions for safety and efficiency. Energy follows closely, with wind farms in colder regions seeking coatings to reduce downtime and improve turbine longevity. Electronics benefit from coatings that prevent condensation and protect sensitive components. Textiles and food packaging segments explore lightweight and eco-friendly coatings to enhance product safety and durability. It shows increasing adoption across diverse sectors, reflecting the versatility of nanocoating technologies and the strong alignment with Japan’s industrial and safety priorities.
- For instance, Kawasaki Heavy Industries has explored advanced material technologies, including surface treatments and coatings, to enhance the safety and reliability of its BK117 helicopters, where anti-icing capabilities are a priority for rotor blade performance in cold climates.
Segmentation:
By Type
- Inorganic Nanocoating
- Organic Nanocoating
By Application
- Transportation
- Textiles
- Energy
- Electronics
- Food & Packaging
- Others
Regional Analysis:
Kanto holds the largest share of the Japan Anti-Icing and De-Icing Nanocoatings Market, accounting for 42%. The region benefits from a strong concentration of automotive and electronics manufacturers, creating consistent demand for advanced protective solutions. Tokyo and its industrial zones drive adoption through integration in transport and infrastructure projects. Aviation hubs in the region also prioritize nanocoatings for safety and operational efficiency. It maintains a leading position by combining technological innovation with large-scale commercial deployment. Government-backed R&D investments in Kanto further accelerate the pace of adoption. The presence of multinational firms strengthens regional competitiveness.
Kansai represents 28% of the market share, supported by its diversified industrial base and robust manufacturing clusters. The region emphasizes renewable energy expansion, particularly in wind power projects requiring reliable anti-icing technologies. Osaka and Kyoto-based research institutions foster development of sustainable nanocoating formulations, enhancing competitiveness. Textiles and packaging industries in Kansai also integrate nanocoatings to boost product performance and resilience. It demonstrates steady growth by balancing traditional industries with emerging applications. The local government promotes collaborations between academia and industry to strengthen commercialization. This support ensures Kansai’s role as a strong growth contributor.
Tohoku holds 19% of the market, driven by its cold climate and reliance on energy infrastructure. Wind farms and transportation systems in this northern region depend heavily on anti-icing nanocoatings for reliability. It gains traction through regional initiatives focused on sustainable energy and safe mobility. Hokkaido and other northern prefectures contribute significantly by deploying coatings in extreme winter conditions. The market here expands steadily as infrastructure projects and energy operators increase adoption. Research collaborations with universities add value by testing coatings under real-world conditions. Other regions, including Chubu and Kyushu, account for the remaining 11%, reflecting niche adoption in electronics and industrial sectors.
Key Player Analysis:
- Battelle
- PPG
- Fraunhofer
- Hygratek
- Nanosonic
- Luna Innovations
- Nanovere Technologies
- NEI Corporation
- Cytonix
- Other Key Players
Competitive Analysis:
The Japan Anti-Icing and De-Icing Nanocoatings Market is characterized by strong competition among global leaders and domestic innovators. Established companies such as PPG, Battelle, and Fraunhofer focus on advanced product development and strategic collaborations to maintain leadership. These players emphasize durable and high-performance nanocoatings that address stringent safety requirements in aviation, automotive, and energy sectors. It strengthens competitiveness through continuous R&D investment, targeted acquisitions, and partnerships with Japanese manufacturers. Global companies leverage their international expertise, while tailoring solutions to local needs. Domestic firms and niche players such as Hygratek, Luna Innovations, and Nanovere Technologies contribute to the market by offering specialized formulations. Their agility enables faster adaptation to emerging applications in textiles, electronics, and packaging. The market also sees activity from research-driven institutions collaborating with industrial partners to enhance scalability and cost-effectiveness. It reflects a dynamic competitive landscape shaped by innovation, sustainability, and regulatory alignment. Intense rivalry encourages differentiation through eco-friendly solutions, multi-functional coatings, and digital monitoring integration. With both multinational corporations and regional innovators advancing their strategies, competition remains high across end-use industries.
Recent Developments:
- In September 2025, PPG announced a strategic partnership with Toyota Motor Europe to build long-term collaboration around coatings technologies. While the main partnership region is Europe, PPG's ongoing streamlining of its coatings portfolio and increased focus on global automotive innovations positions it for additional expansion in Japan’s nanocoatings segment.
- In August 2025, Battelle entered a collaboration with Nanotherm to launch Novara™, an advanced carbon nanotube-based heating solution aimed at automotive, industrial, and consumer applications. This agreement targets the fast-growing demand for thermal management technologies enabled by nanocoatings, supporting the expansion of next-generation anti-icing and de-icing solutions in global and Japanese markets.
Report Coverage:
The research report offers an in-depth analysis based on type and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for nanocoatings will increase in aviation and automotive industries focused on operational safety.
- Expansion of wind power projects in cold regions will reinforce adoption across the energy sector.
- Research institutions and corporate partnerships will accelerate development of more durable coating solutions.
- Eco-friendly and sustainable nanocoating formulations will gain importance in regulatory-driven markets.
- Digital monitoring and predictive maintenance integration will enhance long-term coating performance.
- Broader adoption in textiles and packaging industries will diversify application opportunities.
- Domestic players will strengthen competitiveness through niche innovation and faster commercialization.
- Global firms will continue expanding presence through collaborations with Japanese manufacturers.
- Government support for clean energy and infrastructure resilience will create favorable market conditions.
- The Japan Anti-Icing and De-Icing Nanocoatings Market will evolve into a multi-sector growth hub driven by safety, sustainability, and technology.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Japan Anti-Icing and De-Icing Nanocoatings Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Japan Anti-Icing and De-Icing Nanocoatings Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Japan Anti-Icing and De-Icing Nanocoatings Market?
Who are the leading companies in the Japan Anti-Icing and De-Icing Nanocoatings Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Anti-Icing and De-Icing Nanocoatings Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Anti-Icing and De-Icing Nanocoatings Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 30.17 million → 2032: USD 89.95 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Anti-Icing and De-Icing Nanocoatings Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Anti-Icing and De-Icing Nanocoatings Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Anti-Icing and De-Icing Nanocoatings Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Anti-Icing and De-Icing Nanocoatings Market Drivers
- 3.3 Japan Anti-Icing and De-Icing Nanocoatings Market Restraints & Challenges
- 3.4 Japan Anti-Icing and De-Icing Nanocoatings Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Anti-Icing and De-Icing Nanocoatings Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Anti-Icing and De-Icing Nanocoatings Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Anti-Icing and De-Icing Nanocoatings category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Anti-Icing and De-Icing Nanocoatings Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Anti-Icing and De-Icing Nanocoatings Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Anti-Icing and De-Icing Nanocoatings market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Anti-Icing and De-Icing Nanocoatings Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Anti-Icing and De-Icing Nanocoatings Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Anti-Icing and De-Icing Nanocoatings Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Anti-Icing and De-Icing Nanocoatings (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Anti-Icing and De-Icing Nanocoatings Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Anti-Icing and De-Icing Nanocoatings Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Anti-Icing and De-Icing Nanocoatings Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Anti-Icing and De-Icing Nanocoatings Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Anti-Icing and De-Icing Nanocoatings Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Anti-Icing and De-Icing Nanocoatings Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Anti-Icing and De-Icing Nanocoatings Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Anti-Icing and De-Icing Nanocoatings Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Anti-Icing and De-Icing Nanocoatings Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
