
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
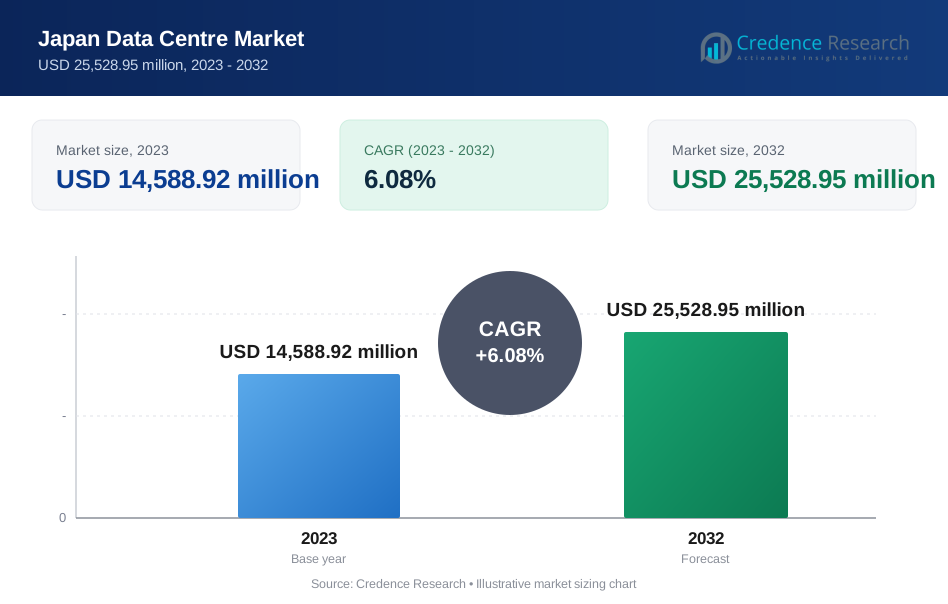
| Japan Data Centre MarketSize 2023 | USD 14,588.92 Million |
| Japan Data Centre Market, CAGR | 6.08% |
| Japan Data Centre Market Size 2032 | USD 25,528.95 Million |
Market Overview
The Japan Data Centre Market is projected to grow from USD 14,588.92 million in 2023 to USD 25,528.95 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.08%.
The Japan Data Centre Market is driven by increasing demand for cloud computing, digital transformation, and the rapid growth of data-intensive industries such as e-commerce, finance, and telecommunications. Rising adoption of IoT, AI, and big data analytics is further boosting the need for reliable and scalable data center infrastructure. Government initiatives supporting digital infrastructure development, along with a focus on sustainability and energy efficiency, are key trends shaping the market. Additionally, the growing use of edge computing and colocation services to reduce latency and improve operational efficiency is contributing to the market's expansion.
The Japan Data Centre Market is geographically dominated by Tokyo, which holds the largest market share due to its advanced digital infrastructure and concentration of global enterprises. Osaka is the second-largest region, rapidly growing as a key hub for data centers, driven by lower real estate costs and strategic location. Key players in the market include Colt Technology Services, NTT Ltd, Digital Realty Trust Inc., Equinix Inc., and Telehouse (KDDI Corporation). These companies are investing in hyperscale, colocation, and edge data centers to support the growing demand for digital services across the country.
Market Drivers
Digital Transformation, Cloud Adoption, and IoT Expansion
The Japan Data Centre Market is being significantly driven by the increasing reliance on cloud services and digital transformation initiatives. Organizations are increasingly adopting cloud-based solutions to enhance their IT infrastructure, leading to higher demand for robust data centers capable of handling increased data storage and processing needs. For instance, according to a survey by the Japan External Trade Organization (JETRO), the shift to cloud computing accelerated after the 2011 Great East Japan Earthquake, with many companies moving to cloud-based solutions to ensure data security and business continuity. Government and corporate initiatives to modernize and digitize operations are further contributing to this trend. Alongside this, the proliferation of Internet of Things (IoT) devices is generating vast amounts of data that need to be stored, processed, and analyzed. Companies are leveraging this data to gain insights through big data analytics, which requires advanced and scalable data center infrastructure to manage the growing data load.
Government Initiatives and Cybersecurity Demands
The Japanese government is playing a pivotal role in promoting data center growth through favorable digitalization policies and infrastructure investments. These initiatives aim to foster economic growth while ensuring that businesses have access to the necessary digital infrastructure, including advanced data centers. For instance, the Government of Japan’s broad digitalization strategy covers key infrastructure such as 5G networks, submarine cables, and fiber optics. Alongside this, growing concerns around cybersecurity and data privacy are pushing organizations to invest in secure and resilient data center solutions. Compliance with data privacy regulations and the need for secure data storage have become essential, with many companies facing data localization requirements that mandate storing sensitive data within Japan's borders, further driving demand for local data centers.
Artificial Intelligence, Machine Learning, and 5G Network Deployment
The growing adoption of Artificial Intelligence (AI) and Machine Learning (ML) technologies is another key driver for the Japan Data Centre Market. These technologies require substantial computing power and high-performance data centers to handle the processing of large datasets and AI-driven workloads. AI and ML applications are increasingly being integrated into various sectors, such as healthcare, finance, and manufacturing, demanding more sophisticated data center resources. Additionally, the deployment of 5G networks in Japan is accelerating the need for data center infrastructure. 5G enables higher data traffic and more connected devices, which requires extensive network management and edge computing capabilities. Edge data centers, in particular, are becoming crucial as 5G networks push data processing closer to the source, reducing latency and enhancing real-time applications.
Economic Growth and Foreign Direct Investment
Japan’s steady economic growth and rising GDP are contributing to increased demand for data center capacity. As businesses expand, they require more robust digital infrastructure to support their operations. Additionally, foreign direct investment (FDI) is playing a key role in the expansion of the data center market, with global companies investing in Japan's growing digital economy. This influx of investment not only strengthens the existing data center infrastructure but also brings in advanced technologies and expertise, helping Japan maintain its competitive edge in the global digital landscape.
Market Trends
Consolidation, Expansion, and Focus on Sustainability
The Japan Data Centre Market is experiencing significant consolidation as leading providers engage in mergers and acquisitions to increase market share and achieve economies of scale. This trend enables larger operators to pool resources, streamline operations, and strengthen their competitive positioning. For instance, major data center providers are actively consolidating their market positions through strategic mergers and acquisitions, aiming to leverage economies of scale and enhance service offerings. Alongside this, data center providers are expanding their geographic footprint across Japan to meet the rising demand for digital infrastructure in different regions, particularly in urban centers and key business districts. This expansion is critical for reducing latency and ensuring reliable access to data services. At the same time, there is a growing emphasis on sustainability within the industry. Providers are increasingly focusing on building and operating green data centers by incorporating energy-efficient technologies and renewable energy sources. Carbon neutrality goals are becoming a priority, with many data center operators setting ambitious targets to reduce their carbon footprint and align with Japan's national environmental goals. These sustainability initiatives not only help meet regulatory requirements but also appeal to environmentally conscious customers and investors, positioning operators as responsible leaders in the industry.
Edge Computing, 5G, and the Rise of Hybrid Cloud Strategies
The deployment of 5G networks is revolutionizing Japan’s data center market by driving the adoption of edge computing. As 5G enables faster, more reliable connections, there is an increasing need for smaller, distributed data centers located closer to the network's edge. These edge data centers are essential for processing data in real-time, reducing latency, and supporting emerging technologies such as Internet of Things (IoT) devices and autonomous systems. In parallel, the growing use of hybrid cloud and multi-cloud strategies is transforming the way organizations manage their IT infrastructure. Businesses are increasingly adopting hybrid cloud models that combine on-premises systems with cloud-based environments, requiring flexible and scalable data center solutions. Data center providers are responding to this shift by offering support for multi-cloud environments, ensuring compatibility with various cloud platforms to meet the diverse needs of their customers. The rise of edge computing, combined with the flexibility offered by hybrid and multi-cloud strategies, is reshaping the demand for data center services across Japan, creating new opportunities for innovation and investment in network infrastructure.
Market Challenges Analysis
Land Constraints, Energy Costs, and Natural Disaster Risks
One of the major challenges facing the Japan Data Centre Market is the scarcity of suitable land for data center construction, particularly in urban areas where space is already at a premium due to high levels of urbanization. The limited availability of land in densely populated cities such as Tokyo and Osaka restricts expansion opportunities, while the high real estate costs in these areas further complicate development. Securing affordable, strategically located land is crucial for operators looking to meet the growing demand for data centers. Alongside land constraints, rising energy costs pose another significant challenge. For instance, the electricity costs for the industry in Japan amounted to approximately 27.55 Japanese yen per kilowatt hour in the fiscal year 2022. Data centers consume vast amounts of energy, and with energy prices increasing, operational expenses continue to rise. Ensuring a reliable and stable energy supply is critical for maintaining seamless operations, as disruptions in power can lead to downtime, which is costly both in terms of service delivery and reputation. Compounding these issues is Japan's vulnerability to natural disasters, particularly seismic activity. Earthquakes and tsunamis pose significant risks to data centers, requiring operators to invest in disaster preparedness measures such as backup facilities and robust recovery plans to ensure resilience and minimize disruptions.
Regulatory, Talent, and Technological Challenges
The regulatory landscape in Japan presents another set of challenges for data center operators. Navigating complex regulations, which include strict building codes, environmental standards, and data privacy laws, can be time-consuming and costly. Ensuring compliance with these regulations adds to the operational costs of data centers, especially as the regulatory environment continues to evolve. At the same time, the industry is grappling with a shortage of skilled professionals. There is a significant skills gap in the data center sector, making it difficult for operators to find qualified staff to manage and maintain their facilities. Furthermore, retaining skilled employees is a challenge, as the growing demand for talent has led to fierce competition and attractive compensation packages in the industry. Lastly, rapid advancements in emerging technologies such as edge computing and quantum computing are pressuring data center operators to continuously invest in innovation to stay competitive. While necessary, this investment in research and development requires substantial financial resources, which can strain smaller operators as they try to keep up with the technological pace.
Market Segmentation Analysis:
By Type:
The Japan Data Centre Market is segmented by type into enterprise, edge, colocation, hyperscale, managed, and modular data centers. Hyperscale data centers are gaining significant traction due to the growing demand for large-scale data processing and cloud services from global providers such as AWS, Google Cloud, and Microsoft Azure. Colocation services are also expanding rapidly, as businesses seek cost-effective solutions for hosting IT infrastructure without large capital investments. Additionally, edge data centers are increasingly essential for supporting low-latency applications and processing data closer to the source, driven by the rise of 5G and IoT deployments. Managed and modular data centers offer flexible, scalable solutions that meet the evolving needs of businesses in Japan's digital economy.
By Component:
Based on components, the market is divided into hardware, software, and services. The hardware segment includes power systems, cooling systems, racks, servers, and networking devices, with a strong focus on energy efficiency and performance. Japan Data Centre Infrastructure Management (DCIM) software is categorized into cloud-based and on-premises solutions, with cloud-based management tools seeing increased adoption due to their flexibility and ease of deployment. The services segment encompasses professional services, integration & implementation, consulting, support & maintenance, and managed services, all of which are critical to ensuring smooth data center operations. As data centers become more complex, businesses increasingly rely on external expertise to maintain high levels of service availability and operational efficiency.
Segments:
Based on Type:
- Enterprise
- Edge
- Colocation
- Hyperscale
- Managed
- Modular
Based on Component:
- Hardware
- Power Systems
- Cooling Systems
- Racks
- Servers
- Networking Devices
- Others
- Japan Data Centre Infrastructure Management Software
- Cloud-based
- On-premises
- Service
- Professional Services
- Integration & Implementation
- Consulting
- Support & Maintenance
- Managed Services
Based on Size:
- Small
- Mid-Sized
- Large
Based on Tire:
- Tier 1
- Tier 2
- Tier 3
- Tier 4
Based on Industry:
- IT & Telecom
- BFSI
- Manufacturing
- Healthcare
- Government
- Others
Based on the Geography:
- Tokyo
- Osaka
- Nagoya
- Fukuoka
- Hokkaido
- Okinawa
Regional Analysis
Tokyo
Tokyo holds the largest market share in the Japan Data Centre Market, accounting for approximately 50% of the total market. As the nation's capital and economic hub, Tokyo is home to a dense concentration of businesses, financial institutions, and global enterprises that drive demand for robust data center infrastructure. The city's well-developed digital infrastructure, including advanced connectivity and reliable power supply, makes it a preferred location for hyperscale and colocation data centers. Major cloud service providers and multinational companies have established data centers in Tokyo to cater to the growing needs of their clients in the region. However, the high cost of land and real estate in the city presents challenges for further expansion, driving some operators to explore alternative locations outside the capital.
Osaka
Osaka, the second-largest region in the Japan Data Centre Market, holds around 20% of the market share. As a major commercial and industrial center, Osaka is experiencing rapid growth in data center investments, particularly in colocation and edge data centers. The city's strategic location, combined with its relatively lower real estate costs compared to Tokyo, has made it an attractive option for data center operators looking to expand their footprint. Additionally, Osaka's growing digital economy, supported by government initiatives and infrastructure development, is driving increased demand for data center services. The region is also becoming a hub for edge computing, as businesses seek to reduce latency and enhance performance by processing data closer to end-users. As Osaka continues to develop, it is expected to play an increasingly important role in Japan's overall data center landscape.
Key Player Analysis
- Colt Technology Services
- AirTrunk Operating Pty Ltd
- Arteria Networks Corporation
- Digital Edge (Singapore) Holdings Pte Ltd
- Digital Realty Trust Inc.
- Equinix Inc.
- IDC Frontier Inc. (SoftBank Group)
- NEC Corporation
- netXDC (SCSK Corporation)
- NTT Ltd
- Telehouse (KDDI Corporation)
- Zenlayer Inc.
Competitive Analysis
The Japan Data Centre Market is highly competitive, with leading players such as Colt Technology Services, NTT Ltd, Digital Realty Trust Inc., Equinix Inc., and Telehouse (KDDI Corporation) driving market growth through significant investments in hyperscale, colocation, and edge data centers. These companies leverage their strong financial capabilities and advanced technological infrastructure to meet the growing demand for data storage, cloud services, and digital transformation across various industries. The increasing adoption of sustainability practices and energy-efficient technologies is a key differentiator among players, as they aim to meet both customer expectations and regulatory requirements. While the market remains dominated by these major players, competition is intensifying with new entrants and the rise of niche service providers offering specialized data center solutions such as edge computing and modular infrastructure, further shaping the competitive landscape.
Recent Developments
- In July 2024, Arteria Networks began offering leased circuit services “DynaEther” for the Topaz submarine cable, contributing to the resilience of Japan’s digital infrastructure3.
- In May 2024, AirTrunk opened its second Tokyo hyperscale data centre, named AirTrunk TOK2, with a capacity of over 110MW.
- In May 2024, NEC launched two new data center buildings at its campuses in Kanagawa and Kobe, Japan, utilizing 100% renewable energy.
- In April 2023, Colt Data Centre Services (Colt DCS) broke ground on a new 20MW data center in Tokyo, Japan.
- In March 2023, Digital Edge announced a partnership with Hulic to develop a carrier-neutral data center facility in downtown Tokyo, named TYO7.
Market Concentration & Characteristics
The Japan Data Centre Market exhibits a moderate to high level of market concentration, with a few dominant players such as NTT Ltd, Equinix Inc., and Digital Realty Trust Inc. controlling a significant portion of the market. These companies possess the financial strength, technological expertise, and expansive infrastructure to cater to the growing demand for cloud services, colocation, and edge computing. The market is characterized by high capital expenditure requirements, creating barriers for smaller or new entrants. However, the rise of niche segments like modular data centers and sustainability-focused solutions is offering opportunities for smaller players. The focus on energy efficiency and green data centers is becoming a defining characteristic of the market, driven by both regulatory pressure and customer demand. Additionally, the market is shaped by the need for low-latency services, particularly with the ongoing 5G rollout, positioning edge data centers as a growing segment within the industry.
Report Coverage
The research report offers an in-depth analysis based on Type, Component, Size, Tire, Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan data centre market is expected to continue growing, driven by increasing demand for cloud services and digital transformation.
- Hyperscale data centres will expand significantly, with global providers investing in larger facilities to support growing data needs.
- Edge computing will gain traction as 5G deployment accelerates, increasing the need for smaller, localized data centres.
- Sustainability will become a key focus, with data centre operators adopting energy-efficient technologies and renewable energy sources.
- Government policies supporting digital infrastructure development will continue to drive market growth.
- Rising data privacy concerns will increase demand for secure, compliant data storage solutions.
- Colocation services will see steady growth as businesses seek cost-effective data centre solutions.
- Technological advancements, such as AI and IoT, will boost the need for high-performance data centres.
- The market will see increased competition from both local and international players.
- Investment in disaster recovery and resilience measures will remain a priority due to Japan's vulnerability to natural disasters.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Data Centre Market?
What factors are driving the growth of the Japan Data Centre Market?
What are the key segments within the Japan Data Centre Market?
What are some challenges faced by the Japan Data Centre Market?
Who are the major players in the Japan Data Centre Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Data Centre Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Japan Data Centre Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 14,588.92 million → 2032: USD 25,528.95 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Data Centre Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Data Centre Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Data Centre Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Japan Data Centre Drivers
- 3.3 Japan Data Centre Restraints & Challenges
- 3.4 Japan Data Centre Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Data Centre Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Data Centre Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Data Centre category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Data Centre Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Japan Data Centre Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Japan Data Centre in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Data Centre Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Japan Data Centre Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Japan Data Centre Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Data Centre (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Japan Data Centre
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Japan Data Centre – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Japan Data Centre – Priority Domestic Market 1
Chapter 10. Japan Data Centre – Priority Domestic Market 2
Chapter 11. Japan Data Centre – Priority Domestic Market 3
Chapter 12. Japan Data Centre – Priority Domestic Market 4
Chapter 13. Japan Data Centre Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
