
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Japan Industrial Design Market Size 2023 | USD 2,915.58 million |
| Japan Industrial Design Market, CAGR | 5.26% |
| Japan Industrial Design Market Size 2032 | USD 4,626.96 million |
Market Overview
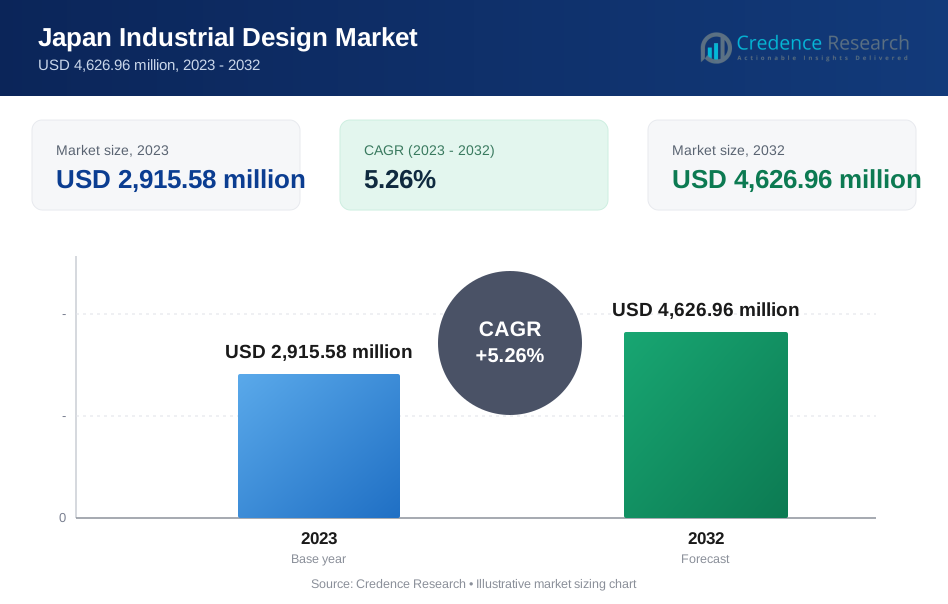
The Japan Industrial Design Market is projected to grow from USD 2,915.58 million in 2023 to an estimated USD 4,626.96 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.26% from 2024 to 2032. This growth is driven by increasing demand for innovative and user-centric product designs across sectors such as consumer electronics, automotive, and healthcare.
The market growth is fueled by factors such as rising consumer demand for advanced product functionality, sustainability, and aesthetic appeal. Trends such as the integration of digital tools like CAD software and 3D printing are transforming traditional design processes, enhancing efficiency and creativity. Additionally, the focus on eco-friendly and sustainable design solutions aligns with Japan’s commitment to environmental responsibility, further propelling market adoption. Strong collaboration between design firms and technology innovators also stimulates industry dynamics.
Geographically, major growth is concentrated in metropolitan areas like Tokyo and Osaka, where industries such as automotive and electronics dominate. Japan’s strong export market amplifies the demand for industrial design to meet international standards and preferences. Key players in the market include GK Industrial Design, Nendo Inc., Takram Design Engineering, and IDEO Japan, who leverage their expertise to stay ahead in this competitive landscape. These companies are pivotal in shaping design trends and driving innovation in the industrial design sector.
Market Insights
- The Japan Industrial Design Market is projected to grow from USD 2,915.58 million in 2023 to USD 4,626.96 million by 2032, at a CAGR of 5.26% from 2024 to 2032.
- The integration of digital tools like CAD software, 3D printing, and AI enhances efficiency, creativity, and product functionality, driving market demand.
- Eco-friendly materials and sustainable design solutions are increasingly prioritized, aligning with Japan's environmental goals and consumer preferences.
- Sectors like automotive, consumer electronics, and healthcare are fueling demand for innovative, user-centric, and aesthetically appealing product designs.
- Market saturation and intense competition, both domestically and internationally, challenge companies to innovate and maintain a competitive edge.
- Metropolitan areas such as Tokyo and Osaka dominate, contributing a significant share to the market due to their strong industrial presence and export orientation.
- Japan's reputation for precision and minimalistic design philosophy enhances its global competitiveness, driving demand for its industrial design expertise internationally.
Market Drivers
Growing Demand for Innovative and User-Centric Products
The increasing consumer preference for products that combine functionality, usability, and aesthetic appeal is a significant driver of the Japan Industrial Design Market. Japanese consumers, known for their discerning taste and high expectations, push industries to innovate continuously. This demand spans various sectors, including consumer electronics, automotive, and healthcare, where products must meet rigorous quality and design standards.For instance, in consumer electronics, companies like Sony and Panasonic focus on creating sleek, ergonomic designs that align with modern lifestyles while incorporating advanced technology such as 4K/8K displays and robotics. Similarly, in the automotive industry, manufacturers like Toyota and Nissan emphasize user-centric designs to enhance driving experiences, comfort, and safety. These designs reflect cultural values such as omotenashi (hospitality), ensuring vehicles are intuitive and aesthetically pleasing. The healthcare sector also requires innovative design solutions for medical devices and equipment to ensure usability and compliance with safety standards.The interplay of functionality, aesthetics, and sustainability continues to drive the need for industrial design services in Japan. By addressing these demands across sectors, industrial designers foster market growth while maintaining Japan’s reputation for quality and innovation.
Technological Advancements in Design Processes
The adoption of cutting-edge technologies has revolutionized industrial design practices in Japan. Tools such as Computer-Aided Design (CAD), 3D printing, and Virtual Reality (VR) enable designers to create precise prototypes efficiently, accelerating product development cycles. These technologies not only streamline the design process but also reduce costs by minimizing errors and material waste.For instance, AI-powered tools are increasingly integrated into workflows to predict consumer preferences and optimize designs. Companies like Toyota utilize AI to analyze parameters such as aerodynamics and material properties, generating innovative alternatives for lightweight yet durable automotive components. Similarly, 3D printing technologies have enabled firms like Mitsubishi Heavy Industries to produce lightweight aerospace parts with precision while reducing production times.This synergy between technology and design expertise has positioned Japan as a global leader in industrial design innovation. By leveraging these advancements, Japanese companies maintain a competitive edge in creating high-quality products that meet evolving market demands.
Focus on Sustainability and Eco-Friendly Designs
Japan’s strong commitment to environmental sustainability significantly influences its industrial design market. Companies prioritize eco-friendly designs to meet both regulatory standards and consumer expectations for sustainable products. This shift is evident in industries such as packaging, automotive, and consumer goods, where sustainable materials and production methods are becoming mainstream.For instance, the automotive sector focuses on lightweight designs to improve fuel efficiency and reduce emissions. Companies like Suzuki adopt bio-polycarbonate materials for vehicle parts, reducing reliance on petroleum-based products while cutting CO2 emissions during production. Similarly, the packaging industry emphasizes biodegradable materials; companies like Dell use mushroom-based packaging for electronics to enhance recyclability.These sustainability-driven initiatives align with Japan’s broader environmental goals while enhancing the appeal of its industrial designs globally. Brands that incorporate sustainability into their ethos gain a competitive advantage by attracting environmentally conscious consumers.
Expanding Export Market and Global Influence
Japan’s reputation for quality and innovation has established it as a key player in global markets, driving demand for industrial design services. As Japanese products are exported worldwide, companies must adapt their designs to cater to diverse cultural preferences and regulatory requirements.For instance, Japanese automotive exports benefit from industrial designs that enhance vehicle appeal in competitive markets like Europe and North America. Toyota’s hybrid technology in models like the Prius exemplifies this adaptation by meeting international standards for sustainability while maintaining advanced safety features. Similarly, Japanese consumer electronics brands like Sony leverage their reputation for sleek, functional designs by introducing cutting-edge products such as high-resolution cameras and VR systems.By aligning industrial design with international trends while maintaining local craftsmanship values, Japan ensures sustained demand for its products globally. This adaptability positions Japan as a leader in the global design landscape while fostering growth in its industrial design market.
Market Trends
Integration of Technology in Design Processes
The integration of advanced technologies such as Computer-Aided Design (CAD), 3D printing, Artificial Intelligence (AI), and Virtual Reality (VR) is revolutionizing Japan's industrial design landscape. These tools enable precise prototyping, faster iterations, and enhanced creativity while reducing production time and costs. For instance, Toyota has implemented AI-driven predictive maintenance systems within its IIoT framework, allowing real-time monitoring of vehicle components to prevent failures before they occur. Similarly, 3D printing is transforming the automotive and healthcare industries by enabling rapid prototyping and experimentation with complex geometries. This approach not only accelerates product development but also optimizes resource use, aligning with Japan’s reputation for technological innovation.Moreover, AI-powered generative design tools are being adopted to explore countless design variations, optimizing factors like material usage and functionality. Virtual Reality (VR) and Augmented Reality (AR) are also enhancing design presentations by offering immersive visualizations of products before production. These advancements reflect Japan's leadership in integrating cutting-edge technologies into industrial design, solidifying its position as a global innovator. The synergy between these technologies and Japan’s commitment to efficiency ensures that the country remains at the forefront of modern industrial practices.
Focus on Sustainability and Eco-Friendly Designs
Sustainability is a core focus in Japan's industrial design practices, driven by regulatory pressures and growing consumer awareness. Japanese companies are adopting eco-friendly materials, energy-efficient production methods, and sustainable design principles to minimize environmental impact. For example, Toyota’s use of cellulose nanofiber—a lightweight yet durable material—reduces vehicle weight while improving fuel efficiency. Additionally, the packaging sector emphasizes biodegradable materials, such as biomass-based paper packaging developed by Dai Nippon Printing, to address plastic waste concerns.Japan’s lean manufacturing approach further supports sustainability by reducing waste and optimizing production processes. Advanced recycling technologies are also being employed to transform waste into reusable resources, exemplifying the country’s innovation in circular economy practices. These efforts resonate with environmentally conscious consumers while positioning Japanese products as globally desirable for their eco-friendly attributes. By integrating sustainability into industrial design, Japan not only addresses environmental challenges but also gains a competitive edge in international markets.
Rise of Minimalism and Aesthetic Precision
Minimalism continues to define Japanese industrial design across sectors such as consumer electronics, home appliances, and furniture. Rooted in cultural philosophies like wabi-sabi and ma, this design approach emphasizes simplicity, functionality, and the intentional use of negative space. For instance, Muji's minimalist products prioritize utility over decoration, creating timeless designs that appeal globally. In the automotive industry, brands like Toyota adopt aerodynamic silhouettes with clean lines to balance aesthetics with functionality.This minimalist ethos extends to interior design and architecture, where open layouts and natural materials create serene spaces that align with modern wellness trends. The emphasis on aesthetic precision also influences global design preferences, making Japanese products highly sought after for their elegance and usability. By maintaining its "less is more" philosophy, Japan strengthens both domestic demand and its international reputation for innovative yet understated designs.
Customization and User-Centric Designs
The demand for personalized products is reshaping Japan's industrial design market as companies prioritize user-centric approaches. Customization allows industries like automotive to offer tailored features such as adjustable seating configurations or personalized infotainment systems. Similarly, modular designs in consumer electronics enable users to upgrade components easily, enhancing product longevity.In healthcare, companies like Harloff provide customized medical carts tailored to specific workflows, improving operational efficiency. This trend reflects a broader shift toward human-centered design that prioritizes usability and consumer satisfaction. By fostering collaboration between designers and end-users during product development stages, Japanese firms ensure their offerings resonate with diverse needs while strengthening brand loyalty. Customization not only enhances client satisfaction but also aligns with sustainability goals by reducing waste through precise production tailored to individual requirements.
Market Challenges
High Competition and Market Saturation in Japan's Industrial Design Market
The Japan Industrial Design Market faces significant challenges due to intense competition and market saturation. Domestically, established players and new entrants continuously vie for market share, particularly in mature sectors like automotive, consumer electronics, and furniture. For instance, the automotive industry is highly competitive, with both local and international companies striving to differentiate themselves through innovative designs. Japanese firms must also contend with cost-effective design solutions from competitors in China and South Korea, which offer comparable quality but at lower prices. This dynamic forces Japanese companies to justify premium pricing through superior craftsmanship and innovation, a challenging balance in price-sensitive markets.Global competition further complicates the landscape. Chinese companies benefit from government subsidies for research and development, allowing them to rapidly improve product competitiveness and capture market share previously dominated by foreign firms. In response, Japanese companies are compelled to invest heavily in R&D to maintain their edge. However, this can strain resources, especially for small and medium-sized enterprises (SMEs), which may struggle to compete against larger players with deeper financial reserves.Moreover, saturation in key markets limits growth opportunities. To address this, businesses must explore untapped areas or adopt strategies such as localization to better align with regional preferences. For example, entering inland Chinese markets with tailored designs could provide a first-mover advantage.
Integration of Advanced Technologies and Skills Gap
The integration of advanced technologies like Artificial Intelligence (AI), 3D printing, and Virtual Reality (VR) is transforming industrial design but presents significant challenges for Japanese companies. Adopting these technologies requires substantial investment in infrastructure, software, and training. For SMEs with limited financial resources, this can be particularly burdensome. For instance, while 3D printing offers enhanced design flexibility and customization capabilities, its high costs deter widespread adoption among smaller firms.Additionally, the growing reliance on digital tools has highlighted a critical skills gap in the industry. The demand for professionals proficient in advanced technologies far exceeds supply, exacerbating delays in innovation and product development. For example, Japan faces an acute shortage of digital workers, with an estimated gap of 430,000 IT professionals by 2025. This shortage hinders the efficient utilization of technologies like cloud computing and IoT systems.To bridge this gap, companies are investing in workforce upskilling and collaborating with academic institutions to align educational curricula with industry demands. For example, initiatives like integrating digital manufacturing skills into industrial design programs aim to prepare a workforce ready for Industry 4.0. However, these efforts require time and resources, impacting short-term productivity and profitability. Addressing these challenges is crucial for maintaining Japan's position as a leader in industrial design innovation.
Market Opportunities
Rising Demand for Sustainable and Innovative Designs
The global emphasis on sustainability is creating significant opportunities for the Japan Industrial Design Market. Consumers and industries are increasingly prioritizing eco-friendly products and processes, driving demand for sustainable design solutions across sectors such as automotive, packaging, and consumer electronics. Japanese companies, renowned for their precision and innovation, are well-positioned to capitalize on this trend by incorporating recyclable materials, energy-efficient designs, and modular concepts into their offerings. For instance, a multinational consumer goods corporation achieved LEED Silver certification for its manufacturing facility in Shiga Prefecture, Japan, by integrating sustainable features such as recycled water systems, efficient lighting designs, and energy-saving ventilation systems. These efforts not only reduced the company’s environmental impact but also demonstrated the potential of eco-friendly industrial design in Japan. Additionally, the increasing adoption of electric vehicles (EVs) and renewable energy systems aligns with the expertise of Japanese designers in creating lightweight, functional, and aesthetically pleasing products. By leveraging this shift toward sustainability, Japanese companies can expand their domestic footprint while enhancing their competitiveness in international markets. This growing demand for sustainable solutions underscores the importance of integrating environmentally conscious practices into industrial design to meet evolving consumer expectations and regulatory requirements.
Technological Advancements Driving Digital Transformation
The integration of advanced technologies such as Artificial Intelligence (AI), 3D printing, and Augmented Reality (AR) is transforming the industrial design landscape in Japan. These tools enable faster prototyping, improved precision, and enhanced user experiences, empowering Japanese companies to stay ahead in a rapidly evolving market. With Japan’s strong foundation in technological innovation, businesses can harness these advancements to streamline design processes and introduce cutting-edge products. For instance, Mitsubishi Heavy Industries (MHI) has utilized 3D printing to produce lightweight aerospace components that enhance fuel efficiency while aligning with sustainability goals. Similarly, Serendix has introduced 3D-printed homes in Japan, showcasing how advanced technologies can revolutionize construction by reducing material waste and enabling innovative designs tailored to specific needs. Furthermore, the rising global demand for smart devices and connected systems creates opportunities for Japanese designers to lead in developing intelligent, user-centric solutions. By investing in technology-driven design processes, companies can enhance efficiency, reduce costs, and meet the evolving needs of a tech-savvy consumer base. These advancements not only ensure long-term growth but also position Japanese firms as leaders in the global industrial design market by fostering innovation and adaptability.
Market Segmentation Analysis
By Product
The automotive segment dominates the Japan Industrial Design Market, reflecting the country’s global leadership in vehicle manufacturing and innovation. Automakers invest heavily in design to enhance vehicle interiors, aerodynamics, and lightweight components, particularly for electric vehicles (EVs). The furniture segment also holds a significant share, driven by Japan’s focus on minimalist and multi-functional designs. Urbanization and shrinking living spaces further boost demand for compact and space-saving furniture. The packaging segment is growing steadily, fueled by the increasing need for sustainable and recyclable solutions. With stricter regulations and consumer preferences for eco-friendly options, industrial design in packaging focuses on reducing waste and enhancing functionality
By Application
In terms of applications, the transportation sector leads the market, owing to the critical role of industrial design in automotive and public transit systems. The integration of advanced design tools ensures vehicles and infrastructure are user-centric, safe, and efficient. The consumer goods segment is another key contributor, with strong demand for aesthetically pleasing, durable, and functional products like electronics and household appliances. Additionally, the medical devices segment is expanding rapidly, driven by the need for ergonomic and intuitive designs to improve usability and meet stringent healthcare standards. Japan’s aging population also amplifies demand for innovative medical equipment and assistive devices.
Segments
Based on Product
- Automotive
- Furniture
- Packaging
Based on Application
- Transportation
- Consumer Goods
- Medical Devices
Based on End-User
- Automotive
- Electronics
- Healthcare
- Aerospace
Based on Region
- Kanto
- Kansai
- Chubu
Regional Analysis
Kanto Region (40%)
The Kanto region accounts for the largest market share, approximately 40%, driven by the high concentration of multinational corporations, design firms, and research institutions in Tokyo and its surrounding areas. Tokyo serves as the epicenter for industrial design innovation, with its diverse industries ranging from consumer electronics to automotive manufacturing. The region’s thriving startup ecosystem also supports the growth of design-driven businesses, with cutting-edge advancements in technology, including artificial intelligence (AI) and 3D printing, significantly influencing the market. Additionally, the presence of leading design schools and international design exhibitions positions Kanto as a global leader in industrial design.
Kansai Region (25%)
The Kansai region holds approximately 25% of the market share, driven by its well-established manufacturing industries and cultural emphasis on craftsmanship. Osaka and Kobe are known for their expertise in industrial equipment and medical device manufacturing, with a strong focus on integrating user-friendly designs. Kyoto contributes to the market with its reputation for blending traditional Japanese aesthetics with modern innovation, particularly in the consumer goods sector. The Kansai region benefits from government incentives and partnerships with universities, fostering research and development in sustainable and ergonomic designs.
Key players
- RKS Design
- Busse Design
- Designworks
- Accenture
- BlueFocus Intelligent Communications Group Co.
- IDEO LLC
- GK Design
- Altran Technologies SA
- Naoto Fukasawa
- Codetta Product Design
- Yasuhide Yokoi
Competitive Analysis
The Japan Industrial Design Market is highly competitive, characterized by the presence of both domestic and international players. Companies like RKS Design and IDEO LLC leverage their global reputation and innovative approaches to dominate the market. Meanwhile, local firms such as GK Design and prominent designers like Naoto Fukasawa contribute significantly with their deep understanding of Japanese aesthetics and consumer preferences. Multinational corporations, including Accenture and Altran Technologies SA, bring advanced technological capabilities, enabling them to cater to diverse industry needs such as automotive, electronics, and healthcare. In addition, firms like Busse Design and Codetta Product Design specialize in niche segments, providing tailored solutions for unique applications. The market’s competitive dynamics are further intensified by strategic collaborations, R&D investments, and a strong focus on sustainability. Companies differentiate themselves through design innovation, customer-centric strategies, and the adoption of cutting-edge technologies, ensuring market leadership.
Recent Developments
- In 2024, Busse completed over 300 projects, including advancements in augmented and virtual reality applications and sustainable design methodologies.They introduced a modular motion table for hybrid AR/VR validations and laser welding capabilities in their production facilities.
- In November 2023, Designworks opened a new studio in Shanghai to focus on human-centered design innovations tailored to the Asian market. The studio emphasizes sustainable materials and traditional craftsmanship integration into modern designs.The firm also collaborated with Grammer to design versatile automotive interiors featuring productivity, relaxation, and social modes.
- In November 2024, BlueFocus deepened its collaboration with Volcano Engine to integrate AI marketing solutions into video generation and intelligent applications for marketing systems.The company announced an equity buyback worth CNY 300 million in January 2025 as part of its strategic financial management.
- In 2024, GK Design celebrated its 70th anniversary with notable projects like the rebranding of KYOTO COOP and the development of Omron's wireless ECG recorder.They continue to focus on interactive exhibitions, transportation design, and packaging innovations.
Market Concentration and Characteristics
The Japan Industrial Design Market is moderately concentrated, with a mix of established domestic firms and globally renowned players dominating the industry. The market is characterized by a strong emphasis on innovation, precision, and user-centric design, reflecting Japan's reputation for high-quality craftsmanship and technological excellence. Key players such as GK Design and IDEO LLC focus on leveraging cutting-edge tools like Artificial Intelligence (AI), 3D printing, and Virtual Reality (VR) to stay competitive. Additionally, the market demonstrates a unique blend of traditional Japanese aesthetics and modern minimalism, catering to both local and global consumer preferences. While the presence of multinational corporations like Accenture enhances competition, local firms maintain an edge through their deep understanding of cultural nuances and sustainable design practices. This dynamic ecosystem fosters a steady pace of innovation, making Japan a global leader in industrial design.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The shift toward EVs will drive demand for lightweight, aerodynamic designs and innovative interior concepts in the automotive sector.
- The emphasis on sustainability will lead to the integration of eco-friendly materials and energy-efficient design solutions across industries.
- Technologies like Artificial Intelligence (AI), 3D printing, and Augmented Reality (AR) will enhance efficiency, precision, and creativity in the design process.
- The growing need for ergonomic and intuitive medical devices will create new opportunities for industrial designers to address healthcare challenges.
- Consumer demand for personalized products will spur innovation in modular and customizable designs, particularly in electronics and furniture.
- Japanese design firms will increasingly collaborate with global partners to meet international market demands and adapt to diverse cultural preferences.
- Compact, multi-functional designs catering to urban lifestyles will gain prominence, especially in furniture and consumer goods.
- The rise of IoT-enabled devices will require industrial designers to create products that seamlessly integrate technology with aesthetics and functionality.
- Japan’s traditional minimalist design philosophy will continue to influence global design trends, enhancing the market’s international appeal.
- Companies will invest heavily in R&D to innovate and maintain a competitive edge, focusing on sustainable, tech-driven, and user-centric designs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Japan Industrial Design Market in 2023 and 2032, and its CAGR?
What drives the growth of the Japan Industrial Design Market?
Which industries contribute most to the Japan Industrial Design Market?
What role does sustainability play in the Japan Industrial Design Market?
Which regions lead in the Japan Industrial Design Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Industrial Design Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Industrial Design Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2,915.58 million → 2032: USD 4,626.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Industrial Design Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Industrial Design Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Industrial Design Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Industrial Design Market Drivers
- 3.3 Japan Industrial Design Market Restraints & Challenges
- 3.4 Japan Industrial Design Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Industrial Design Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Industrial Design Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Industrial Design category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Industrial Design Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Industrial Design Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Industrial Design market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Industrial Design Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Industrial Design Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Industrial Design Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Industrial Design (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Industrial Design Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Industrial Design Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Industrial Design Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Industrial Design Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Industrial Design Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Industrial Design Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Industrial Design Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Industrial Design Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Industrial Design Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
