
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
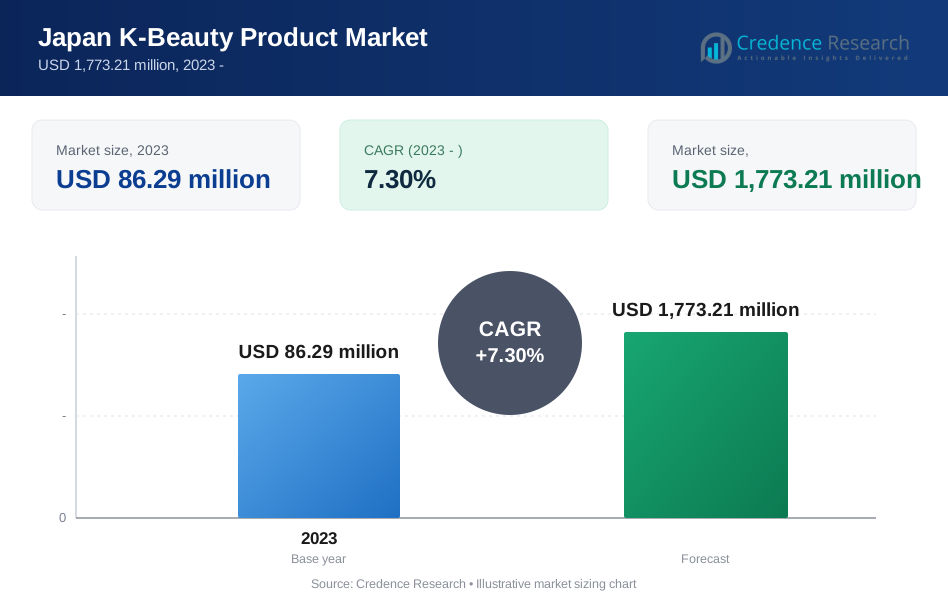
| Japan K-Beauty Product Market Size 2023 | USD 866.17 million |
| Japan K-Beauty Product Market, CAGR | 8.28% |
| Japan K-Beauty Product Market Size 2032 | USD 1,773.21 million |
Market Overview
The Japan K-Beauty Product Market is projected to grow significantly, expanding from USD 866.17 million in 2023 to an estimated USD 1,773.21 million by 2032. This robust growth corresponds to a compound annual growth rate (CAGR) of 8.28% from 2024 to 2032. The market's expansion reflects increasing consumer preference for innovative, high-quality skincare and cosmetics, driven by the popularity of South Korean beauty products known for their efficacy, unique formulations, and affordability.
Key drivers for this market include rising demand for anti-aging and skincare products, fueled by Japan's aging population and strong consumer focus on maintaining youthful and healthy skin. Trends such as the growing influence of social media, celebrity endorsements, and the shift towards natural and sustainable beauty products further support market growth. Additionally, advancements in product development, such as multifunctional cosmetics and innovative skincare solutions, have attracted a diverse consumer base seeking personalized beauty experiences.
Geographically, major urban centers like Tokyo, Osaka, and Yokohama serve as primary hubs for K-Beauty product consumption, driven by high population density and consumer purchasing power. Online retail channels are playing an increasingly significant role, enabling the market to reach rural areas and younger consumers. Key players in this dynamic market include AmorePacific, LG Household & Health Care, Missha, and Nature Republic, alongside Japanese distributors and e-commerce platforms, ensuring diverse product availability and competitive pricing.
Market Insights
- The Indonesia K-Beauty Product Market is projected to expand from USD 86.29 million in 2023 to USD 162.95 million by 2032, achieving a compound annual growth rate (CAGR) of 7.30%. This growth reflects the increasing popularity and acceptance of K-beauty products among Indonesian consumers.
- A significant market driver is the strong cultural affinity for Korean beauty standards. Indonesian consumers are increasingly embracing K-beauty trends, influenced by the global reputation of Korean skincare and beauty innovations.
- The rise of digital marketing and the expansion of e-commerce platforms are key drivers facilitating market growth. Enhanced online shopping experiences and effective digital campaigns make K-beauty products more accessible to a wider audience.
- There is a rising consumer preference for natural and organic beauty solutions. This trend is pushing brands to develop products with clean ingredients and sustainable practices, aligning with the health-conscious and environmentally aware Indonesian market.
- The market is characterized by intense competition among established Korean brands like Innisfree and Laneige, as well as emerging local brands. This competitive landscape drives continuous innovation and strategic marketing efforts to capture and retain market share.
- Major urban centers such as Jakarta, Surabaya, and Bali are the primary hubs for K-beauty product consumption, holding the largest market shares. These regions benefit from higher income levels, greater exposure to international beauty trends, and the presence of numerous specialty stores and beauty salons.
- Despite the positive outlook, the market faces restraints related to regulatory compliance and distribution logistics. Navigating local regulations and optimizing distribution channels are essential for brands to effectively penetrate and sustain their presence in the Indonesian market.
Market Drivers
Growing Demand for Innovative and Effective Skincare Solutions
Japanese consumers have a strong preference for high-quality skincare products, which aligns seamlessly with the innovative formulations offered by K-Beauty brands. For instance, the increasing interest in multi-step skincare routines among Japanese consumers is reflected in the rising sales of products such as sheet masks and serums, which are integral to K-Beauty practices. This trend indicates a cultural shift towards elaborate skincare regimens that promise visible results and functional benefits, resonating with Japan's beauty-conscious population.K-Beauty's ability to consistently introduce cutting-edge ingredients—such as snail mucin, fermented extracts, and cica (Centella Asiatica)—has established it as a trendsetter in the skincare industry. The demand for anti-aging products is particularly strong in Japan due to its aging population. K-Beauty brands’ focus on anti-aging innovations, including collagen-infused and hydrating solutions, has resonated well with older demographics. This combination of innovative ingredients and effective results has fostered a growing loyalty among Japanese consumers, further driving market growth and solidifying K-Beauty's position in Japan's competitive skincare landscape.
Rising Influence of Social Media and Digital Marketing
Social media platforms and digital marketing campaigns have played a pivotal role in increasing the visibility and desirability of K-Beauty products in Japan. For instance, platforms like Instagram and TikTok serve as critical channels for beauty product promotion, where influencers frequently showcase K-Beauty items. This trend highlights a significant shift in how Japanese consumers discover and choose their skincare products, often relying on peer recommendations and influencer endorsements over traditional advertising methods.Additionally, the rise of Korean pop culture, including K-dramas and K-pop, has significantly influenced consumer behavior. Fans of K-pop idols and actors emulate their beauty routines and prefer products endorsed by these celebrities. This cultural influence has created a loyal customer base for K-Beauty brands in Japan, particularly among younger demographics who are active on social media. As these platforms continue to shape consumer preferences and drive engagement, K-Beauty brands are well-positioned to leverage this trend to enhance their market presence in Japan.
Shift Toward Natural and Sustainable Beauty Products
Japanese consumers are increasingly prioritizing natural, organic, and eco-friendly beauty solutions, a trend that aligns with K-Beauty’s focus on clean formulations. For instance, many South Korean beauty brands emphasize the use of botanical ingredients and minimal synthetic additives, appealing to environmentally conscious consumers in Japan. This growing preference reflects a broader cultural appreciation for harmony with nature, driving demand for K-Beauty brands that prioritize sustainable practices.Brands that adopt eco-friendly packaging, cruelty-free certifications, and ethical production methods have gained a competitive edge in the market. The success of these brands indicates a significant shift in consumer values towards sustainability. Furthermore, increased awareness about environmental issues among Japanese consumers has amplified the demand for eco-conscious K-Beauty products. As this trend continues to evolve, it presents an opportunity for K-Beauty brands to align their offerings with the values of Japanese consumers who seek both efficacy and sustainability in their skincare choices.
Expansion of E-Commerce and Retail Distribution Channels
The rapid growth of e-commerce platforms has significantly boosted the accessibility of K-Beauty products in Japan. For instance, online retailers like Rakuten and Amazon Japan provide consumers with a wide variety of choices at competitive prices. The convenience of online shopping allows Japanese consumers to compare products easily and read reviews before making a purchase decision. This shift towards e-commerce reflects changing consumer habits, particularly among younger demographics who value convenience and variety.In addition to online retail channels, physical distribution avenues such as department stores, specialty beauty shops, and convenience stores have also played a crucial role in driving market penetration for K-Beauty brands. Many brands have partnered with Japanese retailers to ensure their products are readily available in-store. Furthermore, pop-up shops and brand collaborations create buzz around new product launches while enhancing brand visibility in the market. Together, these strategies contribute to an expanding presence of K-Beauty products across various retail formats in Japan.
Market Trends
Personalized and Customizable Beauty Solutions
Consumers in Japan are increasingly seeking personalized skincare and cosmetic products tailored to their unique needs. For instance, the launch of innovative tools like "SkinlifeLab" by AS Watson Group exemplifies this trend, utilizing AI-based skin analysis to provide tailored skincare recommendations based on individual selfies. This technology reflects a growing consumer demand for products that cater specifically to their unique skin conditions and preferences, marking a significant shift in the beauty landscape towards personalization. K-Beauty brands are leveraging advanced technologies such as DNA-based skincare solutions, allowing consumers to receive products formulated to address their genetic predispositions. This trend highlights the shift towards a more consumer-centric approach in the beauty industry, where personalization plays a vital role in building brand loyalty. As consumers become more educated about their skincare needs, they are gravitating towards brands that offer customized solutions that resonate with their individual identities. This evolution not only enhances customer satisfaction but also fosters deeper connections between brands and consumers, creating a loyal customer base that values tailored experiences over generic offerings.
Hybrid and Multi-Functional Products
The demand for hybrid and multi-functional beauty products is on the rise among Japanese consumers who value convenience and efficiency. K-Beauty brands are meeting these needs by introducing innovative products that serve multiple purposes. For example, BB and CC creams have gained immense popularity as they combine skincare benefits with makeup coverage, allowing users to streamline their beauty routines without sacrificing effectiveness. Additionally, sunscreens infused with hydration and anti-aging properties cater to the modern consumer's desire for multifunctionality in their beauty regimen. This trend aligns perfectly with the fast-paced lifestyles prevalent in urban Japan, where consumers seek to maximize their time without compromising on quality or results. The integration of multiple functions into single products not only simplifies daily routines but also appeals to those looking for effective solutions that fit seamlessly into their lives. As K-Beauty brands continue to innovate and develop hybrid products, they are likely to capture an even larger share of the market by addressing the evolving preferences of consumers who prioritize both convenience and performance in their beauty choices.
Focus on Men’s Grooming and Beauty
The men’s grooming segment in Japan is witnessing steady growth as K-Beauty brands increasingly cater to this emerging market. Products such as lightweight moisturizers, anti-aging creams, and comprehensive grooming kits are gaining popularity among male consumers who are becoming more conscious of their skincare needs. The influence of Korean male celebrities has played a significant role in promoting skincare as an integral part of daily routines for men, helping to normalize self-care practices within this demographic. Campaigns featuring these celebrities highlight not only product efficacy but also the importance of grooming in enhancing personal image and confidence. As societal norms evolve, more men are embracing skincare routines that were traditionally associated with women, leading to a broader acceptance of beauty products designed specifically for them. This cultural shift is reflected in the increasing availability of targeted products that address common male concerns such as oiliness, acne, and aging skin. By tapping into this growing demand for men's grooming solutions, K-Beauty brands are not only expanding their product lines but also fostering a more inclusive beauty landscape that celebrates self-care for all genders.
Emphasis on Minimalism and Skinimalism
The concept of "skinimalism" has gained significant traction in Japan, where consumers are opting for minimalist skincare routines that focus on fewer but highly effective products. This movement reflects a broader societal shift towards simplicity and intentional consumption in the beauty industry. K-Beauty brands are responding by offering streamlined product lines that emphasize essential skincare steps such as cleansing, hydrating, and protecting the skin without overwhelming consumers with excessive options. For instance, brands are now promoting multifunctional serums that combine hydration with active ingredients targeting specific concerns like pigmentation or fine lines. This approach not only simplifies daily routines but also encourages consumers to invest in high-quality products rather than numerous items that may clutter their shelves. As awareness grows about the benefits of minimalism—such as reduced waste and enhanced product efficacy—more Japanese consumers are embracing skinimalism as a lifestyle choice rather than just a beauty trend. K-Beauty brands that align with this philosophy stand to gain loyal customers who appreciate thoughtful formulations designed for maximum impact with minimal effort, reinforcing the idea that less can indeed be more in skincare practices.
Market Challenges
Intense Market Competition
The Japanese beauty market is highly competitive, with strong domestic brands, international luxury labels, and other Asian competitors vying for consumer attention. For instance, established Japanese brands like Shiseido and SK-II have cultivated a loyal customer base over decades, leveraging their deep understanding of local consumer preferences. This entrenched loyalty poses a significant challenge for K-Beauty brands attempting to penetrate the market and maintain market share. The influx of Western beauty brands has further intensified this competition, compelling K-Beauty brands to innovate continuously and differentiate their products to stand out. As a result, K-Beauty companies are increasingly focusing on unique formulations and marketing strategies that resonate with Japanese consumers. They must not only offer high-quality products but also create compelling narratives that align with local values and aesthetics. This dynamic environment necessitates that K-Beauty brands remain agile and responsive to emerging trends while addressing the established dominance of local players.
Regulatory and Cultural Barriers
K-Beauty brands must navigate stringent regulatory requirements in Japan, including ingredient approvals and labeling standards. These regulations can slow down product launches and increase operational costs, complicating market entry strategies. For example, the approval process for cosmetics can be lengthy, requiring comprehensive testing and documentation before products can reach consumers. Additionally, cultural differences in beauty preferences and routines may limit the adoption of certain K-Beauty products. Japanese consumers often favor understated makeup looks and minimalistic routines, which may conflict with some of the more elaborate K-Beauty trends. This necessitates that K-Beauty brands adapt their offerings to align with local tastes, focusing on simplicity and subtlety rather than bold statements. Brands that successfully tailor their products to meet these cultural expectations are more likely to resonate with Japanese consumers, fostering acceptance and loyalty in a challenging market landscape. Thus, understanding both regulatory frameworks and cultural nuances is essential for K-Beauty brands aiming to thrive in Japan.
Market Opportunities
Leveraging Technological Advancements for Product Innovation
The integration of advanced technologies in beauty products, such as AI-powered skincare diagnostics and wearable beauty devices, presents a substantial opportunity for K-Beauty brands to differentiate themselves. For instance, Kao Corporation's SENSAI brand has introduced an AI-powered tool called the "Silk Skin Checker," which analyzes skin conditions using facial scan data from users' devices. This innovative tool evaluates five categories—Moisture, Spots, Wrinkles, Texture, and Dark Circles—providing personalized skincare recommendations based on the user's unique skin profile. Additionally, Banuba's TINT platform utilizes AI algorithms to analyze individual skin types and imperfections, offering tailored product suggestions that address specific concerns like acne or dark spots. These technological advancements not only enhance the consumer experience but also appeal to tech-savvy Japanese consumers who value precision and innovation in their skincare routines. By offering cutting-edge solutions that cater to individual skincare needs, K-Beauty brands can position themselves as leaders in the market. Furthermore, partnerships with tech companies can help create unique offerings that elevate the consumer experience, solidifying brand loyalty and encouraging repeat purchases.
Expanding into Untapped Demographics and Regions
K-Beauty brands can capitalize on the growing interest in skincare among younger and male demographics in Japan. Tailoring product lines to meet the specific needs of these segments, such as lightweight and multi-functional solutions, can unlock new revenue streams. For instance, brands like Innisfree have successfully launched campaigns targeting younger consumers by promoting products that are not only effective but also environmentally friendly. Moreover, expanding into rural areas and smaller cities through online platforms and targeted marketing can help reach underserved markets. Recent studies indicate that online shopping has surged in these regions, with consumers increasingly turning to e-commerce for their beauty needs. By leveraging social media marketing and influencer partnerships tailored to local tastes, K-Beauty brands can foster greater brand recognition and adoption among diverse demographics. This strategic approach not only broadens market reach but also cultivates a loyal customer base eager for innovative skincare solutions that resonate with their lifestyles and values.
Market Segmentation Analysis
By Type
In the Japan K-Beauty Product Market, the type segmentation includes sheet masks, cleansers, moisturizers, and other specialized products. Sheet masks are highly popular due to their ease of use and effectiveness, with Japanese consumers valuing the variety of textures and infused ingredients that address specific skin concerns, thereby maintaining their status as a fundamental K-beauty product. Cleansers occupy a significant portion of the market, driven by the Japanese emphasis on meticulous skincare routines; innovations such as double cleansing systems and gentle formulations for sensitive skin further enhance their appeal. Moisturizers are essential in the Japanese K-beauty arsenal, offering advanced hydration, anti-aging benefits, and skin barrier protection, while the demand for lightweight, non-greasy formulations that provide long-lasting moisture continues to grow. Additionally, the "Others" category, which includes serums, essences, sunscreens, and specialized treatments, complements comprehensive skincare regimens by allowing consumers to address specific skin issues and support overall skin health, thereby contributing to the market's growth. Collectively, these product types illustrate the diverse and innovative nature of the Japan K-Beauty Market, catering to a wide range of consumer needs and preferences.
By Application
K-beauty products in Japan are utilized across various applications, including the beauty business, personal use, and institutional settings. In the beauty business segment, these products are extensively employed in salons, spas, and professional skincare services, leveraging the expertise and trusted reputation of K-beauty brands to enhance service quality and customer satisfaction. The personal application segment dominates the market, driven by individual consumers who seek high-quality and effective skincare and beauty solutions. This demand is fueled by a strong cultural emphasis on skincare and the desire for aesthetically pleasing skin. Additionally, K-beauty products are used in institutional applications such as hotels and wellness centers, where they enhance guest experiences and promote relaxation and beauty. Together, these application segments illustrate the broad and versatile use of K-beauty products in Japan, catering to both professional and personal skincare needs.
Segments
Based on Type
- Sheet Masks
- Cleansers
- Moisturizers
- Others
Based on Application
- Beauty Business
- Personal
- Others
Based on End User
- Male
- Female
- Children and Teenage
Based on Distribution Channel
- Online Retail
- Supermarket/Hypermarket
- Specialty/Monobrand Stores
Based on Region
- Tokyo
- Osaka
- Kyoto
- Other Regions
Regional Analysis
Osaka (25%):
Osaka follows as the second-largest region, holding a 25% market share. Known for its vibrant beauty and fashion scene, Osaka attracts a diverse range of consumers who are keen on adopting the latest beauty trends. The region benefits from a strong network of trendy retail outlets and a tech-savvy population that actively engages with digital marketing and e-commerce platforms. Additionally, Osaka’s strategic location as a commercial center facilitates efficient distribution and accessibility of K-beauty products.
Nagoya (15%):
Nagoya, accounting for 15% of the market share, is another key region contributing to the growth of the Japan K-Beauty Product Market. As one of Japan’s largest metropolitan areas, Nagoya boasts a significant middle-class population with increasing disposable incomes. The region’s consumers show a growing preference for high-quality skincare and beauty solutions, driving demand for both established and emerging K-beauty brands. The presence of numerous shopping malls and beauty specialty stores enhances product availability and consumer accessibility.
Key players
- Able C & C Ltd
- Adwin Korea Corporation
- Amorepacific Corporation
- CLIO COSMETICS Co. Ltd
- Cosrx Inc
- LG H&H Co. Ltd. (LG Corporation)
- The Crème Shop Inc
- The Face Shop Inc
- Tonymoly Co. Ltd
- Aekyung Industrial Co
Competitive Analysis
The Japan K-Beauty Product Market is characterized by intense competition among both global giants and innovative local brands. Leading companies such as Amorepacific Corporation and LG H&H Co. Ltd leverage their extensive product portfolios and strong brand reputations to dominate the market. These firms benefit from significant investments in research and development, allowing them to introduce cutting-edge products that meet the evolving demands of Japanese consumers. Additionally, brands like Cosrx Inc and Tonymoly Co. Ltd distinguish themselves through unique formulations and trendy packaging, appealing to younger demographics and skincare enthusiasts. The Face Shop Inc and CLIO COSMETICS Co. Ltd enhance their market presence through strategic marketing initiatives and expansive distribution networks, including robust online retail platforms. Emerging brands are also making significant inroads by focusing on niche segments such as natural and organic skincare, which resonates with the increasing consumer preference for clean beauty products. The competitive landscape is further driven by continuous innovation, strategic collaborations, and the ability to swiftly adapt to market trends, ensuring that key players remain agile and responsive in a dynamic environment. Overall, the competitive intensity in the Japan K-Beauty Product Market fosters a vibrant and dynamic marketplace, encouraging brands to continuously innovate and enhance their offerings to maintain and grow their market share.
Recent Developments
- In October 2023, Amorepacific completed the acquisition of Cosrx for approximately USD 559.7 million. This strategic move is expected to enhance Cosrx's product line and distribution strategy, allowing for innovation and global expansion in the K-Beauty market.
- In September 2023, The Face Shop launched a new line of eco-friendly skincare products aimed at environmentally conscious consumers. This collection features biodegradable packaging and natural ingredients, catering to the growing demand for sustainable beauty solutions in Japan.
- In August 2023, Tonymoly introduced its latest series of vegan skincare products, designed specifically for the Japanese market. These products emphasize cruelty-free formulations and have been well-received by consumers seeking ethical beauty options.
- In July 2023, LG H&H unveiled a new range of K-Beauty cosmetics that incorporate advanced technology for personalized skincare solutions. This innovative approach targets tech-savvy consumers looking for tailored beauty experiences.
- In June 2023, Able C & C announced a partnership with local influencers to promote its latest skincare line in Japan, focusing on younger demographics and leveraging social media for brand awareness.
Market Concentration and Characteristics
The Japan K-Beauty Product Market exhibits a moderately concentrated structure, dominated by major multinational corporations such as Amorepacific Corporation, LG H&H Co. Ltd., and Cosrx Inc., which collectively hold a significant market share due to their extensive product portfolios and strong brand recognition. Despite the presence of these key players, the market remains highly competitive and fragmented, with numerous innovative local and niche brands continuously emerging to cater to diverse consumer preferences. A hallmark characteristic of this market is its emphasis on advanced skincare technologies, high-quality ingredients, and trendy, aesthetically appealing packaging, which resonate well with Japan’s discerning and trend-sensitive consumers. Additionally, the market is characterized by robust distribution channels, including expansive online retail platforms, specialty stores, and traditional supermarkets, ensuring wide accessibility and convenience for consumers. The dynamic nature of the market is further driven by ongoing trends such as the rising demand for natural and organic beauty products, personalized skincare solutions, and sustainable packaging, which compel brands to continuously innovate and adapt. Moreover, strategic collaborations and effective digital marketing initiatives, including influencer partnerships and social media campaigns, play a crucial role in enhancing brand visibility and consumer engagement. Overall, the Japan K-Beauty Product Market is defined by its blend of strong market concentration among leading brands and a vibrant, competitive landscape that fosters continuous innovation and responsiveness to evolving consumer trends.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End User, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan K-Beauty Product Market is expected to continue its robust expansion, driven by a CAGR of 7.30% from 2024 to 2032. Increasing consumer demand for innovative skincare solutions will underpin this growth trajectory.
- E-commerce and digital platforms will play a pivotal role in market expansion. Enhanced online shopping experiences, coupled with advanced digital marketing strategies, will attract a broader consumer base and facilitate seamless product accessibility.
- Consumer preference for natural and organic beauty products will intensify. Brands will focus on incorporating clean ingredients and sustainable practices to meet the growing demand for environmentally friendly and health-conscious skincare options.
- The trend towards personalized skincare will gain momentum. Advanced technologies such as AI-driven diagnostics and customized formulations will enable brands to offer tailored solutions, enhancing consumer satisfaction and loyalty.
- The male grooming segment will experience significant growth as Japanese men increasingly adopt comprehensive skincare routines. Products specifically designed for men, including anti-aging and beard care solutions, will become more prevalent.
- Continuous innovation in product formulations and delivery systems will remain crucial. Brands will invest in research and development to introduce cutting-edge products that address specific skin concerns and leverage the latest beauty technologies.
- Sustainability will become a key differentiator in the market. Brands will prioritize eco-friendly packaging, ethical sourcing of ingredients, and transparent supply chains to align with consumer values and regulatory requirements.
- Collaborations between Korean beauty brands and Japanese retailers will strengthen market presence. Strategic partnerships will enhance distribution networks, improve brand visibility, and enable the introduction of exclusive product lines tailored to the Japanese market.
- Specialty and monobrand stores will expand, offering immersive brand experiences and expert consultations. These stores will cater to dedicated K-Beauty enthusiasts, fostering deeper brand loyalty and higher consumer engagement.
- The integration of advanced skincare technologies, such as biotechnology and smart skincare devices, will revolutionize product offerings. These innovations will provide enhanced efficacy and unique user experiences, positioning K-Beauty brands at the forefront of the beauty industry in Japan.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Indonesia K-Beauty Product Market in 2023, and what is it projected to reach by 2032?
What is the compound annual growth rate (CAGR) for the Indonesia K-Beauty Product Market from 2024 to 2032?
What are the key drivers fueling the growth of the Indonesia K-Beauty Product Market?
Who are the key players in the Indonesia K-Beauty Product Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan K-Beauty Product Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan K-Beauty Product Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (the forecast period) (2023: USD 86.29 million → forecast year: USD 1,773.21 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan K-Beauty Product Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan K-Beauty Product Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan K-Beauty Product Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan K-Beauty Product Market Drivers
- 3.3 Japan K-Beauty Product Market Restraints & Challenges
- 3.4 Japan K-Beauty Product Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan K-Beauty Product Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan K-Beauty Product Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan K-Beauty Product category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan K-Beauty Product Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan K-Beauty Product Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan K-Beauty Product market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan K-Beauty Product Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan K-Beauty Product Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan K-Beauty Product Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan K-Beauty Product (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan K-Beauty Product Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan K-Beauty Product Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan K-Beauty Product Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan K-Beauty Product Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan K-Beauty Product Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan K-Beauty Product Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan K-Beauty Product Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan K-Beauty Product Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan K-Beauty Product Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
