
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
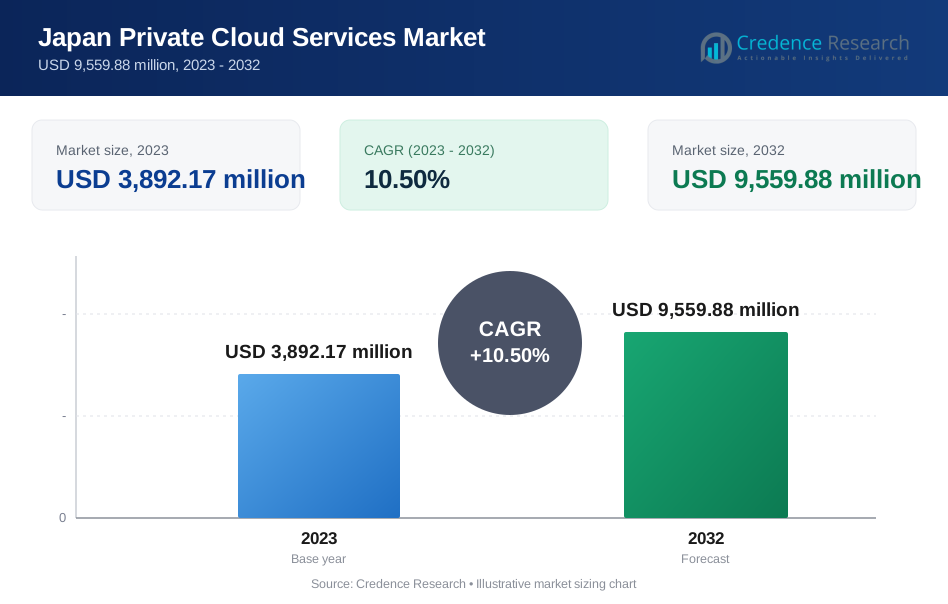
| Japan Private Cloud Services Market Size 2023 | USD 3,892.17 Million |
| Japan Private Cloud Services Market, CAGR | 10.50% |
| Japan Private Cloud Services Market Size 2032 | USD 9,559.88 Million |
Market Overview
The Japan Private Cloud Services market is projected to grow from USD 3,892.17 million in 2023 to an estimated USD 9,559.88 million by 2032, registering a compound annual growth rate (CAGR) of 10.50% from 2024 to 2032. This significant growth is driven by the increasing demand for scalable and secure cloud solutions among businesses in Japan.
Market drivers include the growing need for enhanced data security and compliance, particularly in industries such as finance, healthcare, and government sectors. Additionally, the rising focus on cost optimization and operational efficiency is pushing organizations to adopt private cloud services over traditional IT infrastructures. The trend of hybrid cloud adoption, where companies integrate private and public cloud solutions, is also gaining traction, further boosting the market.
Geographically, the market is predominantly concentrated in urban areas such as Tokyo, Osaka, and Yokohama, where major businesses and enterprises are headquartered. The presence of key players like Fujitsu, NEC Corporation, Hitachi Vantara, and NTT Communications is driving competition and innovation within the market. These companies are continuously expanding their service offerings and investing in advanced technologies to cater to the growing demand for private cloud solutions in Japan.
Market Drivers
Rising Demand for Data Security and Compliance
The increasing demand for enhanced data security and regulatory compliance is a key driver of Japan's private cloud services market. As cyber threats grow more sophisticated, organizations across sectors are prioritizing robust data protection measures. Japan's stringent regulations, including the Act on the Protection of Personal Information, have heightened the need for secure data handling practices. Private cloud solutions offer organizations greater control over their data through dedicated, customizable environments. This is especially crucial for industries like finance, healthcare, and government that deal with highly sensitive information. Private clouds enable the implementation of tailored security measures such as advanced encryption, multi-factor authentication, and comprehensive auditing capabilities. These features allow companies to meet strict regulatory requirements while safeguarding against potential data breaches. For instance, a survey by the Japan Network Security Association found that over 60% of large enterprises cited data security as a top reason for adopting private cloud services. As data privacy concerns continue to escalate, the demand for secure private cloud infrastructure is expected to grow substantially across Japan's business landscape.
Growing Adoption of Digital Transformation Initiatives
The widespread push for digital transformation across Japanese industries is fueling significant growth in the private cloud services market. As businesses strive to remain competitive in an increasingly digital economy, they are rapidly adopting advanced technologies like artificial intelligence, big data analytics, and the Internet of Things. These technologies generate and process massive volumes of data, necessitating robust and scalable cloud infrastructure. Private cloud services provide the flexibility and customization needed to support these digital initiatives while maintaining control over IT resources. They enable seamless integration with existing systems, facilitating a smooth transition during digital transformation efforts. For example, a study by the Japan Information Technology Services Industry Association revealed that over 70% of surveyed companies were actively pursuing digital transformation projects, with private cloud adoption being a key component of their strategies. Industries such as manufacturing, finance, and retail, which rely heavily on real-time data processing and analytics for decision-making, are increasingly turning to private cloud solutions to support their digital transformation journeys.
Cost Optimization and Operational Efficiency
The drive for cost optimization and improved operational efficiency is a significant factor propelling the growth of Japan's private cloud services market. Traditional IT infrastructure often involves substantial capital expenditure and ongoing maintenance costs, which can be burdensome for organizations. Private cloud services offer a more cost-effective alternative by shifting to an operational expenditure model, where companies only pay for the resources they use. This approach not only reduces costs but also enhances IT agility and scalability. Furthermore, private clouds enable the automation of various IT processes, streamlining operations and reducing the workload on IT staff. A report by the Japan Cloud Computing Association highlighted that organizations adopting private cloud services reported an average reduction of 30% in IT infrastructure costs. The ability to rapidly scale resources based on demand allows businesses to respond quickly to changing market conditions without incurring unnecessary expenses. As Japanese companies increasingly prioritize efficiency and cost-effectiveness, the adoption of private cloud services is expected to accelerate across various sectors.
Increasing Preference for Hybrid Cloud Solutions
The growing preference for hybrid cloud solutions, which combine the benefits of both private and public clouds, is another significant driver of the Japan private cloud services market. Hybrid cloud environments allow organizations to leverage the scalability and cost-effectiveness of public clouds for non-sensitive workloads while maintaining control over critical data and applications in a private cloud. This approach offers the best of both worlds, enabling businesses to optimize their IT infrastructure based on their specific needs. In Japan, where regulatory compliance and data sovereignty are critical considerations, the hybrid cloud model is particularly appealing. It allows organizations to store sensitive data on-premises or in a private cloud, while utilizing public clouds for less critical operations. This flexibility is especially valuable for large enterprises and government agencies that require a high level of control over their IT environments. Additionally, the hybrid cloud model supports business continuity and disaster recovery efforts by allowing data to be replicated across different environments, ensuring that operations can continue seamlessly in the event of an outage or other disruptions. As organizations in Japan increasingly recognize the advantages of hybrid cloud solutions, the demand for private cloud services as part of these strategies is expected to grow.
Market Trends
Integration of AI and Machine Learning in Private Cloud Services
A prominent trend in the Japan private cloud services market is the increasing integration of artificial intelligence (AI) and machine learning (ML) technologies into cloud environments. Businesses across Japan are recognizing the potential of AI and ML to enhance their operations, drive innovation, and gain competitive advantages. Private cloud platforms are evolving to support these advanced technologies by providing the necessary computational power, data storage, and infrastructure. For instance, a survey conducted by the Japan Information Technology Services Industry Association (JISA) revealed that a significant portion of Japanese enterprises are actively investing in AI and ML capabilities within their private cloud environments. Companies are leveraging AI and ML for a variety of applications, including predictive analytics, automated decision-making, natural language processing, and more. By integrating these capabilities into their private clouds, organizations can process and analyze vast amounts of data in real-time, improving their ability to respond to market changes, customer demands, and operational challenges. This trend is particularly relevant in industries such as finance, healthcare, and manufacturing, where the ability to derive actionable insights from data is crucial for maintaining competitiveness.
Growing Emphasis on Data Localization and Sovereignty
Another significant trend in the Japan private cloud services market is the growing emphasis on data localization and sovereignty. With increasing concerns over data privacy, security, and regulatory compliance, Japanese organizations are prioritizing the storage and processing of data within the country. This trend is driven by both regulatory requirements and the desire to mitigate risks associated with cross-border data transfers. According to a report by the Ministry of Economy, Trade and Industry (METI), a substantial number of Japanese companies have cited data sovereignty as a primary factor in their decision to adopt private cloud solutions. Private cloud services are becoming the preferred choice for businesses that need to ensure their data remains within Japan's borders while maintaining high levels of security and control. The Japanese government has also been actively promoting data localization through regulations and policies, further encouraging organizations to adopt private cloud solutions that comply with these requirements. This trend is particularly important for sectors such as finance, healthcare, and government, where data sensitivity is paramount. As data localization and sovereignty concerns continue to influence IT strategies, the demand for private cloud services that offer localized data storage and processing capabilities is expected to rise, shaping the future of the market in Japan.
Market Restraints and Challenges
High Initial Costs and Complexity of Implementation
One of the primary restraints in the Japan private cloud services market is the high initial cost and complexity associated with implementing private cloud solutions. Private clouds require substantial upfront investment in infrastructure, software, and skilled personnel, which can be prohibitive for many organizations, especially small and medium-sized enterprises (SMEs). For instance, a survey conducted by the Japan Information Technology Services Industry Association found that cost was cited as the top barrier to cloud adoption among Japanese businesses. The complexity of setting up and managing a private cloud environment also requires specialized knowledge and expertise, which can be challenging for companies lacking in-house IT resources. As reported by the Ministry of Economy, Trade and Industry, many Japanese firms struggle to find and retain skilled IT professionals, further complicating private cloud implementations. The need for ongoing maintenance, updates, and scalability adds to the operational burden, deterring organizations from fully embracing private cloud solutions. This has led to slower adoption rates, particularly among smaller businesses that are more sensitive to cost and resource constraints.
Concerns Over Vendor Lock-in and Interoperability
Another significant challenge in the Japan private cloud services market is the issue of vendor lock-in and interoperability. Organizations investing in private cloud solutions often become heavily reliant on specific vendors for infrastructure, software, and support. This dependency can create difficulties when switching to a different vendor or integrating with other cloud services. For instance, a study by the Japan External Trade Organization revealed that many Japanese companies expressed concerns about being tied to a single cloud provider, limiting their flexibility to adapt to changing business needs. Interoperability issues between different cloud platforms and on-premises systems further complicate matters, as businesses struggle to achieve seamless integration across their IT environments. The Japan Cloud Consortium reported that interoperability challenges were a major concern for enterprises considering private cloud adoption. These factors can deter organizations from fully committing to private cloud solutions, as they weigh the potential risks against the benefits of cloud adoption. Overcoming these challenges requires careful planning, strategic vendor selection, and a focus on creating flexible, interoperable cloud environments that can evolve with the organization's needs.
Market Segmentation Analysis
By Type
Large enterprises dominate the Japan private cloud services market, leveraging their substantial IT budgets and complex infrastructure needs to adopt highly customized and scalable cloud solutions. For instance, a survey by the Japan Information Technology Services Industry Association found that over 70% of large enterprises in Japan have adopted private cloud services. These organizations prioritize data security, compliance, and control over their IT environments. Meanwhile, small and medium-sized enterprises (SMEs) are gradually increasing their adoption of private cloud services. A study by the Ministry of Economy, Trade and Industry revealed that SME adoption of cloud services grew by 15% year-over-year. Although high initial costs and implementation complexity pose challenges, the growing availability of more affordable options is encouraging SMEs to embrace these solutions. For example, a report by IDC Japan noted that local cloud providers are increasingly offering tailored private cloud packages for SMEs, contributing to the segment's growth.
By Services
In the Japan private cloud market, Software as a Service (SaaS) is the most widely adopted service model. According to a survey conducted by the Cloud Service Users Association in Japan, over 60% of businesses using private cloud services have implemented SaaS solutions. This popularity stems from the ease of access to software applications without extensive infrastructure management. Platform as a Service (PaaS) is also gaining traction, with the Japan External Trade Organization reporting a 25% increase in PaaS adoption among Japanese businesses over the past year. This growth is driven by organizations focused on innovation and rapid application deployment. Infrastructure as a Service (IaaS) remains critical for businesses needing scalable solutions. A government report on digital transformation trends indicated that IaaS usage in private clouds has doubled among Japanese enterprises in the last three years, particularly in sectors with fluctuating workloads such as e-commerce and financial services.
Segments
Based on Type
- Large Enterprises
- SMEs
Based on Services
- Software as a Service (SaaS)
- Platform as a Service (PaaS)
- Infrastructure as a Service (IaaS)
Based on Industry Vertical
- Banking, Financial Services, and Insurance (BFSI)
- Telecom
- Government and Education
- Healthcare
- Retail and Manufacturing
- Media and Entertainment
- Energy and Utilities
- Others
Based on Region
- Tokyo
- Osaka
- Yokohama
Regional Analysis
Kanto Region (45%):
The Kanto region, which includes Tokyo, accounts for the largest share of the Japan private cloud services market, contributing approximately 45% of the total market revenue. Organizations in this area prioritize advanced infrastructure and secure data management solutions, driving their reliance on private cloud services. This trend is bolstered by support from leading cloud service providers who cater to the unique requirements of these enterprises. For instance, a survey conducted by the Japan Information Technology Services Industry Association (JISA) revealed that Tokyo-based companies had the highest adoption rate of private cloud services among all regions in Japan.
Kansai Region (25%):
The Kansai region, centered around Osaka, holds the second-largest share of the Japan private cloud services market, contributing around 25% of the market revenue. Regional companies are increasingly investing in private cloud services to facilitate their transition into digital enterprises and to fortify their data protection capabilities. This heightened demand reflects the overall trend towards technological modernization across various industries. For example, a study by the Kansai Economic Federation found that over 60% of surveyed companies in the region planned to increase their investment in private cloud services within the next three years.
Key players
- Cisco Systems, Inc.
- Dell Inc.
- HP Inc.
- IBM Corporation
- Microsoft Corporation
- Oracle Corporation
- Rackspace Hosting, Inc.
- Red Hat, Inc.
- com, Inc.
- VMware, Inc.
Competitive Analysis
The Japan private cloud services market is characterized by intense competition among global technology giants. Key players like Cisco Systems, Dell Inc., and HP Inc. dominate the hardware and networking segments, providing robust infrastructure solutions essential for private cloud environments. IBM Corporation and Microsoft Corporation lead in the software and services domains, offering comprehensive cloud solutions that cater to the diverse needs of large enterprises. Oracle Corporation, with its strong database and enterprise software offerings, is a significant player in the market, particularly in data-intensive industries. Rackspace Hosting, Inc. and Red Hat, Inc. provide specialized cloud hosting and open-source solutions, appealing to organizations seeking flexible and customizable private cloud options. Salesforce.com, Inc. and VMware, Inc. are also key players, known for their innovative software platforms that support digital transformation initiatives. The competitive landscape is dynamic, with companies continually innovating to capture a larger market share in Japan.
Recent Developments
- In April 2024, Microsoft announced a US$2.9 billion investment over two years to expand its hyperscale cloud computing and AI infrastructure in Japan. This includes increasing cloud capacity, training 3 million people in AI skills, and opening its first Microsoft Research Asia lab in Japan.
- In April 2024, Oracle announced plans to invest more than $8 billion over the next 10 years to expand its cloud computing and AI infrastructure in Japan. This includes growing Oracle Cloud Infrastructure's footprint across Japan and expanding local support and operations teams.
- In May 2023, Dell Technologies unveiled new Dell APEX offerings, including Dell APEX Cloud Platforms which will be globally available starting in the second half of 2023. While not specific to Japan, these advancements aim to help customers strengthen multicloud strategies and simplify IT operations globally.
- In June 2021, Rackspace Technology, in partnership with KDDI Corporation and iret, Inc., announced the availability of Rackspace Private Cloud powered by VMware as an optional service for KDDI's cloud platform in Japan.
- In January 2024, HP's parent company Hewlett Packard Enterprise (HPE) announced plans to acquire Juniper Networks for approximately $14 billion. While not specific to Japan, this acquisition aims to enhance HPE's networking portfolio globally, which could impact its offerings in the Japanese market.
- In April 2024, Cisco completed the acquisition of Isovalent, a leader in open source cloud native networking and security. While not specific to Japan, this acquisition aims to enhance Cisco's multicloud networking and security capabilities globally.
Market Concentration and Characteristics
The Japan private cloud services market is moderately concentrated, with a few dominant players such as IBM Corporation, Microsoft Corporation, and VMware, Inc. holding significant market shares. These companies benefit from their extensive experience, broad product portfolios, and strong customer bases, particularly among large enterprises and government sectors. The market is characterized by high entry barriers due to the substantial initial investment required for infrastructure, as well as the need for specialized knowledge and expertise in cloud technologies. Additionally, the market is marked by rapid innovation and the continuous introduction of advanced features and services, which further strengthens the position of established players. However, the market also exhibits competitive dynamics, with several smaller and specialized companies, such as Red Hat, Inc. and Rackspace Hosting, Inc., offering niche solutions that cater to specific industry needs, thus maintaining a balanced competitive environment.
Report Coverage
The research report offers an in-depth analysis based on Type, Services, Industry Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of private cloud services among SMEs in Japan is expected to rise significantly, driven by the availability of more affordable and simplified cloud solutions tailored to their needs.
- The integration of private and public cloud environments will gain momentum, with more Japanese organizations adopting hybrid cloud models to balance security with scalability and cost efficiency.
- The demand for private cloud platforms that support AI and machine learning applications will continue to grow, as businesses seek to leverage these technologies for enhanced decision-making and operational efficiency.
- Data localization will remain a critical factor, with more companies opting for private cloud services that ensure data is stored and processed within Japan to meet regulatory and compliance requirements.
- Private cloud providers will increasingly focus on offering advanced security features, such as zero-trust architecture and AI-driven threat detection, to address growing concerns over cyber threats.
- There will be a greater emphasis on developing customized and industry-specific private cloud solutions, particularly for sectors such as healthcare, finance, and manufacturing, which have unique regulatory and operational requirements.
- The demand for managed private cloud services will increase, as organizations seek to offload the complexity of cloud management to trusted providers, allowing them to focus on core business activities.
- The integration of edge computing with private cloud services will become more prevalent, enabling faster data processing and real-time analytics for industries such as telecom and manufacturing.
- Automation will play a key role in the future of private cloud services, with providers offering more automated tools for resource management, security updates, and compliance monitoring, reducing the operational burden on IT teams.
- The rollout of 5G networks in Japan will drive the development of private cloud services that leverage 5G’s high-speed, low-latency capabilities, supporting advanced applications such as IoT, autonomous systems, and smart cities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Data Security and Compliance
Japanese organizations, especially in finance, healthcare, and government, are prioritizing private cloud adoption to meet stringent data protection regulations and mitigate sophisticated cyber threats. Private cloud solutions offer dedicated environments with advanced security features, enabling compliance with laws like the Act on the Protection of Personal Information.
Growing Adoption of Digital Transformation Initiatives
As Japanese businesses accelerate digital transformation, the need for scalable and customizable IT infrastructure is driving private cloud uptake. Private clouds support integration with AI, big data, and IoT, enabling organizations to modernize operations and remain competitive.
Cost Optimization and Operational Efficiency
Private cloud services allow Japanese companies to shift from capital-intensive IT investments to flexible, pay-as-you-go models, reducing infrastructure costs and improving agility. Automation and resource scalability further enhance operational efficiency, making private clouds attractive for both large enterprises and SMEs.
Increasing Preference for Hybrid Cloud Solutions
The hybrid cloud model, combining private and public clouds, is gaining traction in Japan as it balances security, compliance, and scalability. Organizations can keep sensitive data in private clouds while leveraging public clouds for less critical workloads, supporting business continuity and regulatory requirements.
Emphasis on Data Localization and Sovereignty
With growing concerns over data privacy and government regulations mandating local data storage, Japanese enterprises are increasingly adopting private cloud solutions that ensure data remains within national borders. This trend is particularly strong in regulated sectors and is reinforced by government policy.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Japan private cloud services market?
What factors are driving the adoption of private cloud services in Japan?
Which industries are most likely to adopt private cloud services in Japan?
How is hybrid cloud adoption influencing the private cloud market in Japan?
Who are the key players in the Japan private cloud services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Large Enterprises
- 1.2.2 SMEs
- 1.3 By Services
- 1.3.1 Software as a Service (SaaS)
- 1.3.2 Platform as a Service (PaaS)
- 1.3.3 Infrastructure as a Service (IaaS)
- 1.4 By Industry Vertical
- 1.4.1 Banking, Financial Services, and Insurance (BFSI)
- 1.4.2 Telecom
- 1.4.3 Government and Education
- 1.4.4 Healthcare
- 1.4.5 Retail and Manufacturing
- 1.4.6 Media and Entertainment
- 1.4.7 Energy and Utilities
- 1.4.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 3,892.17 million → 2032: USD 9,559.88 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Private Cloud Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Private Cloud Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Japan Private Cloud Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Japan Private Cloud Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Private Cloud Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Private Cloud Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Private Cloud Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Private Cloud Services Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 3,892.17 million → 2032: USD 9,559.88 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Private Cloud Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Base-Year Market Share, 2023
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Large Enterprises
- 12.3.6.2 SMEs
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Services - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Base-Year Market Share, 2023
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Software as a Service (SaaS)
- 12.4.6.2 Platform as a Service (PaaS)
- 12.4.6.3 Infrastructure as a Service (IaaS)
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Industry Vertical - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Base-Year Market Share, 2023
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Banking, Financial Services, and Insurance (BFSI)
- 12.5.6.2 Telecom
- 12.5.6.3 Government and Education
- 12.5.6.4 Healthcare
- 12.5.6.5 Retail and Manufacturing
- 12.5.6.6 Media and Entertainment
- 12.5.6.7 Energy and Utilities
- 12.5.6.8 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Private Cloud Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Japan Private Cloud Services Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Japan Private Cloud Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2023-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Japan Private Cloud Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Fujitsu
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 NEC Corporation
- 18.4 Hitachi Vantara
- 18.5 NTT Communications
- 18.6 IBM Corporation
- 18.7 Microsoft Corporation
- 18.8 Oracle Corporation
- 18.9 Dell Inc.
- 18.10 VMware, Inc.
- 18.11 Red Hat, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

