
Market Overview:
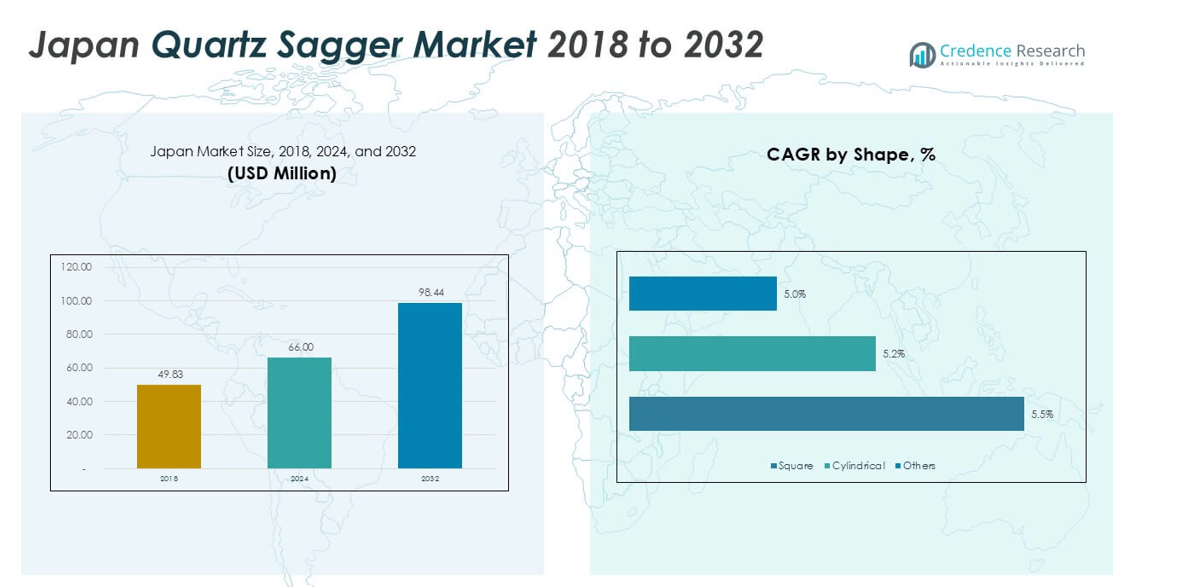
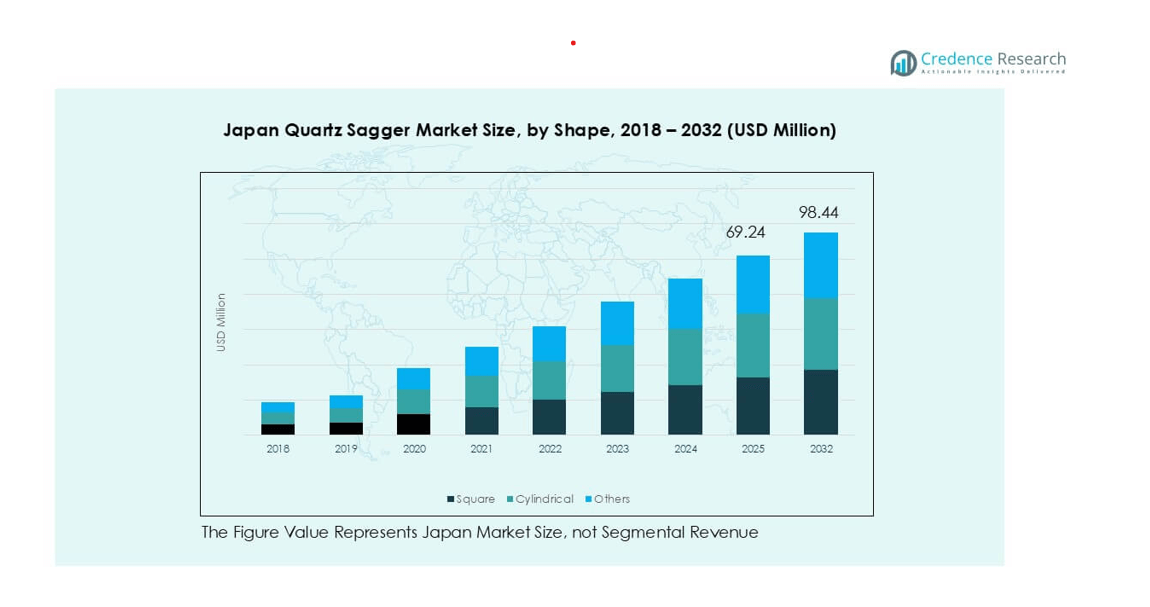
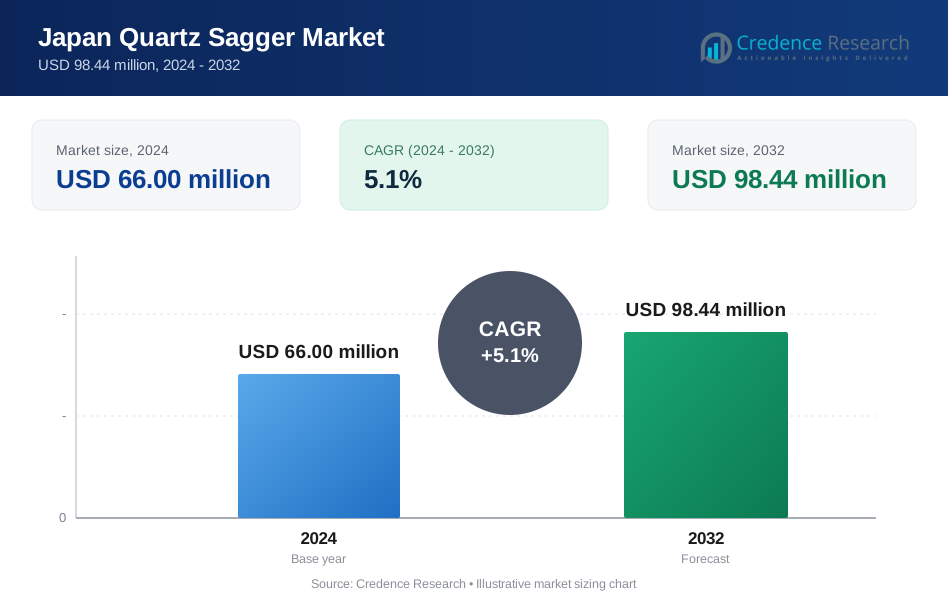
The Japan Quartz Sagger market size was valued at USD 49.83 million in 2018, growing to USD 66.00 million in 2024, and is anticipated to reach USD 98.44 million by 2032, at a CAGR of 5.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Quartz Sagger Market Size 2024 | USD 66.00 million |
| Japan Quartz Sagger Market, CAGR | 5.1% |
| Japan Quartz Sagger Market Size 2032 | USD 98.44 million |
The Japan quartz sagger market is shaped by the presence of global and domestic leaders, including Saint-Gobain, NORITAKE Co., Limited, Morgan Advanced Materials plc, Zibo Gotrays Industry Co., Ltd., and Liling Zen Ceramic Co., Ltd. These companies focus on high-purity quartz materials, advanced design, and strong supply chains to meet the stringent requirements of semiconductor, ceramic, and metallurgy industries. Among regions, the Kanto region led the market in 2024, capturing nearly 35% share, driven by its concentration of electronics and semiconductor manufacturers. Kansai and Chubu followed as strong contributors, supported by their advanced ceramics and automotive manufacturing bases.
Market Insights
- The Japan quartz sagger market was valued at USD 66.00 million in 2024 and is projected to reach USD 98.44 million by 2032, growing at a CAGR of 5.1%.
- Growth is driven by rising demand from the semiconductor and electronics industry, where quartz saggers ensure high-purity firing, sintering, and heat treatment processes.
- A key trend is the shift toward customized, high-purity saggers designed for precision manufacturing, with companies investing in advanced R&D and sustainable production practices.
- Competition is intense, with leading players such as Saint-Gobain, NORITAKE Co., Limited, and Morgan Advanced Materials plc focusing on innovation, while regional firms like Zibo Gotrays Industry Co., Ltd. strengthen their presence through cost-effective solutions.
- Regionally, Kanto held 35% share in 2024, Kansai followed with 20%, and Chubu accounted for 18%, while Kyushu and Okinawa contributed 12%, reflecting the dominance of semiconductor and ceramic hubs.
Market Segmentation Analysis:
By Shape
The square segment dominated the Japan quartz sagger market in 2024, holding over 45% of the total share. Square saggers are widely preferred for their structural stability, uniform heat distribution, and efficient stacking capability during high-temperature processing. Their durability and ability to withstand repeated thermal cycles make them the leading choice in large-scale firing operations. Cylindrical saggers are also gaining traction, especially in precision sintering processes, while other shapes remain limited to niche applications. Rising demand from high-volume manufacturing industries continues to reinforce the leadership of square saggers in the market.
- For instance, AGC Ceramics, a subsidiary of AGC, manufactures and supplies a wide range of advanced ceramics and refractory materials, including some that can withstand high temperatures, for industrial applications in Japan and worldwide.
By Application
Firing ceramics accounted for the largest share of the Japan quartz sagger market in 2024, with more than 40% of demand. This dominance is driven by extensive use in ceramic component production for electronics, automotive, and construction applications. Quartz saggers provide high thermal resistance and chemical inertness, ensuring defect-free ceramic products, which is critical in advanced applications. Sintering powders and heat-treating metals follow, supported by their growing role in precision manufacturing and metallurgy. The strong expansion of ceramic materials in electronic devices continues to sustain the leadership of this segment.
- For instance, Kyocera and Murata Manufacturing both use high-temperature sintering in their production of electronic-grade ceramic components, such as multi-layer ceramic capacitors and crystal devices. This manufacturing process involves firing ceramic components inside specialized containers called saggers to protect them from contamination.
By End User
The electronics and semiconductors industry led the Japan quartz sagger market in 2024, capturing nearly 50% of the total share. This dominance stems from the country’s strong semiconductor ecosystem, where quartz saggers are essential in firing and sintering processes for components such as wafers and substrates. The demand is reinforced by Japan’s growing investment in chip production and advanced electronic materials. Metallurgy industries and glass industries represent secondary markets, utilizing quartz saggers in specialized heat treatment and glass forming processes. The rapid expansion of semiconductor fabrication drives the growth of this leading end-user segment.
Key Growth Drivers
Expanding Semiconductor and Electronics Industry
The rapid expansion of Japan’s semiconductor and electronics industry is the primary driver for quartz sagger demand. Quartz saggers are essential in firing and sintering processes for wafers, substrates, and ceramic-based electronic components. With Japan investing heavily in semiconductor R&D and capacity expansion, the need for high-purity materials that ensure stable performance at extreme temperatures is increasing. The government’s strategic initiatives to strengthen the domestic chip supply chain further support demand. As production volumes grow, manufacturers rely on quartz saggers for consistent quality, long service life, and compatibility with advanced electronic materials.
- For instance, a major semiconductor fabrication plant utilizes thousands of specialized high-purity quartz wafer boats in its manufacturing operations. These quartz components, which are rated for thermal endurance and stability at temperatures exceeding 1,200°C, are used to hold and transport wafers during high-temperature thermal processes like oxidation and annealing to ensure purity and stability.
Rising Demand for Advanced Ceramics in Industrial Applications
Advanced ceramics play a key role in multiple industries, including automotive, construction, and consumer electronics, fueling quartz sagger adoption. These saggers withstand high thermal loads during ceramic firing, ensuring defect-free outputs for components such as insulators, substrates, and heat-resistant coatings. Japan’s strong presence in ceramics manufacturing, particularly for precision parts in electronics and mobility solutions, reinforces this trend. Increasing applications of ceramics in electric vehicles and renewable energy systems further stimulate market growth. The high performance and durability of quartz saggers make them indispensable for industries seeking both reliability and energy efficiency.
- For instance, in 2024, Kyocera manufactured and supplied advanced technical ceramic components for a variety of high-tech applications, including the production of electric vehicle (EV) batteries and electronic packaging.
Growth in Metallurgy and Heat-Treating Processes
The metallurgy industry in Japan contributes significantly to quartz sagger demand, especially in sintering and heat-treating applications. Saggers are vital for controlling thermal processes in metals, ensuring material integrity and high-quality output. Japan’s focus on producing advanced alloys and specialty metals for aerospace, automotive, and high-performance equipment drives adoption. Additionally, the growing need for energy-efficient and eco-friendly processes in metallurgy aligns with quartz saggers’ capability to withstand repeated thermal cycles. As demand rises for high-strength materials across end-user industries, quartz saggers remain a preferred solution due to their superior thermal stability and resistance.
Key Trends & Opportunities
Shift Toward High-Purity and Customized Quartz Saggers
A growing trend in Japan is the shift toward high-purity and customized quartz saggers to meet the strict quality needs of semiconductors and advanced ceramics. Manufacturers increasingly require saggers designed for specific thermal loads, chemical resistance, and geometries. Customized solutions reduce contamination risk and extend lifecycle, supporting higher yields in production. Companies are also focusing on saggers with improved structural designs for precision applications. This trend offers opportunities for suppliers to expand through value-added services, catering to niche requirements of semiconductor fabs and advanced manufacturing industries across Japan.
- For instance, AGC offers various high-purity materials, such as synthetic quartz glass and specialized ceramics, for semiconductor processing equipment. These materials are critical for ensuring contamination-free wafer manufacturing during high-temperature processes like sintering.
Adoption of Sustainable and Energy-Efficient Manufacturing Practices
Sustainability is creating opportunities for quartz sagger manufacturers, with growing emphasis on energy-efficient production and longer lifecycle products. Industries seek saggers that minimize energy losses during high-temperature operations and withstand multiple reuse cycles. Japan’s regulatory focus on reducing carbon footprints in industrial processes aligns with this opportunity, driving demand for durable, recyclable, and eco-friendly materials. Manufacturers adopting advanced production techniques, such as low-defect quartz processing, gain a competitive advantage. This shift positions quartz saggers as enablers of sustainable manufacturing practices while addressing the long-term cost concerns of end users.
Key Challenges
High Manufacturing Costs and Price Sensitivity
One of the major challenges in the Japan quartz sagger market is the high cost of production. The fabrication of saggers requires high-purity raw quartz, precision processing, and advanced thermal treatment, all of which contribute to elevated costs. Price-sensitive industries, particularly smaller manufacturers in ceramics and metallurgy, often struggle to adopt premium quartz saggers. This restricts broader market penetration. Additionally, fluctuations in raw material prices further increase financial pressure on producers. Balancing cost competitiveness with product quality remains a critical hurdle for suppliers in sustaining growth.
Intense Competition from Alternative Materials
The market also faces challenges from alternative materials such as alumina and silicon carbide saggers, which offer comparable thermal resistance at lower costs in certain applications. These alternatives are gaining popularity in metallurgy and ceramic firing where purity levels are less critical. While quartz saggers hold advantages in high-precision and contamination-sensitive processes, their higher cost limits adoption against cost-effective substitutes. This competitive pressure forces quartz sagger manufacturers to continuously innovate, differentiate, and prove long-term performance benefits to retain market share in Japan’s evolving industrial landscape.
Regional Analysis
Kanto Region
The Kanto region dominated the Japan quartz sagger market in 2024, accounting for nearly 35% of the overall share. The region’s dominance is driven by its concentration of electronics and semiconductor manufacturers, including Tokyo and surrounding industrial hubs. High demand for quartz saggers in semiconductor wafer firing, powder sintering, and advanced ceramics production strengthens its leadership. Growing investments in R&D and technological advancements by leading firms in Kanto continue to fuel demand. The strong presence of Japan’s major electronic material producers ensures this region remains the largest contributor to the quartz sagger market.
Kansai Region
The Kansai region held about 20% of the Japan quartz sagger market in 2024. This share is supported by its diverse industrial base, particularly ceramics and metallurgy, which extensively use saggers for firing and heat treatment. The region’s manufacturing hubs in Osaka and Kyoto also contribute to demand, with a focus on precision ceramics for electronics and optical applications. Investments in energy-efficient production and material innovation further drive adoption. The Kansai region benefits from strong academic-industry collaboration, reinforcing its role as the second-largest regional market for quartz saggers in Japan.
Chubu Region
The Chubu region accounted for approximately 18% of the quartz sagger market share in 2024. This region, home to Japan’s robust automotive and electronics industries, drives demand through applications in ceramics, powder sintering, and glass components. Aichi and Nagoya serve as major industrial centers, supporting extensive usage in both automotive-grade ceramics and semiconductor supply chains. The presence of precision manufacturing facilities also reinforces steady growth. Expanding material applications in electric vehicles and electronic devices enhances demand for quartz saggers, ensuring Chubu’s strong position as a significant regional market in the country.
Kyushu and Okinawa Region
The Kyushu and Okinawa region represented around 12% of the Japan quartz sagger market in 2024. Kyushu is a growing semiconductor hub, housing several fabrication plants and electronics manufacturers, which directly boosts quartz sagger usage in wafer processing and sintering. The region’s rising investment in advanced semiconductor projects has positioned it as a rapidly expanding market. Okinawa’s smaller industrial footprint contributes minimally, but the overall demand is reinforced by Kyushu’s high-tech industry base. The focus on next-generation electronics manufacturing continues to strengthen this region’s share and growth potential within the quartz sagger market.
Hokkaido and Tohoku Region
The Hokkaido and Tohoku region accounted for nearly 8% of the quartz sagger market in 2024. This region benefits from government-backed initiatives to expand semiconductor and electronics material production, especially in Tohoku, which has seen new investments in fabrication facilities. Quartz saggers are increasingly adopted in sintering and ceramic component processing to support these industries. Hokkaido’s limited industrial activity results in a smaller share, but the region’s growing role in Japan’s semiconductor strategy ensures gradual expansion. The ongoing push to decentralize semiconductor production from Kanto further supports market growth in this northern region.
Chugoku and Shikoku Region
The Chugoku and Shikoku region held about 7% of the quartz sagger market in 2024. Demand is largely supported by metallurgy, glass manufacturing, and ceramics industries located in Hiroshima and surrounding areas. The region’s contribution is smaller compared to major hubs but remains consistent due to its industrial specialization. Heat-treating metals and firing ceramics are the main applications of quartz saggers in this region. Continued development of local manufacturing capacity and government incentives for regional industries are expected to sustain steady growth, keeping Chugoku and Shikoku as stable contributors to the national market.
Market Segmentations:
By Shape
- Square
- Cylindrical
- Others
By Application
- Firing Ceramics
- Sintering Powders
- Heat Treating Metals
- Others
By End User
- Electronics and Semiconductors Industry
- Metallurgy Industries
- Glass Industries
- Others
By Geography
- Kanto Region
- Kansai Region
- Chubu Region
- Kyushu and Okinawa Region
- Hokkaido and Tohoku Region
- Chugoku and Shikoku Region
Competitive Landscape
The competitive landscape of the Japan quartz sagger market is characterized by the presence of both international leaders and domestic manufacturers, each focusing on specialized strengths. Global players such as Saint-Gobain, Morgan Advanced Materials plc, and NORITAKE Co., Limited emphasize high-performance materials, extensive product portfolios, and innovation tailored for advanced ceramics and semiconductor processes. Meanwhile, regional firms like Zibo Gotrays Industry Co., Ltd, Liling Zen Ceramic Co., Ltd., and Shandong Topower Pte Ltd. maintain strong positions through cost efficiency, customization, and supply chain proximity. Companies are increasingly investing in R&D to develop high-purity quartz saggers that address contamination concerns and extend product lifecycles. Recent developments show collaborations with semiconductor and electronics industries, as well as strategies focused on expanding production capacity to meet growing demand. The competition remains intense, with differentiation largely based on material purity, durability, pricing strategies, and the ability to meet strict end-user requirements in Japan’s advanced manufacturing ecosystem.
Key Player Analysis
- Zibo Gotrays Industry Co., Ltd
- Saint-Gobain
- NORITAKE CO., LIMITED
- Morgan Advanced Materials plc
- Liling Zen Ceramic Co., Ltd.
- Shandong Topower Pte Ltd.
- Magma Group
- Other Key Players
Recent Developments
- In 2023, Sumitomo Refractories announces the development of a sustainable, recyclable quartz sagger.
- In 2022, RHI Magnesita invests in a new manufacturing facility for advanced quartz saggers in China.
Report Coverage
The research report offers an in-depth analysis based on Shape, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan quartz sagger market will expand steadily, driven by rising semiconductor production.
- Demand will grow for high-purity saggers to ensure contamination-free processing.
- Advanced ceramics applications will strengthen adoption across automotive and electronics industries.
- Metallurgy will remain a consistent user, especially for high-strength alloys and specialty metals.
- Companies will invest in R&D to deliver customized saggers with longer service life.
- Regional hubs like Kanto and Kansai will continue leading due to strong industrial bases.
- Sustainability goals will push manufacturers toward energy-efficient and recyclable quartz saggers.
- Competition from alternative materials will intensify, requiring continuous innovation.
- Strategic collaborations with electronics and semiconductor companies will shape future growth.
- The market will witness increased localization of production to meet rising domestic demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Japan Quartz Sagger market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Japan Quartz Sagger market projected to grow between 2025 and 2032?
Which Japan Quartz Sagger market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Japan Quartz Sagger market?
Who are the leading companies in the Japan Quartz Sagger market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Quartz Sagger Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Japan Quartz Sagger Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 66.00 million → 2032: USD 98.44 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Quartz Sagger Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Quartz Sagger Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Quartz Sagger Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Japan Quartz Sagger Drivers
- 3.3 Japan Quartz Sagger Restraints & Challenges
- 3.4 Japan Quartz Sagger Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Quartz Sagger Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Quartz Sagger Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Quartz Sagger category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Quartz Sagger Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Japan Quartz Sagger Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Japan Quartz Sagger in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Quartz Sagger Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Japan Quartz Sagger Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Japan Quartz Sagger Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Quartz Sagger (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Japan Quartz Sagger
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Japan Quartz Sagger – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Japan Quartz Sagger – Priority Domestic Market 1
Chapter 10. Japan Quartz Sagger – Priority Domestic Market 2
Chapter 11. Japan Quartz Sagger – Priority Domestic Market 3
Chapter 12. Japan Quartz Sagger – Priority Domestic Market 4
Chapter 13. Japan Quartz Sagger Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
