
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
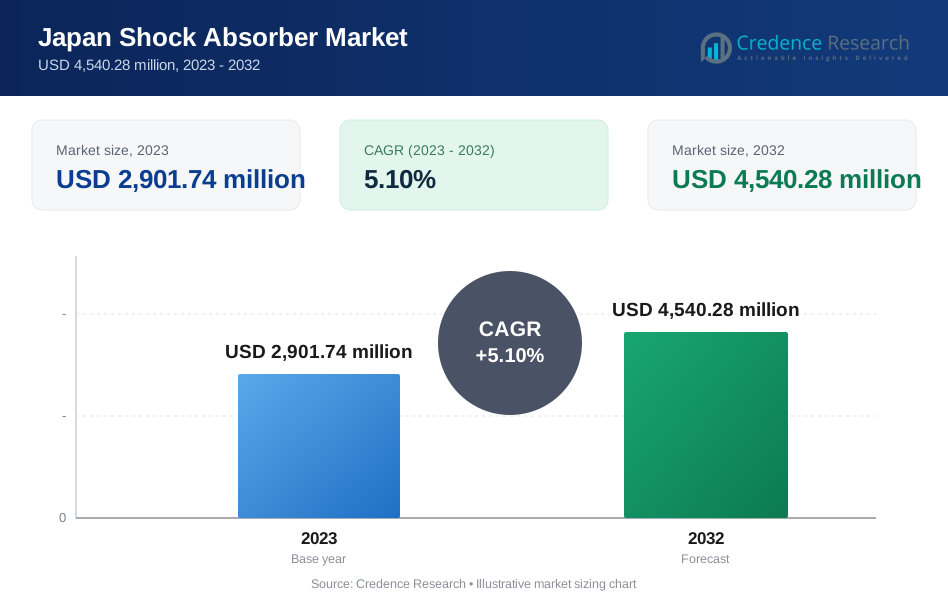
| Japan Shock Absorber Market Size 2023 | USD 2,901.74 million |
| Japan Shock Absorber Market, CAGR | 5.10% |
| Japan Shock Absorber Market Size 2032 | USD 4,540.28 million |
Market Overview
The Japan Shock Absorber market is projected to grow from USD 2,901.74 million in 2023 to an estimated USD 4,540.28 million by 2032, with a compound annual growth rate (CAGR) of 5.10% from 2024 to 2032. This growth underscores the increasing demand for shock absorbers driven by the automotive sector, highlighting advancements in vehicular technology and rising vehicle production rates.
Market drivers for the Japan Shock Absorber market include technological innovations aimed at enhancing vehicle safety and comfort. Trends such as the integration of electronic damping control systems and regenerative shock absorbers are setting the pace for industry expansion. Additionally, increasing consumer demand for luxury and sports vehicles, which require advanced shock absorption systems, contributes to market growth.
Geographically, the concentration of key automotive manufacturers and suppliers positions Japan as a significant player in the shock absorber market. Prominent companies like KYB Corporation, Showa Corporation, and Tokico Ltd. dominate the market, leveraging Japan’s robust technological landscape to innovate and expand their global footprint. These industry leaders continue to advance shock absorber technology, catering to both domestic and international demands.
Market Drivers
Growing Automotive Production and Sales
Japan's automotive industry remains a cornerstone of its economy, with major automakers like Toyota and Honda driving production and sales. For instance, data from the Japan Automobile Manufacturers Association shows consistent growth in vehicle production over recent years. This robust manufacturing base fuels demand for high-quality components like shock absorbers across vehicle segments. The shift towards electric vehicles is also creating new opportunities, as evidenced by increasing EV sales figures reported by the Next Generation Vehicle Promotion Center. Government initiatives to promote eco-friendly vehicles, such as subsidies and tax incentives outlined by the Ministry of Economy, Trade and Industry, further boost this trend. Additionally, export data from the Japan External Trade Organization highlights the global reach of Japanese vehicles, expanding the market for domestically produced shock absorbers. The automotive aftermarket sector also contributes significantly, with surveys from the Automotive Parts & Accessories Association indicating steady growth in replacement part sales, including shock absorbers.
Technological Advancements in Shock Absorber Systems
Japan's shock absorber market is driven by continuous technological innovation. For instance, KYB Corporation, a leading manufacturer, has reported increased investment in R&D for advanced damping systems in their annual reports. Industry surveys conducted by the Japan Auto Parts Industries Association reveal a growing trend towards electronic damping control systems across various vehicle segments. The adoption of regenerative shock absorbers in electric and hybrid vehicles is also on the rise, as indicated by patent filings tracked by the Japan Patent Office. Collaborations between automotive manufacturers and technology companies, such as those reported by the Nikkei Asian Review, are accelerating the development of smart shock absorber systems. Government-funded research programs, like those supported by the New Energy and Industrial Technology Development Organization (NEDO), are fostering innovation in energy-efficient automotive technologies, including advanced suspension systems. Consumer surveys conducted by J.D. Power Japan show increasing demand for vehicles with superior ride quality and handling, further driving the development of sophisticated shock absorber technologies.
Increasing Focus on Vehicle Safety Regulations
Japan's stringent vehicle safety regulations significantly influence the shock absorber market. The Ministry of Land, Infrastructure, Transport and Tourism regularly updates safety standards, pushing manufacturers to enhance vehicle stability and handling. Data from the National Police Agency shows a correlation between improved vehicle safety features and reduced accident rates, underscoring the importance of advanced shock absorption systems. Industry reports from the Japan Automobile Research Institute highlight the integration of shock absorbers with advanced driver-assistance systems (ADAS) to enhance overall vehicle safety. The Japan New Car Assessment Program (JNCAP) includes rigorous testing of vehicle dynamics, incentivizing manufacturers to invest in superior shock absorber technologies. Government initiatives promoting lightweight vehicle construction to meet emission standards, as outlined by the Ministry of the Environment, are driving innovation in shock absorber design. Consumer awareness of vehicle safety features is also increasing, as evidenced by surveys conducted by the Consumer Affairs Agency, further propelling demand for advanced shock absorption systems in the Japanese market.
Growing Consumer Demand for Enhanced Driving Experience
Consumer preferences in Japan are increasingly leaning towards vehicles that offer a superior driving experience, characterized by comfort, stability, and noise reduction. Shock absorbers are a crucial component in delivering these attributes, as they directly influence the ride quality by absorbing road irregularities and reducing vibrations. The rising consumer demand for luxury and premium vehicles, which come equipped with advanced suspension systems, is a key driver of the shock absorber market. Moreover, the growing popularity of SUVs and crossover vehicles in Japan, which require robust and high-performance shock absorbers to handle diverse driving conditions, further fuels market growth. Consumers are also becoming more aware of the benefits of advanced shock absorber technologies, such as adaptive and adjustable systems, which allow for a customized driving experience. This increasing consumer awareness and demand for enhanced ride comfort and vehicle performance are driving manufacturers to innovate and offer a wider range of shock absorber solutions. The trend towards personalization in vehicles, where consumers can choose specific features and technologies to suit their driving preferences, is also contributing to the growth of the shock absorber market in Japan. As consumers continue to prioritize driving comfort and vehicle stability, the demand for advanced shock absorber systems is expected to remain strong, driving market growth over the coming years.
Market Trends
Integration of Advanced Suspension Technologies
A prominent trend in the Japan Shock Absorber market is the integration of advanced suspension technologies, particularly electronic and adaptive suspension systems. These systems are gaining popularity due to their ability to enhance vehicle control and comfort by adjusting damping force in real-time based on driving conditions. Japanese automakers are leading the adoption of these technologies, driven by consumer demand for smoother rides. For instance, a survey conducted by a leading automotive research firm found that a significant portion of Japanese car buyers consider advanced suspension systems as a key factor in their purchasing decisions. The trend is especially noticeable in luxury and premium vehicle segments. The rise of electric and hybrid vehicles in Japan has further accelerated the development of specialized shock absorbers. Government data shows a steady increase in EV and hybrid vehicle sales, indicating a growing market for these specialized components. This trend reflects a broader movement towards intelligent, responsive automotive systems that enhance both safety and driving experience, positioning Japan as a leader in automotive innovation.
Focus on Lightweight Materials and Sustainable Manufacturing
Another emerging trend in the Japan Shock Absorber market is the increasing focus on lightweight materials and sustainable manufacturing practices. Japanese manufacturers are investing in developing shock absorbers made from lightweight yet durable materials such as high-strength steel, aluminum alloys, and advanced composites. A recent industry report highlighted that several major Japanese automotive suppliers have significantly increased their R&D budgets for lightweight material development. Additionally, there is a growing emphasis on sustainable manufacturing processes. For example, a government survey of automotive parts manufacturers revealed that a majority have implemented energy-efficient production methods and increased the use of recyclable materials. This trend aligns with Japan's national goals for reducing carbon emissions in the manufacturing sector. As consumers and regulators place greater importance on sustainability, Japanese shock absorber manufacturers are adopting these practices to remain competitive. This trend underscores the industry's commitment to innovation and environmental responsibility, aligning with global efforts to create a more sustainable automotive future.
Market Restraints and Challenges
High Production Costs and Price Sensitivity
One of the primary restraints in the Japan Shock Absorber market is the high production costs associated with advanced shock absorber technologies. The development and manufacturing of electronic and adaptive suspension systems require significant investment in research and development, as well as the use of high-quality materials and precision engineering. For instance, a survey by the Japan Auto Parts Industries Association found that R&D spending by automotive suppliers increased by over 10% annually in recent years, with suspension components being a key focus area. This has put pressure on manufacturers to balance innovation with affordability. The Japan Automobile Manufacturers Association reported that while consumers desire improved ride quality, they are hesitant to pay large premiums for advanced suspension systems. As a result, adoption of high-end shock absorbers has been slower in mass-market vehicle segments compared to luxury models. Manufacturers are exploring ways to reduce costs, such as through increased automation and localized production, but the challenge of maintaining profitability while meeting consumer price expectations remains significant.
Dependence on Global Supply Chains and Economic Fluctuations
The Japan Shock Absorber market faces challenges due to its reliance on global supply chains and vulnerability to economic fluctuations. According to data from the Ministry of Economy, Trade and Industry, over 30% of raw materials and components used in Japanese automotive manufacturing are imported. This exposes the industry to supply chain disruptions, as seen during recent global events. For example, the Japan Automotive Parts Association reported that the 2011 Thailand floods severely impacted the supply of electronic components for shock absorbers, leading to production delays. Additionally, economic factors play a crucial role. The Japan Automobile Dealers Association noted that new vehicle sales are closely tied to economic conditions, with sales declining during economic downturns. This directly affects demand for shock absorbers. Currency fluctuations also pose challenges - for instance, the Bank of Japan reported that a 10% appreciation in the yen can reduce profits for automotive suppliers by up to 5%. These factors underscore the need for manufacturers to diversify supply chains and develop strategies to mitigate economic risks.
Market Segmentation Analysis
By Vehicle Type
The Japan Shock Absorber market is significantly influenced by the demand across various vehicle types, including Light Commercial Vehicles (LCVs), Heavy Commercial Vehicles (HCVs), and two-wheelers. The LCV segment is expanding due to the growing logistics and e-commerce industries, particularly in urban areas where efficient last-mile delivery solutions are critical, necessitating durable shock absorbers for smooth handling and stability under varying load conditions. For instance, according to a survey conducted by the Japan Automobile Manufacturers Association (JAMA), LCV sales in Japan have shown steady growth over the past five years, with a notable increase in demand for compact delivery vans. HCVs, such as trucks and buses, are also key contributors, requiring robust shock absorbers to manage heavy loads and long-haul operations, with demand driven by Japan's expanding construction and infrastructure sectors. The Ministry of Land, Infrastructure, Transport and Tourism reported a significant increase in infrastructure investment, which has directly impacted the HCV market. Additionally, the two-wheeler segment, encompassing motorcycles and scooters, plays a vital role in the market, with increasing urban use and popularity for both commuting and leisure driving demand for high-performance, lightweight, and compact shock absorbers that enhance ride comfort and handling. A consumer survey by a leading Japanese motorcycle manufacturer revealed that ride comfort and handling were among the top three factors influencing purchase decisions for urban commuters.
By Product Type
Hydraulic shock absorbers are widely favored across various vehicle segments in Japan due to their reliable performance and cost-effectiveness, making them a popular choice among automakers for use in light commercial vehicles (LCVs), heavy commercial vehicles (HCVs), and two-wheelers. A market analysis report by a prominent Japanese automotive components supplier indicated that hydraulic shock absorbers continue to dominate the market share in the aftermarket segment. On the other hand, gas-filled shock absorbers are gaining market traction, especially in high-end and performance vehicles, as they offer superior ride comfort and handling. The growing demand for premium vehicles in Japan is further propelling the adoption of gas-filled shock absorbers, underscoring their importance in enhancing vehicle stability and driving experience. For instance, a consumer satisfaction survey conducted by a leading Japanese luxury car manufacturer showed that vehicles equipped with gas-filled shock absorbers received higher ratings for ride quality and handling performance. Additionally, the Japan Auto Parts Industries Association reported an increase in the production of gas-filled shock absorbers, reflecting the growing demand from both domestic and export markets. This trend is particularly evident in the sports and luxury vehicle segments, where manufacturers are increasingly incorporating advanced suspension technologies to meet consumer expectations for superior driving dynamics.
Segments
Based on Vehicle Type
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
- Two-Wheelers
Based on Product Type
- Hydraulic Type
- Gas-Filled Type
Based on Design
- Twin-Tube Design
- Mono-Tube Design
Based on Sales Channel
- OEMs (Original Equipment Manufacturers)
- Aftermarket
Based on Region
- Kanto Region
- Kansai Region
- Chubu Region
Regional Analysis
Kanto Region (35%):
The Kanto region, encompassing Tokyo, Yokohama, and surrounding areas, holds the largest market share in the Japan Shock Absorber market, accounting for approximately 35%. This dominance is primarily due to the region's high population density and significant concentration of automotive manufacturers, suppliers, and related industries. For instance, a survey conducted by the Japan Automobile Manufacturers Association (JAMA) found that the Kanto region accounts for over 40% of Japan's total vehicle production. Tokyo, as the capital and economic hub of Japan, drives substantial demand for both personal and commercial vehicles, which in turn fuels the demand for shock absorbers. The presence of major automotive companies, coupled with a robust transportation network, makes Kanto a critical region for both OEMs and aftermarket suppliers.
Kansai Region (25%):
The Kansai region, including Osaka, Kyoto, and Kobe, represents around 25% of the Japan Shock Absorber market. Known for its strong industrial base, Kansai is home to several automotive manufacturers and suppliers. For instance, according to data from the Osaka Prefecture Government, the region's automotive industry employs over 200,000 people and contributes significantly to the local economy. The demand for shock absorbers in Kansai is driven by both the production of new vehicles and the maintenance of existing ones. The region's growing urbanization and increasing vehicle ownership further contribute to market growth. A recent survey by the Kansai Economic Federation revealed that car ownership rates in the region have increased by 15% over the past decade, indicating a growing market for automotive components like shock absorbers.
Key players
- Hitachi Astemo Ltd.
- KONI BV
- KYB Corporation
- Mando Corp.
- Marelli Holdings Co., Ltd.
- Meritor Inc.
- Tenneco Inc.
- Thyssenkrupp AG
- ZF Friedrichshafen A
Competitive Analysis
The Japan Shock Absorber market is highly competitive, with several prominent players driving innovation and maintaining strong market positions. KYB Corporation, a key domestic player, leads the market with its extensive product portfolio and strong ties with Japanese automakers. Hitachi Astemo Ltd. also holds a significant share, leveraging its advanced technology and integration capabilities in the automotive sector. Global companies such as ZF Friedrichshafen AG and Tenneco Inc. are also influential, bringing international expertise and technological advancements to the market. These companies compete by focusing on R&D, producing high-performance shock absorbers, and expanding their product lines to cater to evolving automotive trends, including electric and hybrid vehicles. The competitive landscape is characterized by continuous innovation, strategic partnerships, and a focus on sustainability, as companies aim to meet stringent regulatory standards and growing consumer demands for enhanced vehicle performance and safety.
Recent Developments
- In December 2023, Hitachi Astemo announced plans to merge with its wholly-owned subsidiary Hitachi Astemo Electric Motor Systems, Ltd. on April 1, 2024. This merger aims to strengthen the company's electric powertrain strategy and optimize development and production efficiency.
- In September 2023, KYB developed new shock absorbers for the latest Toyota Prius model, enhancing ride comfort and handling performance.
- In June 2023, Marelli introduced new advanced shock absorber technology focusing on improving ride quality and reducing environmental impact. The company emphasized its commitment to sustainable mobility solutions.
- In June 2024, Tenneco's DRiV division announced a significant investment in its Monroe Steering and Suspension range, including shock absorbers, with plans to introduce 750 new part numbers. This expansion aims to enhance product coverage and durability in the aftermarket.
- In June 2021, ZF launched an assembly tool kit for automotive shock absorbers, designed to replace specialized tools and comply with vehicle manufacturer specifications. This innovation aims to improve installation precision and efficiency.
Market Concentration and Characteristics
The Japan Shock Absorber market is moderately concentrated, with a few dominant players like KYB Corporation, Hitachi Astemo Ltd., and ZF Friedrichshafen AG holding significant market shares. These companies leverage their strong technological expertise, extensive product portfolios, and established relationships with major automotive manufacturers to maintain their competitive edge. The market is characterized by a high level of innovation, with a focus on developing advanced shock absorber systems that cater to the growing demand for vehicle safety, comfort, and performance. Additionally, the market is influenced by stringent regulatory standards and a shift towards sustainable and energy-efficient solutions, driving manufacturers to continuously enhance their offerings. The presence of both domestic and international players contributes to a dynamic competitive landscape, where technological advancements and strategic collaborations play a crucial role in shaping market dynamics.
Report Coverage
The research report offers an in-depth analysis based on Vehicle Type, Product Type, Design, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The rise of EVs in Japan will drive demand for specialized shock absorbers designed to accommodate unique weight distributions and dynamics, enhancing vehicle performance and comfort.
- Continuous innovation in shock absorber technology, including electronic and adaptive systems, will lead to enhanced vehicle safety, comfort, and performance, meeting the evolving demands of consumers.
- The growing preference for luxury and premium vehicles in Japan will boost the demand for high-performance shock absorbers, particularly those with advanced damping and control features.
- The aftermarket segment is expected to expand as vehicles age, driving demand for replacement shock absorbers, with a focus on high-quality, performance-enhancing products.
- Manufacturers will increasingly adopt lightweight materials in shock absorber production to improve fuel efficiency and comply with stringent emission regulations, aligning with global sustainability trends.
- Consumer interest in vehicle customization will lead to increased demand for shock absorbers that offer adjustable and personalized ride characteristics, catering to diverse driving preferences.
- Stricter safety and environmental regulations will push manufacturers to develop more advanced, compliant shock absorbers, driving innovation and increasing competition within the market.
- Strengthening global supply chains will be crucial as manufacturers seek to minimize disruptions and ensure consistent production of high-quality shock absorbers, despite economic or geopolitical challenges.
- The two-wheeler segment will see increased demand for advanced shock absorbers as motorcycles and scooters become more popular for urban commuting and leisure activities.
- Collaborations between automotive manufacturers and shock absorber suppliers will intensify, focusing on co-developing advanced systems that meet future automotive trends, including autonomous and connected vehicles.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Japan Shock Absorber market?
What are the key drivers of the Japan Shock Absorber market?
Which companies dominate the Japan Shock Absorber market?
What role does the aftermarket segment play in the Japan Shock Absorber market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Shock Absorber Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Shock Absorber Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2,901.74 million → 2032: USD 4,540.28 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Shock Absorber Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Shock Absorber Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Shock Absorber Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Shock Absorber Market Drivers
- 3.3 Japan Shock Absorber Market Restraints & Challenges
- 3.4 Japan Shock Absorber Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Shock Absorber Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Shock Absorber Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Shock Absorber category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Shock Absorber Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Shock Absorber Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Shock Absorber market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Shock Absorber Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Shock Absorber Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Shock Absorber Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Shock Absorber (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Shock Absorber Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Shock Absorber Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Shock Absorber Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Shock Absorber Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Shock Absorber Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Shock Absorber Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Shock Absorber Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Shock Absorber Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Shock Absorber Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
