
Wages, online buying and older shoppers set demand
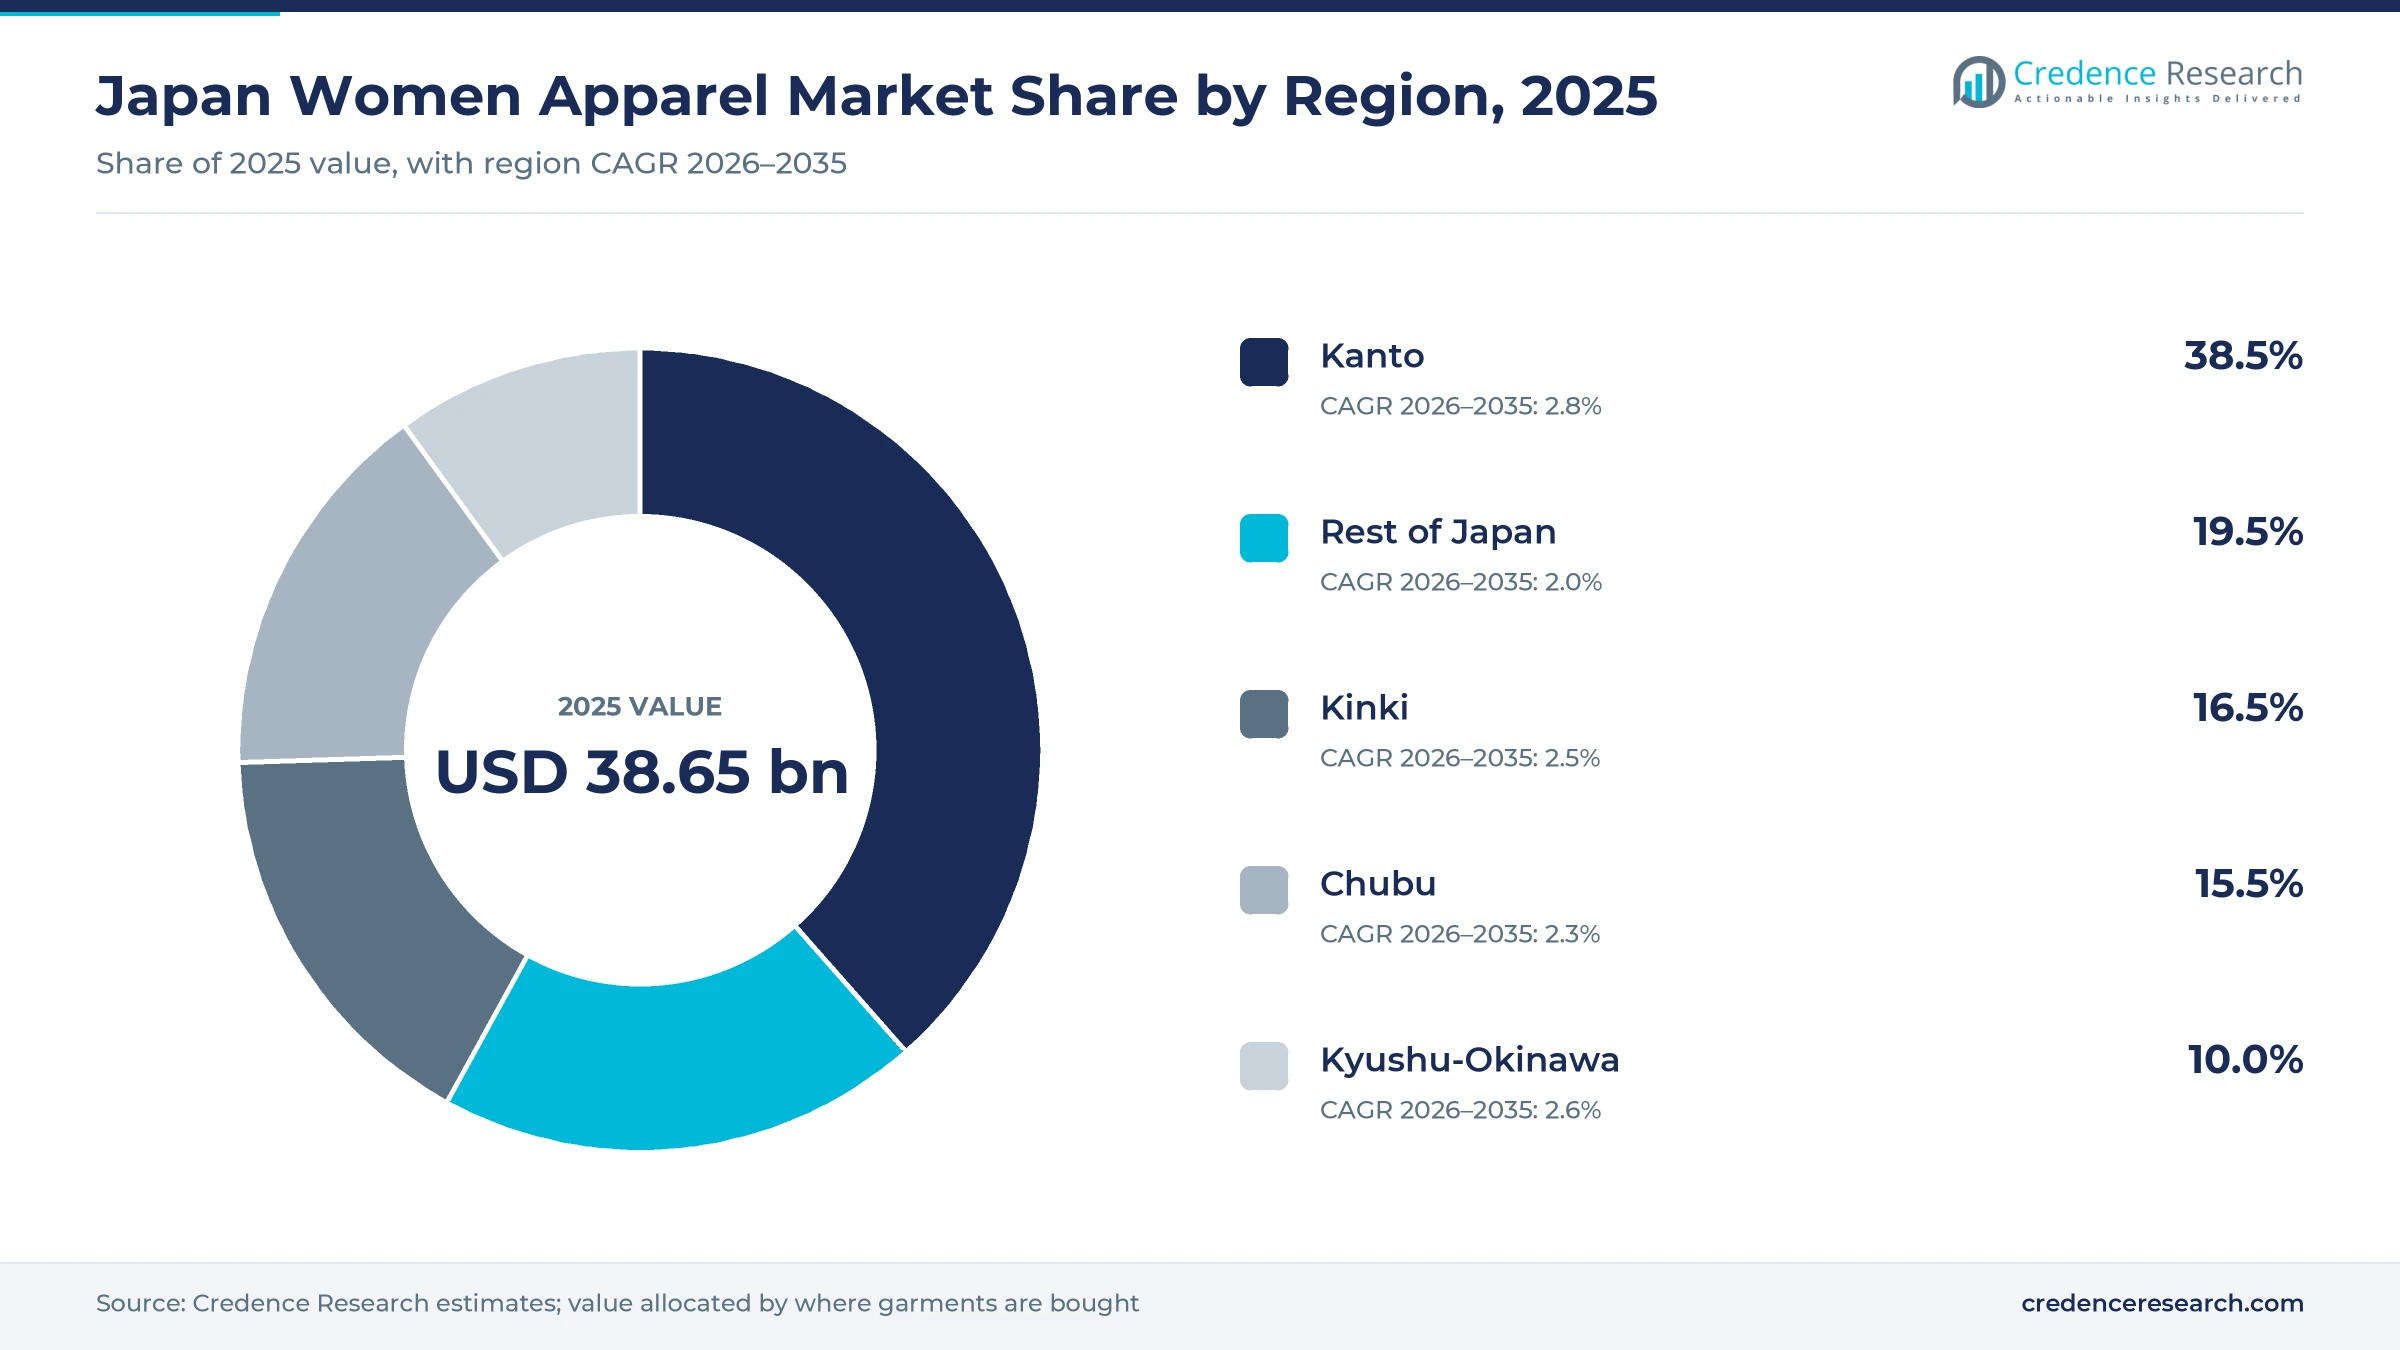
The Japan women apparel market was valued at USD 38.65 billion in 2025 and is projected to increase from USD 39.60 billion in 2026 to USD 49.23 billion by 2035, registering a CAGR of 2.45% during 2026–2035. Demand rests on about 30.8 million employed women who buy workwear and casual clothing, and on a fast-growing group of women aged 65 and over who want comfortable, easy-care garments. Most value moves through value chains such as Uniqlo and Shimamura, department stores in large cities and online malls such as ZOZOTOWN and Rakuten. Kanto held the largest regional share, 38.5% in 2025, because Tokyo concentrates incomes, department store floors and tourist spending. Kanto is also the fastest-growing region at 2.8% a year, as higher incomes and tourist spending concentrate in and around Tokyo. The record heat of summer 2025 is changing product ranges, since cooling innerwear and quick-dry tops now sell over a longer season.
Everyday garments sold through value chains make up the count
The market counts retail spending in Japan on garments for women and girls aged 5 and above, covering casual wear, formal and office wear, sportswear, nightwear and loungewear, and innerwear. It includes sales through value chains, specialty stores, department stores, general merchandise stores and online channels, at mass, premium and luxury price points, and it includes purchases by foreign visitors in Japan.
Footwear, bags, accessories, cosmetics and secondhand garments are excluded, and so are exports by Japanese brands. Almost all garments sold in Japan are imported, mainly from China and Southeast Asia, so value moves from overseas factories through trading houses and brand owners to retail floors and online malls. Brand owners such as Fast Retailing and Adastria control design and retail, which places most of the margin with them rather than with contract makers.
Japan Women Apparel Market Insights
- The Japan women apparel market rises from USD 38.65 billion in 2025 to USD 49.23 billion by 2035, a 2.45% CAGR during 2026–2035, as wage gains offset a shrinking population.
- Kanto held 38.5% of 2025 value, because Tokyo department stores alone sold JPY 441.1 billion of clothing in 2025, the largest city total in Japan.
- Casual Wear held 40.0% of 2025 value, since value chains with national store networks sell everyday tops, trousers and knits in high volume.
- Japan recorded its hottest summer since 1898 in 2025, which lengthens the selling season for cooling innerwear and quick-dry tops.
- The 2026 Tax Reform Proposals would end the JPY 10,000 import tax exemption from April 2028, which narrows the price gap with cross-border sellers.
Casual wear and mass pricing hold most of the value
Casual wear leads while inner wear grows fastest
Based on type, the market is categorized into casual wear, formal wear, sportswear, night wear and inner wear. Casual Wear led with 40.0% of 2025 value because value chains sell everyday tops, trousers and knits in high volume, and Uniqlo built its October 2025 promotions in Japan around jeans, sweats and AIRism cotton tops. Inner Wear grows fastest at 3.2% a year, as hotter summers lift functional underlayers, and Gunze's Asedoron sweat-control range sold more than four million units after its 2024 launch, Monocle reported. Night wear gains from the same shift toward comfort, although it remains the smallest type group by value in 2025.
Mass pricing leads and keeps the fastest pace
Based on price range, the market is categorized into mass, premium and luxury. Mass led with 62.0% of 2025 value because clothing and footwear prices rose only 1.5% in August 2026 against headline inflation of 1.9%, FashionUnited reported, so value chains kept prices below household cost growth. Mass also grows fastest at 2.7% a year, because shoppers buy more items per visit at that level, and Uniqlo said its average spend per customer in Japan rose 7.6% in October 2025 on innerwear and cut-and-sewn purchases. Luxury trails because spending by Chinese tourists has weakened since late 2025.
Working-age women lead while those over 70 grow fastest
Based on age group, the market is categorized into 5-16 years, 16-45 years, 45-70 years, and 70 and above. 16-45 Years led with 41.0% of 2025 value because this group buys office, commuting and casual wardrobes, and employed women rose by 310,000 to 30.82 million in 2024, according to the Labor Force Survey. Women 70 and Above grow fastest at 3.7% a year, because this cohort keeps growing in number while every younger cohort shrinks, as the population data in the trends section show. Girls aged 5 to 16 shrink with each smaller birth cohort.
Stores lead while online buying grows faster
Based on distribution channel, the market is categorized into offline and online. Offline led with 76.0% of 2025 value because fit, fabric feel and same-day purchase still favor stores, and department stores alone sold JPY 1,505.8 billion of clothing in 2025, the Japan Department Stores Association said. Online grows fastest at 4.0% a year, as the e-commerce rate for clothing and accessories rose to 23.38% in 2024 from 22.88% a year earlier, the Ministry of Economy, Trade and Industry said, and brands now add online-only sizes and colors.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Casual Wear | 40.0% | Inner Wear | 3.2% |
| By Price Range | Mass | 62.0% | Mass | 2.7% |
| By Age Group | 16-45 Years | 41.0% | 70 and Above | 3.7% |
| By Distribution Channel | Offline | 76.0% | Online | 4.0% |
Value chain prices anchor what women pay for basics
Women's clothing in Japan is priced per item, and value chains set the reference price that other brands must justify. Functional basics such as leggings and sweat-control innerwear sell in the JPY 2,000 to 4,000 range, while loungewear labels charge two to four times more for fabric, print and gift appeal. Import costs and the yen move prices most, because almost all garments are made overseas. Brands that hold prices while competitors raise them win volume, while premium labels protect margin through design and limited collaborations.
| Offer or segment | Typical price or fee | Basis |
|---|---|---|
| Uniqlo AIRism soft flare leggings, mass | JPY 2,990 per item | Roomie, July 2025 |
| Gunze Asedoron sweat-pad tank tops, two-pack | JPY 3,740 to 4,180 reference retail | Gunze official Rakuten store, 2025 |
| gelato pique sakura print long pants, premium loungewear | JPY 7,480 per item | Fashion Press, March 2025 |
| gelato pique frill dress, premium loungewear | JPY 12,100 per item | Fashion Press, March 2025 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Wage gains, online reach and value chains lift sales
Minimum wage gains lift spending power for working women
Wage gains widen the clothing budget of the women who buy most garments, because a large share of employed women work part time near the minimum wage. The national average minimum wage reached JPY 1,121 an hour in fiscal 2025, and on July 28, 2026, the Central Minimum Wages Council recommended a rise to JPY 1,176, taking effect from about October 2026, Nippon.com reported. Employed women already form the largest buyer group, and women in the 16 to 45 age bracket held 41.0% of 2025 value. Because these increases land on lower-paid workers first, value chains and mass brands capture most of the extra spending, while premium labels gain less from the same change.
Online malls widen the reach of women's brands
Online channels let brands reach women outside the big cities without opening stores, which shifts value toward brands with strong e-commerce operations. Online sales of clothing and accessories reached about JPY 2.80 trillion in 2024, and their e-commerce rate rose to 23.38% from 22.88%, the Ministry of Economy, Trade and Industry said. ZOZO estimates that the online share of fashion in Japan is about 24%, against about 30% in Europe and the United States, which leaves room to grow. Onward Holdings aims for 20 million members by the year ending February 2031. Brands that run their own sites keep more margin than those selling through malls.
Value chains extend low prices to every prefecture
Large value chains keep women's clothing affordable across the country, because their scale lets them hold prices while import costs rise. Shimamura operated 1,423 stores in all 47 prefectures as of August 2026, Go Live Tokyo reported, which gives rural shoppers the same basics as city shoppers. Adastria runs about 1,600 stores across brands such as Global Work, niko and, studio CLIP and Lowrys Farm, FashionSnap reported in October 2025. The mass tier, where these chains sit, held 62.0% of 2025 value. Smaller independent boutiques lose share when chains of this size extend their ranges into office wear and loungewear, and roadside chains also take share from regional general merchandise stores.
Record tourist arrivals support city store sales
Foreign visitors add spending to city department stores and brand flagships, because tax-free shopping draws buyers who pay less than in their home markets. Japan received a record 42.7 million international visitors in 2025, who spent a record JPY 9.5 trillion, Nippon.com reported using Japan National Tourism Organization data. Department store tax-free sales still reached JPY 566.7 billion in 2025 despite a fall that year. Tokyo held most of this demand, which keeps Kanto the largest regional market by a wide margin. Luxury houses and department stores in Tokyo, Osaka and Kyoto gain most when visitor numbers rise, while suburban value chains see little direct benefit from these visitors.
Cooling fabrics and organized resale reshape buying
Hotter summers shift ranges toward cooling fabrics
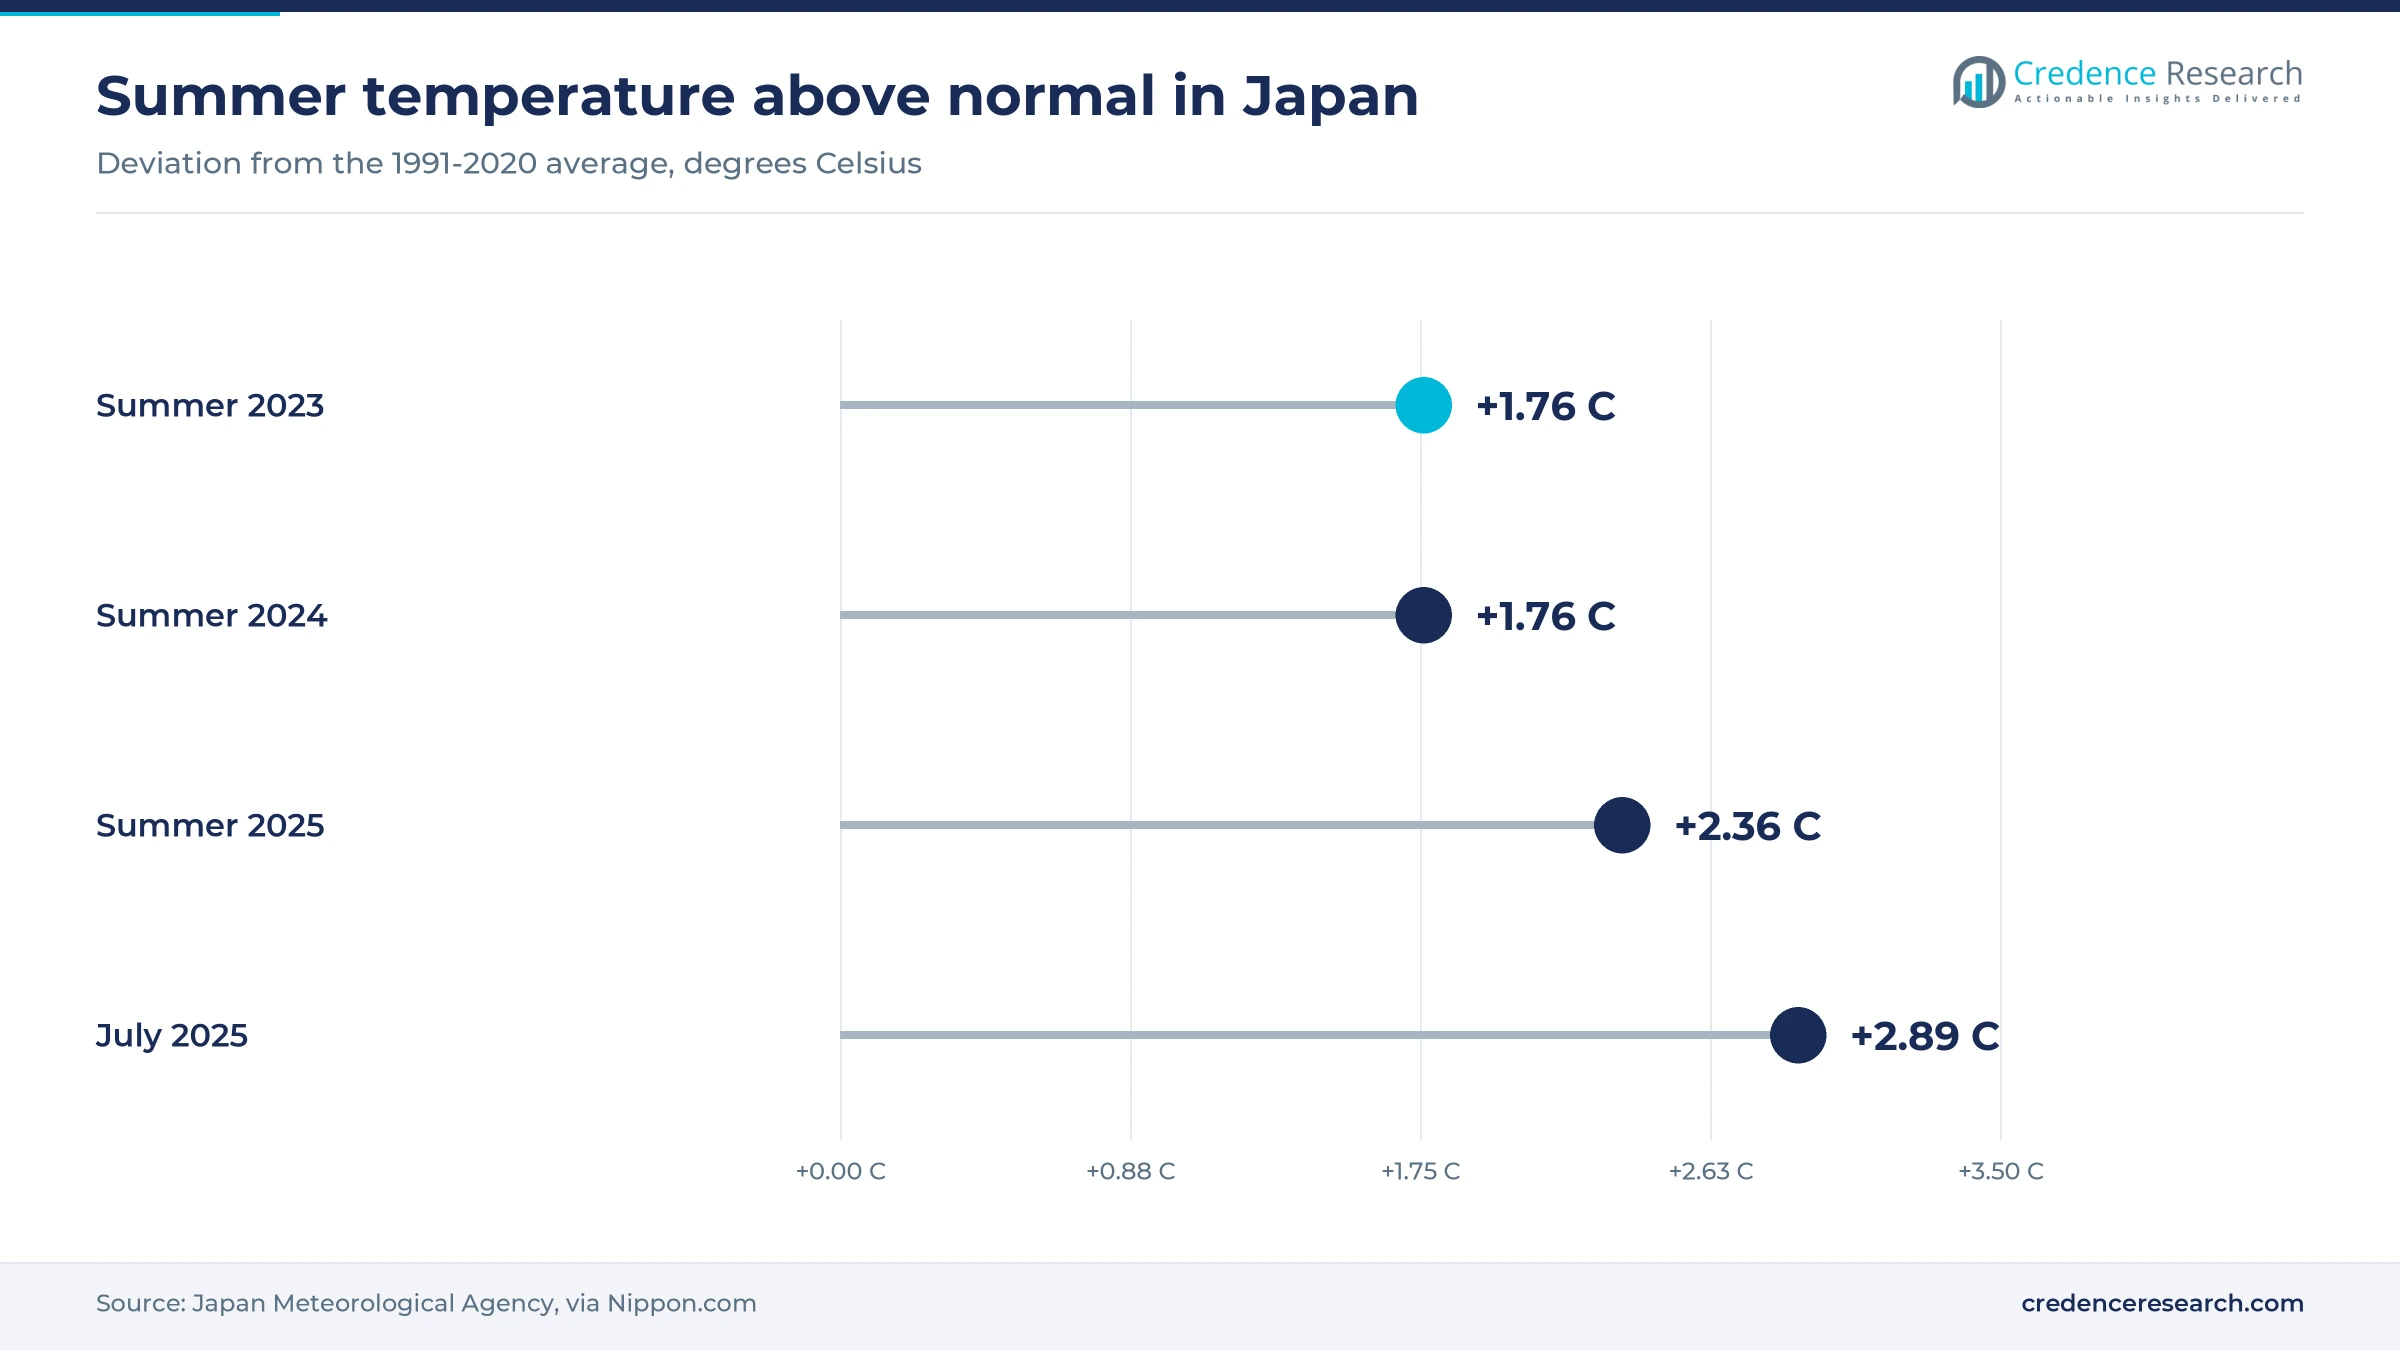
Brands are shifting product ranges toward cooling and quick-dry fabrics, because summers now run longer and hotter. The Japan Meteorological Agency said summer 2025 was 2.36 C above normal, the hottest since records began in 1898, with a national high of 41.8 C in Isesaki on Aug. 5. Muji sells Cool Touch shirts and dresses made from shaped yarns, and Workman makes Ice Assist fabrics that cool and dry fast, Monocle reported. A Gunze executive said Japan's four seasons are giving way to more of a two-season pattern. Innerwear makers and casual chains that shorten autumn ranges and extend summer lines gain the most from this shift.
Organized resale chains rise as waste rules tighten
Resale is rising from flea markets into organized chains, because shoppers sell used garments for cash and buy branded pieces at lower prices. Geo Holdings' 2nd Street runs more than 900 stores in Japan, including Shinjuku 2nd, a women's luxury concept store, WWDJAPAN reported in November 2025. Households discarded about 480,000 tons of clothing in 2024, and the Environment Ministry planned an action plan by March 2026, Nippon.com reported. The government plan targets a 25% cut in clothing waste by fiscal 2030, Fibre2Fashion reported in January 2026. Growth in secondhand clothing resale takes some volume from new mass garments, while brands that run take-back schemes gain repeat visits.
Women over 65 remain an underserved buyer group
Women over 65 remain an open niche for brands, because most ranges are still designed and marketed for younger bodies and lifestyles. Women aged 65 and over numbered 20.5 million in September 2026, or 32.6% of the female population, according to estimates reported by Nippon.com. About 9.4 million people aged 65 or over were in work in 2025, which keeps commuting and work clothing in demand at older ages. Brands that add easy fastenings, softer waistbands and cooling layers for heat-sensitive older shoppers can win this group without heavy discounting, and chains that already serve older customers can test such ranges with little new store investment.
The exercise gap leaves room for entry sportswear
The low exercise rate among women in their 30s and 40s leaves an opening for entry-level sportswear that also works as daily wear. About 40% of women in their 30s and early 40s do not exercise at all, and only about 30% of women in their 30s exercise weekly, a Japan Sports Agency survey found, The Japan Times reported in October 2024. Uniqlo sells AIRism soft flare leggings at JPY 2,990, which keeps the entry price low. Brands that design athleisure pieces for both gym and office can convert this group, as sportswear already grows faster than casual wear and needs little extra store space.
Weak yen, tourist slump and formalwear decline weigh
A weak yen raises the cost of imported garments
Japan imports almost all of its clothing, so a weak yen raises landed costs for every brand that buys from overseas factories. About 98.2% of clothing sold in Japan is imported, FashionUnited reported in December 2025. The yen averaged 151.44 per dollar in 2024 and 149.67 in 2025, against 140.51 in 2023, OECD data show. Mass brands that price below JPY 3,000 are most exposed, because they cannot pass on cost increases without losing shoppers.
Chinese tourist slump cuts luxury and tax-free sales
A sharp fall in Chinese visitors weakens luxury and department store clothing sales, which depend on tax-free buyers. Department store tax-free sales fell 12.7% to JPY 566.7 billion in 2025 as luxury clothing struggled, Jiji Press reported. Chinese arrivals then fell 59.0% in August 2026 after Beijing urged its citizens not to visit Japan, FashionUnited reported, citing preliminary Japan National Tourism Organization estimates. Luxury houses and Tokyo, Osaka and Kyoto department stores are most exposed, while value chains that serve local shoppers feel little of this decline.
Falling department store sales weigh on formal wear
Department stores, the main channel for formal wear and office suits, are losing clothing sales, which constrains the formal wear segment. Department store clothing sales fell 2.2% to JPY 1,505.8 billion in 2025, and in Tokyo they fell 2.0% to JPY 441.1 billion, the Japan Department Stores Association said. Women's wear slipped 0.1% in August 2026 even as total clothing rose. Brands that rely on department store concessions are most exposed unless they move sales online.
Untaxed cross-border parcels undercut domestic prices
Low-priced cross-border sellers keep an edge until 2028, because parcels worth JPY 10,000 or less still enter Japan free of duty and import consumption tax. The 2026 Tax Reform Proposals released on Dec. 19, 2025, would tax such items at the seller level from April 1, 2028, PwC Japan said, and the content may still change. Domestic fast fashion and mass chains are most exposed to this price gap until then.
Kanto spends most while other regions track population
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Kanto | 14.88 | 38.5% | 2.8% |
| Rest of Japan | 7.54 | 19.5% | 1.9% |
| Kinki | 6.38 | 16.5% | 2.5% |
| Chubu | 5.99 | 15.5% | 2.2% |
| Kyushu-Okinawa | 3.87 | 10.0% | 2.5% |
Kanto leads on Tokyo stores, incomes and tourists
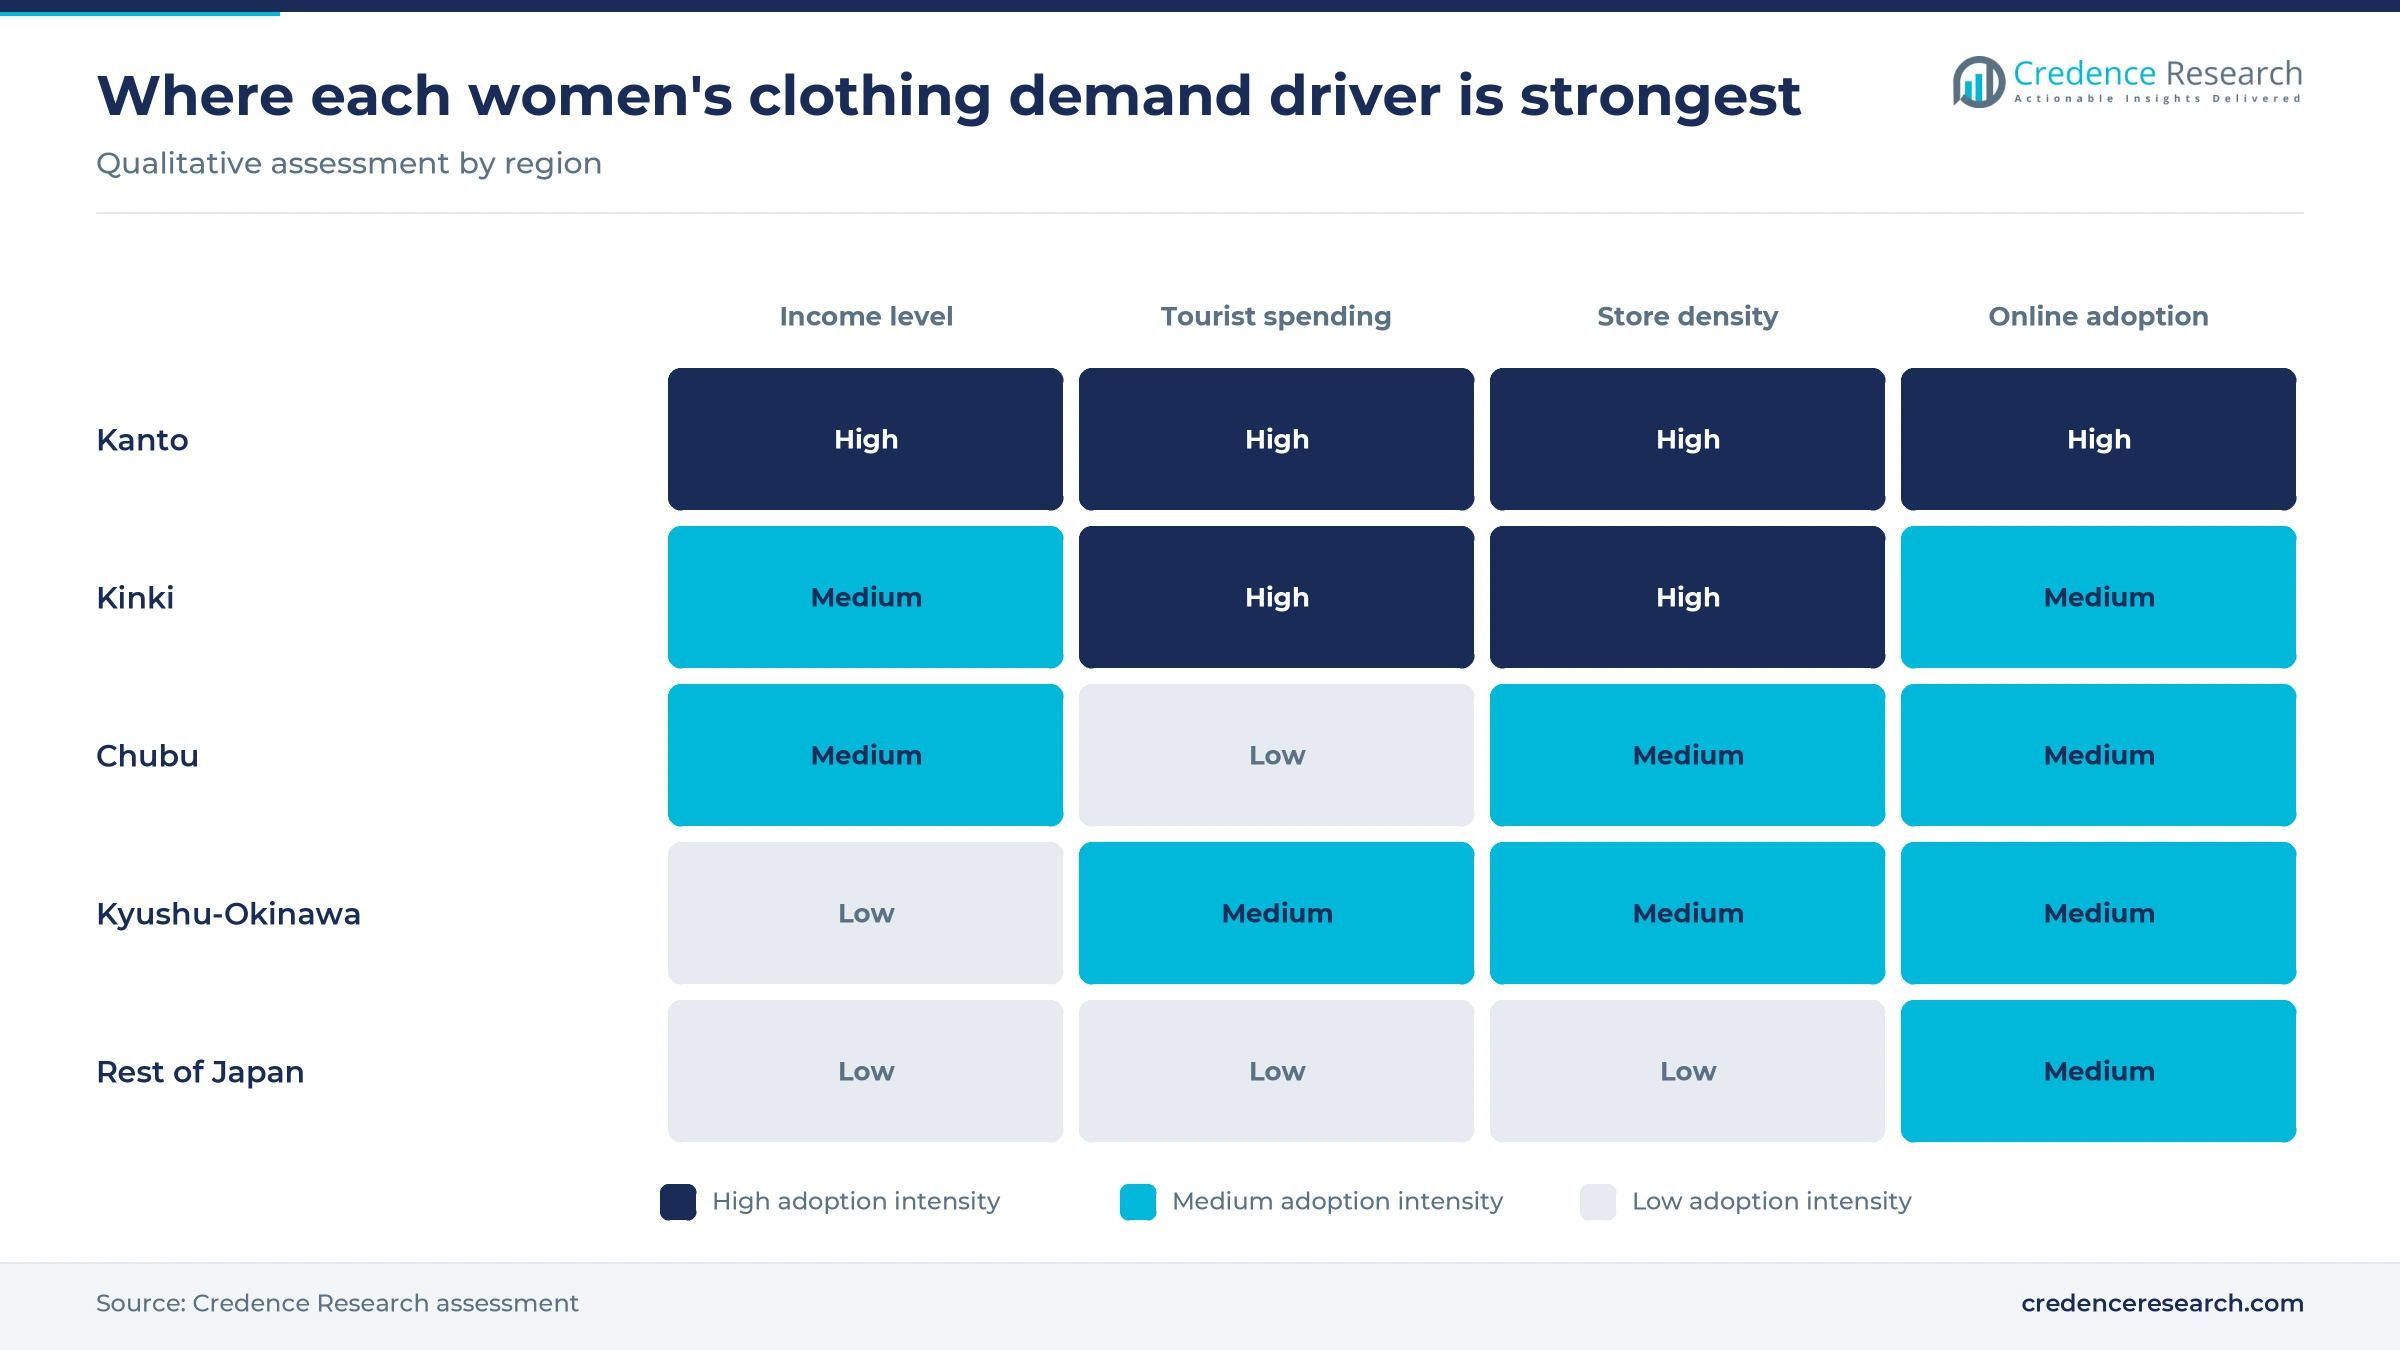
Kanto held 38.5% of 2025 value and is the fastest-growing region at 2.8% a year through 2035. Tokyo department stores sold JPY 441.1 billion of clothing in 2025, more than a quarter of the national department store total, according to the Japan Department Stores Association. Ginza and Omotesando hold the flagships of the luxury houses profiled below, which concentrates tourist and high-income spending in the capital. Isesaki in Gunma recorded 41.8 C in August 2025, which makes Kanto the first market for cooling innerwear each summer.
Kinki relies on Osaka and Kyoto city floors
Kinki held 16.5% of 2025 value and grows at 2.5% a year. Osaka and Kyoto department stores depend on tourist shoppers, which exposes the region to the fall in Chinese arrivals described above. Loungewear brand gelato pique opened stores at Takashimaya Kyoto on June 5, 2026, and at Daimaru Kyoto on June 18, 2026, its operator MASH Holdings announced. 2nd Street reopened its Kobe Sannomiya store after renovation in September 2025. Local demand keeps growth near the national pace even when tourist spending falls.
Rest of Japan grows slowest as residents decline
Rest of Japan, which covers Hokkaido, Tohoku, Chugoku and Shikoku, held 19.5% of 2025 value and grows at 1.9% a year. Credence Research assumes slower growth here because resident numbers fall faster outside the large metropolitan areas, and public data reviewed do not split women's clothing spending by these regions, which is an evidence gap. Brands still open stores at transport hubs, and gelato pique opened a store at minamoa in Hiroshima Station on March 24, 2025. Value chains with stores in every prefecture serve most of this demand.
Chubu follows national spending patterns
Chubu held 15.5% of 2025 value and grows at 2.2% a year. The region combines the Nagoya metropolitan area with manufacturing towns, so demand leans toward value chains and roadside stores rather than city department floors. Women's and children's wear sales at large Chubu retailers fell 13.3% to JPY 17.9 billion in December 2025, as department stores held near level but supermarkets fell 52.7%, the METI Chubu Bureau reported. That gap suggests general merchandise stores are ceding clothing floor space to specialty chains. Shimamura and Uniqlo stores in every prefecture keep local prices in line with national levels.
Kyushu-Okinawa grows from Fukuoka and visitor flows
Kyushu-Okinawa held 10.0% of 2025 value and grows at 2.5% a year. Fukuoka is the region's main fashion center, and 2nd Street opened Fukuoka Tenjin 2nd, a vintage-focused store, in March 2025, WWDJAPAN reported. Foreign visitors arriving through Fukuoka add city demand, although public data reviewed do not split their clothing spending or women's clothing sales by region, so the estimate follows population and tourist arrivals.
Platform deals, mergers and import tax reform
| Development | Status and market relevance |
|---|---|
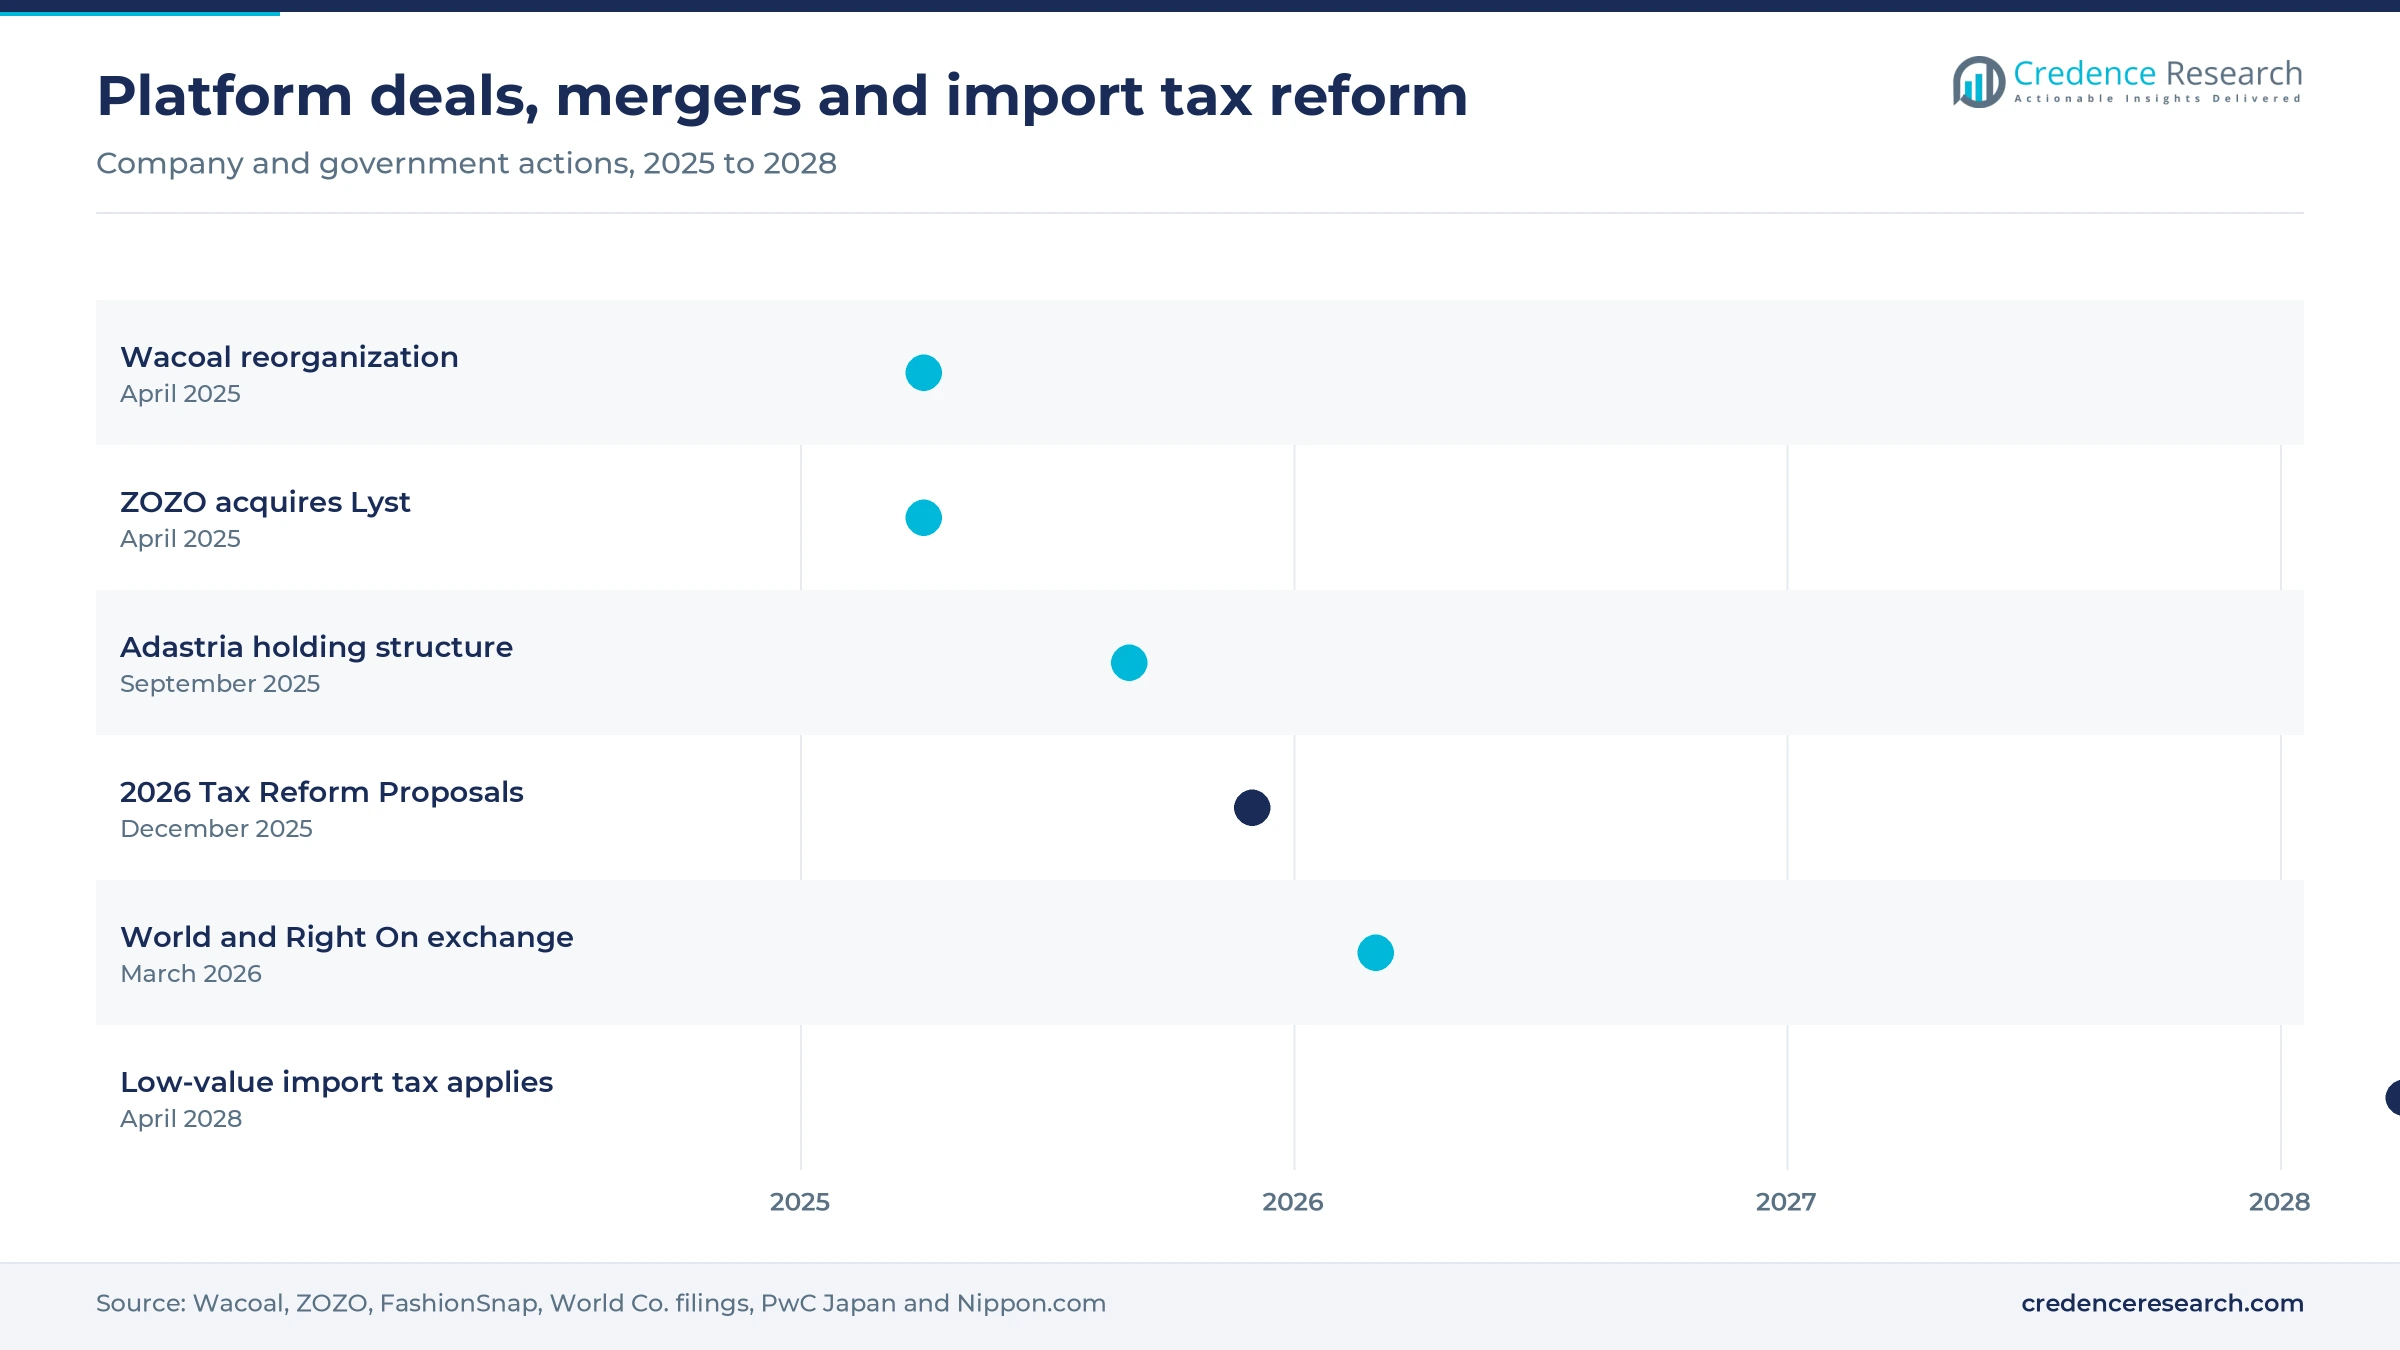
| In January 2025, Wacoal Holdings announced a reorganization that merged three divisions into marketing and supply chain units, effective April 1, 2025. | Completed; the new structure took effect in April 2025 as part of an innerwear turnaround. |
| In April 2025, ZOZO agreed to acquire 100% of Lyst, the London-based fashion shopping platform, through a new British subsidiary. | Acquisition agreed; completion was scheduled for the end of April 2025. |
| In September 2025, Adastria's parent became the holding company &ST HD, and a new Adastria company took over the retail brands. | Completed; the holding structure took effect Sept. 1, 2025. |
| In November 2025, World Co. agreed to acquire casual chain Right On through a share exchange, effective March 1, 2026. | Agreement signed; the exchange was scheduled for March 2026, with Right On delisted in February. |
| In December 2025, the government released 2026 Tax Reform Proposals that would tax low-value imported goods from April 1, 2028. | Proposal; the measures may still change before they apply. |
Cooling fibers, quick-dry knits and size data tools
- Cooling fibers such as AIRism, developed by Uniqlo with Toray, absorb moisture and feel cool, which suits longer hot seasons.
- Quick-dry knits such as Gunze Asedoron and Muji Cool Touch pull sweat away from the skin, which lowers discomfort in humid weather.
- Size and fit data from online malls let shoppers compare garment measurements, which reduces returns for online buyers.
- Membership apps link store and online purchases, which lets brands such as Onward target repeat buyers with their own offers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Value chains and luxury houses split the market
Competition in the Japan women apparel market splits between value chains, department store brands and luxury houses. Fast Retailing's Uniqlo and GU, Shimamura and Adastria compete on price, fabric function and store reach, and their national networks give them the widest access to women outside the big cities. World, Onward and United Arrows compete with office and occasion wear sold through department store floors and their own sites, and World is consolidating weaker chains such as Right On. Wacoal leads in innerwear and is restructuring to restore margins, while PAL Group runs casual and women's fashion chains such as Ciaopanic and Collage Gallardagalante. LVMH, Chanel, Kering and Prada compete for tourists and wealthy residents through flagships in Ginza, Omotesando and Osaka. Buyers judge suppliers on price, fit and fabric function, so brands that control design and retail hold customers longest.
How is the women's clothing supply side organized?
Supply runs in three tiers that largely share the same overseas factories. Vertically integrated value chains such as Fast Retailing, Shimamura and Adastria design, source and sell their own ranges, which lets them control price and stock. Department store brands from World, Onward and United Arrows rely on concessions and their own online sites, and consolidation is continuing as World absorbs weaker chains. Luxury houses such as LVMH, Chanel, Kering and Prada sell through flagships in Tokyo, Osaka and Kyoto. Entry barriers are low online but high in stores, and margins sit with brands that control design and retail.
Retailers and brands that Japanese buyers shortlist
| Company | Type | Role in the market |
|---|---|---|
| Fast Retailing Co., Ltd. (Uniqlo, GU) | Value chain | Sells casual wear, innerwear and loungewear through national stores and online |
| Shimamura Co., Ltd. | Value chain | Sells low-priced women's clothing through 1,423 stores in all prefectures |
| &ST HD Co., Ltd. (Adastria) | Multi-brand retailer | Sells casual brands such as Global Work and Lowrys Farm |
| World Co., Ltd. | Apparel group | Sells women's office and casual brands through department stores and own stores |
| Onward Holdings Co., Ltd. | Apparel group | Sells women's brands such as 23ku through department stores and online |
| TABAYA Holdings Inc. (United Arrows) | Specialty retailer | Sells select women's fashion and own brands through stores and online |
| Wacoal Holdings Corp. | Innerwear specialist | Sells bras, innerwear and loungewear through stores and online |
| PAL GROUP Holdings Co., Ltd. | Multi-brand retailer | Sells casual and women's fashion chains such as Ciaopanic and Collage Gallardagalante |
| LVMH (Louis Vuitton, Christian Dior) | Luxury group | Sells luxury women's ready-to-wear through Japanese flagships |
| Chanel | Luxury house | Sells luxury women's ready-to-wear through boutiques in major Japanese cities |
| Kering (Gucci) | Luxury group | Sells luxury women's ready-to-wear through Gucci boutiques in Japan |
| Prada Group | Luxury group | Sells Prada and Miu Miu women's ready-to-wear through Japanese boutiques |
Older women and cooling wear hold untapped value
Credence Research's view is that women over 65 and cooling functional wear hold more untapped value than the crowded young casual segment. Value chains already serve younger women at low prices, so new entrants there compete mainly on cost. Older women form a third of the female population, yet few ranges are built for their fit and comfort needs. Brands that combine cooling fabrics with easy-care designs should gain share, while a weak yen and the slump in Chinese tourist spending are the main threats to margins through 2027.
Estimates rest on official and company data
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. The 2025 value is a Credence Research estimate built from domestic apparel retail spending, the women's share of that spending and online sales data, and it replaces the earlier estimate, which exceeded total apparel spending for all genders once converted at 2025 exchange rates. Market values come from the Credence Research model, and the regional, type, price, age and channel splits are Credence Research estimates informed by public data. Sources include METI e-commerce surveys, Ministry of Internal Affairs and Communications population and labor data, Japan Department Stores Association sales, Japan Meteorological Agency data, company announcements and business publishers. No official statistic tracks women's clothing sales by region, so regional splits carry wider ranges. No interviews or surveys were used to build these estimates.
Online reach and functional wear decide gains
Credence Research expects women's clothing value in Japan to reach USD 49.23 billion by 2035 as wage gains and online buying offset a shrinking population. Kanto should keep the fastest pace and remain the largest source of value. Inner wear grows at 3.2% a year during 2026–2035, ahead of casual wear, as hotter summers lift cooling layers. A weaker yen and slow tourist recovery are the main downside, while ranges built for women over 65 offer the clearest upside.
Wages, the yen and tourism set the range of outcomes
The range to 2035 depends mainly on whether wage gains keep pace with prices and on how far the yen recovers. A shrinking population caps volume in every case, so value growth must come from higher spending per buyer and from older women buying more often. Tourist flows decide the luxury outcome, because Chinese visitors drove much of the tax-free spending before 2026.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 1.0% | USD 43.11 billion | Real wages fall again and the yen weakens further, cutting spending per buyer |
| Base | 2.45% | USD 49.23 billion | Wages rise near inflation and online channels keep gaining share each year |
| Upside | 3.5% | USD 53.73 billion | Tourist spending recovers and brands win older women with new comfort ranges |
Frequently Asked Questions
How big is the Japan women apparel market?
How does women's clothing spending in Japan split by age cohort?
How do senior women in Japan buy clothing?
How large is loungewear demand among women in Japan?
Which Japanese apparel brands lead women's clothing?
How much women's clothing is bought online in Japan?
Which region leads women's clothing demand in Japan?
What are the main challenges for women's clothing sellers in Japan?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Casual Wear
- 1.2.2 Inner Wear
- 1.2.3 Formal Wear
- 1.2.4 Sportswear
- 1.2.5 Night Wear
- 1.3 By Price Range
- 1.3.1 Mass
- 1.3.2 Premium
- 1.3.3 Luxury
- 1.4 By Age Group
- 1.4.1 5-16 Years
- 1.4.2 16-45 Years
- 1.4.3 45-70 Years
- 1.4.4 70 and Above
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 38.65 billion → 2035: USD 49.23 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Women Apparel Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Women Apparel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Women Apparel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Women Apparel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Women Apparel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Women Apparel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Women Apparel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Women Apparel Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 38.65 billion → 2035: USD 49.23 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Women Apparel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Casual Wear
- 12.3.7.2 Inner Wear
- 12.3.7.3 Formal Wear
- 12.3.7.4 Sportswear
- 12.3.7.5 Night Wear
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Price Range - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mass
- 12.4.7.2 Premium
- 12.4.7.3 Luxury
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Age Group - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 5-16 Years
- 12.5.7.2 16-45 Years
- 12.5.7.3 45-70 Years
- 12.5.7.4 70 and Above
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Women Apparel Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Japan Women Apparel Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Japan Women Apparel Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Fast Retailing Co., Ltd. (Uniqlo, GU)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Shimamura Co., Ltd.
- 17.4 &ST HD Co., Ltd. (Adastria)
- 17.5 World Co., Ltd.
- 17.6 Onward Holdings Co., Ltd.
- 17.7 TABAYA Holdings Inc. (United Arrows)
- 17.8 Wacoal Holdings Corp.
- 17.9 PAL GROUP Holdings Co., Ltd.
- 17.10 LVMH (Louis Vuitton, Christian Dior)
- 17.11 Chanel
- 17.12 Kering (Gucci)
- 17.13 Prada Group
- 17.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

