
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Laundry For Healthcare Facilities Market Size 2024 | USD 5825.58 million |
| Laundry For Healthcare Facilities Market, CAGR | 5.3% |
| Laundry For Healthcare Facilities Market Size 2032 | USD 8805.7 million |
Market Overview:
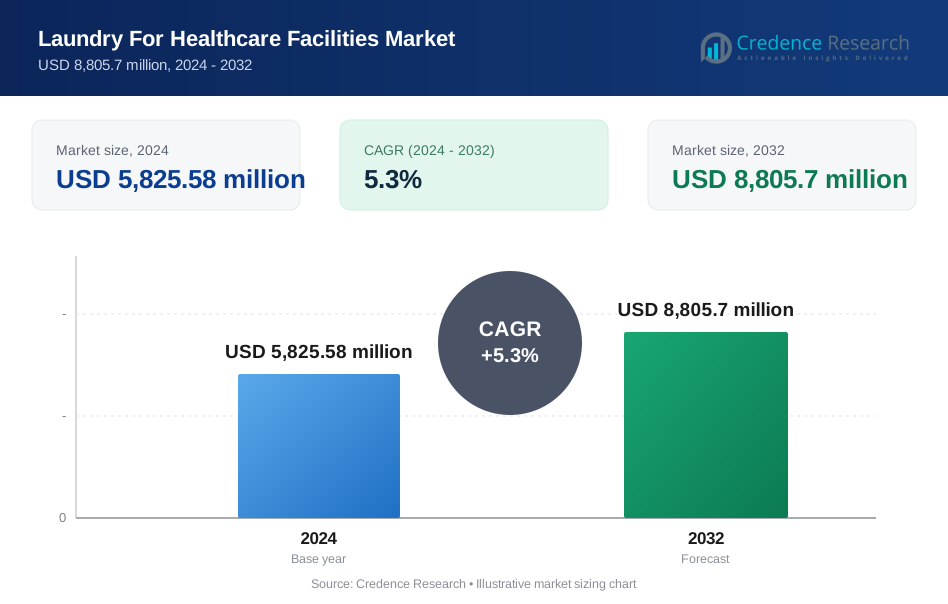
Laundry For Healthcare Facilities Market size was valued at USD 5825.58 million in 2024 and is anticipated to reach USD 8805.7 million by 2032, at a CAGR of 5.3% during the forecast period (2024-2032).
Key drivers propelling the market include rising awareness of infection control protocols and the need for cost-efficient, outsourced laundry services. Healthcare institutions are increasingly outsourcing laundry operations to professional service providers that offer advanced disinfection processes and comply with healthcare-specific regulations such as HLAC (Healthcare Laundry Accreditation Council) and CDC guidelines. Technological advancements, such as the use of ozone and UV disinfection in laundry systems, further support demand. Moreover, the aging global population and the increasing number of hospital admissions due to chronic diseases fuel the need for high-volume and hygienic linen management. Increasing accreditation requirements for healthcare facilities further elevate the importance of certified laundry operations. Growing demand for automation in handling contaminated linens also contributes to market evolution. Rising labor costs are also pushing facilities toward automated and outsourced laundry models.
Regionally, North America leads the market due to its well-established healthcare infrastructure, strict hygiene regulations, and high rate of service outsourcing. Europe follows closely, supported by stringent infection control norms and widespread adoption of healthcare laundry standards. The Asia-Pacific region is expected to witness the fastest growth over the forecast period, driven by healthcare infrastructure development in countries such as China, India, and Southeast Asia. Rapid urbanization and government investment in public health facilities are catalyzing service adoption in emerging markets. Expansion of private hospital chains and medical tourism further strengthens the regional outlook. In Latin America and the Middle East, growing healthcare expenditure and policy reforms are gradually enhancing the demand for professional laundry services.
Market Insights:
- The Laundry for Healthcare Facilities Market was valued at USD 5,825.58 million in 2024 and is expected to reach USD 8,805.7 million by 2032, growing at a CAGR of 5.3% during the forecast period.
- Rising awareness of infection control and compliance with healthcare regulations is increasing demand for professional laundry services in hospitals and long-term care centers.
- Outsourcing continues to gain traction as healthcare institutions seek cost-effective solutions and operational flexibility in managing linen services.
- Adoption of advanced technologies like ozone and UV disinfection, automated folding, and digital tracking is transforming laundry operations and improving service quality.
- Aging populations and rising chronic disease rates are boosting linen consumption, driving the need for high-volume, hygienic laundering solutions.
- High operational costs, infrastructure demands, and regulatory compliance requirements remain key challenges for service providers in both developed and emerging markets.
- North America dominates the market, while Asia-Pacific is witnessing the fastest growth due to expanding healthcare infrastructure and increasing government investment in public health systems.
Market Drivers:
Rising Focus on Infection Control and Regulatory Compliance Drives Market Growth:
The Laundry for Healthcare Facilities Market is expanding due to heightened awareness of infection prevention standards in hospitals, clinics, and long-term care centers. Healthcare providers prioritize stringent hygiene protocols to prevent hospital-acquired infections and ensure patient safety. Compliance with standards from the CDC, OSHA, and HLAC has made professional laundering essential. Facilities must meet traceability and validation requirements for linen disinfection. This has created demand for third-party laundry services that specialize in healthcare-specific cleaning. Hospitals increasingly seek providers that deliver consistent microbial decontamination with documented procedures. It positions laundry services as a core component of clinical risk management strategies.
Shift Toward Outsourced Services Enhances Efficiency and Reduces Operational Burden:
Healthcare institutions are moving away from in-house laundry operations in favor of outsourced models. The Laundry for Healthcare Facilities Market benefits from this trend as providers aim to reduce capital expenditure and improve process efficiency. Outsourced services eliminate the need for maintaining on-site equipment, labor, and energy management. Service providers offer expertise, scale, and compliance assurance that hospitals may lack internally. They also help healthcare centers adapt quickly to fluctuating linen volumes and emergency needs. This shift supports predictable budgeting and frees up internal resources for core clinical functions. It allows institutions to maintain a focus on patient care while ensuring hygiene standards are met.
- For instance, Quick Smart Wash provides comprehensive hospital laundry services in India, ensuring strict hygiene standards through advanced infection control protocols and eco-friendly detergents.
Technological Advancements Improve Operational Reliability and Linen Quality:
Advanced disinfection technologies are transforming the operational landscape of the Laundry for Healthcare Facilities Market. Innovations such as ozone, UV, and tunnel washers enable enhanced cleaning while optimizing water and energy use. Automation in sorting, tracking, and folding processes boosts efficiency and reduces human error. Digital monitoring and reporting systems help providers document compliance in real time. These systems appeal to healthcare clients that must meet audit-ready standards. It also supports sustainable practices by reducing chemical and resource consumption. Service providers are using technology to differentiate and scale their offerings in competitive markets.
- For instance, Lindström Group employs digital monitoring, IoT-enabled garment tracking, and HEPA filtration in its cleanroom laundry services, ensuring real-time quality control and compliance with ISO 14644-1 standards, which supports both operational excellence and stringent hygiene requirements for healthcare clients.
Growing Healthcare Demand Driven by Demographic and Chronic Disease Trends:
The global increase in elderly populations and chronic disease prevalence is expanding healthcare utilization. The Laundry for Healthcare Facilities Market reflects this demand through increased linen volumes and service frequency. Aging patients require more frequent hospitalization and long-term care, leading to greater demand for clean bedding, gowns, and surgical linens. High occupancy in hospitals amplifies the need for rapid laundry turnaround and infection control. Healthcare infrastructure expansion, particularly in Asia-Pacific and Latin America, contributes to higher laundry service adoption. It aligns with rising government investment in public health systems and universal healthcare coverage. The market responds with scalable, high-volume solutions to meet growing needs.
Market Trends:
Adoption of Automation and Smart Laundry Technologies is Transforming Service Delivery:
The Laundry for Healthcare Facilities Market is witnessing a shift toward automation and digital integration across operations. Service providers are investing in smart laundry technologies that enable real-time tracking, load optimization, and automated folding and sorting. These solutions reduce manual labor, improve turnaround times, and ensure process consistency. The integration of RFID tags and cloud-based monitoring platforms allows for better inventory control and compliance documentation. It supports healthcare institutions that require traceable and audit-ready processes. Smart systems also enhance resource efficiency by minimizing water, detergent, and energy usage per load. The trend reflects growing demand for scalable and cost-effective laundry models.
- For instance, Exark’s RFID laundry tracking solution is actively used in hospitals to automate and streamline linen management, providing real-time data for accurate tracking and compliance, while Quick Smart Wash implements sustainable, technology-driven laundry processes for hospitals, ensuring hygiene and operational efficiency.
Sustainability and Eco-Efficient Practices are Reshaping Industry Standards:
Sustainable operations are becoming a defining trend in the Laundry for Healthcare Facilities Market. Providers are adopting eco-friendly technologies such as ozone-based disinfection, low-water-use tunnel washers, and biodegradable detergents. These practices help reduce environmental impact while meeting stringent hygiene standards. It aligns with the broader push from healthcare institutions to meet ESG goals and regulatory expectations on sustainability. The market is also seeing rising demand for certifications that validate green operations and chemical safety. Service providers that demonstrate environmental responsibility gain a competitive advantage. This trend continues to influence equipment upgrades, facility design, and procurement decisions across regions.
- For instance, Quick Smart Wash employs ozone laundry systems and biodegradable detergents in its hospital laundry services to reduce chemical use and carbon footprint, while promoting eco-conscious practices and supporting hospitals’ sustainability goals.
Market Challenges Analysis:
High Operational Costs and Infrastructure Requirements Limit Market Penetration:
The Laundry for Healthcare Facilities Market faces challenges due to high operational costs and complex infrastructure needs. Establishing compliant laundry facilities requires significant investment in equipment, water treatment systems, and energy-efficient technologies. Smaller hospitals and rural care centers often lack the capital and technical expertise to maintain in-house laundry operations. Outsourcing can offset some burdens but may involve long-term contracts and service-level dependencies. It becomes difficult for providers to balance cost control with maintaining consistent hygiene standards. Rising utility prices and labor shortages further strain operational margins and deter new entrants. These factors restrict service expansion in cost-sensitive regions.
- For instance, Los Angeles County hospitals reported notable operational cost savings after outsourcing linen services, demonstrating that strategic partnerships can help healthcare providers manage costs and maintain high hygiene standards despite challenging infrastructure and budgetary constraints.
Strict Regulatory Standards Increase Compliance Burden on Service Providers:
Compliance with healthcare-specific laundry regulations remains a major challenge across markets. The Laundry for Healthcare Facilities Market must align with standards from bodies such as CDC, OSHA, and HLAC, which require detailed documentation and validation. Service providers must continuously update processes to meet evolving disinfection, chemical usage, and worker safety requirements. Frequent audits and certifications demand significant time and resource investment. It creates pressure on providers to maintain quality while managing compliance costs. Failure to meet regulatory expectations can result in reputational damage and loss of contracts. The need for continuous training and system upgrades increases operational complexity.
Market Opportunities:
Rising Demand from Emerging Markets Creates Expansion Opportunities:
The Laundry for Healthcare Facilities Market has strong growth potential in emerging economies across Asia-Pacific, Latin America, and the Middle East. Rapid healthcare infrastructure development and increasing hospital admissions are driving demand for reliable linen management services. Public and private investments in new hospitals, clinics, and eldercare facilities open new markets for laundry service providers. It enables businesses to expand regional footprints through partnerships and facility setups. Urbanization and higher healthcare awareness support the shift toward professional and compliant laundry solutions. Local outsourcing models also gain traction where facilities lack in-house capacity. These dynamics create long-term opportunities for market penetration and scalability.
Technology Integration Offers Competitive Differentiation and Efficiency Gains:
Advances in smart laundry systems, energy-efficient machines, and data-driven compliance tools present growth avenues. The Laundry for Healthcare Facilities Market can benefit by adopting automation and digital monitoring to meet healthcare clients’ evolving expectations. Technology-driven services offer faster turnaround, real-time reporting, and better inventory control. Providers that invest in such capabilities gain a competitive edge in service contracts and tenders. Integration with hospital information systems can streamline coordination and boost transparency. The ability to demonstrate operational excellence through digital tools attracts large healthcare networks. These innovations position providers to scale operations while maintaining regulatory compliance and cost efficiency.
Market Segmentation Analysis:
By Type of Healthcare Facilities
Hospitals hold the largest share of the Laundry for Healthcare Facilities Market due to their high patient volume and constant need for sterile linens. These facilities demand daily laundering of bed sheets, gowns, surgical drapes, and towels, driving consistent service requirements. Long-term care centers and outpatient clinics also contribute significantly, where regular linen use is essential for patient care and hygiene. Rehabilitation centers and specialty clinics follow, reflecting the market's broad relevance across all healthcare tiers. It highlights the role of hygiene in supporting operational efficiency and patient safety across facility types.
By Type of Laundry Services
Off-site laundry services lead the market due to their ability to manage high volumes efficiently while maintaining regulatory compliance. These services reduce infrastructure costs for healthcare providers and offer advanced technologies not feasible in smaller on-site setups. Large hospitals may still rely on on-site systems to maintain control over linen turnaround and emergencies. However, off-site providers are expanding their service capabilities with rapid delivery, traceability, and scalable operations. It supports healthcare facilities aiming to streamline non-clinical functions and focus on core patient care.
By Laundry Equipment Type
Washer extractors and tunnel washers dominate this segment, offering high throughput and energy-efficient operation. Barrier washers are in growing demand where infection control is a priority, particularly in surgical and isolation wards. Dryers, flatwork finishers, and automated folding machines improve process speed and linen consistency. Service providers prefer programmable and automated systems to meet stringent healthcare requirements. It drives ongoing equipment upgrades and operational optimization in both in-house and outsourced facilities.
Segmentations:
By Type of Healthcare Facilities
- Hospitals
- Long-Term Care Centers
- Outpatient Clinics
- Rehabilitation Centers
- Diagnostic Centers
By Type of Laundry Services
- On-Site Laundry Services
- Off-Site Laundry Services
By Laundry Equipment Type
- Washer Extractors
- Tunnel Washers
- Barrier Washers
- Dryers
- Flatwork Finishers
- Folding and Ironing Machines
By Type of Textiles
- Bed Linens
- Patient Gowns
- Surgical Drapes
- Towels
- Staff Uniforms
By Cleaning Method
- Water-Based Cleaning
- Ozone-Based Disinfection
- UV-Based Disinfection
- Chemical Disinfection
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Maintains Market Leadership with Mature Infrastructure and Regulatory Compliance
North America holds 39% of the Laundry for Healthcare Facilities Market, making it the leading region by revenue share. This dominance is driven by advanced healthcare infrastructure, strict hygiene regulations, and a high reliance on third-party service providers. The U.S. and Canada enforce rigorous standards under CDC, OSHA, and HLAC guidelines, which necessitate professional laundering solutions. High patient volumes, aging populations, and increased outsourcing contribute to sustained demand. Healthcare providers in this region continue to invest in automation, RFID tracking, and digital reporting systems to ensure service quality and compliance. It remains a mature and technologically advanced market, attracting continuous investment in innovation and service expansion.
Europe Follows with Strong Regulatory Alignment and Public Health Prioritization
Europe represents 27% of the global market, ranking second due to its structured regulatory framework and comprehensive healthcare systems. Countries such as Germany, the UK, and France maintain high infection control standards and support the adoption of certified laundry services. The region places strong emphasis on sustainability, encouraging the use of energy- and water-efficient equipment. Hospitals are increasingly choosing providers that align with environmental goals while ensuring hygiene compliance. Government programs aimed at healthcare modernization promote outsourcing in both public and private facilities. It fosters growth for accredited providers capable of meeting dual demands for hygiene and eco-efficiency.
Asia-Pacific Emerges as the Fastest-Growing Region with Infrastructure Expansion
Asia-Pacific captures 22% of the Laundry for Healthcare Facilities Market and registers the highest growth rate among all regions. Rapid healthcare infrastructure development in countries like China, India, and Indonesia is driving service demand. Hospitals are moving toward outsourced models to handle higher patient volumes and meet international hygiene standards. Urbanization and rising healthcare spending support increased adoption of professional laundry services. Both regional and global players are expanding their footprint through partnerships and localized operations. It gains further momentum from government reforms and the growing role of the private sector in healthcare delivery.
Key Player Analysis:
- Miele
- Dexter
- Kannegiesser
- EDRO
- Girbau
- Braun
- Pellerin Milnor
- Whirlpool
- Fagor
- Alliance Laundry
- LG
Competitive Analysis:
The Laundry for Healthcare Facilities Market includes prominent equipment manufacturers such as Miele, Fagor, Alliance Laundry, LG, Dexter, EDRO, and Pellerin Milnor. These companies compete by offering advanced, energy-efficient, and high-capacity laundry solutions tailored to healthcare requirements. It prioritizes machines that support disinfection protocols, automation, and long-term durability under continuous use. Players focus on innovation in washer-extractors, barrier washers, and drying systems to meet hygiene standards and reduce operational costs. Integration of programmable controls, remote diagnostics, and eco-friendly features enhances product value and customer retention. Strategic distribution networks and after-sales service are key to sustaining market share. Equipment providers also collaborate with healthcare laundry service companies to supply scalable systems for both on-site and off-site operations. Competitive success depends on performance reliability, regulatory compliance, and the ability to adapt to evolving demands in infection control and resource efficiency.
Recent Developments:
- In April 2024, Miele launched its new Benchmark Machines for laundries in care and nursing homes. These connectivity-enabled machines offer 9–20 kg washing capacities and up to 44 kg drying, featuring smart controls for energy efficiency, RKI-compliant disinfection programs, and AirRecycling Flex technology for reduced energy consumption and gentler fabric care.
- In February 2024, LG announced a $4 million investment to launch 200 self-laundry service centers in India by the end of the year, introducing commercial laundry solutions for institutional settings, including healthcare.
Market Concentration & Characteristics:
The Laundry for Healthcare Facilities Market exhibits moderate concentration, with a few large players holding significant regional and national contracts. It features a mix of multinational providers and specialized regional firms that serve hospitals, clinics, and long-term care facilities. The market is service-intensive, compliance-driven, and reliant on operational scale and efficiency. High entry barriers, including regulatory certifications, capital requirements, and hygiene standards, limit new competition. It values consistency, reliability, and documented disinfection processes that align with healthcare regulations. Digital integration, traceability, and automation are shaping service delivery models. The market continues to evolve with growing demand for outsourced solutions, environmental compliance, and rapid response capabilities. Rising pressure on healthcare institutions to meet audit standards strengthens long-term partnerships with certified laundry providers. Demand for customized service models based on facility size and specialty is also influencing provider differentiation strategies.
Report Coverage:
The research report offers an in-depth analysis based on Type of Healthcare Facilities, Type of Laundry Services, Laundry Equipment Type, Type of Textiles, Cleaning Method and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Healthcare facilities will increasingly adopt automated laundry systems to enhance efficiency and reduce manual labor.
- The demand for eco-friendly and energy-efficient laundry equipment will rise as institutions aim to meet sustainability goals.
- Outsourcing of laundry services by hospitals and clinics will continue to grow, driven by cost-effectiveness and compliance requirements.
- Integration of digital tracking and inventory management systems will become standard to ensure transparency and accountability.
- The market will see a surge in the use of advanced disinfection technologies, such as ozone and UV treatments, to meet stringent hygiene standards.
- Emerging markets in Asia-Pacific and Latin America will experience significant growth due to expanding healthcare infrastructure.
- Regulatory bodies will enforce stricter guidelines, prompting facilities to upgrade their laundry operations accordingly.
- Customized laundry solutions tailored to specific healthcare facility needs will gain traction, offering flexibility and improved service delivery.
- Investment in staff training and development will be prioritized to ensure adherence to best practices and operational excellence.
- Collaborations between laundry service providers and healthcare institutions will strengthen, focusing on innovation and quality improvement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Focus on Infection Control and Regulatory Compliance
Healthcare facilities are prioritizing stringent hygiene protocols to prevent hospital-acquired infections, driving demand for professional laundry services that comply with CDC, OSHA, and HLAC standards. This regulatory pressure ensures consistent microbial decontamination and traceability, making certified laundry operations essential.
Shift Toward Outsourced Laundry Services
Hospitals and clinics are increasingly outsourcing laundry operations to specialized providers to reduce capital expenditure, improve efficiency, and ensure compliance. Outsourcing enables healthcare institutions to focus on core clinical functions while maintaining high hygiene standards and operational flexibility.
Technological Advancements in Laundry Processes
The adoption of advanced disinfection technologies such as ozone and UV, along with automation in sorting, folding, and digital tracking, is transforming laundry operations. These innovations improve service quality, reduce human error, and help providers meet audit-ready standards required by healthcare clients.
Growing Healthcare Demand Due to Aging Population and Chronic Diseases
An aging global population and rising rates of chronic diseases are increasing hospital admissions and long-term care needs, which in turn drive higher linen consumption and more frequent laundering. This trend fuels the need for scalable, hygienic laundry solutions in healthcare settings.
Sustainability and Eco-Efficient Practices
Healthcare institutions are seeking laundry partners that use eco-friendly technologies, such as low-water-use washers and biodegradable detergents, to meet environmental goals and regulatory expectations. Providers that demonstrate sustainable operations gain a competitive advantage and align with the broader push for ESG compliance in healthcare.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Laundry for Healthcare Facilities Market?
Why is the demand for healthcare laundry services increasing?
Which regions are leading the market growth?
How are rising costs affecting laundry services in healthcare?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Cleaning Method
- 1.2.1 Water-Based Cleaning
- 1.2.2 Ozone-Based Disinfection
- 1.2.3 UV-Based Disinfection
- 1.2.4 Chemical Disinfection
- 1.3 By Laundry Equipment Type
- 1.3.1 Washer Extractors
- 1.3.2 Tunnel Washers
- 1.3.3 Barrier Washers
- 1.3.4 Dryers
- 1.3.5 Flatwork Finishers
- 1.3.6 Folding and Ironing Machines
- 1.4 By Type of Laundry Services
- 1.4.1 On-Site Laundry Services
- 1.4.2 Off-Site Laundry Services
- 1.5 By Type of Healthcare Facilities
- 1.5.1 Hospitals
- 1.5.2 Long-Term Care Centers
- 1.5.3 Outpatient Clinics
- 1.5.4 Rehabilitation Centers
- 1.5.5 Diagnostic Centers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,825.58 million → 2032: USD 8,805.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Laundry For Healthcare Facilities Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Laundry For Healthcare Facilities Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Laundry For Healthcare Facilities Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Laundry For Healthcare Facilities Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Laundry For Healthcare Facilities Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Laundry For Healthcare Facilities Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Laundry For Healthcare Facilities Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Laundry For Healthcare Facilities Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,825.58 million → 2032: USD 8,805.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Laundry For Healthcare Facilities Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Cleaning Method - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Water-Based Cleaning
- 12.3.7.2 Ozone-Based Disinfection
- 12.3.7.3 UV-Based Disinfection
- 12.3.7.4 Chemical Disinfection
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Laundry Equipment Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Washer Extractors
- 12.4.7.2 Tunnel Washers
- 12.4.7.3 Barrier Washers
- 12.4.7.4 Dryers
- 12.4.7.5 Flatwork Finishers
- 12.4.7.6 Folding and Ironing Machines
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Laundry Services - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-Site Laundry Services
- 12.5.7.2 Off-Site Laundry Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Type of Healthcare Facilities - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hospitals
- 12.6.7.2 Long-Term Care Centers
- 12.6.7.3 Outpatient Clinics
- 12.6.7.4 Rehabilitation Centers
- 12.6.7.5 Diagnostic Centers
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Laundry For Healthcare Facilities Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Laundry For Healthcare Facilities Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Laundry For Healthcare Facilities Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Miele
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Dexter
- 17.4 Kannegiesser
- 17.5 EDRO
- 17.6 Girbau
- 17.7 Braun
- 17.8 Pellerin Milnor
- 17.9 Whirlpool
- 17.10 Fagor
- 17.11 Alliance Laundry
- 17.12 LG
- 17.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
